
 Global Smart Shoes Market | 2026-2036
Global Smart Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Shoes Market Outlook
Modular sensor architectures that separate the electronics pod from the shoe chassis is recalibrating how buyers evaluate upgrade cycles and total cost of ownership. Nike leverages vertical integration to control proprietary motion-capture firmware stacks. Adidas anchors its position through deep R&D partnerships with European biomechanics institutes. Xiaomi competes on manufacturing scale, driving sensor miniaturization costs downward across Asia-Pacific supply chains.
Smart shoes integrate embedded microelectromechanical systems, conductive textiles, and low-energy wireless transceivers to capture gait kinematics, ground reaction forces, and geolocation data for performance optimization or clinical assessment. Fitness tracker shoes currently occupy the largest revenue pool, while health monitoring shoes represent the fastest-expanding category as diabetic neuropathy screening and fall-risk protocols gain reimbursement traction in aging economies. Bluetooth dominates connectivity deployments, though foot pressure sensors are displacing simpler accelerometer-only designs in clinical-grade configurations.
FDA clearance pathways for Class II medical device footwear, EU GDPR biometric data processing requirements, and China's GB standards for wearable electromagnetic compatibility collectively raise compliance costs but also erect barriers against unvalidated entrants. Japan's METI has issued interoperability guidelines that pressure vendors toward open data formats. Stakeholders must monitor whether clinical validation requirements expand from health monitoring shoes into adjacent categories, as this would reshape R&D budgets and partnership strategies across the value chain.
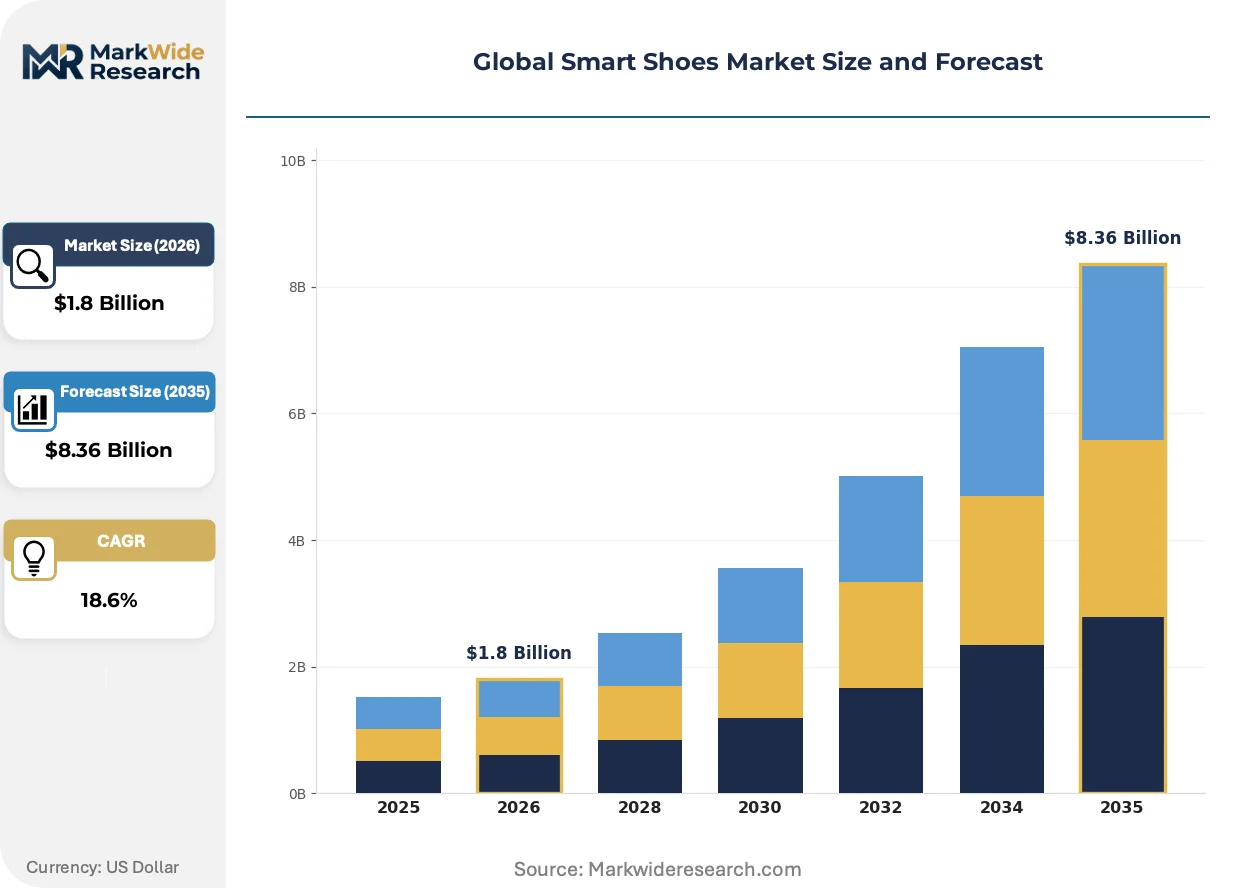
Market Dynamics
Modular sensor architectures are fragmenting upgrade cycles and forcing vendors to recalibrate hardware-software bundling strategies as professional sports franchises demand swapable electronics pods.
Growth Catalysts
- EU AI Act biometric governance:The regulation mandates algorithmic transparency for wearable data processing, pushing healthcare providers toward validated smart footwear for diabetic neuropathy screening protocols.
- Conductive textile miniaturization:Foot pressure sensor arrays now embed directly into woven uppers, eliminating rigid chassis requirements and expanding addressable use cases into fashion-forward consumer segments.
- Japan METI interoperability guidelines:The framework pressures vendors toward open data formats, reducing hospital IT integration friction and accelerating clinical procurement timelines for gait analysis systems.
Market Restraints
- Lithium-polymer cell volatility:Battery chemistry costs fluctuate with cobalt supply disruptions from Central African mining concentrations, compressing hardware margins on mid-tier fitness tracker configurations.
- GDPR biometric processing friction:The regulation's explicit consent requirements and data localization mandates impose compliance overhead that disadvantages smaller vendors lacking dedicated privacy engineering teams.
- Accelerometer-only design obsolescence:Simpler motion-capture footwear faces substitution pressure from pressure-mapping insoles and smartphone-native gait apps in price-sensitive consumer segments.
Strategic Opportunities
- India PLI scheme for wearables:The production-linked incentive program subsidizes domestic sensor assembly, creating cost-competitive export capacity for Asia-Pacific distribution networks.
- Bluetooth Low Energy-UWB convergence:Hybrid wireless stacks enable sub-meter indoor positioning for warehouse worker safety applications, opening industrial procurement channels beyond consumer fitness.
- Germany KBA automotive integration:Driver fatigue detection mandates for commercial fleets create embedded footwear demand for long-haul trucking operators seeking biometric alert systems.
Industry Challenges
- FDA 510(k) clearance timelines:Class II medical device pathways for fall-risk assessment footwear extend development cycles 18-24 months, straining R&D capitalization for mid-stage vendors.
- Embedded firmware talent scarcity:Motion-capture algorithm development requires rare cross-disciplinary expertise spanning biomechanics, signal processing, and edge computing optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Shoes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Tracker Shoes, Navigation Shoes, Gaming Shoes, Health Monitoring Shoes Technology: Bluetooth, GPS, NFC, Foot Pressure Sensors End User: Athletes, Fitness Enthusiasts, Casual Users, Healthcare Providers Distribution Channel: Online Retail, Offline Retail, Specialty Stores, Direct Sales |
| Companies Covered | Nike, Adidas, Puma, Under Armour, New Balance, Xiaomi, ASICS, Li-Ning, Digitsole, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Shoes Market Strategic Shifts
Hardware-software decoupling is rewriting competitive moats as sensor miniaturization commoditizes while proprietary motion-capture firmware stacks differentiate outcomes. Vendors now face strategic bets on open versus closed data architectures.
Pressure-mapping insole arrays are integrating machine-learning inference engines for real-time gait anomaly detection. Professional sports teams in the United States and Germany deploy these systems for load management in basketball and football programs. The technology is integrating predictive injury analytics into athlete conditioning workflows, compressing the value capture toward software subscriptions and away from hardware replacement cycles.
China's GB standards for wearable electromagnetic compatibility now mandate shielding validation for devices operating near medical equipment. The regulation forces export-oriented manufacturers to maintain dual certification tracks for domestic and international product variants. Health monitoring shoe configurations face the steepest compliance burden, with some vendors delaying China market entry until 2026 to amortize retooling costs across larger production runs.
Hospital procurement departments in aging economies now unbundle hardware acquisition from data analytics subscriptions, treating smart footwear as connected service infrastructure rather than capital equipment. Medical device distributors in Japan and France respond by building in-house biomechanics consulting capabilities to capture recurring revenue streams. The shift pressures pure hardware vendors to assemble software partnerships or exit clinical channels entirely.
Global Smart Shoes Market Segmentation
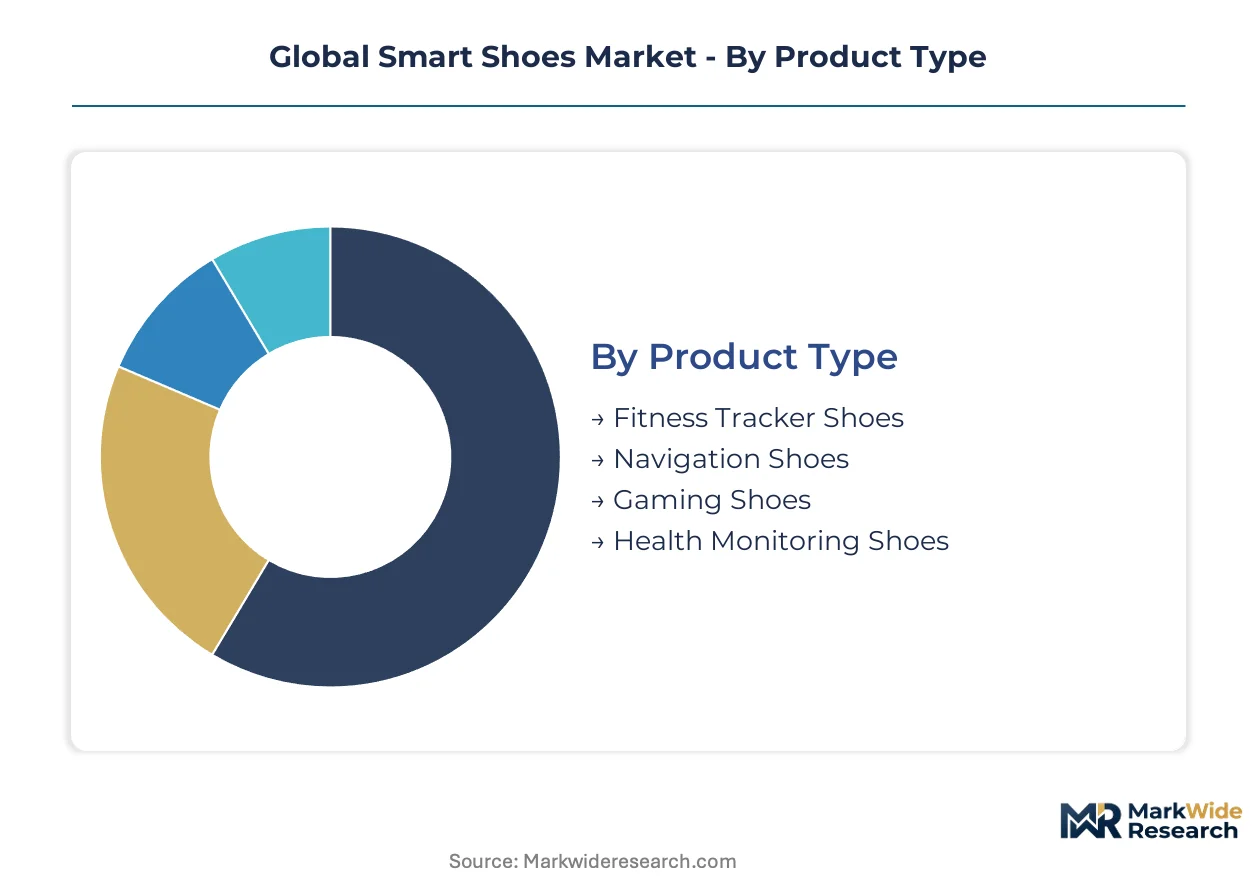
Smart shoes segment across four interlocking dimensions that determine integration complexity and procurement economics. Product type governs sensor density and regulatory pathway, while technology choices dictate power budgets and data fidelity. End-user profiles separate consumer discretionary spend from institutional reimbursement, and distribution channel selection shapes margin capture and upgrade-cycle access.
Product Type:
Fitness tracker shoes operate as standalone wellness peripherals with minimal IT integration, while health monitoring variants embed into clinical workflows and electronic health record systems.
- Fitness Tracker Shoes:Accelerometer and gyroscope arrays capture step count, cadence, and calorie burn estimates through companion smartphone applications. Demand concentrates in United States and German consumer markets where gym membership penetration and wearable device ownership overlap. Bluetooth Low Energy dominates connectivity to preserve battery life across 7-10 day usage cycles.
- Health Monitoring Shoes:Pressure-mapping insole arrays and conductive textile electrodes enable diabetic neuropathy screening, fall-risk assessment, and gait disorder diagnosis. Clinical validation requirements in Japan and France drive procurement through hospital supply chains rather than direct-to-consumer channels. Reimbursement traction in aging economies accelerates category expansion.
- Navigation Shoes:GPS and haptic feedback modules assist visually impaired pedestrians with turn-by-turn guidance through vibration patterns in the midsole. Municipal accessibility programs in Barcelona and Singapore pilot deployments for public transit integration.
- Gaming Shoes:Motion-capture sensors translate foot position and pressure into virtual reality locomotion inputs. Niche positioning limits volume to enthusiast segments in South Korea and United States esports markets.
Fitness tracker shoes lead volumes today; health monitoring shoes are gaining share fastest.
Technology:
Wireless protocol selection determines interoperability scope and power consumption trade-offs, while sensor modality governs data richness and clinical utility.
- Bluetooth:Low-energy transceivers dominate fitness and casual consumer deployments through universal smartphone compatibility. The protocol's 10-meter range and 1-3 year battery life align with daily activity tracking use cases.
- Foot Pressure Sensors:Capacitive and piezoelectric arrays measure ground reaction force distribution across 50-200 sensing nodes. Clinical-grade configurations in Germany and Japan achieve 5% force accuracy for biomechanics research and rehabilitation protocols. The technology commands premium pricing but captures highest-margin applications.
- GPS:Multi-constellation receivers enable outdoor pace and distance measurement for runner segmentation in Australia and United States trail running communities. Signal occlusion limits indoor utility.
- NFC:Passive 13.56 MHz tags facilitate tap-to-pair authentication and access control integrations. Enterprise wellness programs in France deploy NFC-enabled footwear for secure locker and facility access.
Bluetooth leads volumes today; foot pressure sensors are climbing the fastest.
End User:
User sophistication spans casual consumers seeking aesthetic differentiation to clinical professionals demanding validated measurement protocols and audit trails.
- Athletes:Professional and semi-professional competitors in United States basketball and German football programs drive load-management analytics adoption. Franchise procurement departments treat smart footwear as performance infrastructure with 12-18 month replacement cycles.
- Healthcare Providers:Hospital systems and rehabilitation clinics in Japan and France unbundle hardware acquisition from gait analysis subscriptions. Procurement committees prioritize FDA-cleared or CE-marked devices with electronic health record interoperability.
- Fitness Enthusiasts:Recreational runners and gym members in United Kingdom and Australia represent price-sensitive volume demand. Purchase decisions weight brand affinity and app ecosystem integration over clinical-grade accuracy.
- Casual Users:Fashion-forward consumers in Italy and South Korea value aesthetic design and social sharing features over biomechanical depth. Short replacement cycles and gift-market seasonality characterize demand patterns.
Fitness enthusiasts lead volumes today; healthcare providers are expanding most quickly.
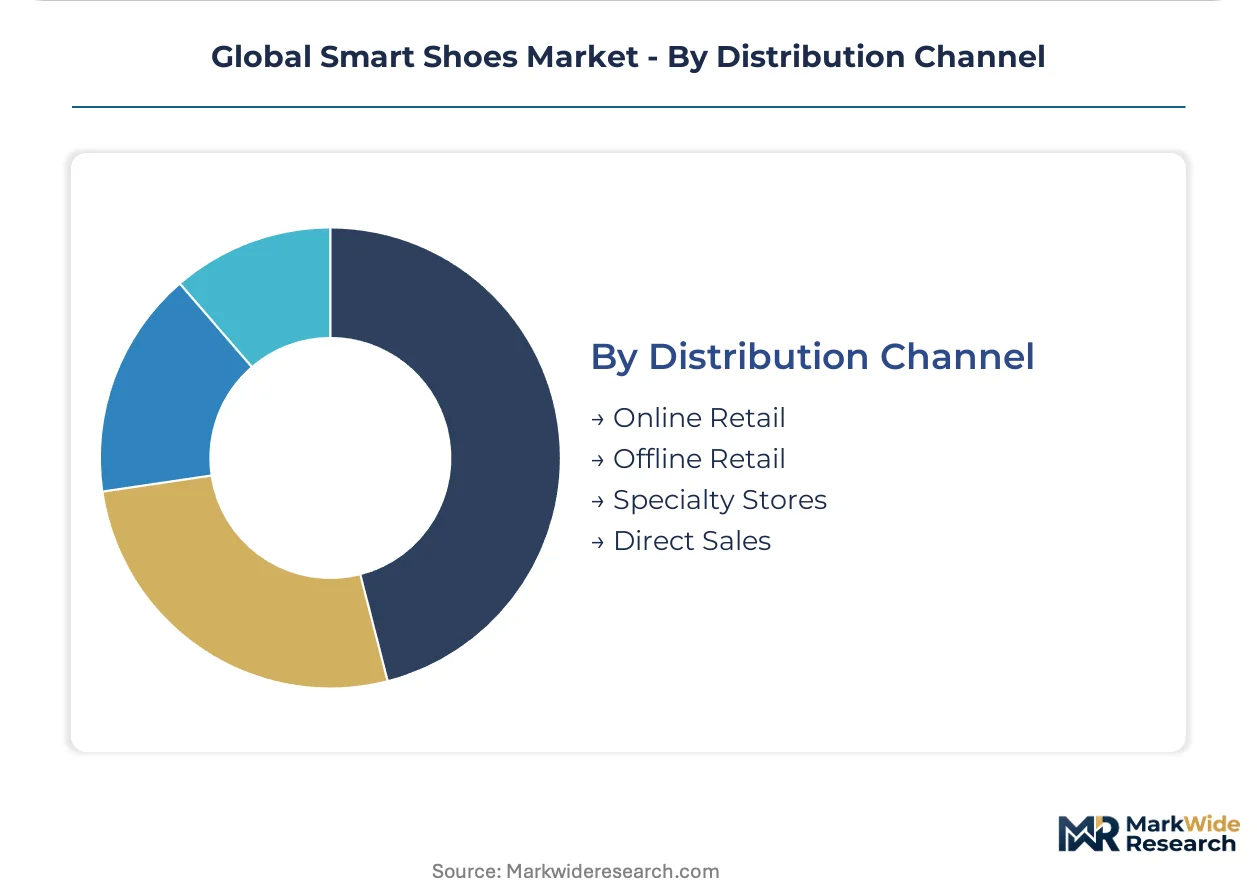
Distribution Channel:
Channel selection determines customer acquisition cost, margin retention, and post-sale engagement depth for software subscription attach.
- Online Retail:Direct-to-consumer and marketplace platforms capture fitness enthusiast and casual user segments in United States and United Kingdom markets. Lower customer acquisition costs support mid-tier pricing, though return rates exceed 25% for sizing-sensitive footwear.
- Specialty Stores:Running and outdoor retailers in Germany and Japan provide gait analysis services and fitting expertise. Staff biomechanics training justifies premium positioning and reduces return incidence.
- Direct Sales:Enterprise and clinical procurement in France and Japan runs through manufacturer field teams with dedicated account management. Long sales cycles accompany higher lifetime value through analytics subscription renewals.
- Offline Retail:Mass-market sporting goods chains in Brazil and India drive volume for entry-level fitness tracker configurations. Price competition compresses margins but builds brand awareness for upgrade pathway capture.
Online retail leads volumes today; direct sales are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered athletic footwear electronics through early military and sports biomechanics programs, establishing the foundational IP that now diffuses across consumer and clinical applications worldwide.
United States
Professional basketball and football franchises drive load-management analytics procurement, with team medical staffs embedding pressure-mapping footwear into athlete conditioning protocols. FDA 510(k) clearance pathways for Class II medical device configurations extend development timelines but validate reimbursement claims for fall-risk assessment products. Boston and the San Francisco Bay Area concentrate venture-backed startups developing edge-computing gait analysis algorithms.
Germany
Automotive fleet operators under KBA driver fatigue mandates create embedded footwear demand for long-haul trucking biometric alert systems. EU AI Act algorithmic transparency requirements push healthcare providers toward validated smart footwear for diabetic neuropathy screening. The Munich and Stuttgart metropolitan areas host biomechanics institutes partnering with vendors on clinical-grade pressure sensor validation protocols.
China
Domestic manufacturing scale drives sensor miniaturization cost reductions across Asia-Pacific supply chains for export-oriented producers. GB standards for wearable electromagnetic compatibility mandate shielding validation for devices operating near medical equipment, forcing dual certification tracks for domestic and international variants. Shenzhen and Dongguan electronics clusters concentrate contract manufacturing capacity for pressure sensor array assembly.
Japan
Hospital procurement departments unbundle hardware acquisition from gait analysis subscriptions, treating smart footwear as connected service infrastructure. METI interoperability guidelines pressure vendors toward open data formats, reducing hospital IT integration friction. Tokyo and Osaka metropolitan areas concentrate aging-population clinical trials for fall-risk assessment footwear seeking reimbursement approval.
India
Domestic assembly cost advantages under the PLI scheme for wearables create export-competitive capacity for Asia-Pacific distribution networks. Price-sensitive consumer segments favor accelerometer-only fitness tracker configurations over pressure-mapping clinical alternatives. Bangalore and Hyderabad technology corridors concentrate firmware development talent for motion-capture algorithm optimization.
Global Smart Shoes Market Competitive Environment
Premium-margin players sit above commodity-margin players across firmware differentiation and clinical validation depth, with the vendor base stratifying into three tiers: vertically integrated sportswear giants controlling proprietary motion-capture stacks; European biomechanics partnerships anchoring clinical-grade positioning; and Asian scale manufacturers competing on sensor cost curves. Strategic moves concentrate on hardware-software bundling recalibration and modular sensor architecture adoption to fragment upgrade cycles.
Within the vertically integrated tier, Nike and Adidas occupy positions exemplifying divergent approaches to proprietary control versus open partnership ecosystems. Xiaomi sits within the scale-driven manufacturing archetype, leveraging Asia-Pacific supply chain density to compress sensor miniaturization costs. Digitsole represents the specialist configuration, anchoring the pressure-mapping insole segment through focused hardware-software integration for clinical and athletic applications.
| Leading Market Players |
|---|
| Nike |
| Adidas |
| Puma |
| Under Armour |
| New Balance |
| Xiaomi |
| ASICS |
| Li-Ning |
| Digitsole |
| Others |
Value Chain & Pricing Dynamics
Captive production of proprietary motion-capture firmware stacks anchors Nike's supply position and pricing power, while outsourced sensor assembly in Asia-Pacific compresses margins for mid-tier vendors competing on hardware cost curves. The bifurcation between vertically integrated sportswear giants and contract-dependent specialists directly shapes how procurement committees negotiate lifetime value versus upfront acquisition costs.
Pricing Analysis
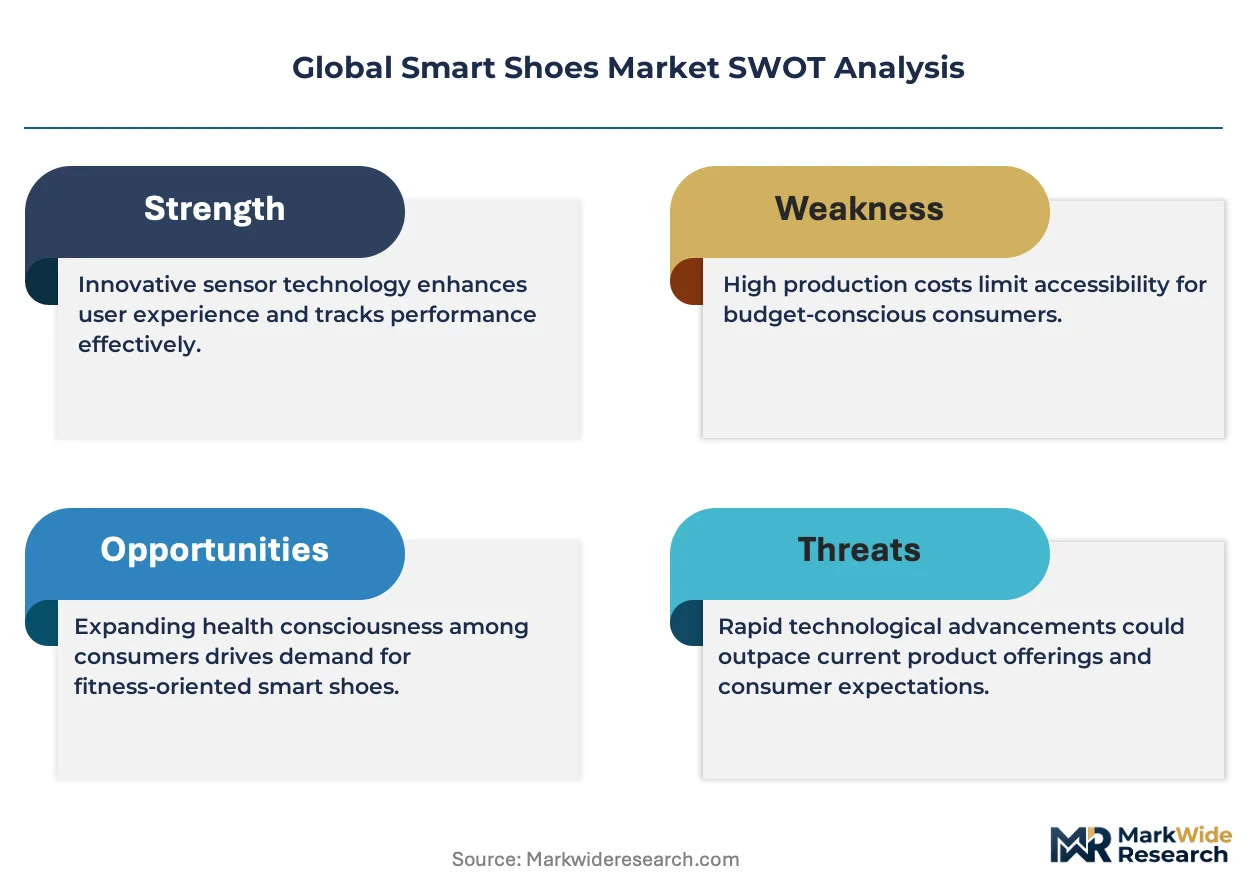
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical configurations from fitness tracker peripherals and accelerometer-only entry models. Certification grade and sensor density drive price differentiation, with pressure-mapping insoles commanding substantial premiums over Bluetooth-only wellness variants. Cost compression in mid-tier fitness configurations intensifies because Xiaomi's manufacturing scale erodes hardware margins. Casual users in Italy and South Korea exhibit highest price sensitivity, while hospital procurement committees in Japan prioritize validated measurement protocols over unit economics.
Supply Chain Analysis
Returns and refurbishment flows for sizing-sensitive footwear create reverse-logistics overhead that online retail channels absorb through elevated customer acquisition costs. Manufacturing concentrates in China, Vietnam, and Indonesia, with Shenzhen and Dongguan electronics clusters feeding pressure sensor array assembly. Supply chains draw from lithium-polymer cell suppliers, conductive textile weavers, and MEMS foundries. Single-source vulnerability in cobalt supply from Central African mining concentrations elevates battery chemistry cost volatility. Distribution runs through direct-to-consumer platforms, specialty running retailers, and hospital supply chains with diverging margin profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Smart Shoes Market compounds as a regulatory compounder, with EU AI Act biometric governance mandates driving healthcare provider demand for validated diabetic neuropathy screening footwear.
For Market Incumbents: Extend proprietary firmware differentiation into open data architectures before Japan METI interoperability guidelines commoditize integration layers. Consolidate clinical validation pipelines to defend against pressure-mapping insole specialists capturing hospital procurement share. Capacity addition in Germany's Munich-Stuttgart corridor secures European biomechanics partnership density against Adidas's anchored R&D network. For New Entrants and Emerging Players: EU AI Act in Europe opens a window for algorithmic transparency specialists to penetrate healthcare provider procurement committees previously locked by incumbent certification moats. Target India's PLI-subsidized domestic sensor assembly for export-competitive Asia-Pacific distribution capacity. A direct sales model with dedicated account management captures higher lifetime value through analytics subscription attach than online retail's 25% return rate burden. For Investors and Strategic Acquirers: Roll-up economics work for pressure-mapping insole specialists because hospital procurement unbundling creates fragmented software subscription assets ripe for platform consolidation. Five-to-ten year viability hinges on FDA 510(k) clearance pathway navigation and electronic health record interoperability depth. Watch for reimbursement approval signals in Japan's aging-population clinical trial pipeline as inflection indicators for category expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Sensor Architecture Adoption | Swapable electronics pods fragment upgrade cycles and recalibrate hardware-software bundling for professional sports franchises. |
| Clinical Validation Pipeline Investment | FDA 510(k) clearance pathways validate reimbursement claims and erect barriers against unvalidated entrants in fall-risk assessment. |
| Open Data Format Compliance | Japan METI interoperability guidelines reduce hospital IT integration friction and accelerate procurement timelines for gait analysis systems. |
| Backward Integration into Firmware Stacks | Proprietary motion-capture algorithms differentiate outcomes as sensor miniaturization commoditizes hardware components. |
| Asia-Pacific Manufacturing Scale Expansion | India PLI scheme subsidies create export-competitive sensor assembly capacity for cost-sensitive fitness tracker configurations. |
Study Parameters
Direct dialogue with biomechanics researchers, hospital procurement managers, athletic franchise medical staffs, and contract manufacturing executives grounded qualitative insights in operational reality. Secondary validation drew from FDA 510(k) filings, EU AI Act regulatory texts, Japan METI interoperability guidelines, China GB standards documentation, and hospital supply chain procurement databases. Bottom-up and top-down triangulation cross-checked unit economics assumptions against aggregate market sizing.
Bottom-up modeling built from sensor cost curves, certification pathway timelines, and reimbursement traction patterns across product type and end-user segments. Top-down analysis anchored aggregate demand in aging-population demographics, professional sports technology budgets, and industrial safety mandates. Segmentation dimensions spanned product type, technology protocol, end-user sophistication, and distribution channel structure. CAGRs derived from hardware replacement cycle compression, software subscription attach rates, and clinical validation expansion across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cobalt supply disruption scenarios or accelerated EU AI Act enforcement timelines. Practitioners should monitor FDA clearance timeline extensions, Japan reimbursement approval signals, and China GB standard retooling cost amortization patterns for early indicators of competitive position shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Smart Bra Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Women's Watch Market
Wearable Technology
Pet Wearable Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Europe Watch Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Global Smart Watch Market