
 US Pet Wearable Market | 2026-2036
US Pet Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Wearable Market Intelligence
Silicon-based microprocessors is restructuring cost structures across GPS collar and health monitor manufacturing. Garmin Ltd. leverages vertical integration in GPS chipset design to sustain hardware margins. PetPace LLC specializes in veterinary-grade physiological monitoring, anchoring clinical channel partnerships. Whistle Labs Inc. dominates consumer-facing subscription services, extending recurring revenue per activated device.
US Pet Wearables comprise electronic devices affixed to companion animals for location tracking, biometric measurement, and behavior logging, typically incorporating accelerometers, photoplethysmography sensors, and low-power wide-area network transceivers operating at 2.4 GHz or sub-GHz frequencies. Their commercial purpose centers on reducing veterinary emergency incidence, accelerating lost-pet recovery, and generating quantified wellness datasets for insurance underwriting. Activity Trackers and GPS Collars capture the majority of unit volume, while Health Monitors command premium pricing through FDA-adjacent validation workflows. Bluetooth and Cellular technologies split the connectivity architecture, with Bluetooth dominating short-range indoor deployment and Cellular capturing outdoor roaming use cases where Wi-Fi infrastructure proves intermittent.
FAA regulations govern drone-integrated pet retrieval systems that pair with GPS collar coordinates, while FDA Center for Veterinary Medicine guidance shapes health claim substantiation for biometric sensors. FCC Part 15 and Part 27 certifications mandate electromagnetic emissions compliance for all radio-frequency transmitting wearables sold domestically. Stakeholders must monitor emerging USDA APHIS data interoperability standards and state-level pet privacy legislation to anticipate compliance burdens ahead of product roadmap commitments.
Market Dynamics
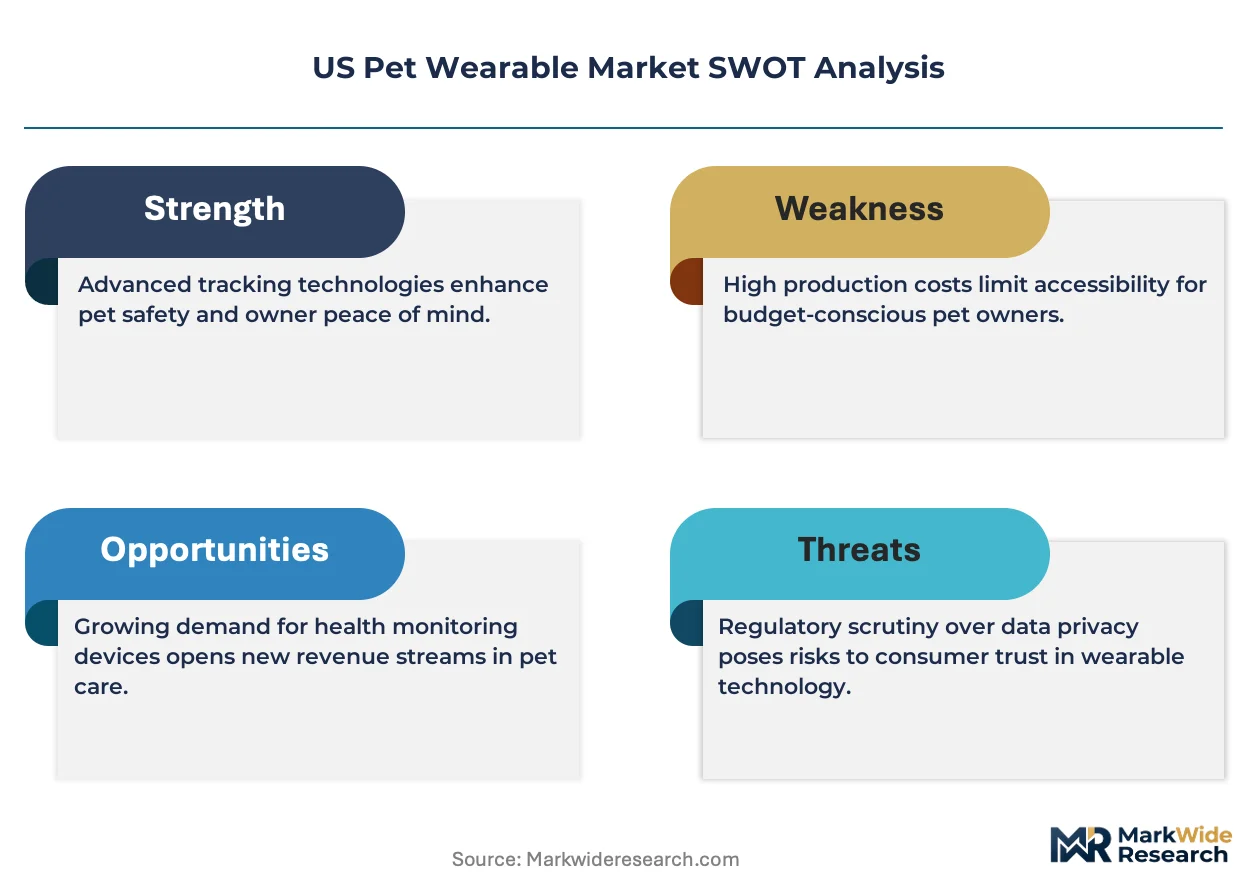
FDA Center for Veterinary Medicine guidance on animal health device substantiation is forcing manufacturers to restructure validation workflows, compressing time-to-market for biometric sensors while elevating compliance costs for market entrants.
Growth Catalysts
- Veterinary remote monitoring protocols:Clinics in California and Texas metropolitan corridors are embedding GPS collar and health monitor data into preventive care workflows, driving recurring device procurement.
- FCC Part 15 certification standardization:Streamlined electromagnetic emissions compliance for 2.4 GHz transceivers is reducing technical barriers for new hardware entrants.
- Silicon-based microprocessor cost compression:Foundry capacity expansion is lowering bill-of-materials costs for accelerometer and photoplethysmography sensor integration.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing remains concentrated among East Asian contract manufacturers, exposing hardware vendors to input cost volatility and logistics disruption.
- FDA-adjacent validation burden:Health claim substantiation for biometric sensors requires clinical evidence packages that extend development timelines and consume technical talent.
- Subscription fatigue threshold:Consumer willingness to maintain recurring payments for GPS tracking services shows early saturation signals in premium urban demographics.
Strategic Opportunities
- USDA APHIS data interoperability standards:Emerging federal guidelines for cross-platform pet health record exchange will reward early-compliant vendors with institutional channel access.
- Drone-integrated retrieval systems:FAA regulatory clarity on unmanned aircraft coordination with GPS collar coordinates is opening aerial recovery service monetization.
- Insurance underwriting integration:Quantified wellness datasets from continuous health monitors are penetrating pet insurance actuarial models, creating B2B2C channel partnerships.
Industry Challenges
- Veterinary clinical trial recruitment:Validating physiological monitoring algorithms requires species-specific biometric baselines that complicate FDA-adjacent evidence generation.
- Cellular carrier certification timelines:Sub-GHz LPWAN module approval processes with major US mobile network operators extend hardware launch schedules unpredictably.
- State-level pet privacy legislation fragmentation:Emerging biometric data protection laws in California and Texas create compliance patchwork that strains national product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Wearable Market |
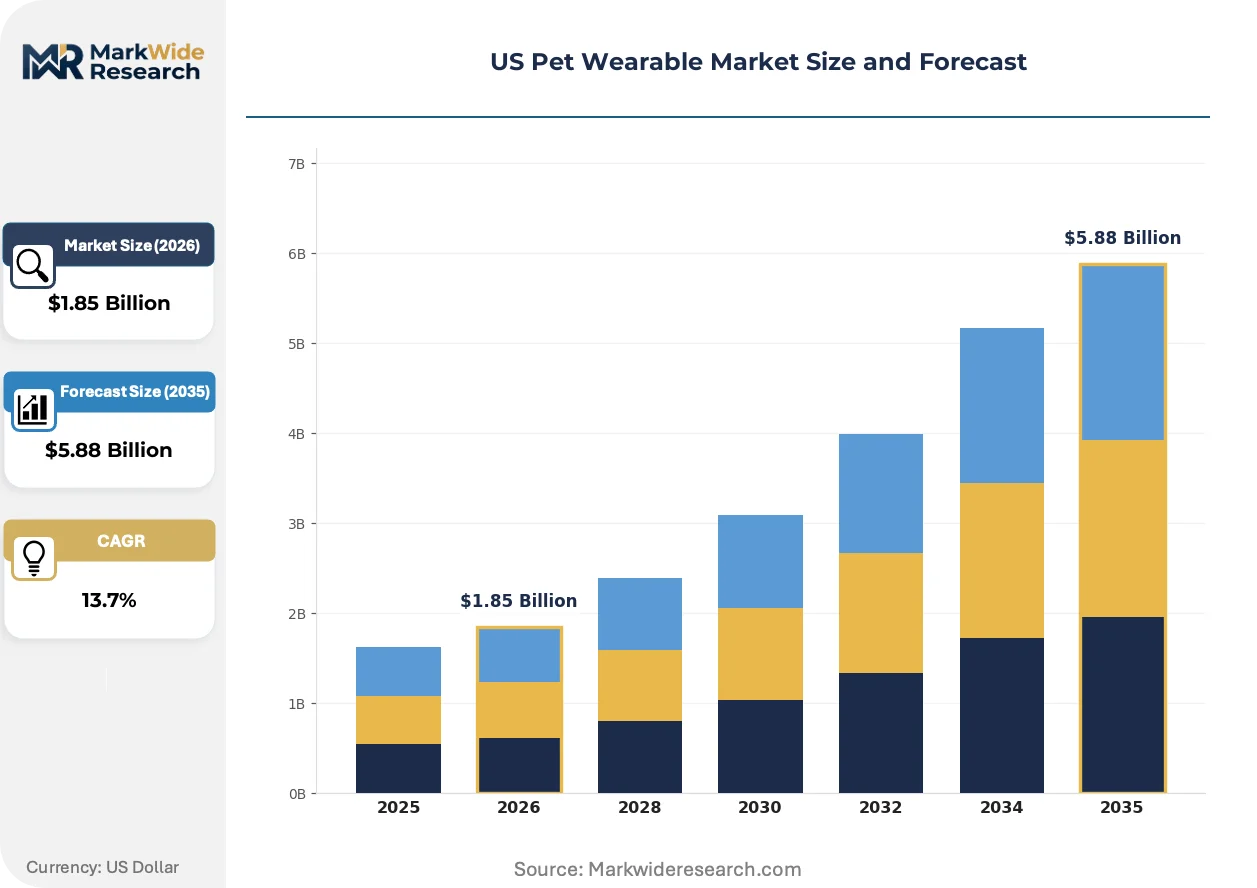
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activity Trackers, GPS Collars, Health Monitors, Smart Leashes Technology: Bluetooth, RFID, Cellular, Wi-Fi End User: Pet Owners, Veterinary Clinics, Training Facilities, Animal Shelters Deployment: Mobile Apps, Cloud-Based Solutions, In-Store Systems, Standalone Devices |
| Companies Covered | Garmin Ltd., PetPace LLC, Whistle Labs Inc., FitBark Inc., Datamars, Avid Identification Systems Inc., High Tech Pet Products Inc., Loc8tor Ltd., Radio Systems Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Wearable Market Strategic Shifts & Innovations
Photoplethysmography sensor miniaturization is compressing form factors for continuous vital sign monitoring, while regulatory pressure on health claim validation is elevating clinical-grade hardware specifications across consumer-facing product tiers.
Silicon photonics integration is overtaking discrete optical component assemblies in health monitor manufacturing. Veterinary-grade device vendors are adopting chip-scale photoplethysmography modules to reduce power consumption and mechanical failure rates. This convergence is overtaking legacy discrete sensor architectures in premium collar designs and enabling multi-day battery life in sub-30 gram form factors.
FDA Center for Veterinary Medicine draft guidance on animal health software functions is reshaping firmware development practices for biometric algorithms. Manufacturers must now document clinical validation protocols for heart rate variability and respiratory rate extraction before marketing health claims. This regulatory pressure is concentrating development resources among vendors with captive veterinary clinical trial networks, particularly those anchored in Texas and California academic veterinary hospitals.
Subscription unbundling from hardware purchase is disrupting direct-to-consumer channel economics. Pet owners in metropolitan corridors increasingly resist multi-year service commitments bundled at point of sale, forcing retailers to offer month-to-month GPS tracking plans. This behavioral shift is most visible in California pet specialty chains, where attach rates for annual subscriptions have compressed against monthly alternatives with higher per-unit service pricing.
US Pet Wearable Market Segmentation
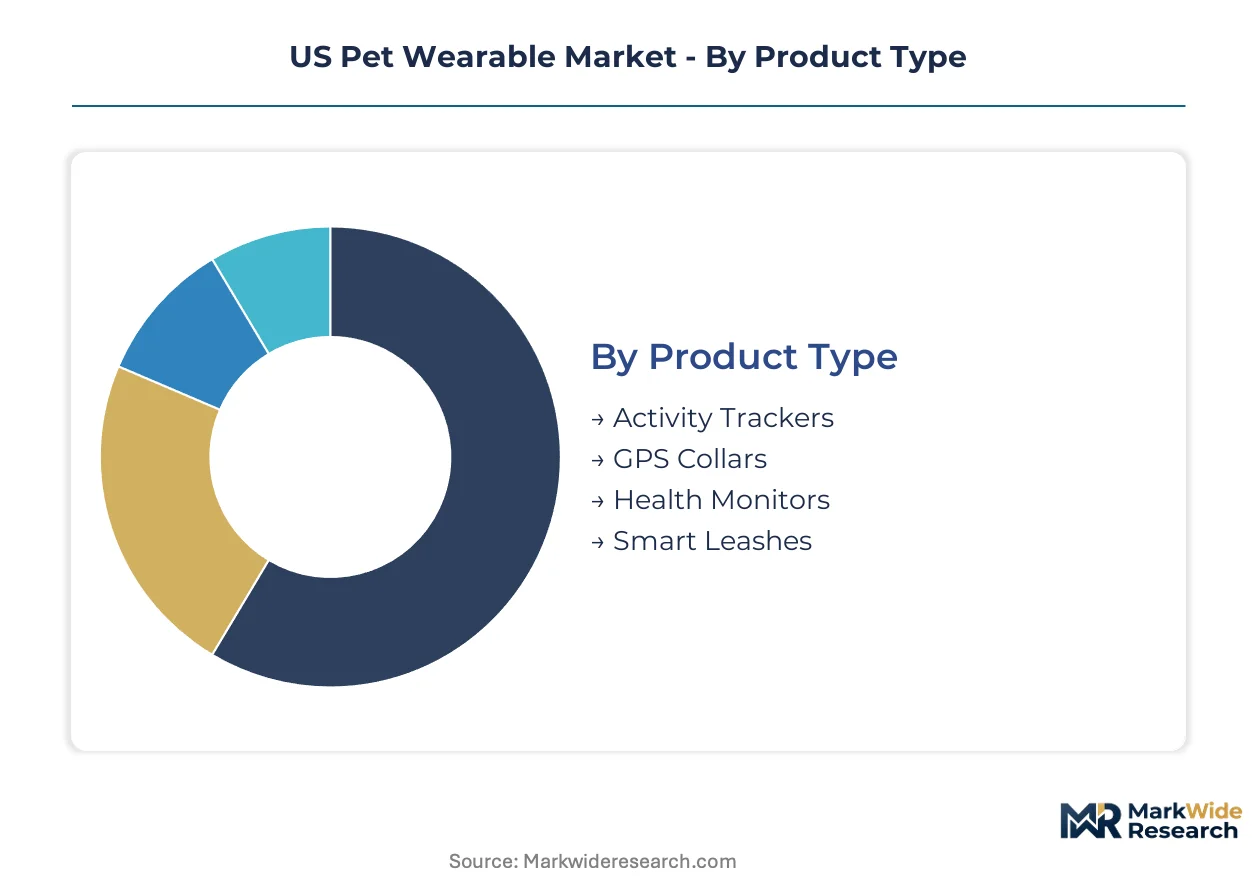
Device architecture and connectivity choices determine procurement patterns across veterinary and consumer channels. Understanding segment boundaries clarifies where FDA validation requirements apply versus FCC certification alone.
Product Type:
Capital intensity peaks in segments requiring clinical-grade sensor validation and extended battery engineering.
- Activity Trackers:Accelerometer-based motion logging devices measure step counts, sleep duration, and calorie expenditure through tri-axial sensing. Demand clusters in California metropolitan corridors where urban pet owners prioritize fitness benchmarking against breed-specific baselines.
- GPS Collars:Location-tracking hardware integrates multi-constellation satellite receivers with LPWAN transceivers for real-time coordinate transmission. Texas veterinary networks embed these into roaming recovery protocols for large-animal practices, driving institutional procurement volumes.
- Health Monitors:Photoplethysmography-enabled devices capturing heart rate variability, respiratory patterns, and temperature fluctuations.
- Smart Leashes:Tension-sensing and proximity-alert accessories with Bluetooth tethering to owner smartphones.
Most installed capacity flows through GPS Collars. Expansion is steepest in Health Monitors.
Technology:
Certification burden varies sharply—cellular modules require carrier-specific testing while Bluetooth leverages standardized FCC Part 15 pathways.
- Bluetooth:Short-range 2.4 GHz protocol dominates indoor proximity applications with minimal power draw and streamlined electromagnetic compliance. Pet specialty retailers in California metropolitan areas stock Bluetooth-dominant SKUs for apartment-dwelling cat owners.
- Cellular:Sub-GHz LPWAN architectures enable nationwide roaming without Wi-Fi dependency, critical for rural search-and-recovery scenarios. Texas cattle ranches and hunting dog operations drive demand for satellite-backup cellular collars where terrestrial coverage gaps persist.
- RFID:Passive identification tags for shelter intake and microchip verification workflows.
- Wi-Fi:Home-bound connectivity for stationary monitoring stations and charging base communications.
Bluetooth claims the largest installed base. Cellular is climbing the fastest as rural veterinary protocols expand.
End User:
Procurement authority splits between individual consumers and institutional buyers with contrasting validation requirements.
- Pet Owners:Direct-to-consumer purchasers selecting devices through specialty retail and e-commerce channels. California and Texas urban demographics show diverging preferences—coastal markets favor subscription-light hardware, while Texas buyers accept bundled multi-year GPS service contracts.
- Veterinary Clinics:Clinical settings requiring FDA-adjacent device validation for diagnostic-grade physiological monitoring. University-affiliated hospitals in Texas and California anchor trial networks for algorithm development.
- Training Facilities:Behavior modification centers utilizing location and activity data for performance conditioning.
- Animal Shelters:Municipal and nonprofit intake operations prioritizing low-cost identification and basic location recovery.
Veterinary Clinics command the highest per-unit spending. Expansion is steepest among Training Facilities integrating biometric feedback into behavior protocols.
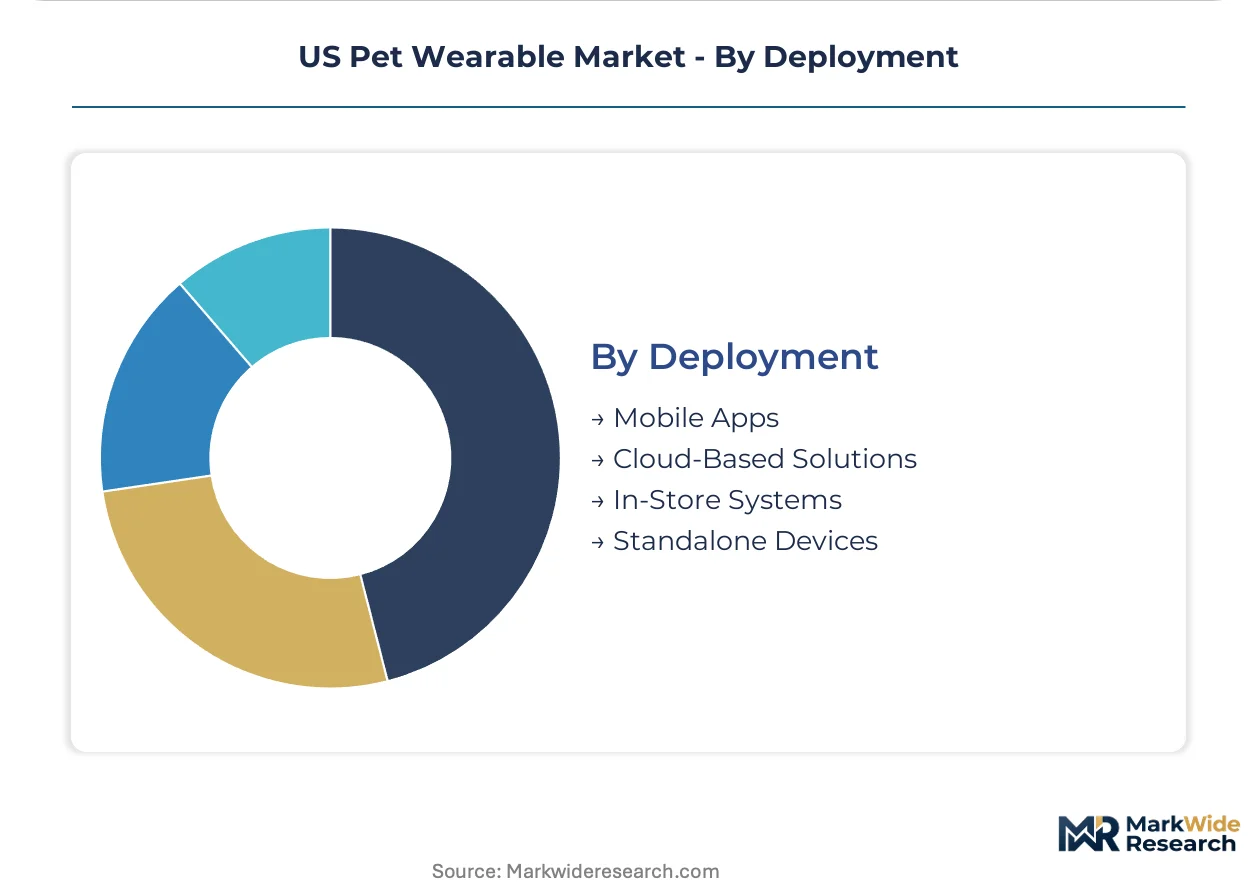
Deployment:
Data architecture choices determine recurring revenue potential and cybersecurity exposure profiles.
- Mobile Apps:Smartphone-tethered interfaces processing Bluetooth and cellular data streams for real-time owner alerts. California consumers demonstrate strongest preference for app-centric control, driving OEM investment in iOS-first development roadmaps.
- Cloud-Based Solutions:Centralized data lakes enabling veterinary clinic dashboard access and insurance underwriting integration. Texas academic veterinary networks pilot cross-platform health record exchange through cloud intermediaries.
- In-Store Systems:Retailer-managed activation and subscription enrollment at point of sale.
- Standalone Devices:Offline-capable hardware with embedded storage and delayed synchronization.
Cloud-Based Solutions capture the most institutional investment. Mobile Apps are gaining share fastest as consumer UX expectations rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California metropolitan corridors anchor domestic demand concentration for US pet wearables, with Texas veterinary networks driving institutional procurement volumes through remote monitoring protocols.
California
Urban pet owners in Los Angeles and San Francisco Bay Area metros prioritize fitness benchmarking through activity trackers, generating subscription-light hardware preference. California Consumer Privacy Act provisions on biometric data shape vendor compliance roadmaps for health monitor deployments. San Diego anchors photoplethysmography sensor miniaturization R&D through university-affiliated veterinary hospitals.
Texas
Cattle ranches and hunting dog operations in Dallas-Fort Worth and Houston corridors drive cellular-enabled GPS collar demand for rural roaming recovery. FAA regulatory frameworks on drone-integrated retrieval systems enable aerial service pilots in Austin tech corridors. Texas A&M veterinary networks anchor clinical trial recruitment for FDA-adjacent physiological monitoring validation.
New York Metro
Apartment-dwelling cat owners in Manhattan and Brooklyn favor Bluetooth-tethered smart leashes with minimal power draw. State-level pet privacy legislation proposals in Albany create compliance anticipation for biometric data handlers. Cornell veterinary medicine partnerships in Ithaca support algorithm development for respiratory rate extraction.
Florida
Training facilities in Miami and Orlando integrate location and activity data for performance conditioning of sporting breeds. USDA APHIS data interoperability standards pilot programs engage Tampa Bay veterinary networks. University of Florida veterinary school anchors species-specific biometric baseline research for algorithm validation.
Pacific Northwest
Seattle and Portland metros demonstrate strong preference for cloud-based deployment architectures enabling veterinary dashboard access. Washington State consumer protection frameworks on subscription billing transparency influence service plan structures. Microsoft Azure and Amazon Web Services infrastructure concentration supports pet health data lake development.
US Pet Wearable Market Key Industry Players
Global majors compete with regional champions across hardware manufacturing and subscription service provisioning, producing a tiered structure where GPS chipset designers, veterinary-grade specialists, and consumer-facing platforms occupy distinct competitive positions. Market consolidation concentrates among vertically integrated hardware vendors and recurring-revenue platform operators. Three archetypes dominate: silicon-integrated device manufacturers, clinical-channel specialists, and subscription-first service providers. Competitive moves center on FCC certification streamlining and USDA APHIS compliance pre-positioning for institutional channel access.
Within the GPS-integrated hardware tier, Garmin Ltd. exemplifies silicon-integrated manufacturing with captive chipset design capabilities. PetPace LLC occupies a position among veterinary-grade specialists anchoring clinical-channel partnerships. Whistle Labs Inc. represents the subscription-first archetype with consumer-facing recurring revenue models. These three entities illustrate the strategic segmentation between hardware margin defense, clinical validation depth, and service monetization scale across the US market.
| Leading Market Players |
|---|
| Garmin Ltd. |
| PetPace LLC |
| Whistle Labs Inc. |
| FitBark Inc. |
| Datamars |
| Avid Identification Systems Inc. |
| High Tech Pet Products Inc. |
| Loc8tor Ltd. |
| Radio Systems Corporation |
| Others |
Cost & Logistics Intelligence
Silicon photonics integration in photoplethysmography sensor manufacturing is compressing production costs while concentrating sourcing leverage among foundries with captive MEMS capabilities. This dual effect reshapes margin structures across GPS collar and health monitor tiers, rewarding vendors with backward integration into chip-scale optical component design.
Pricing Analysis
Input-cost pass-through from lithium-ion cell volatility is compressing hardware margins at the economy tier while subscription bundling sustains premium pricing for cellular-enabled GPS collars. Three-tier pricing structure across premium, standard, and economy levels separates FDA-adjacent clinical validation from FCC-only certification and basic activity tracking. Pricing pressure stems from subscription fatigue in California metropolitan corridors, where urban pet owners resist multi-year service commitments. Pet owners in apartment-dwelling segments show highest price sensitivity, while Texas veterinary clinics absorb premium pricing for diagnostic-grade physiological monitoring.
Supply Chain Analysis
Freight cost escalation from East Asian battery pack sourcing is amplifying landed cost volatility for hardware vendors dependent on contract manufacturer consolidation in China, South Korea, and Japan. Silicon wafer supply draws from Taiwan and US foundry networks, while photoplethysmography sensor modules rest on Japanese optical component specialists. Single-source vulnerability in sub-GHz LPWAN module certification with US cellular carriers extends hardware launch schedules unpredictably. Distribution runs through pet specialty retail chains in California and Texas, with direct-to-consumer e-commerce gaining share fastest among subscription-first service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Pet Wearable Market functions as a geographic-arbitrage play between California's subscription-light consumer preference and Texas's bundled-service veterinary procurement, exploiting the cost differential in customer acquisition economics across coastal and interior corridors.
For Market Incumbents: Deploy captive veterinary clinical trial networks to accelerate FDA-adjacent validation workflows and defend against emerging silicon-integrated device manufacturers encroaching on health monitor premium tiers. Backward integration into GPS chipset design preserves hardware margins against foundry cost volatility. Channel control through exclusive partnerships with Texas A&M-affiliated veterinary networks locks in institutional procurement volumes. For New Entrants and Emerging Players: Veterinary clinic dashboard providers represent the most penetrable channel partner type for cloud-based deployment architectures, particularly in Pacific Northwest metros where Seattle and Portland demonstrate strongest preference for centralized data lake access. White-space targets include USDA APHIS-compliant cross-platform health record exchange and drone-integrated aerial recovery services in FAA-clarified Austin corridors. Month-to-month subscription unbundling offers the sharpest go-to-market angle against incumbent annual-contract bundling. For Investors and Strategic Acquirers: Roll-up economics work for subscription-first service providers because recurring revenue per activated device concentrates customer lifetime value in platforms with above-average retention metrics. Long-term viability hinges on insurance underwriting integration penetration, where quantified wellness datasets from continuous health monitors feed actuarial models. Acquisition target archetype: consumer-facing platforms with 100,000-plus activated devices and veterinary channel partnerships in California or Texas. Watch cellular carrier certification timeline compression as the inflection signal for hardware launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| FDA-Adjacent Validation Investment | Clinical evidence packages for biometric sensors unlock veterinary clinic procurement in Texas academic hospital networks. |
| Silicon Photonics Integration | Chip-scale photoplethysmography modules reduce power consumption and mechanical failure rates in sub-30 gram form factors. |
| USDA APHIS Compliance Pre-Positioning | Early adoption of cross-platform pet health record exchange standards secures institutional channel access ahead of federal mandates. |
| Drone-Integrated Retrieval Development | FAA regulatory clarity on unmanned aircraft coordination with GPS collar coordinates enables aerial recovery service monetization. |
| Subscription Unbundling | Month-to-month GPS tracking plans capture California metropolitan consumers resisting multi-year hardware-service bundles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with veterinary clinic procurement managers, pet specialty retail category buyers, cellular carrier certification engineers, FDA regulatory affairs consultants, and pet insurance actuarial specialists with secondary validation against FCC Part 15 and Part 27 filings, FDA Center for Veterinary Medicine guidance documents, USDA APHIS interoperability standards drafts, and SEC 10-K disclosures from publicly traded hardware vendors. Bottom-up device shipment modeling and top-down addressable market sizing were cross-referenced for triangulation.
Comparable-period anchoring linked historical reference data to projection outputs across the analysis window, with segmentation modeling across product type, connectivity technology, end-user archetype, and deployment architecture. CAGRs were derived from fitted growth curves applied to unit volume and average selling price trajectories. Industry-specific forecast inputs incorporated cellular carrier certification timeline assumptions and veterinary remote monitoring protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cell supply disruption, FDA guidance finalization timelines, and state-level pet privacy legislation fragmentation in California and Texas. Forecasts reflect documented assumptions about hardware-service bundling persistence and subscription fatigue thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Wearable Camera Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Kids Watch Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Smart Band Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Wearable Communicator Market