
 Water Heater Market | 2026-2036
Water Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Water Heater Market Analysis
Heat pump refrigerants are realigning product economics as R-410A gives way to lower-GWP alternatives like R-32 and R-454B. A.O. Smith leverages its captive compressor supply chain to offset refrigerant transition costs. Rheem Manufacturing Company anchors its North American position through deep distribution partnerships with utility rebate programs. Bosch Thermotechnology differentiates via European engineering standards that command premium positioning in retrofit markets.
A water heater is a thermodynamic appliance engineered to raise and store potable water between 120°F and 140°F using electric resistance elements, gas combustion, or ambient heat transfer, serving residential hygiene, commercial food service, and industrial process requirements. Tankless systems lead in new construction for space-constrained multifamily developments, while heat pump technology captures the fastest growth trajectory as building electrification mandates proliferate. Storage tanks retain dominant installed-base share but face margin compression from efficiency regulations and longer replacement cycles.
The U.S. Department of Energy minimum efficiency standards, the EU Ecodesign Directive, and China's GB standards collectively force manufacturers toward heat pump and condensing gas architectures. India's BIS certification requirements for electric storage units create compliance barriers for unorganized imports. Stakeholders must monitor refrigerant phase-down timelines and utility rebate program redesigns to calibrate portfolio allocation between gas, electric, and heat pump platforms.
Market Dynamics
Heat pump water heaters are absorbing capital allocation from conventional gas and electric resistance architectures as building electrification mandates tighten across North America and Europe, compressing the addressable market for legacy storage-tank technologies and forcing incumbent manufacturers to reconfigure assembly footprints.
Growth Catalysts
- US IRA Residential Clean Energy Credit:Federal tax incentives covering up to 30% of heat pump water heater installation costs are accelerating replacement cycles in single-family retrofits across the Midwest and Northeast corridors.
- Commercial foodservice expansion:Quick-service restaurant chains in Southeast Asia are standardizing tankless systems for back-of-house sanitation compliance, driving specification pull-through for high-BTU gas-fired units.
- R-32 refrigerant transition:Lower-GWP alternatives are unlocking heat pump water heater deployment in jurisdictions with strict F-Gas Regulation phase-down schedules, particularly in Nordic retrofit markets.
Market Restraints
- Copper and nickel price volatility:Heat exchanger raw material costs swing 15-40% on London Metal Exchange indices, eroding manufacturer margin buffers on fixed-price utility contracts.
- Compressor supply concentration:Rotary and scroll compressor production clusters in China and Japan create single-source vulnerability for heat pump water heater assemblers outside integrated supply chains.
- Cold-climate performance degradation:Ambient air-source heat pump water heaters lose 40-60% efficiency below 40°F, limiting addressable market penetration in Canadian Prairie and Upper Midwest housing stock without hybrid backup configurations.
Strategic Opportunities
- India urban electrification corridors:BIS-certified electric storage units face underpenetration in tier-2 and tier-3 cities where grid reliability improvements are outpacing gas infrastructure extension.
- Grid-interactive water heating:Utility-controlled thermal storage programs are creating new revenue streams for heat pump water heater owners through demand response aggregation in California and Texas ISO markets.
- Commercial heat pump integration:Convergence with solar thermal and battery storage systems is opening packaged energy-as-a-service contracts for hotels and multifamily developers in Germany and the Netherlands.
Industry Challenges
- Refrigerant handling certification gaps:EPA Section 608 technician shortages are extending installation lead times for heat pump water heaters in rural US markets, constraining volume throughput despite rebate availability.
- Legacy electrical panel upgrades:Residential service capacity limitations require 200-amp panel replacements that add $2,000-$4,000 to project economics, creating sales friction in older housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Heater Market |
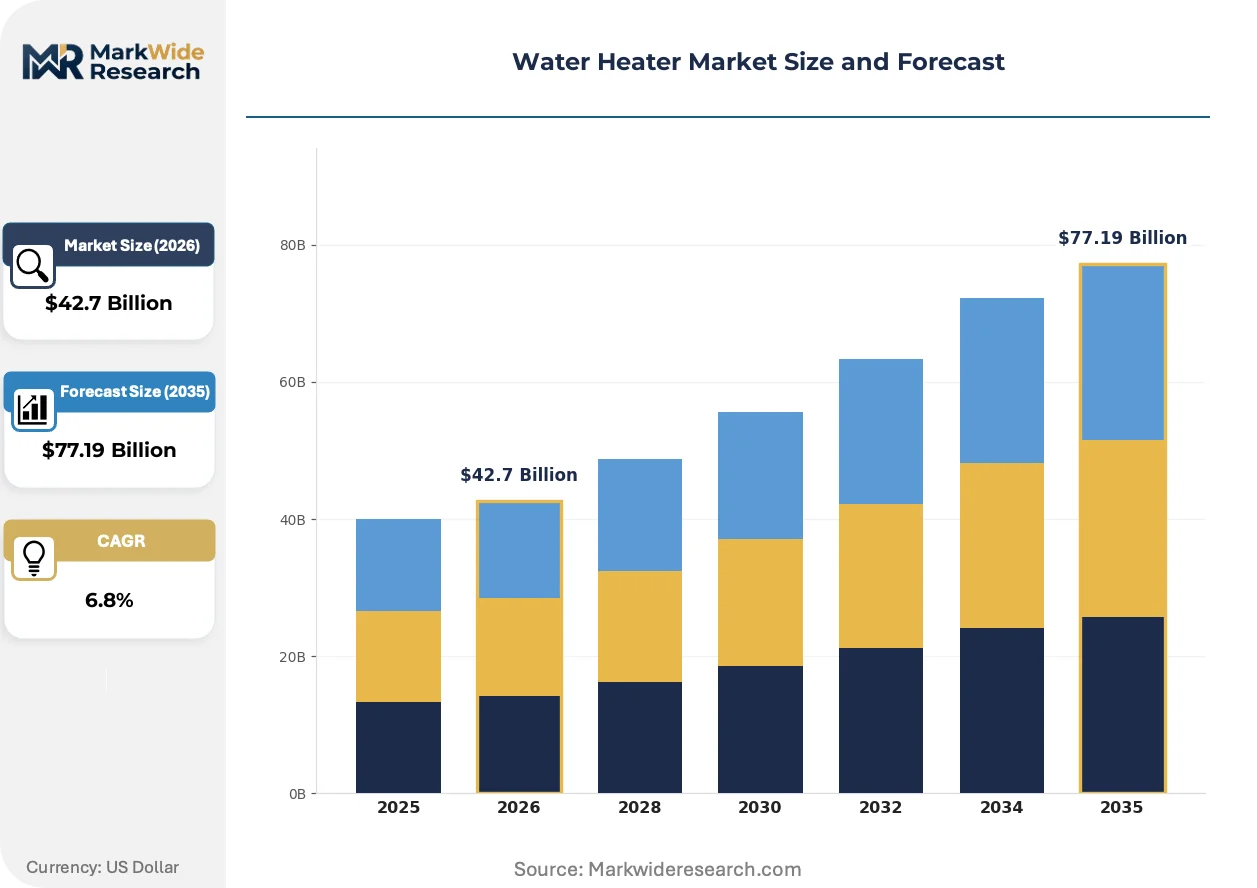
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tankless, Storage, Heat Pump, Solar Technology: Electric, Gas, Propane, Hybrid End User: Residential, Commercial, Industrial, Hospitality Installation Type: Indoor, Outdoor, Wall-mounted, Freestanding |
| Companies Covered | A.O. Smith, Rheem Manufacturing Company, Bosch Thermotechnology, Bradford White Corporation, Rinnai Corporation, Ariston Holding N.V., Navien Inc., Haier Inc., Lennox International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Heater Market Emerging Trajectories
Product architectures are bifurcating between connected, grid-responsive heat pump systems and simplified, cost-optimized tankless units for emerging market housing. Three forces are actively restructuring competitive positioning and value capture mechanisms.
Thermal battery water heaters are absorbing grid flexibility value by pre-heating storage during off-peak renewable generation windows and dispatching stored energy during peak demand periods. Multi-unit residential developers in California and New York are specifying these systems to meet local building electrification ordinances while avoiding costly electrical service upgrades. The technology is absorbing utility incentive dollars that previously flowed to simple resistance-tank replacements, reshaping manufacturer R&D priorities toward controls and software rather than combustion engineering.
The EU F-Gas Regulation phase-down timeline is compressing refrigerant choice windows for heat pump water heater manufacturers, with R-454B and R-290 emerging as the dominant replacement pathways for R-410A-dependent platforms. Equipment redesign cycles have accelerated from five-year to two-year intervals, straining engineering resources at mid-tier assemblers. Nordic and German markets are responding fastest, with several national building codes now mandating sub-150 GWP refrigerants in new construction specifications.
Homeowner specification behavior is fragmenting between digital-native buyers who prioritize connected-device integration and price-sensitive replacement purchasers who defer to contractor recommendations. Big-box retail and direct-to-consumer channels are capturing share from traditional plumbing wholesale in North America, while in India, organized multi-brand outlets are displacing unorganized dealer networks for electric storage unit distribution. The shift is most pronounced in suburban US markets where online research precedes 60% of water heater replacement decisions.
Water Heater Market Segmentation
Water heater procurement decisions bifurcate sharply between retrofit replacements driven by contractor relationships and new construction specifications governed by developer cost engineering. Segmentation clarity enables manufacturers to calibrate R&D spend, distribution partnerships, and rebate program alignment against divergent margin profiles and replacement cycles.
Product Type:
Capital intensity varies dramatically across architectures, with heat pump platforms requiring compressor integration and refrigerant handling infrastructure that tankless units avoid entirely.
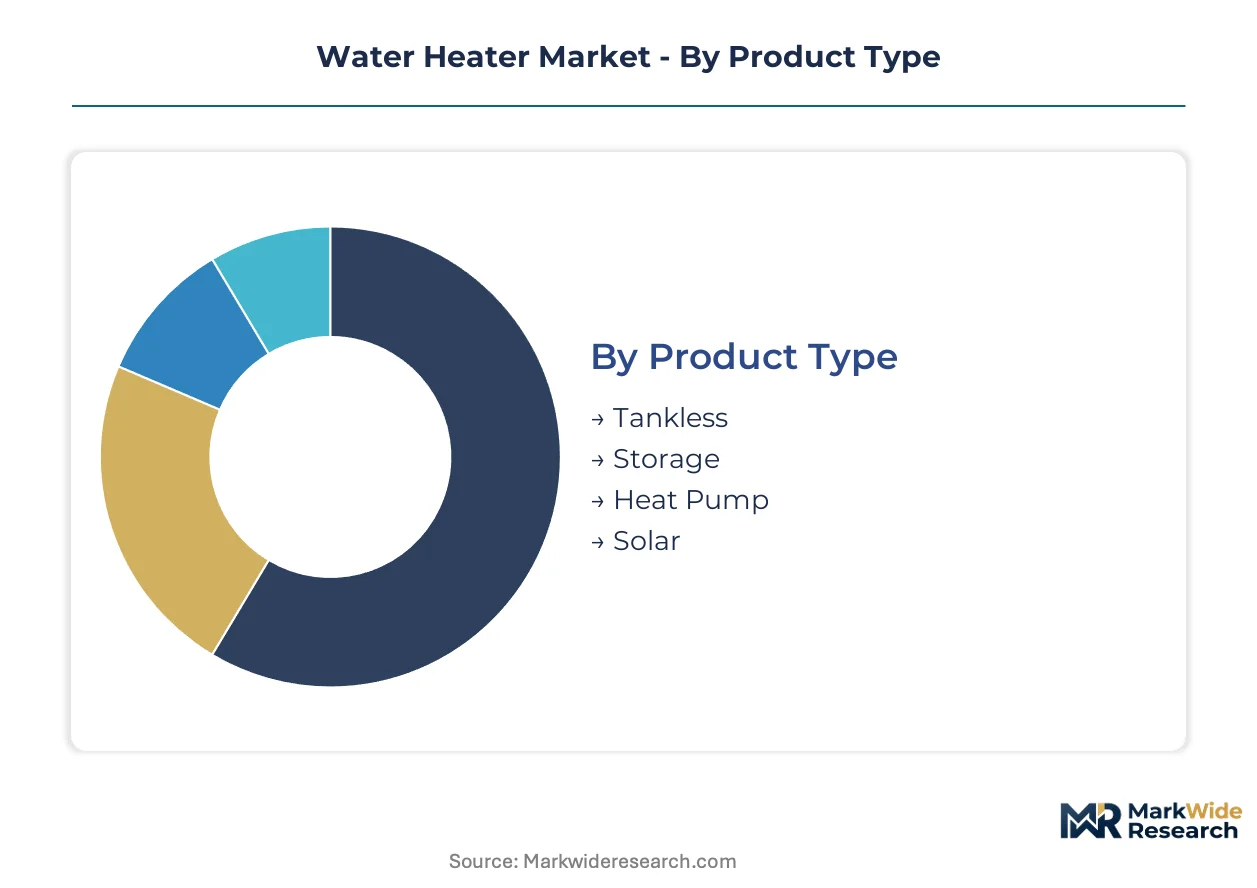
- Storage:Conventional insulated tanks with electric resistance elements or gas burners maintain dominant installed-base presence across single-family housing stock. Demand concentrates in emergency replacement scenarios across the US Midwest and Northeast where existing venting and electrical infrastructure favors like-for-like swaps, though efficiency standards are compressing margins and extending replacement cycles.
- Heat Pump:Vapor-compression systems extracting ambient thermal energy deliver coefficient-of-performance advantages over resistance heating. Specification pull-through is accelerating in California and New York jurisdictions with building electrification mandates, absorbing IRA tax credit flows and utility rebate dollars that previously supported gas alternatives.
- Tankless:Compact gas or electric units providing on-demand heating without storage volume command premium positioning in space-constrained multifamily developments across Southeast Asia.
- Solar:Evacuated-tube or flat-plate collector systems with integrated storage tanks serve niche applications in sun-belt regions with favorable insolation profiles.
Storage units absorb the bulk of installed capacity; heat pump systems are expanding most quickly.
Technology:
Technology choice determines regulatory exposure, with electrification mandates and refrigerant phase-downs rewriting competitive economics across platforms.
- Electric:Resistance-element and heat pump architectures dominate new construction specifications in jurisdictions with carbon-reduction targets. India's urban housing corridors are driving BIS-certified electric storage procurement as grid reliability improvements outpace gas infrastructure extension.
- Gas:Combustion-based systems with atmospheric or power-vented configurations retain contractor preference for retrofit applications. Cold-climate performance limitations of air-source heat pumps preserve gas specification share in Canadian Prairie and Upper Midwest housing stock.
- Propane:LPG-fired units serve rural markets lacking natural gas distribution infrastructure.
- Hybrid:Combined heat pump and resistance-element configurations optimize efficiency across ambient temperature ranges.
Electric platforms are climbing the fastest as building codes tighten; gas retains contractor channel preference for emergency replacements.
End User:
Customer type dictates specification authority, with homeowners deferring to contractors while commercial developers apply lifecycle cost engineering.
- Residential:Single-family and multifamily households represent volume concentration, with replacement cycles averaging 10-15 years. Digital-native buyers in suburban US markets increasingly research connected-device integration before contractor engagement.
- Commercial:Quick-service restaurant chains and retail facilities standardize tankless specifications for back-of-house sanitation compliance in Southeast Asia.
- Industrial:Process heating applications with high throughput requirements specify heavy-duty storage or instantaneous systems.
- Hospitality:Hotels and extended-stay properties prioritize redundancy and recovery rate performance for guest satisfaction.
Residential absorbs the bulk of unit volume; commercial applications are gaining share fastest on foodservice expansion.
Installation Type:
Mounting configuration interacts with space constraints, climate exposure, and service access requirements across housing stock vintages.
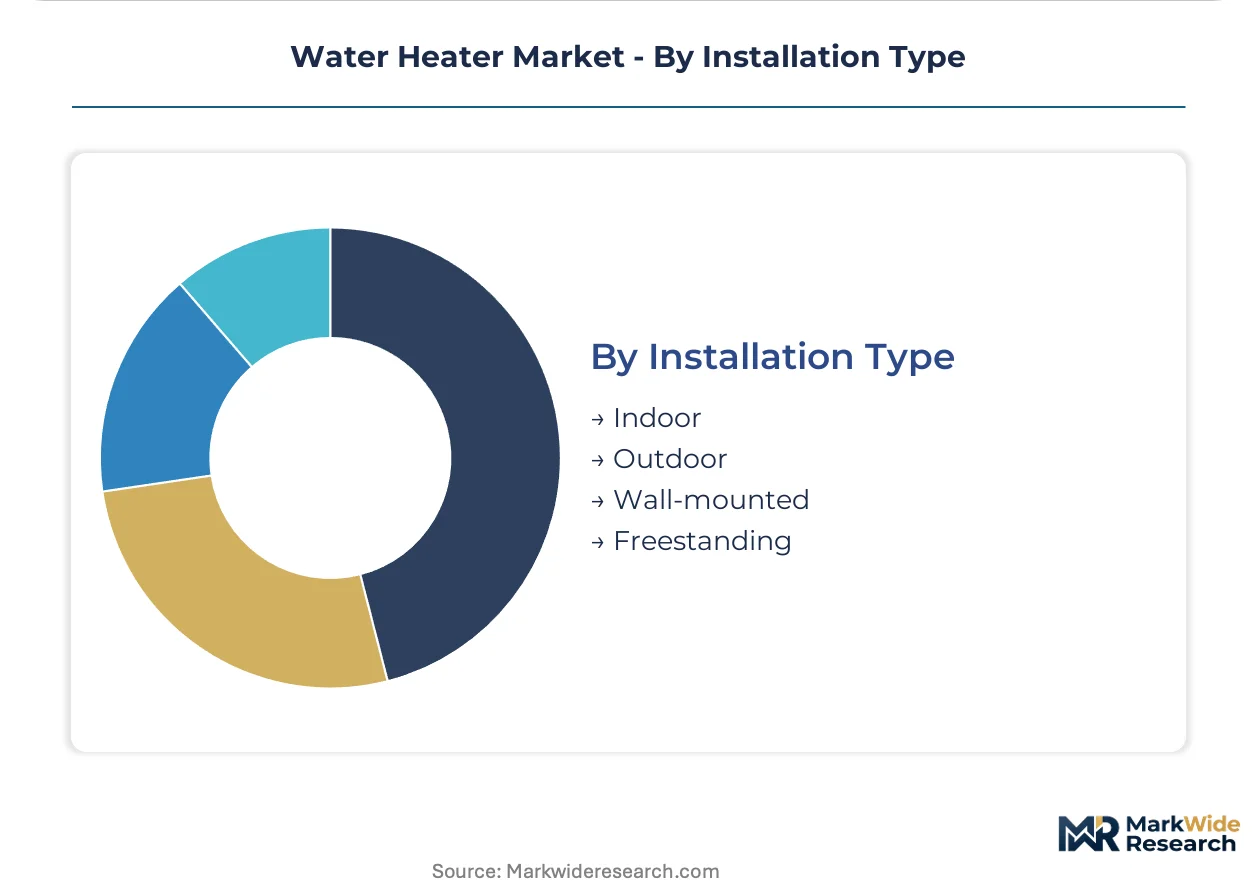
- Indoor:Basement, utility closet, and garage installations dominate North American residential practice, protecting components from weather exposure.
- Outdoor:Exterior mounting common in mild-climate regions reduces ventilation requirements and frees interior space.
- Wall-mounted:Vertical tankless configurations optimize floor space in compact multifamily units across Japanese and Korean urban housing.
- Freestanding:Floor-mounted storage tanks accommodate larger capacities in single-family homes with dedicated utility areas.
Indoor installations retain dominant share; wall-mounted configurations are expanding most quickly on multifamily construction trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban housing corridors concentrate demand acceleration as grid reliability improvements outpace gas infrastructure extension across tier-2 and tier-3 cities.
United States
Midwest and Northeast single-family retrofits absorb IRA Residential Clean Energy Credit flows covering 30% of heat pump water heater installations. The EPA Section 608 refrigerant handling requirements constrain rural installation capacity. Chicago and Detroit metropolitan clusters concentrate emergency replacement volume for conventional storage tanks.
Germany
Nordic retrofit markets drive R-32 and R-290 refrigerant transition specifications for heat pump platforms. The EU F-Gas Regulation phase-down timeline compresses equipment redesign cycles to two-year intervals. Bavarian and North Rhine-Westphalia housing stock dominates heat pump water heater procurement for building electrification compliance.
India
Tier-2 and tier-3 urban corridors generate BIS-certified electric storage unit demand as electrification expands faster than gas network buildout. The Bureau of Indian Standards certification requirements create compliance barriers for unorganized imports. Maharashtra and Gujarat residential construction clusters accelerate tankless unit procurement in space-constrained multifamily developments.
Japan
Wall-mounted tankless configurations optimize floor space in compact Tokyo and Osaka metropolitan housing units. The METI energy efficiency standards drive specification toward heat pump and condensing gas architectures. Kanto and Kansai industrial corridors concentrate compressor supply chain integration for domestic heat pump water heater assembly.
China
GB standards enforcement forces manufacturers toward heat pump and condensing gas product architectures. Yangtze River Delta and Pearl River Delta manufacturing clusters absorb capital allocation from conventional gas and electric resistance platforms. The country's dual carbon goals compress margins for conventional storage models in new construction specifications.
Water Heater Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated incumbents commanding premium positioning in regulated markets while regional assemblers capture volume in price-sensitive corridors. The vendor base organizes around three strategic archetypes: captive compressor integrators leveraging refrigerant transition economics, utility rebate program anchor partners, and European engineering standard specialists. Capacity reconfiguration and distribution partnership restructuring represent the dominant competitive moves as efficiency mandates rewrite product economics.
Among integrated North American manufacturers, A.O. Smith and Rheem Manufacturing Company exemplify the captive supply chain archetype, while Bosch Thermotechnology occupies a position representing European engineering standard differentiation. These three entities anchor the competitive structure through divergent responses to refrigerant phase-down timelines and building electrification mandate proliferation.
| Leading Market Players |
|---|
| A.O. Smith |
| Rheem Manufacturing Company |
| Bosch Thermotechnology |
| Bradford White Corporation |
| Rinnai Corporation |
| Ariston Holding N.V. |
| Navien Inc. |
| Haier Inc. |
| Lennox International Inc. |
| Others |
Supply Flow & Price Mechanics
Captive compressor integration anchors both supply resilience and margin defense for heat pump water heater manufacturers navigating refrigerant transition costs. This backward integration into compressor production shields integrated assemblers from single-source vulnerability while supporting premium positioning against contract manufacturers dependent on Chinese and Japanese supply clusters.
Pricing Analysis
The volume-mid economy split separates emergency replacement storage tanks from specification-driven heat pump systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in conventional gas storage is intensifying because efficiency standards are extending replacement cycles. Price-sensitive replacement purchasers in older US housing stock defer to contractor recommendations, while least-sensitive buyers in California and New York prioritize connected-device integration and grid-interactive capabilities.
Supply Chain Analysis
Direct-to-contractor channels dominate emergency replacement volume, while specification sales run through developer and utility rebate program partnerships. Manufacturing concentrates in China, Japan, and the United States, with Yangtze River Delta and Pearl River Delta clusters absorbing capital allocation from legacy platforms. Production draws from copper, nickel, and refrigerant inputs vulnerable to London Metal Exchange price swings. Single-source vulnerability in rotary and scroll compressor supply creates structural risk for assemblers outside integrated supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around manufacturers with captive compressor supply chains as refrigerant phase-down timelines and efficiency mandates force weaker assemblers toward contract manufacturing or exit.
For Market Incumbents: Anchor North American positioning through deep utility rebate program partnerships that capture IRA Residential Clean Energy Credit flows. Secure backward integration into compressor production to offset R-32 and R-454B transition costs while defending margin buffers against fixed-price utility contract exposure. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer white-space access in suburban US markets where online research precedes contractor engagement. Target India's tier-2 and tier-3 urban corridors for BIS-certified electric storage unit distribution as organized multi-brand outlets displace unorganized dealer networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated North American manufacturers seeking refrigerant-handling certification infrastructure and utility rebate program anchorship. Long-term viability favors assemblers with captive compressor supply and European engineering standard differentiation. Monitor EPA Section 608 technician shortage resolution as inflection indicator for heat pump water heater volume throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | Accelerated R-454B and R-290 transition compresses engineering cycles to meet EU F-Gas Regulation phase-down timelines. |
| Utility Rebate Program Partnership | Deep distribution alignment with Midwest and Northeast IRA credit flows secures specification pull-through for heat pump platforms. |
| Compressor Supply Integration | Captive production of rotary and scroll compressors offsets raw material volatility and single-source vulnerability. |
| Grid-Interactive Controls Development | Software and thermal battery integration captures demand response revenue streams in California and Texas ISO markets. |
| India Distribution Network Buildout | Organized multi-brand outlet penetration in tier-2 and tier-3 cities leverages BIS certification barriers against unorganized imports. |
Methodological Framework
Document review covered regulatory filings from the EPA, EU Ecodesign Directive documentation, and BIS certification records, complemented by interviews with water heater manufacturer product strategy directors, utility rebate program managers, and HVAC contractor network heads. Secondary validation drew from DOE efficiency standard dockets, F-Gas Regulation implementation reports, and India Bureau of Energy Efficiency circulars. Bottom-up unit shipment modeling and top-down construction spend allocation were triangulated against utility incentive disbursement data.
Output modeling produced segment-level value and volume trajectories across the projection horizon. Segmentation dimensions included product architecture, technology platform, end-user category, and installation configuration alongside regional regulatory cluster differentiation. CAGRs were derived from replacement cycle analysis, new construction specification rates, and electrification mandate penetration curves. Forecast inputs incorporated refrigerant phase-down timelines, utility rebate program redesign schedules, and raw material price index volatility assumptions.
The model holds under stable regulatory implementation schedules and consistent utility incentive funding levels; deviation in EPA Section 608 enforcement intensity or IRA credit renewal negotiations would shift replacement cycle acceleration timing. Practitioners should monitor F-Gas Regulation amendment proposals and India grid reliability investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Fan Market
Appliances
Digital Showers Market
Appliances
Laundry Kiosk Market
Appliances
Electrical Appliances Plastics Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Large Cooking Appliance Market
Appliances
United States Washing Machine Market
Appliances
Middle East Water Heater Market
Appliances
APAC White Goods Market
Appliances
Residential Vacuum Cleaners Market
Appliances
Europe Tumble Dryers Market
Appliances
Mexico Washing Machine Market
Appliances
Lightwave Microwave Oven Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Mobile Refrigerators Market
Appliances
Oman Microwave Ovens Market