
 Golf Trolley Market | 2026-2036
Golf Trolley Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Trolley Market Analysis
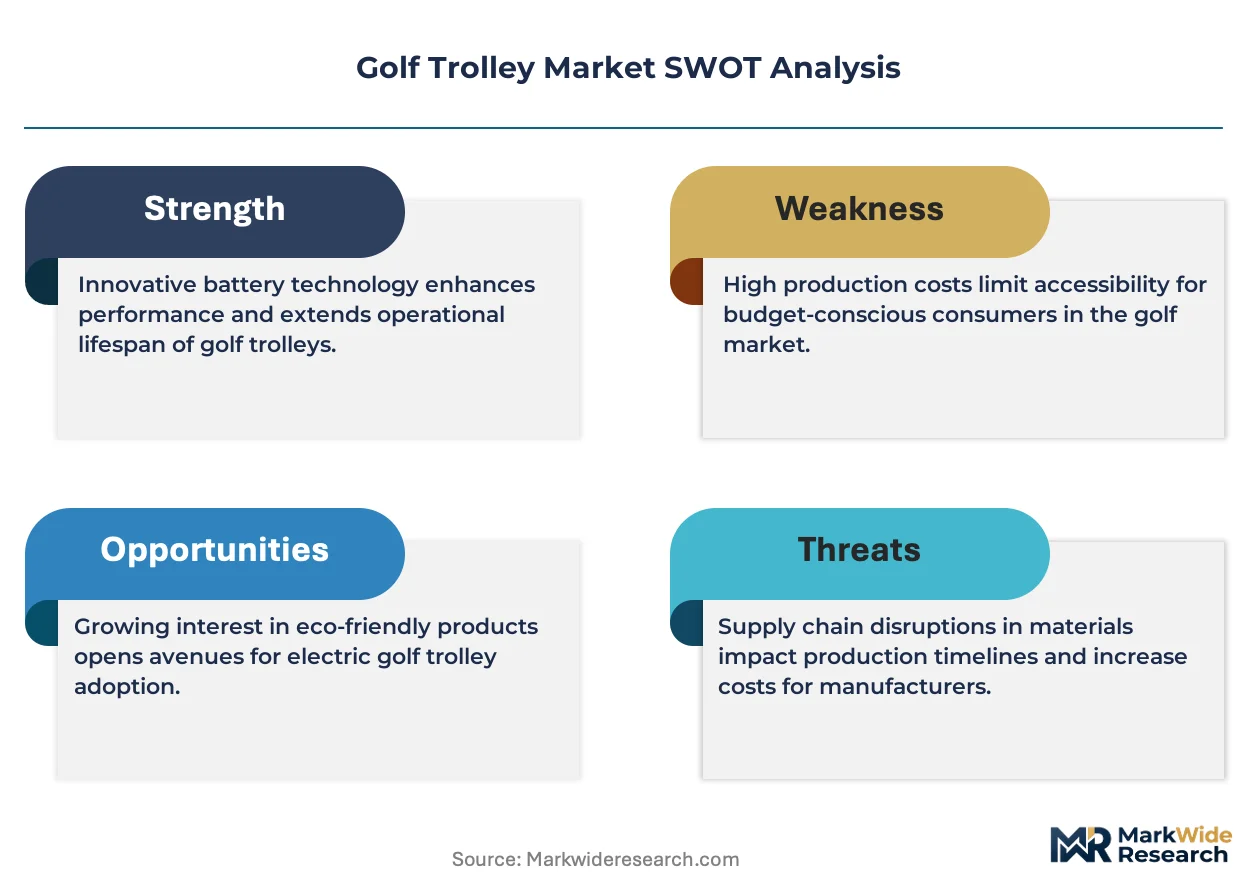
Premium lithium-ion power systems is reorganizing competitive dynamics in golf trolleys. Motocaddy leverages its battery technology leadership to command positioning in the electric segment. PowaKaddy anchors its presence through extensive club-fitting partnerships across the United Kingdom and Ireland. Stewart Golf differentiates via handcrafted aluminum chassis manufacturing and direct-to-consumer channel control.
A golf trolley is a wheeled conveyance designed to transport golf bags and equipment across course terrain, typically constructed from aluminum tubing or carbon fiber composites with load capacities exceeding twenty kilograms and integrated braking mechanisms for slope navigation. Electric variants incorporate sealed lead-acid or lithium-ion battery packs driving dual-motor differential systems for remote-controlled or follow-mode operation. Aluminum construction dominates unit economics due to its strength-to-weight ratio and weldability, while carbon fiber commands margin pools in the premium tier where professional golfers and high-amateur segments concentrate purchasing power. Electric trolleys represent the fastest-growing product category as battery cost curves improve accessibility, whereas manual push trolleys retain volume leadership in entry-level and junior programming at municipal courses.
The Consumer Product Safety Commission governs electrical safety standards for battery-powered trolleys sold in the United States, while the EU Machinery Directive and CE marking requirements shape product access across European member states. The EPA's evolving lithium battery disposal regulations influence end-of-life costs and manufacturer take-back program designs. Stakeholders must monitor battery chemistry substitution timelines and regional compliance harmonization as determinants of sourcing strategy and pricing architecture.
Market Dynamics
Lithium-ion battery energy density improvements are compressing unit costs and expanding electric trolley accessibility to amateur segments previously priced out of powered mobility solutions.
Growth Catalysts
- IRA clean energy tax credits:US-based battery pack assembly qualifies for manufacturing incentives, lowering landed costs for domestic producers serving North American demand.
- Sun Belt municipal course programming:Year-round playability in Florida, Arizona, and Texas sustains replacement cycles and fleet refresh rates unavailable in seasonal markets.
- Lithium iron phosphate chemistry:Enhanced thermal stability and cycle life versus legacy cobalt formulations reduce warranty reserve requirements and total cost of ownership.
Market Restraints
- Raw material concentration:Cathode precursor processing concentrates in China, exposing margin structures to export licensing volatility and geopolitical friction.
- Sealed lead-acid overhang:Entry-level price anchoring by legacy battery chemistry constrains premium positioning for lithium-powered variants at municipal procurement.
- CE marking complexity:EU Machinery Directive conformity assessment timelines extend product launch windows by four to six months versus comparable US EPA registrations.
Strategic Opportunities
- India course development:Greenfield resort construction in Karnataka and Maharashtra creates first-mover positioning for electric trolley fleet suppliers before domestic manufacturing scales.
- Direct-to-consumer channel:Bypassing pro shop intermediaries captures margin pools and enables subscription-style battery replacement programs.
- Follow-mode sensor fusion:Integration of ultrawideband positioning with machine vision enables hands-free operation distinct from basic remote control.
Industry Challenges
- Battery diagnostics talent:Firmware engineering for state-of-charge algorithms and thermal management outpaces vocational training pipeline output.
- Waterproofing certification:IP67 validation for electronics housings requires capital-intensive environmental chamber testing that strains mid-tier R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Trolley Market |
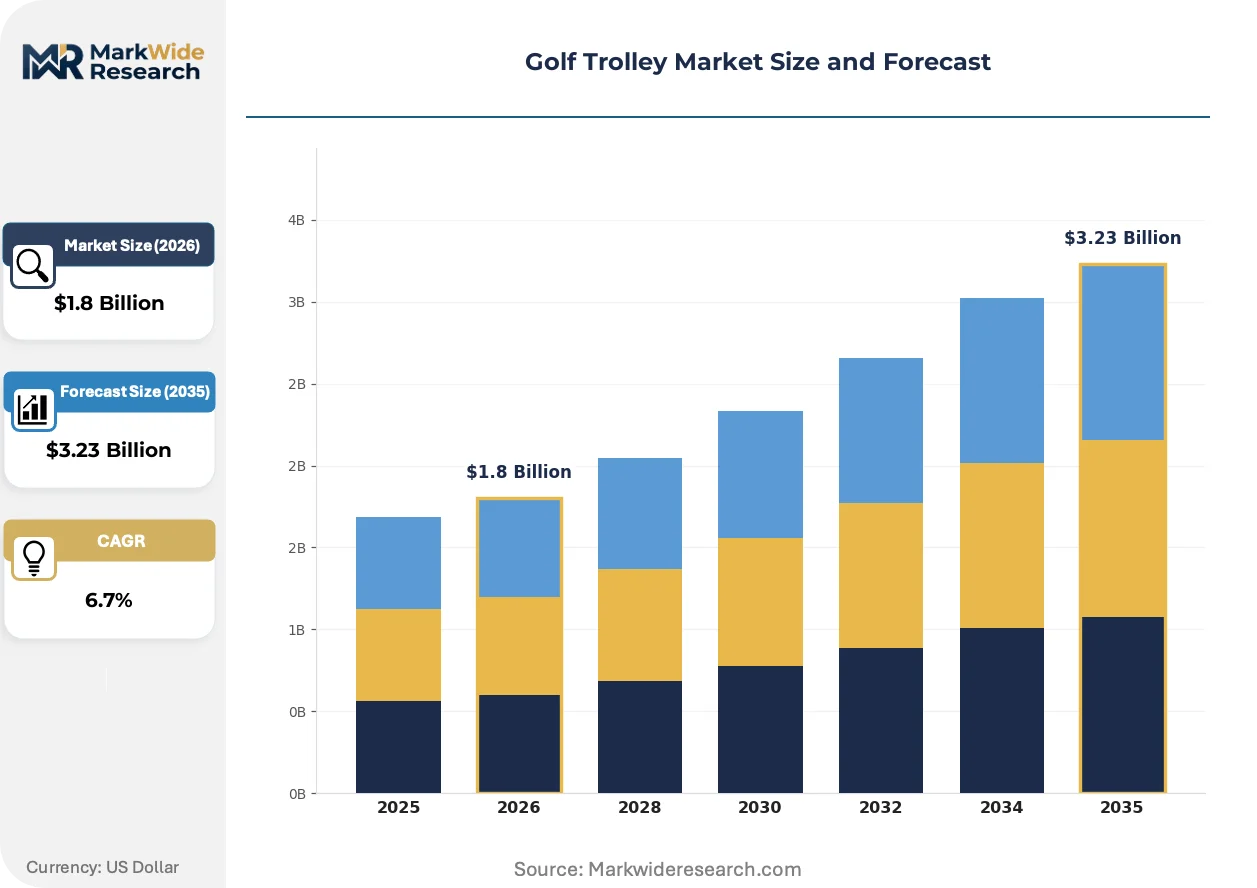
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Trolleys, Electric Trolleys, Push Trolleys, Pull Trolleys Material: Aluminum, Steel, Plastic, Carbon Fiber End User: Amateur Golfers, Professional Golfers, Golf Clubs, Courses Feature: Storage Compartment, Adjustable Handle, Lightweight Design, Folding Mechanism |
| Companies Covered | PLUGG, Cart Tek, Motocaddy, Clicgear, Sun Mountain, PowaKaddy, MGI, Bag Boy, Stewart Golf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Trolley Market Emerging Trajectories
Product architecture is pivoting from mechanical durability to intelligent power management, with software-defined battery systems and connectivity modules becoming primary differentiation vectors.
Lithium iron phosphate cell chemistry is displacing nickel-manganese-cobalt alternatives in mid-tier electric trolleys. Amateur golfers prioritize cycle longevity and thermal safety over energy density. This chemistry shift is compressing warranty cost structures and enabling five-year battery guarantees previously reserved for premium segments.
EPA hazardous waste regulations for end-of-life lithium batteries are tightening material recovery mandates. Manufacturers must redesign pack architecture for disassembly and establish certified recycler networks. United States market participants are responding with prepaid take-back programs bundled at point of sale.
Club-fitting specialists are unbundling trolley selection from bag purchase decisions. Independent retailers now stock narrow electric assortments while directing push trolley demand to direct channels. This disintermediation concentrates most visible in United Kingdom and Ireland pro shop networks.
Golf Trolley Market Segmentation
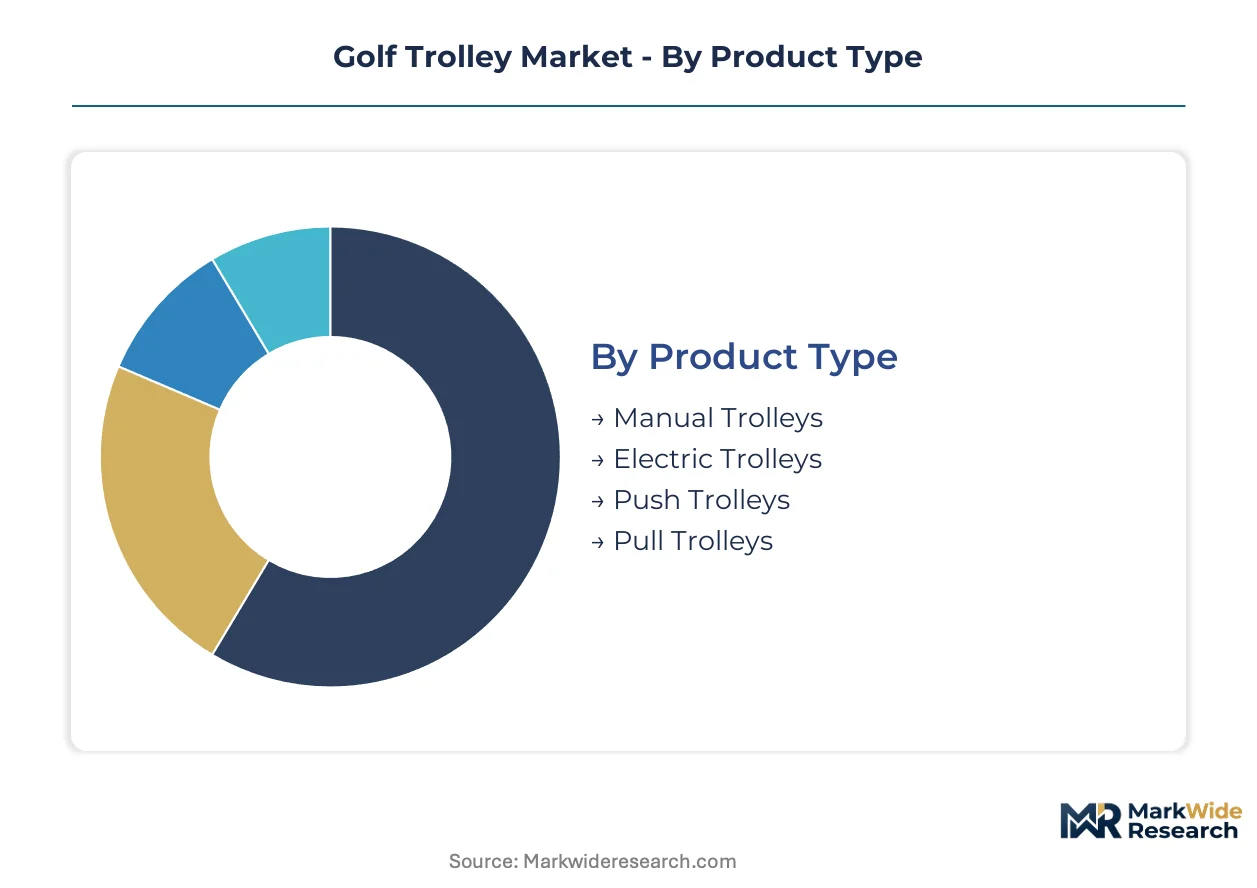
Product architecture in golf trolleys fragments across power source, chassis material, and user sophistication. Regulatory requirements for electrical safety and battery disposal create divergent compliance burdens that reshape competitive positioning within each segment cluster.
Product Type:
CE marking complexity under the EU Machinery Directive imposes four-to-six-month conformity timelines on powered variants, while manual configurations face minimal regulatory friction.
- Manual Trolleys:Unpowered mechanical frames relying on golfer propulsion with basic braking systems for slope management. Municipal courses across Florida and Arizona favor these for junior programming and entry-level fleet procurement where capital constraints dominate acquisition decisions.
- Electric Trolleys:Dual-motor differential systems driven by lithium-ion or sealed lead-acid battery packs enabling remote-controlled or follow-mode operation. Amateur golfers in Sun Belt states represent the primary demand concentration as battery cost curves improve accessibility for previously price-excluded segments.
- Push Trolleys:Three-wheeled configurations with ergonomic handle geometry optimized for walking pace propulsion. Club-fitting specialists in the United Kingdom and Ireland direct this demand toward direct-to-consumer channels, bypassing traditional pro shop intermediaries.
- Pull Trolleys:Two-wheeled trailing designs attaching directly to golf bag frames. These retain niche positioning among traditionalists and compact storage applications where folded footprint constraints dominate purchase criteria.
Established volume favors manual configurations; emerging adoption favors electric variants with lithium power systems.
Material:
Cost tier differentiation separates premium chassis engineering from commoditized frame production.
- Aluminum:Welded tubing construction exploiting strength-to-weight ratios and corrosion resistance for mass-market unit economics. This material anchors production across mid-tier electric and manual segments where manufacturing scalability outweighs absolute performance metrics.
- Carbon Fiber:Layered composite manufacturing delivering maximal stiffness-to-weight for professional and high-amateur segments. Handcrafted production in premium tiers commands margin pools where professional golfer endorsement and tour validation concentrate purchasing power.
- Steel:Entry-level frame material prioritizing durability over weight reduction. Municipal procurement cycles favor these for high-abuse fleet applications where replacement cost minimization supersedes golfer experience optimization.
- Plastic:Injection-molded components for wheels, joints, and accessory housings. This material enables cost engineering in junior and recreational segments where price elasticity constrains retail positioning.
Volume concentration sits with aluminum; margin expansion concentrates in carbon fiber applications.
End User:
Application sophistication determines feature bundling and channel strategy across buyer categories.
- Amateur Golfers:Recreational players seeking powered mobility solutions for walking course enjoyment. This segment drives lithium iron phosphate chemistry adoption as cycle longevity and thermal safety priorities displace energy density preferences in purchase decisions.
- Professional Golfers:Tour players and elite competitors requiring equipment transport meeting competitive standards. Carbon fiber chassis demand concentrates here, with direct manufacturer relationships bypassing retail intermediaries.
- Golf Clubs:Private membership organizations managing fleet procurement for member convenience. These buyers negotiate volume pricing for electric trolley fleets with extended warranty terms and prepaid battery take-back programs.
- Courses:Public and resort operators balancing capital expenditure constraints against golfer satisfaction metrics. Municipal programming in Texas and Arizona represents concentrated demand for durable manual configurations with minimal maintenance requirements.
Procurement scale favors course and club buyers; technology adoption velocity favors amateur golfers.
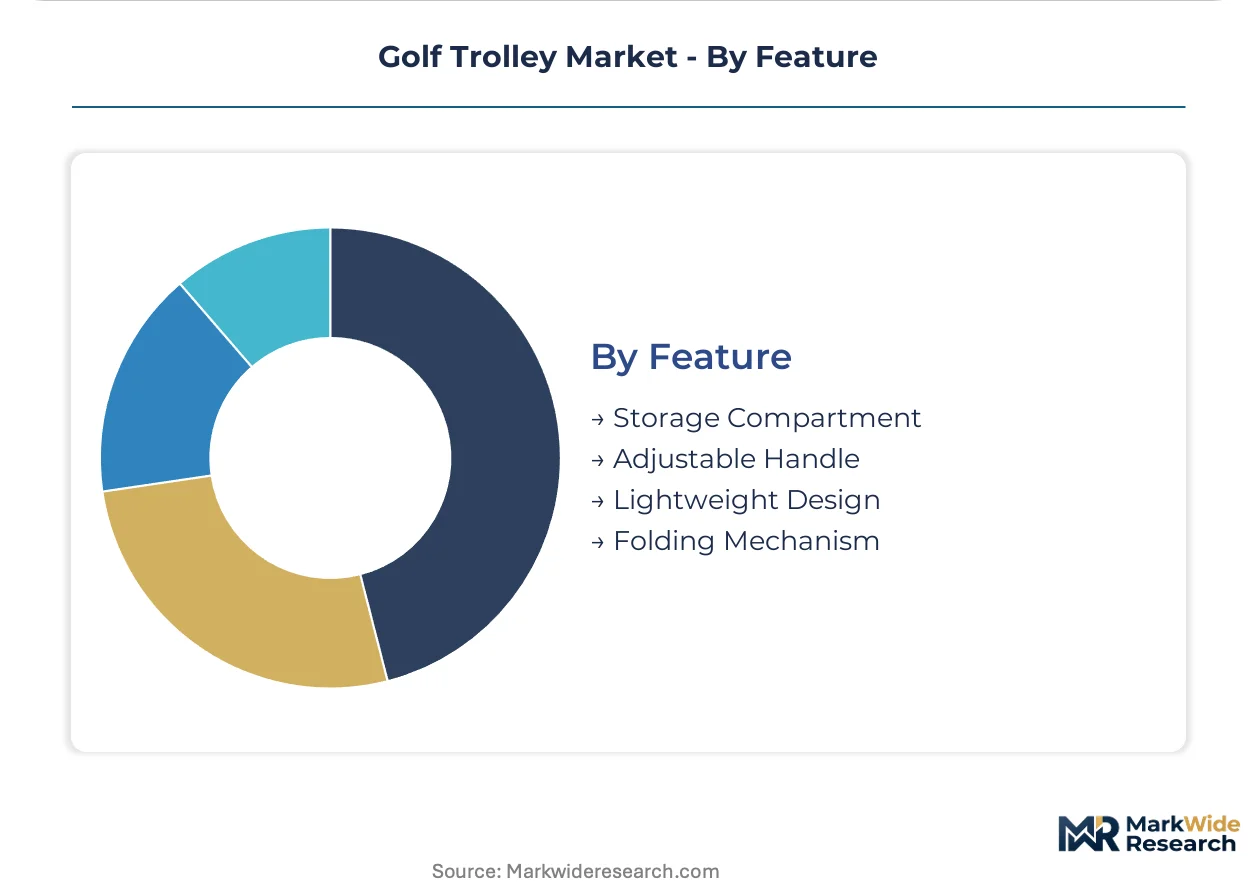
Feature:
Functional differentiation increasingly derives from integrated electronics and smart systems rather than mechanical refinement alone.
- Storage Compartment:Integrated enclosures for accessories, beverages, and personal items. These features anchor premium positioning in electric variants where battery housing geometry creates dedicated compartment space.
- Adjustable Handle:Telescoping or pivoting grip mechanisms accommodating golfer height variation. Ergonomic engineering here separates mid-tier electric products from basic push configurations.
- Lightweight Design:Mass minimization for transport and storage convenience. Carbon fiber and advanced aluminum alloys enable sub-seven-kilogram folded weights in premium segments.
- Folding Mechanism:Collapsible frame engineering for vehicle trunk accommodation. One-step folding systems represent competitive differentiation in electric trolleys where battery pack integration complicates mechanical design.
Mechanical features dominate manual segments; electronic integration defines electric category advancement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chain configuration for golf trolleys concentrates in East Asian battery manufacturing clusters and European precision engineering centers, with final assembly gravitating toward consumer markets. Distribution networks reflect this bifurcation, with lithium cell sourcing dominating landed cost calculations for electric variants.
United States
Sun Belt states including Florida, Arizona, and Texas sustain year-round replacement cycles unavailable in seasonal markets. The IRA clean energy tax credits reward domestic battery pack assembly, lowering costs for producers serving North American demand. Arizona's municipal course networks in Phoenix and Scottsdale represent concentrated fleet procurement for electric configurations.
United Kingdom
Club-fitting specialists across England and Scotland drive premium electric trolley adoption through pro shop networks. CE marking requirements under the EU Machinery Directive extend product launch timelines for powered variants entering the market. London and Manchester retail clusters anchor direct-to-consumer channel experimentation for mid-tier brands.
China
Cathode precursor processing for lithium batteries concentrates manufacturing exposure to export licensing volatility. MIIT industrial standards govern battery safety certification for trolley exports to Western markets. Shenzhen and Dongguan electronics clusters supply control systems and motor assemblies to global OEMs.
Germany
Precision aluminum fabrication and carbon fiber composite engineering serve premium chassis demand from professional segments. REACH chemical regulations and RoHS compliance requirements shape material selection for components entering European distribution. Bavaria's industrial corridor around Munich hosts specialized suppliers for lightweight frame manufacturing.
Australia
Resort development in Queensland and Victoria creates fleet procurement opportunities for electric trolley suppliers. The country's national environmental regulator enforces lithium battery disposal standards influencing end-of-life program design. Melbourne and Sydney golf club networks represent concentrated demand for durable manual configurations in coastal climates.
Golf Trolley Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with battery system innovators competing against aluminum fabrication specialists. The vendor base separates into three tiers: premium handcrafted manufacturers, mid-tier electric specialists, and entry-level volume suppliers. Archetypes include lithium technology integrators, direct-to-consumer channel operators, and municipal fleet contractors. Competitive moves center on strategic partnerships with club-fitting networks and geographic expansion into underpenetrated Sun Belt markets.
Within the battery technology tier, Motocaddy exemplifies European engineering integration, while PowaKaddy occupies a position bridging club-fitting partnerships and retail distribution. Stewart Golf represents the premium handcrafted archetype through aluminum chassis specialization. These three companies anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| PLUGG |
| Cart Tek |
| Motocaddy |
| Clicgear |
| Sun Mountain |
| PowaKaddy |
| MGI |
| Bag Boy |
| Stewart Golf |
| Others |
Supply Flow & Price Mechanics
CE marking requirements under the EU Machinery Directive gate both supplier qualification timelines and price tier separation between powered and manual configurations, compressing margin structures for electric variants while insulating entry-level mechanical products from compliance-driven cost escalation.
Pricing Analysis
CE marking dictates the pricing tier structure across the Golf Trolley Market, separating premium electric configurations with extended conformity timelines from commoditized manual alternatives with minimal regulatory friction. Three-tier pricing stratifies across premium carbon fiber chassis, mid-tier aluminum electric systems, and economy steel push configurations. Pricing pressure intensifies in lithium-powered segments as cathode precursor export licensing volatility from China feeds raw material cost uncertainty. Municipal course procurement teams exhibit highest price sensitivity, while professional golfers and private club buyers prioritize performance specifications over unit economics.
Supply Chain Analysis
Inventory cycles for lithium battery cells currently stretch twelve to sixteen weeks, constraining just-in-time assembly for electric trolley OEMs and forcing working capital commitments that favor larger manufacturers. Manufacturing concentration centers on China for cathode processing and battery pack assembly, Germany for precision aluminum fabrication, and Vietnam for component injection molding. The supply chain draws from lithium carbonate, aluminum tubing, and carbon fiber prepreg as primary inputs. Single-source vulnerability in Chinese cathode precursor processing exposes margin structures to geopolitical friction. Distribution runs through pro shop intermediaries in the United Kingdom and Ireland, direct-to-consumer channels in North America, and municipal fleet contractors across Sun Belt states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes the Golf Trolley Market as lithium iron phosphate chemistry adoption and direct-to-consumer channel experimentation create distinct competitive niches previously consolidated under legacy retail networks.
For Market Incumbents: Shield market position by deepening backward integration into battery pack assembly to capture IRA clean energy tax credits and reduce landed cost exposure. Prioritize certification investment in IP67 waterproofing validation to distance from mid-tier competitors lacking environmental chamber testing capabilities. Defensive consolidation around club-fitting specialist partnerships in the United Kingdom and Ireland resists direct-channel disintermediation threats from digitally native entrants.
For New Entrants and Emerging Players: Anchor in India course development across Karnataka and Maharashtra resort construction, where first-mover positioning precedes domestic manufacturing scale. Target amateur golfer segments in Sun Belt states with subscription-style battery replacement programs that bypass traditional pro shop margin extraction. Deploy follow-mode sensor fusion as differentiated go-to-market positioning against basic remote-control incumbents.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified sporting goods conglomerates with underoptimized golf trolley divisions lacking dedicated battery engineering capabilities. Long-term viability over the projection horizon hinges on software-defined battery management differentiation rather than mechanical chassis commoditization. Monitor lithium iron phosphate chemistry substitution timelines as inflection indicator for warranty cost structure compression and margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Chemistry Transition | Lithium iron phosphate adoption reduces warranty reserves and enables five-year guarantees previously reserved for premium tiers. |
| Direct-to-Consumer Channel Launch | Bypassing pro shop intermediaries captures margin pools and enables subscription battery replacement programs for amateur segments. |
| IP67 Waterproofing Certification | Environmental chamber validation separates premium electric variants from mid-tier competitors with limited R&D budgets. |
| India Geographic Expansion | Greenfield resort construction in Karnataka and Maharashtra creates first-mover fleet procurement positioning. |
| Follow-Mode Sensor Fusion Development | Ultrawideband positioning with machine vision enables hands-free operation distinct from basic remote control systems. |
Methodological Framework
Initial hypotheses were tested against primary input from golf course fleet procurement managers, club-fitting specialists, battery pack engineering leads, and municipal programming directors, then refined through secondary validation against customs records, SEC 10-K filings from sporting goods conglomerates, EPA hazardous waste regulation updates, and lithium carbonate trade flow databases. Bottom-up segment sizing triangulated with top-down market reconstruction across power source, chassis material, and end-user sophistication dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price effects within each segmentation cluster. The analytical framework models product type, material grade, buyer sophistication tier, and regional regulatory cluster as primary dimensions. CAGRs were derived from fitted growth curves anchored to battery cost trajectory assumptions and Sun Belt municipal course fleet refresh cycle data. Specific forecast inputs include lithium iron phosphate chemistry substitution rates and IRA clean energy credit utilization patterns.
Decision-makers should treat outputs as directional under assumptions of continued IRA credit availability and stable cathode precursor export licensing from China; material deviation in either factor would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Fish Hunting Equipment Market
Outdoor & Sports
Sleeper Pads Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Compound Bow and Crossbows Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Inflatable Pool Market