
 Military Hydration Products Market | 2026-2036
Military Hydration Products Market Size, Share, and Industry Trends Forecast 2026-2036
Military Hydration Products Market Outlook
Asset-light manufacturing partnerships and government leasing arrangements for tactical equipment is rewriting competitive dynamics in military hydration. CamelBak Products LLC leverages its vertical integration in reservoir molding to sustain cost advantages on large defense contracts. Source Tactical Gear anchors its position through Israeli Defense Forces relationships and specialized battlefield hydration protocols. Hydrapak LLC competes as a contract manufacturer, supplying bladder technology to multiple uniformed services without maintaining end-brand overhead.
Military hydration products encompass portable fluid delivery systems, electrolyte formulations, and water purification accessories engineered to sustain physiological performance under combat stress, typically constructed from antimicrobial thermoplastic polyurethane with bite-valve flow rates exceeding one liter per minute. The primary purpose centers on preventing heat casualties and maintaining cognitive function during extended dismounted operations in arid or tropical theaters. Ready-to-drink beverages and electrolyte solutions command the largest revenue share among product types due to recurring consumable demand, while hydration tablets represent the fastest-expanding segment as special forces prioritize weight reduction. Pouches and sachets dominate packaging preferences for forward-deployed units, though canteens retain substantial procurement volumes for training facilities where durability outweighs packability concerns.
Natick Soldier Systems Center protocols, NATO standardization agreements for individual equipment, and U.S. Berry Amendment domestic sourcing requirements collectively constrain supplier eligibility while elevating technical performance benchmarks. These frameworks mandate antimicrobial compliance, chemical resistance testing, and provenance documentation that filter out commercial-grade competitors. Stakeholders must monitor evolving joint-service hydration requirements and pre-positioned stockpile modernization schedules to align R&D pipelines with contract windows.
Market Dynamics
Defense procurement officers now compress vendor qualification timelines from 18 months to under 9 months as expeditionary deployment schedules accelerate, forcing hydration system manufacturers to front-load antimicrobial testing and Berry Amendment compliance documentation before contract solicitations release.
Growth Catalysts
- Expeditionary Force Modernization:NATO rapid response units prioritize packable hydration systems for airborne and maritime insertion missions, expanding addressable procurement beyond traditional ground forces.
- REACH Antimicrobial Mandates:European Chemicals Agency restrictions on legacy biocides force reservoir manufacturers toward silver-ion and copper-based alternatives, creating upgrade cycles across existing inventory.
- Electrolyte Formulation Science:Military sports medicine research into hypohydration cognitive degradation drives recurring consumable contracts for precision-dosed sodium-potassium blends.
Market Restraints
- Thermoplastic Polyurethane Feedstock Volatility:Medical-grade TPU resin prices fluctuate with automotive sector demand, compressing bladder manufacturer margins on fixed-price defense contracts.
- Berry Amendment Domestic Sourcing:U.S. defense procurement rules restrict reservoir and valve sourcing to domestic or qualifying country suppliers, excluding lower-cost Asian molding capacity.
- Chemical Resistance Trade-offs:Advanced antimicrobial coatings degrade under exposure to JP-8 fuel vapors and DEET insect repellent, limiting operational lifespan in mechanized infantry applications.
Strategic Opportunities
- Indian Special Forces Expansion:India's Mountain Strike Corps and Marine Commando modernization programs represent underpenetrated demand for high-altitude and amphibious hydration systems.
- Filtration-Convergence Systems:Integration of hollow-fiber membrane technology directly into reservoir bite-valve assemblies addresses forward-operating-base water security gaps.
- Government Leasing Arrangements:NATO equipment pooling mechanisms shift capital expenditure from unit procurement to operational leasing, favoring manufacturers with asset-light service infrastructure.
Industry Challenges
- Natick Certification Timelines:U.S. Army Soldier Systems Center field testing protocols require 14-18 months for antimicrobial efficacy validation, misaligning product development with urgent operational requirements.
- Legacy Canteen Infrastructure:Existing supply chains and training doctrine for aluminum and plastic canteens create institutional resistance to bladder system adoption among reserve and national guard formations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Hydration Products Market |
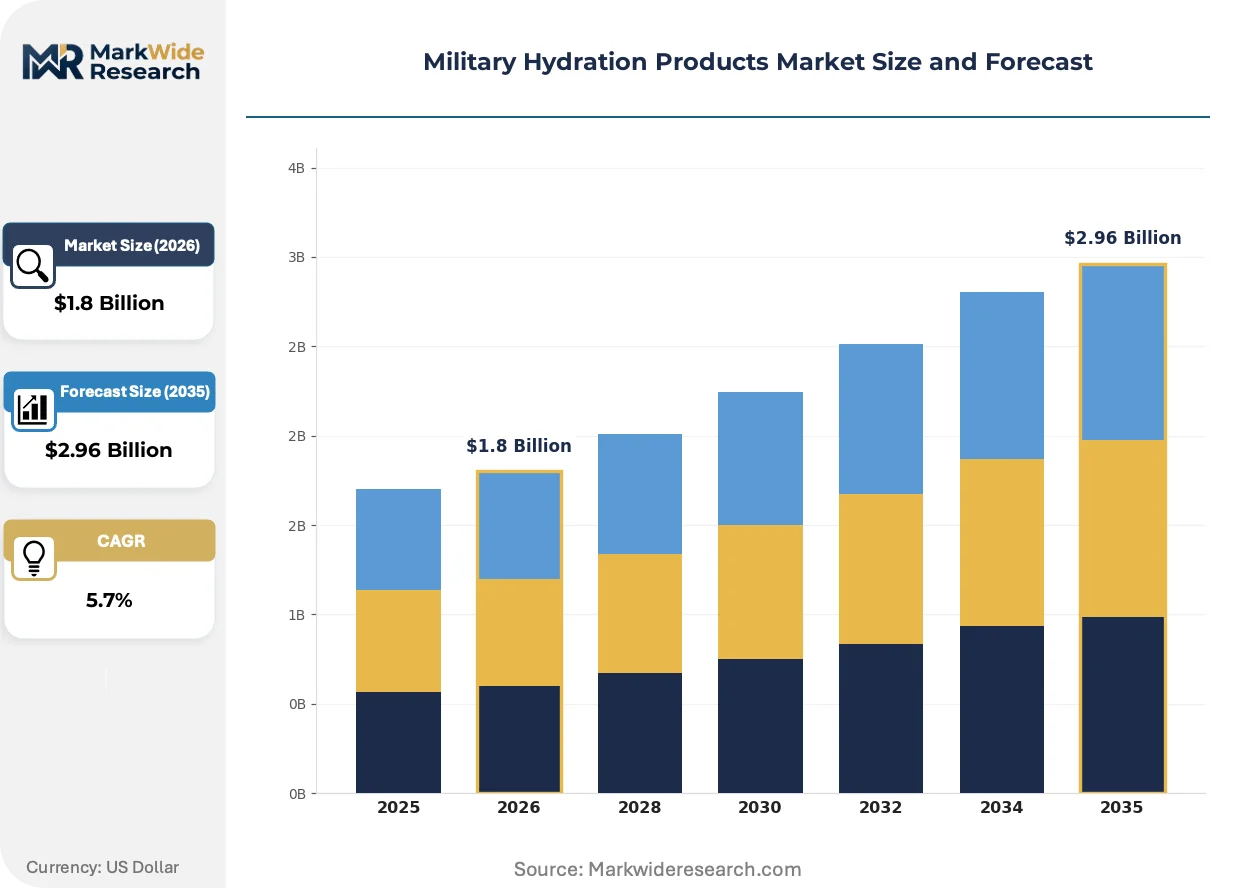
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyte Solutions, Powdered Drink Mixes, Ready-to-Drink Beverages, Hydration Tablets End User: Active Military Personnel, Special Forces, Training Facilities, Defense Contractors Packaging Type: Sachets, Canteens, Boxes, Pouches Distribution Channel: Online Retail, Military Supply Stores, Distributors, Direct Sales |
| Companies Covered | Geigerrig, Cera Products Inc, CamelBak Products LLC, Osprey, Hoist, Source Tactical Gear, Platypus, Lupu Tactical, Hydrapak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Hydration Products Market Strategic Shifts
Active battlefield networking requirements and individual soldier power burdens are compressing hydration system design toward multi-functional platforms that integrate fluid delivery with power management and biometric monitoring.
Closed-cell foam insulation bonded directly to reservoir exteriors is rendering obsolete separate pouch-based temperature management systems that add bulk and snag hazards during vehicle egress. U.S. Army airborne units field-tested these integrated systems during Joint Readiness Training Center rotations in 2024, with feedback compressing procurement specifications toward single-unit solutions that eliminate detachable components. The structural consequence is collapsing the addressable market for standalone insulating accessories and forcing pouch manufacturers toward reservoir subsystem partnerships.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents are accelerating European manufacturer migration toward water-blown TPU foaming processes. This industrial consequence elevates capital requirements for reservoir production lines while filtering out smaller molders lacking process engineering capabilities. German and French defense procurement offices now specify HFC-free construction in tender documents, with Bundeswehr technical acceptance criteria updated to validate alternative blowing agent compatibility with chemical resistance standards.
Unit-level bulk purchasing through defense e-commerce platforms is fragmenting traditional prime-vendor relationships that consolidated hydration procurement at division or corps level. U.S. Marine Corps Systems Command pilot programs allow company-grade officers to direct-order mission-configured hydration kits through GSA Advantage channels, bypassing multi-year indefinite-delivery contracts. This pattern concentrates most visibly in special operations support elements where mission profiles vary weekly and standardized issue fails operational requirements.
Military Hydration Products Market Segmentation
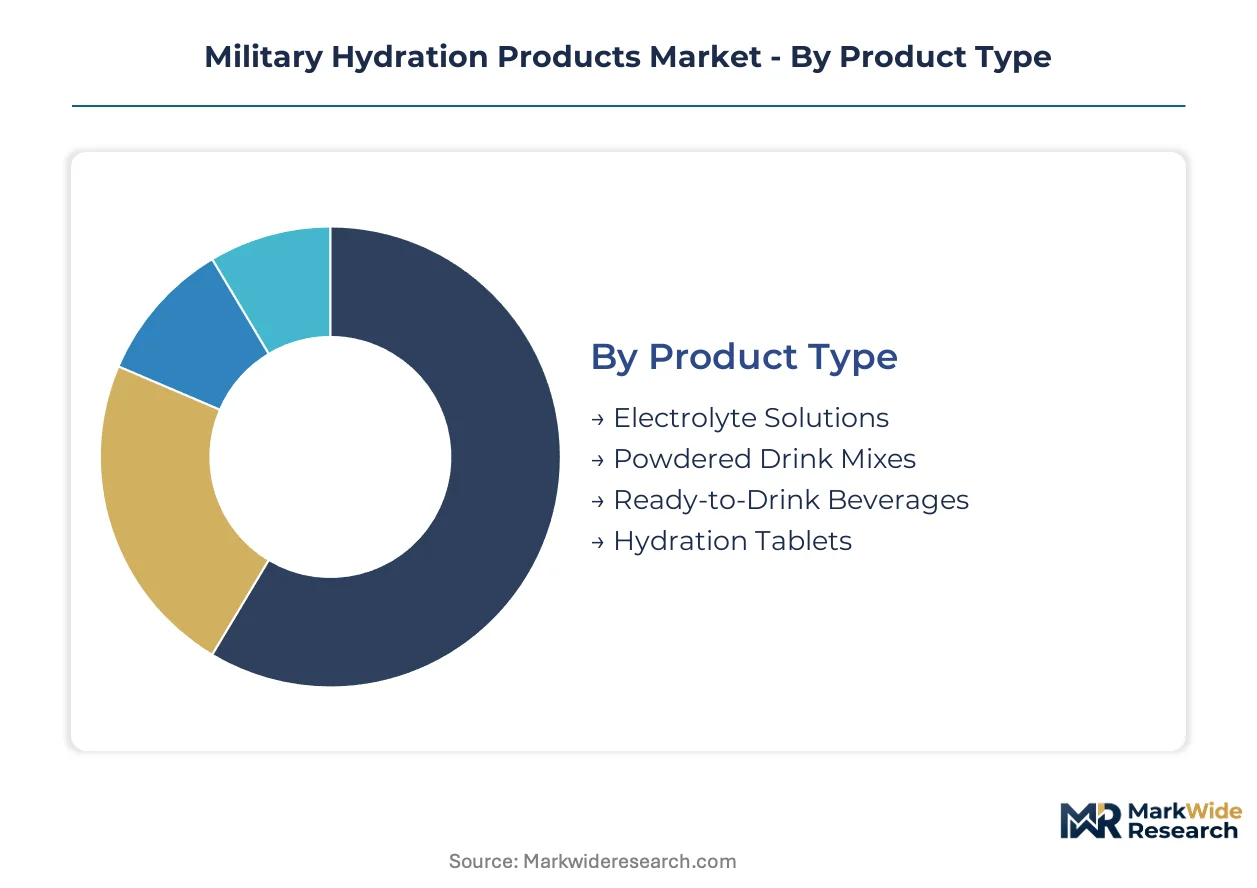
Military hydration procurement splits across consumable formulations, durable equipment, and delivery infrastructure. Each segment carries distinct certification requirements, margin profiles, and contract renewal cycles that reshape supplier economics.
Product Type:
Combat hydration spans immediate consumption liquids, concentrated additives, and solid-state alternatives optimized for load-bearing constraints.
- Ready-to-Drink Beverages:Pre-mixed isotonic solutions in flexible packaging dominate forward deployment logistics. Bundeswehr expeditionary units in Germany drive recurring tender volumes for shelf-stable formulations that bypass field mixing protocols.
- Hydration Tablets:Compressed electrolyte discs dissolve in ambient water sources, cutting transport weight by 90% versus liquid equivalents. Special forces units across NATO rapid response elements prioritize these for airborne insertion missions where every kilogram determines operational range.
- Electrolyte Solutions:Concentrated liquid concentrates requiring dilution serve mechanized infantry with reliable vehicle-borne water supplies.
- Powdered Drink Mixes:Bulk canisters support garrison and training facility provisioning where weight constraints relax.
Established volume favors ready-to-drink beverages; emerging adoption favors hydration tablets.
End User:
Customer archetypes range from mass-issue conventional forces to precision-equipped elite units with bespoke technical requirements.
- Active Military Personnel:General-issue soldiers require standardized hydration systems compatible with existing load-bearing equipment. U.S. Army Natick Soldier Systems Center protocols govern antimicrobial specifications and bite-valve flow rates for this segment.
- Special Forces:Elite operators demand modular systems integrating filtration, insulation, and biometric monitoring. Israeli Defense Forces relationships anchor specialized procurement channels with accelerated development cycles.
- Training Facilities:Fixed installations prioritize durability and cost efficiency over packability, sustaining demand for legacy canteen formats.
- Defense Contractors:Private security and logistics personnel operate under commercial procurement rules without Berry Amendment sourcing constraints.
Contract concentration sits with active military personnel; technology premium concentrates with special forces.
Packaging Type:
Containment formats balance disposability against reuse cycles across operational contexts.
- Pouches:Flexible thermoplastic polyurethane bladders with integrated bite valves dominate dismounted operations. REACH antimicrobial mandates from ECHA are forcing silver-ion coating upgrades across European procurement.
- Sachets:Single-serve powder and tablet packaging eliminates contamination risk in austere environments. Forward operating base water security gaps drive demand for individually sealed electrolyte doses.
- Canteens:Rigid aluminum and polymer containers persist in training and mechanized contexts where vehicle stowage accommodates bulk.
- Boxes:Bulk corrugated packaging serves unit-level resupply rather than individual carriage.
Operational flexibility favors pouches; contamination control favors sachets.
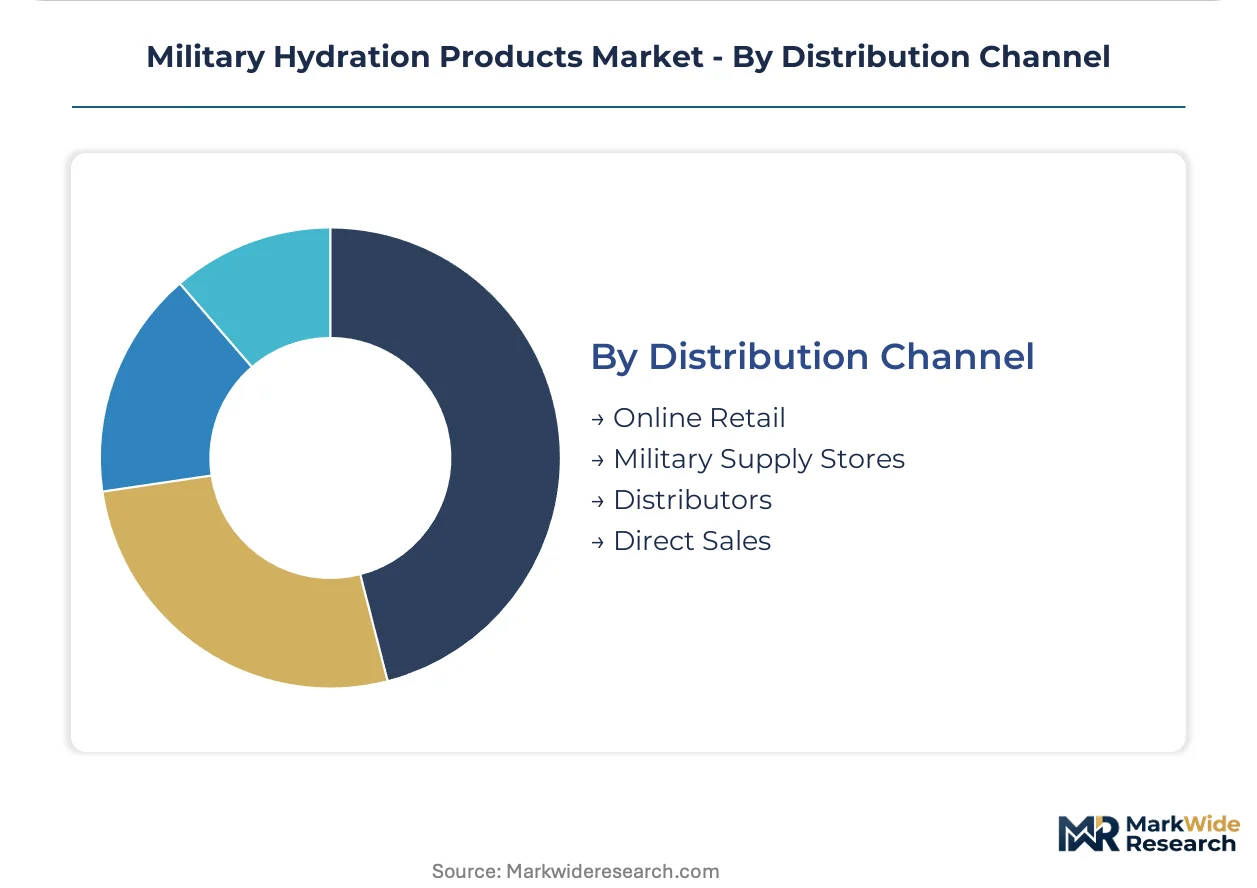
Distribution Channel:
Procurement pathways split between centralized defense logistics and decentralized unit purchasing.
- Direct Sales:Prime contractors negotiate multi-year indefinite-delivery contracts with national defense ministries. CamelBak Products LLC leverages vertical integration in reservoir molding to sustain cost advantages on these large awards.
- Distributors:Authorized military equipment resellers aggregate smaller orders from reserve and national guard formations.
- Military Supply Stores:Base exchange and post exchange retail channels serve individual replacement purchases and personal equipment upgrades.
- Online Retail:GSA Advantage and equivalent government e-commerce platforms fragment traditional prime-vendor relationships, allowing company-grade officers to direct-order mission-configured kits.
Contract value concentrates in direct sales; transaction velocity is climbing fastest through online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in military hydration equipment tilt toward net-import dependence across most NATO members, with specialized reservoir molding capacity concentrating in Germany and the United States while consumable electrolyte formulations flow from domestic pharmaceutical contractors.
United States
Natick Soldier Systems Center protocols drive procurement specifications for antimicrobial TPU reservoirs and bite-valve flow rates exceeding one liter per minute. Berry Amendment domestic sourcing requirements restrict reservoir and valve procurement to qualifying country suppliers, excluding lower-cost Asian molding capacity from defense contracts. Boston-area defense contractors cluster around Massachusetts procurement corridors, supplying precision-dosed electrolyte formulations to expeditionary units.
Germany
Bundeswehr modernization programs prioritize lightweight tactical hydration gear for expeditionary forces, generating sustained tender volumes for packable bladder systems. EU F-Gas Regulation phase-down schedules for hydrofluorocarbon blowing agents force reservoir manufacturers toward water-blown TPU foaming processes validated against chemical resistance standards. Bavaria-based molding operations anchor European production capacity for defense-qualified thermoplastic polyurethane components.
Israel
Israeli Defense Forces relationships anchor specialized procurement channels with accelerated development cycles for modular battlefield hydration protocols. National security-driven sourcing mandates prioritize domestic reservoir fabrication and electrolyte formulation capabilities. Tel Aviv-area defense technology clusters integrate hydration system design with broader individual soldier equipment modernization programs.
India
Mountain Strike Corps and Marine Commando modernization programs generate underpenetrated demand for high-altitude and amphibious hydration systems optimized for Himalayan and maritime operating environments. Defence Procurement Procedure indigenization requirements progressively restrict foreign original equipment manufacturer participation in reservoir supply. Mumbai-Pune industrial corridors host emerging domestic molding capacity seeking defense qualification status.
United Kingdom
Army Expeditionary Forces procurement prioritizes interoperability with NATO standardization agreements for individual equipment, including antimicrobial compliance and provenance documentation. Ministry of Defence equipment pooling mechanisms shift capital expenditure patterns toward operational leasing arrangements. Midlands-based defense suppliers concentrate on subsystem integration for vehicle-mounted hydration distribution in mechanized infantry applications.
Military Hydration Products Market Competitive Environment
On the supply side, the industry is bifurcated between vertically integrated reservoir manufacturers and specialized contract molders serving multiple uniformed services. Three archetypes dominate: defense-dedicated prime contractors with in-house polymer processing, commercial outdoor brands with defense-qualified product lines, and pure-play contract manufacturers supplying bladder technology without end-brand overhead. Competitive positioning hinges on Berry Amendment compliance documentation and accelerated antimicrobial testing protocols as procurement timelines compress from eighteen months to under nine months.
Within the prime contractor tier, CamelBak Products LLC and Source Tactical Gear exemplify divergent strategic postures. CamelBak leverages captive reservoir molding capacity to sustain cost advantages on large defense awards. Source Tactical Gear anchors its market position through specialized relationships with Israeli Defense Forces and accelerated development protocols for elite unit requirements. Hydrapak LLC occupies the contract manufacturing archetype, supplying bladder technology to multiple uniformed services while avoiding end-brand overhead investments.
| Leading Market Players |
|---|
| Geigerrig |
| Cera Products Inc |
| CamelBak Products LLC |
| Osprey |
| Hoist |
| Source Tactical Gear |
| Platypus |
| Lupu Tactical |
| Hydrapak LLC |
| Others |
Value Chain & Pricing Dynamics
German and U.S. reservoir molding capacity anchors upstream supply for antimicrobial thermoplastic polyurethane bladders, concentrating margin capture with defense-qualified manufacturers while fixed-price contracts compress downstream profitability for consumable electrolyte formulators lacking captive polymer processing.
Pricing Analysis
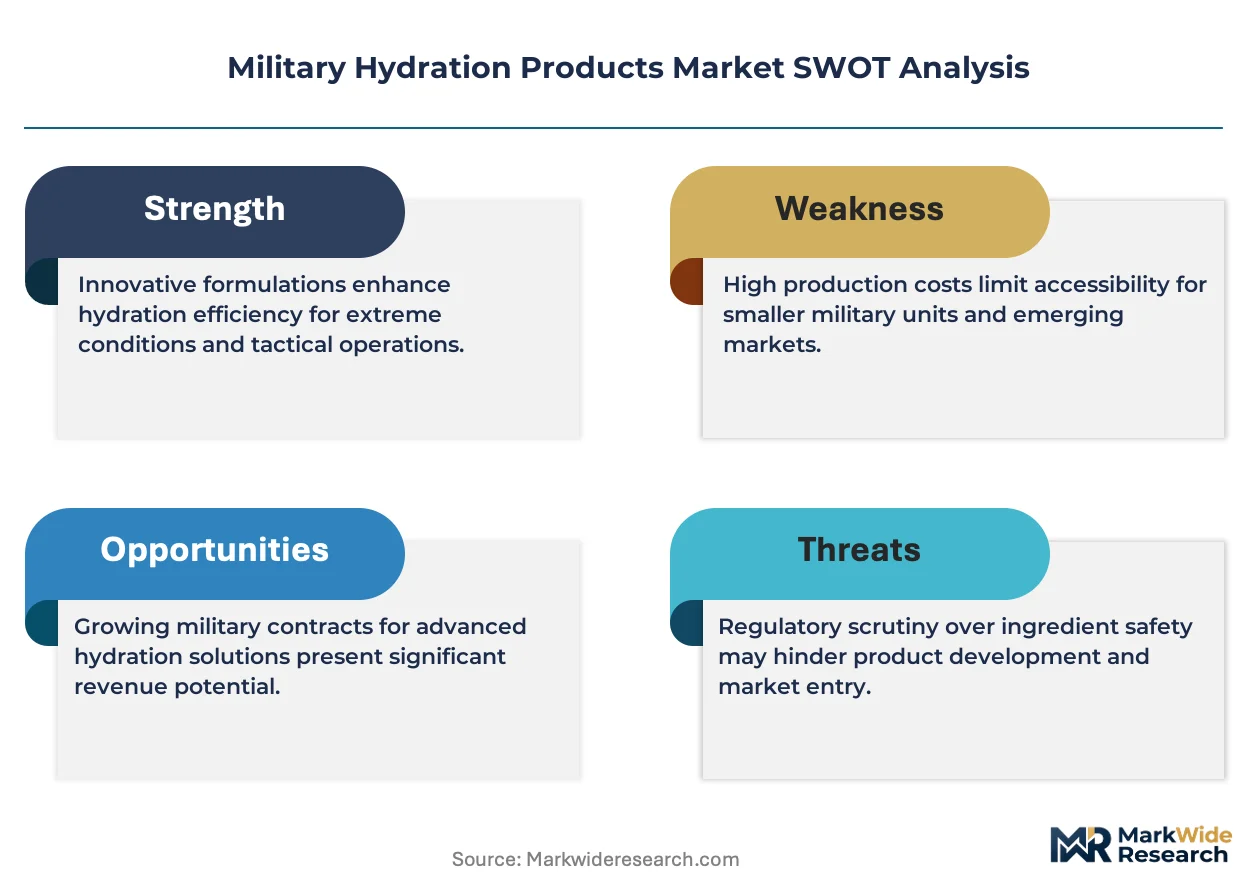
Defense procurement officers anchor contract-based long-term offtake pricing for reservoir systems, with three-tier pricing structure across premium, standard, and economy levels differentiated by Natick certification status and Berry Amendment compliance documentation. Price differentiation stems from antimicrobial testing acceleration fees and vertical integration in bite-valve molding. Pricing pressure intensifies from medical-grade TPU resin cost volatility tied to automotive sector demand swings. Training facility buyers exhibit highest price sensitivity due to canteen legacy infrastructure, while special forces units prioritize performance over unit economics.
Supply Chain Analysis
ITAR and EAR export-control regimes restrict hollow-fiber membrane filtration technology flows to non-qualifying countries, forcing defense contractors toward domestic or NATO-allied subsystem sourcing. Supply concentrates in Germany, the United States, and Israel for reservoir fabrication, while pharmaceutical-grade electrolyte concentrates draw from domestic formulation contractors. Raw material dependencies center on medical-grade TPU resin, silver-ion antimicrobial coatings, and precision-molded silicone bite valves. Single-source vulnerability persists in specialized membrane filtration elements. Distribution runs through prime-vendor indefinite-delivery contracts and fragmenting GSA Advantage e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military hydration procurement is shifting toward platform-economics logic as NATO equipment pooling mechanisms and integrated reservoir-power-biometric systems collapse standalone accessory markets into subsystem partnerships.
For Market Incumbents: Entrench defense-contract positioning by accelerating antimicrobial testing protocols ahead of compressed nine-month vendor qualification timelines, and deepen backward integration into water-blown TPU foaming capacity to capture EU F-Gas Regulation compliance premiums. Threats include filtration-convergence startups and REACH-mandated coating upgrade cycles that obsolete legacy biocide inventory.
For New Entrants and Emerging Players: Establish a beachhead in Indian Mountain Strike Corps and Marine Commando procurement channels where Defence Procurement Procedure indigenization requirements are creating qualification windows for domestic molding capacity. White-space targets include high-altitude insulated reservoir systems and amphibious corrosion-resistant bite-valve assemblies. Go-to-market through joint ventures with Mumbai-Pune industrial corridor fabricators seeking defense certification status.
For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturers with asset-light service infrastructure capable of supporting NATO operational leasing arrangements, rather than prime contractors exposed to fixed-price margin compression. Long-term viability favors suppliers with dual-use commercial-outdoor and defense-qualified product lines. Watch for Indian domestic content threshold escalations as inflection signals for regional production footprint requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Filtration-Convergence Product Development | Integration of hollow-fiber membranes into reservoir bite-valves addresses forward-operating-base water security gaps identified by U.S. Army Natick protocols. |
| Water-Blown TPU Foaming Capacity Expansion | EU F-Gas Regulation phase-down mandates HFC-free reservoir construction, elevating capital barriers for Bundeswehr contract eligibility. |
| Antimicrobial Testing Acceleration Investment | Compressed vendor qualification timelines from eighteen to nine months reward manufacturers with pre-positioned Natick certification documentation. |
| Indian Domestic Joint Venture Formation | Defence Procurement Procedure indigenization thresholds create partnership requirements for foreign OEMs targeting Mountain Strike Corps modernization. |
| Government Leasing Service Infrastructure | NATO equipment pooling mechanisms shift procurement from unit purchase to operational lease, favoring asset-light contract manufacturers over capital-intensive primes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of defense procurement databases, regulatory filings from ECHA and the U.S. Army Natick Soldier Systems Center, and trade flow records for thermoplastic polyurethane resins. Primary interviews engaged defense procurement officers at NATO member ministries, reservoir molding plant managers in Bavaria and Massachusetts, electrolyte formulation R&D directors, and special forces equipment specialists. Secondary sources included Bundeswehr tender documentation, Berry Amendment compliance registries, and customs data for medical-grade polymer imports. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Forecast inputs encompassed product type segmentation across ready-to-drink beverages, hydration tablets, and electrolyte solutions; end-user archetypes spanning active military personnel, special forces, and training facilities; and packaging formats including pouches, sachets, and canteens across the analysis window. CAGRs derived from modeled procurement cycle renewal rates and modernization program budget trajectories. Industry-specific inputs included REACH antimicrobial mandate implementation schedules and Indian Defence Procurement Procedure indigenization phase-ins.
Stress conditions across TPU resin price volatility bands, compressed vendor qualification timeline scenarios, and Indian domestic content threshold escalations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO expeditionary force deployment schedules and EU F-Gas Regulation phase-down adherence. Material shifts in U.S. Berry Amendment qualifying country designations or Indian indigenization enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
Personal Hygiene Market
Personal Grooming Products
Insect Repellent Wipes Market
Personal Grooming Products
Infant Mosquito Repellent Market
Personal Grooming Products
Global Tampons Market
Personal Grooming Products
Biometric Vaporizer Market
Personal Grooming Products
Hair Scissors Market
Personal Grooming Products
Charcoal Bristle Toothbrush Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Toothbrush Market
Personal Grooming Products
Cotton Pads Market
Personal Grooming Products
Self-Tanning Products Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Insoles Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Shaving Market
Personal Grooming Products
India Sexual Wellness Market