
 Percussion Instruments Market | 2026-2036
Percussion Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Percussion Instruments Market Intelligence
China is reshaping percussion instrument manufacturing through expanded drum kit and cymbal foundry capacity in Guangdong and Zhejiang provinces. Yamaha Corporation leverages vertical integration across timber sourcing, shell formation, and electronic trigger systems to control cost structures. Pearl Musical Instrument Co. anchors its competitive position through proprietary Superior Shell Technology and dominant share in marching percussion. Roland Corporation differentiates through hybrid acoustic-electronic drum platforms that merge physical playing response with digital sound libraries.
Percussion instruments encompass struck idiophones and membranophones producing rhythmic and tonal patterns through direct mechanical impact, with shell construction typically employing maple, birch, or mahogany laminates in 6-10 ply configurations tuned via tension rods and lugs. Drum kits command the largest product type revenue pool due to institutional band requirements and live performance infrastructure, while cajóns represent the fastest-expanding segment driven by acoustic portability and flamenco-crossover adoption. Wood materials sustain premium positioning in orchestral and jazz applications where resonance characteristics determine tonal quality, whereas composite shells are displacing traditional options in touring contexts requiring climate stability.
The United States Consumer Product Safety Commission governs lead content in surface coatings under CPSIA standards, while the European Union REACH regulation restricts hazardous substances in drum finishes and adhesives, compelling reformulation across supply chains. Japan's Ministry of Economy, Trade and Industry (METI) oversees JIS standards for electronic percussion electromagnetic compatibility. Stakeholders must monitor evolving material compliance thresholds and electronic integration standards as hybrid instruments blur traditional regulatory boundaries.
Market Dynamics
The percussion instruments market is undergoing structural recalibration as hybrid acoustic-electronic platforms compress replacement cycles and force manufacturers to reconcile traditional craftsmanship with digital integration requirements.
Growth Catalysts
- Marching band infrastructure expansion:Texas and California K-12 systems are enlarging instrument procurement budgets for competitive ensemble programs, driving institutional drum kit and auxiliary percussion orders.
- REACH compliance reformulation:The European Union's chemical substance restrictions are compelling manufacturers to develop water-based finishes and bio-adhesives that open premium positioning in environmentally regulated markets.
- Flamenco-crossover acoustic portability:Cajón adoption in unplugged performance venues and street music circuits is accelerating replacement demand for compact, transportable rhythm instruments.
Market Restraints
- Timber input cost volatility:Maple and birch shell laminates face price instability due to North American hardwood harvesting constraints and kiln-drying energy costs.
- Foundry concentration risk:Cymbal and bronze alloy production clusters in Guangdong and Zhejiang provinces create single-geography dependency for critical metal components.
- Electronic substitution pressure:Digital audio workstations and sample-based production tools are compressing demand for acoustic recording hardware among home studio operators.
Strategic Opportunities
- Underpenetrated music therapy vertical:Clinical rhythm intervention programs in German and Japanese healthcare systems are generating institutional procurement channels outside traditional education markets.
- Climate-stable composite shell innovation:Touring musicians in humid subtropical zones are adopting fiberglass and carbon-fiber drum constructions that eliminate tonal drift across performance environments.
- Direct-to-consumer channel expansion:Configurator-based online ordering for custom shell configurations is bypassing traditional music retailer markups and capturing margin previously lost to distribution intermediaries.
Industry Challenges
- Electro-acoustic integration skill scarcity:Manufacturers struggle to recruit engineers proficient in both physical acoustics and digital signal processing for hybrid trigger system development.
- Multi-jurisdiction certification complexity:Electronic percussion platforms must simultaneously satisfy FCC electromagnetic emissions standards, METI JIS compatibility requirements, and CE marking directives before market entry.
- Legacy artisan succession gaps:Master shell craftsmen in Italian and Japanese traditional workshops lack trained apprentices to sustain hand-finished premium production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Percussion Instruments Market |
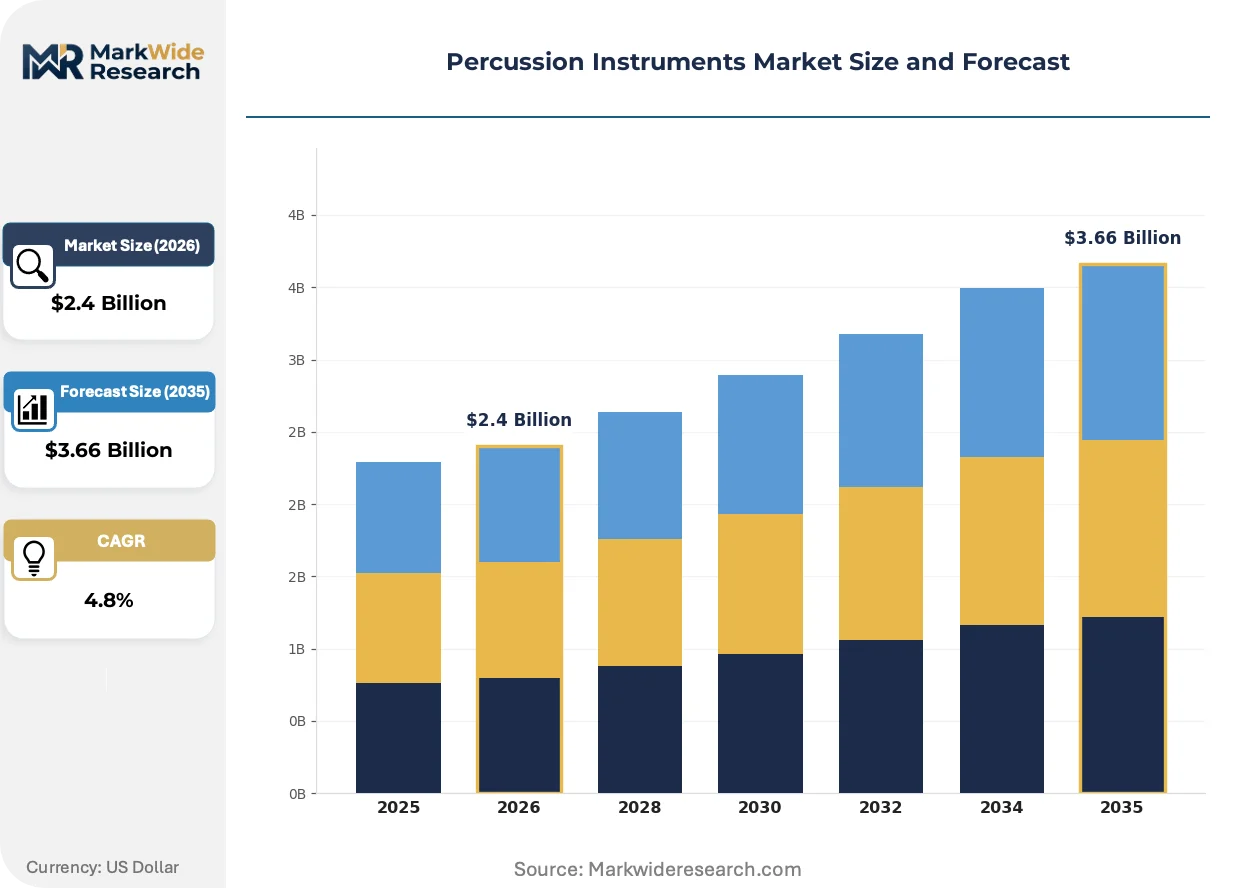
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Kits, Congas, Cajón, Tambourine Material: Wood, Metal, Plastic, Composite End User: Professional Musicians, Amateur Players, Schools, Studios Distribution Channel: Online Retailers, Specialty Stores, Music Shops, Wholesale Distributors |
| Companies Covered | Yamaha Corporation, Pearl Musical Instrument Co., Gretsch Drums, Ludwig Drums, Roland Corporation, Conn-Selmer, Inc., Remo Inc., Meinl Percussion, D'Addario & Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Percussion Instruments Market Strategic Shifts & Innovations
Digital-physical convergence is restructuring how percussion instruments are designed, regulated, and purchased, with implications stretching from foundry floors to end-user experience.
Hybrid acoustic-electronic drum platforms are merging physical playing response with expandable digital sound libraries. Recording studios and touring professionals are adopting these systems at accelerating pace to reduce microphone setup time and enable real-time tonal switching. This convergence is hybridizing product categories that previously operated as distinct market segments.
REACH substance restrictions are forcing reformulation of drum finishes, adhesives, and shell coatings across European supply chains. Manufacturers are substituting solvent-based lacquers with UV-cured and waterborne alternatives that alter curing timelines and capital equipment requirements. Orchestral and jazz segments with premium positioning are absorbing compliance costs fastest, while entry-level producers face margin compression from dual-formulation inventory requirements.
Institutional procurement is consolidating through cooperative purchasing agreements that aggregate K-12 and university band program orders. Traditional music retailers are losing volume to educational consortium contracts that negotiate direct manufacturer relationships and specification standardization. Texas and California district purchasing cooperatives are demonstrating this model most visibly, with implications for how product lines are configured and inventoried.
Percussion Instruments Market Segmentation
Replacement cycles vary dramatically across percussion instrument categories, with touring hardware demanding 3-5 year refresh schedules while educational inventory stretches to 10-15 years. Understanding these temporal patterns helps manufacturers align production capacity with predictable demand windows and margin profiles.
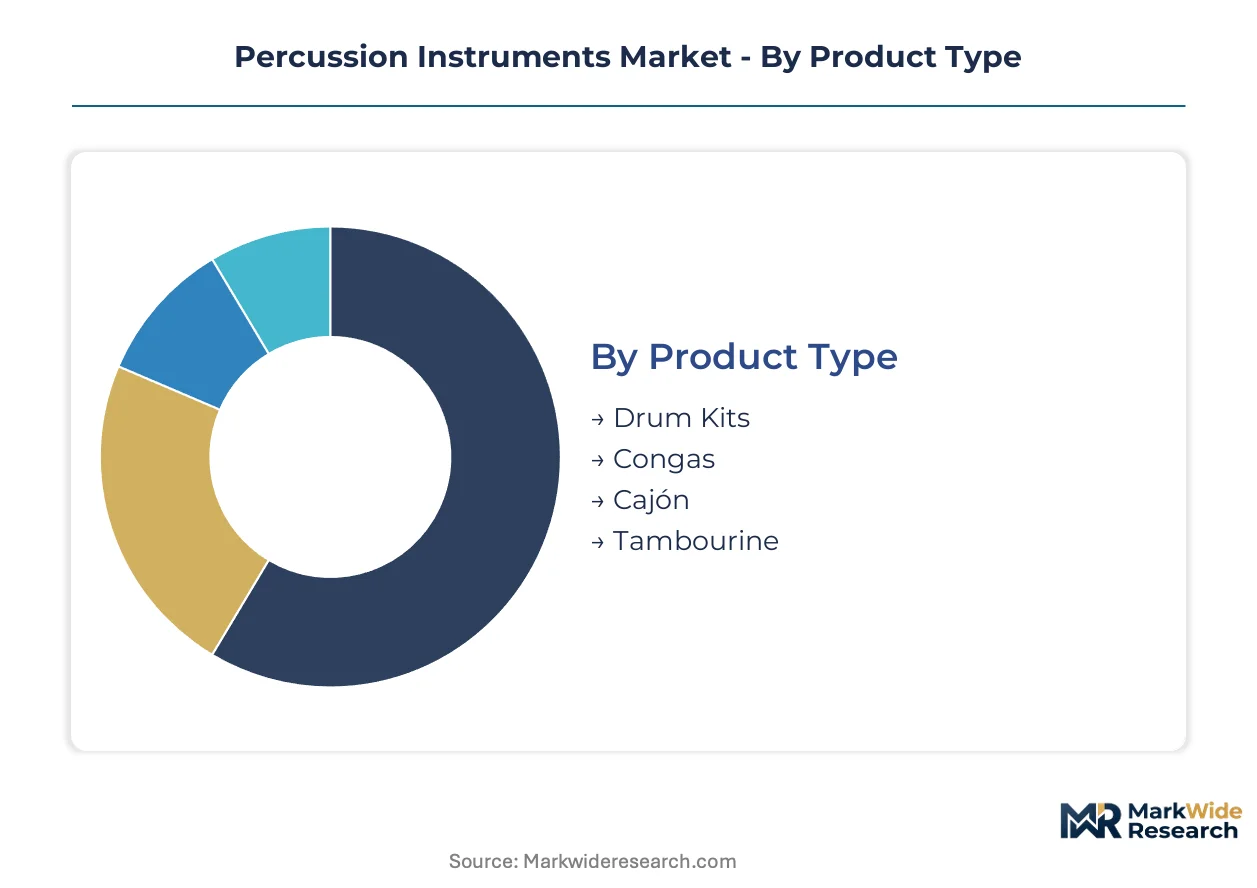
Product Type:
Drum kits turn over fastest in professional touring contexts, while handheld idiophones and auxiliary percussion exhibit extended replacement horizons in institutional settings.
- Drum Kits:Configurations of bass drums, snares, toms, and hardware dominate revenue pools through institutional band procurement and live performance infrastructure. Texas and California K-12 systems are enlarging competitive ensemble budgets, driving replacement orders for marching and concert configurations.
- Cajón:Box-shaped percussion instruments with internal snare wires deliver acoustic portability for unplugged venues and street music circuits. Flamenco-crossover adoption in Barcelona and Madrid performance spaces is accelerating compact rhythm instrument demand.
- Congas:Tall, narrow single-headed drums of Afro-Cuban origin serve Latin jazz and salsa ensembles with tunable natural skin or synthetic heads.
- Tambourine:Frame-mounted jingle instruments provide rhythmic accent in orchestral, pop, and worship applications with minimal maintenance requirements.
Drum kits dominate installed base. Cajón is where expansion concentrates.
Material:
Cost tier stratification separates premium tonewood selections from mass-market synthetic alternatives, with climate stability emerging as a decisive specification for touring professionals.
- Wood:Maple, birch, and mahogany laminates in 6-10 ply configurations sustain premium positioning in orchestral and jazz applications where resonance characteristics determine tonal quality. Japanese master craftsmen in Nagano prefecture maintain hand-finished production lines for select shell formations.
- Composite:Fiberglass and carbon-fiber constructions eliminate tonal drift across humid subtropical performance environments. Touring musicians in Miami and Singapore are adopting climate-stable shells that withstand rapid temperature transitions.
- Metal:Bronze, brass, and aluminum alloys form cymbal, bell, and accent percussion components through foundry casting and hammering processes.
- Plastic:ABS, acrylic, and polymer shells serve entry-level and educational markets with uniform manufacturing tolerances and reduced sensitivity to humidity fluctuations.
Wood commands margin premiums. Composite is climbing the fastest.
End User:
Volume concentration sits with institutional procurement channels, while margin extraction favors professional segments with customization requirements and rapid replacement cycles.
- Schools:K-12 and university band programs aggregate demand through cooperative purchasing agreements that negotiate direct manufacturer relationships. Texas and California district purchasing cooperatives are consolidating specification standardization.
- Professional Musicians:Touring artists and session players demand hybrid acoustic-electronic platforms with real-time tonal switching and reduced microphone setup time.
- Studios:Recording facilities prioritize microphone-friendly shell designs and versatile tuning ranges for diverse genre requirements.
- Amateur Players:Hobbyist segments price-optimize through online configurators and direct-to-consumer channels that bypass traditional retailer markups.
Schools anchor volume throughput. Professional musicians concentrate margin capture.
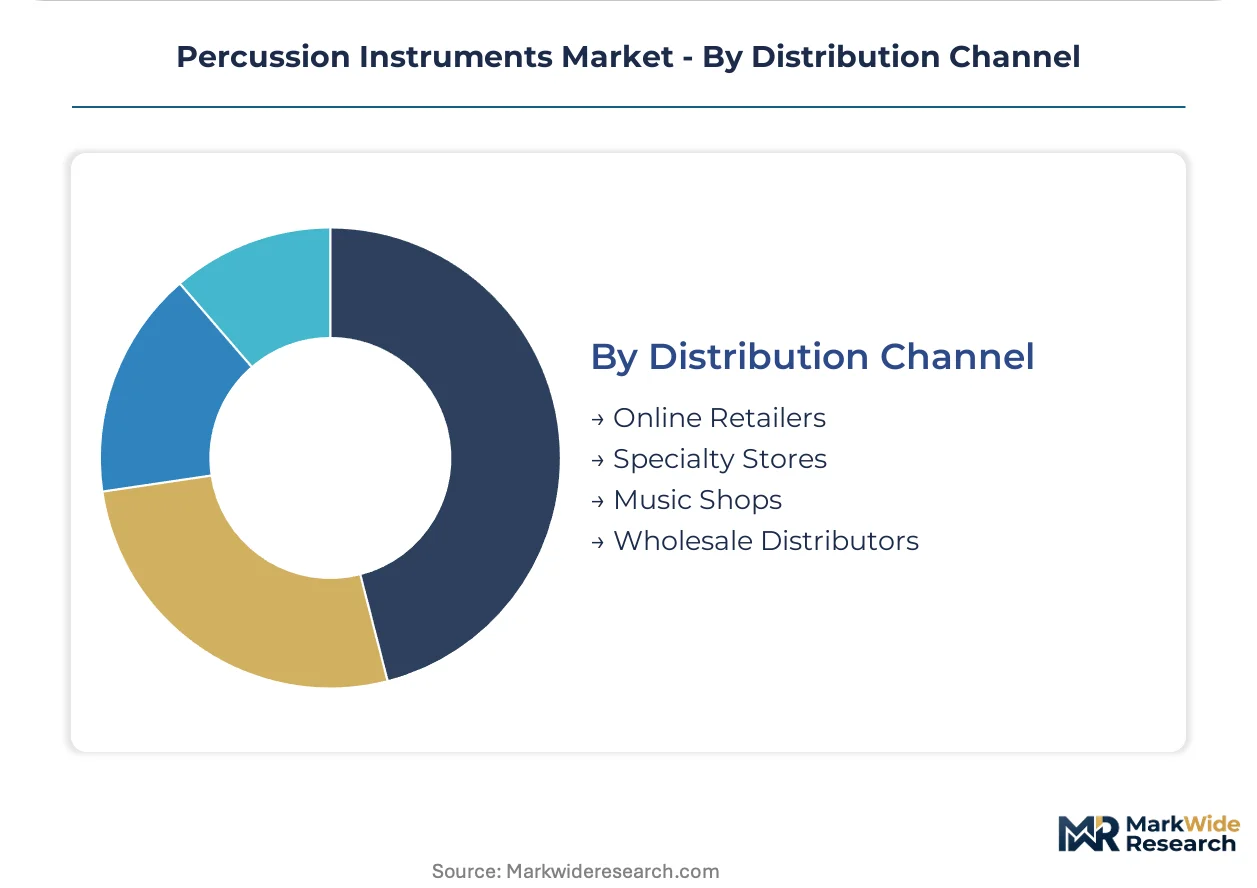
Distribution Channel:
Procurement patterns are shifting from brick-and-mortar intermediaries toward direct manufacturer relationships and digital configurators, redistributing margin across the value chain.
- Online Retailers:Configurator-based ordering for custom shell configurations captures margin previously lost to distribution intermediaries. Yamaha Corporation and Pearl Musical Instrument Co. are expanding direct-to-consumer platforms.
- Specialty Stores:Focused percussion retailers in Nashville, Los Angeles, and London provide hands-on evaluation for professional buyers seeking specific tonal characteristics.
- Music Shops:General instrument retailers face volume pressure from educational consortium contracts and manufacturer-direct channels.
- Wholesale Distributors:Bulk logistics providers serve institutional procurement with specification standardization and consolidated freight arrangements.
Online retailers are gaining share fastest. Specialty stores defend professional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong and Zhejiang provinces host concentrated cymbal foundry and drum kit assembly operations that feed international distribution networks. Timber sourcing for premium shell construction remains anchored in North American and Japanese hardwood regions. Regulatory fragmentation across REACH, CPSIA, and METI JIS standards is forcing manufacturers to maintain multiple formulation and certification tracks.
United States
Texas and California K-12 systems are enlarging competitive ensemble procurement budgets for marching band programs. The Consumer Product Safety Commission governs lead content in surface coatings under CPSIA standards. Nashville and Los Angeles recording studio density drives replacement cycles for hybrid acoustic-electronic platforms.
China
Guangdong and Zhejiang foundry clusters are expanding bronze alloy cymbal and hardware component capacity for export markets. The Ministry of Ecology and Environment enforces dual carbon goals affecting kiln-drying energy inputs. Shenzhen and Guangzhou assembly plants are integrating electronic trigger systems with traditional shell formations.
Japan
Nagano prefecture workshops sustain hand-finished premium shell production for orchestral and jazz segments. METI oversees JIS standards for electronic percussion electromagnetic compatibility. Hamamatsu-based manufacturers leverage vertical timber sourcing through captive supply arrangements.
Germany
Clinical rhythm intervention programs in German healthcare systems are generating institutional procurement outside traditional education channels. ECHA REACH restrictions compel water-based finish and bio-adhesive reformulation across European supply chains. Bavarian precision metalworking regions supply hardware components to drum kit assemblers.
United Kingdom
London and Manchester specialty retailers defend professional buyer relationships through hands-on tonal evaluation services. CE marking directives apply to electronic percussion platforms entering continental European markets. British educational consortium contracts are consolidating specification standardization for K-12 band programs.
Percussion Instruments Market Key Industry Players
Vertically integrated conglomerates and specialized artisan workshops split the market between scale-driven standardization and premium craftsmanship differentiation. The vendor base organizes around three strategic archetypes: timber-to-trigger conglomerates controlling captive supply chains, foundry-specialized metalworkers dominating cymbal and hardware segments, and hybrid-platform innovators merging physical acoustics with digital signal processing. Capacity expansion in Guangdong province and strategic partnerships between acoustic heritage brands and semiconductor firms represent the dominant competitive vectors reshaping positioning.
Within the timber-to-trigger conglomerate tier, Yamaha Corporation and Pearl Musical Instrument Co. occupy positions exemplifying backward integration from shell formation through electronic system assembly. Roland Corporation anchors the hybrid-platform innovation archetype, representing the convergence trajectory between physical playing response and expandable digital libraries. These three entities collectively illustrate how competitive advantage in this market depends on reconciling traditional acoustic craftsmanship with digital integration requirements.
| Leading Market Players |
|---|
| Yamaha Corporation |
| Pearl Musical Instrument Co. |
| Gretsch Drums |
| Ludwig Drums |
| Roland Corporation |
| Conn-Selmer, Inc. |
| Remo Inc. |
| Meinl Percussion |
| D'Addario & Company, Inc. |
| Others |
Cost & Logistics Intelligence
Guangdong and Zhejiang foundry clusters for bronze alloy cymbals and hardware components concentrate upstream bargaining power, feeding margin pools downstream toward manufacturers with captive timber sourcing and in-house electronic trigger assembly. REACH compliance costs and kiln-drying energy inputs are reshaping where value capture concentrates across shell formation, metal casting, and digital integration tiers.
Pricing Analysis
REACH dictates the pricing tier structure across European markets, compelling water-based finish and bio-adhesive reformulation that separates premium hand-finished orchestral lines from standard institutional configurations. Price differentiation rests on certification grade and customization level, with Japanese Nagano workshop production commanding brand premiums. Cost compression in entry-level tiers is intensifying because dual-formulation inventory requirements strain margin structures. Schools exhibit highest price sensitivity through cooperative purchasing agreements, while touring professionals absorb premiums for climate-stable composite shells.
Supply Chain Analysis
Pearl Musical Instrument Co. and Yamaha Corporation anchor contract-manufacturing capacity through vertically integrated shell formation and electronic assembly operations. Geographic supply concentration centers on China for foundry outputs, Japan for premium timber sourcing, and the United States for institutional procurement aggregation. Raw material dependencies draw from North American maple and birch hardwoods, Guangdong bronze alloys, and Shenzhen semiconductor components for trigger systems. Single-geography vulnerability in Zhejiang cymbal production creates concentrated disruption exposure. Distribution runs through educational consortium contracts and direct-to-consumer configurators that bypass traditional retailer markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital audio workstations and sample-based production tools pose acute substitution threats to acoustic hardware demand among home studio operators, forcing incumbents to defend installed base through hybrid platform migration and service bundling.
For Market Incumbents: Insulate core revenue streams by accelerating hybrid acoustic-electronic platform development that merges physical playing response with expandable digital libraries, countering pure software substitution. Deepen backward integration into captive timber sourcing and electronic trigger manufacturing to control cost structures against commodity volatility. Prioritize certification investment for REACH-compliant finishes that lock in European institutional procurement channels. For New Entrants and Emerging Players: Music therapy verticals in German and Japanese healthcare systems represent the most penetrable entry point, with clinical rhythm intervention programs generating institutional procurement outside saturated education markets. Climate-stable composite shell innovation for humid subtropical touring circuits offers differentiated positioning against established tonewood heritage brands. Direct-to-consumer configurator platforms provide the optimal go-to-market angle, capturing margin previously lost to distribution intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed foundry operators in Guangdong province that lack electronic integration capabilities but hold critical bronze alloy casting capacity. Long-term viability hinges on hybrid platform convergence trajectories over the mid-cycle horizon. Target acquisition archetypes include precision metalworkers with hardware component expertise and semiconductor firms with signal processing IP. Monitor cajón segment expansion rates and flamenco-crossover adoption curves as early inflection indicators for acoustic portability demand shifts. Quarterly review of educational procurement budget allocations and REACH compliance cost pass-through rates is advised to detect margin compression signals.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Development | Merges physical acoustics with Roland Corporation-style digital libraries to compress replacement cycles. |
| REACH Compliance Reformulation | Substitutes solvent-based lacquers with waterborne alternatives that alter curing capital equipment requirements. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional music retailer markups through configurator-based custom shell ordering platforms. |
| Climate-Stable Composite Innovation | Adopts fiberglass and carbon-fiber constructions for Miami and Singapore touring environments. |
| Music Therapy Vertical Penetration | Accesses German and Japanese healthcare procurement channels outside traditional education markets. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with instrument manufacturers, educational procurement officers, touring musicians, and specialty retailer buyers; and secondary validation through customs trade records, SEC filings from listed instrument conglomerates, METI JIS standard documentation, and ECHA REACH substance restriction databases. Bottom-up triangulation aggregated shipment data by product configuration and material grade, while top-down verification cross-checked against aggregate market value estimates derived from institutional budget disclosures and foundry capacity reports.
Forecast inputs considered marching band infrastructure expansion rates, flamenco-crossover adoption curves, and electronic substitution pressure indices across the projection horizon. Segmentation modeling incorporated product type, material composition, end-user archetype, and distribution channel dimensions. CAGRs were derived from replacement cycle analysis by segment, with drum kit refresh schedules for touring professionals modeled separately from educational inventory horizons. Hybrid platform penetration rates and REACH compliance cost pass-through assumptions shaped trajectory boundaries.
Practitioners should monitor timber input cost volatility, foundry concentration disruptions, and electronic integration skill scarcity for early signals of forecast deviation. Quarterly review of educational procurement budget allocations, hybrid platform adoption rates, and REACH substance threshold revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Personal Hygiene Market
Consumer Goods
Mixing Console Market
Consumer Goods
Wooden Toys Market
Consumer Goods
Beeswax for Cosmetics Market
Consumer Goods
Smart Home Connect Dishwasher Market
Consumer Goods
Global Cosmetic Shea Butter Market
Consumer Goods
Cannabidiol CBD Pet Market
Consumer Goods
US Smoking Pipe Market
Consumer Goods
Makeup Setting Spray Market
Consumer Goods
Smart Connected Washing Machine Market
Consumer Goods
Mexico Camping Equipment Market
Consumer Goods
UK Pet Diet Market
Consumer Goods
Dog Boot for Winters Market
Consumer Goods
UK Pet Grooming Market
Consumer Goods
Travel Accessories Market
Consumer Goods
Sports Inspired Clothing Market