
 Global Audio Devices and Components Market | 2026-2036
Global Audio Devices and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audio Devices and Components Market Foresight
Platform licensing revenue is reconfiguring margin distribution across the audio value chain as Dolby Atmos and AptX codec ecosystems extract recurring fees from hardware manufacturers. Harman International leverages its automotive and consumer verticals to sustain integrated system dominance across multiple price tiers. d&b audiotechnik anchors premium live-sound installations through German-engineered point-source and line-array systems. QSC competes in networked audio by controlling DSP-enabled amplification platforms for installed commercial sound.
Global audio devices and components encompass transducers, signal processors, and amplification modules engineered to reproduce, capture, or manipulate sound across frequencies typically spanning 20 Hz to 20 kHz, with professional-grade systems extending beyond this range for monitoring accuracy. These products serve commercial purposes from immersive entertainment reproduction to calibrated acoustic measurement in broadcast and recording environments. Headphones and wireless speakers capture the largest consumer volume pools, while professional audio and sound reinforcement segments retain higher per-unit margins due to durability specifications and certification requirements. DACs and audio interfaces represent the fastest-growing structural category as remote production workflows and high-resolution streaming drive interface complexity upward.
The FCC governs wireless spectrum allocation for Bluetooth and Wi-Fi audio transmission in the United States, directly constraining chipset design and antenna configurations for manufacturers targeting North American distribution. Ecodesign requirements under the EU Green Deal and REACH substance restrictions compel material substitutions in driver magnets and enclosure finishes for European market access. China's MIIT enforces GB standards for electromagnetic compatibility that shape local production protocols. Stakeholders must monitor evolving interoperability mandates and substance-limit schedules to preserve cross-border product eligibility without redundant certification cycles.
Market Dynamics
Auracast broadcast audio and Bluetooth Low Energy standards are compressing proprietary wireless protocols while China's MIIT electromagnetic compatibility mandates reshape manufacturing protocols for export-bound production.
Growth Catalysts
- Auracast deployment:Public venues in Germany, the United Kingdom, and Japan are retrofitting assistive listening systems with broadcast audio receivers, expanding installed-base refresh cycles beyond consumer replacement rates.
- EU Ecodesign mandates:Repairability scoring and spare-part availability requirements under the Green Deal are extending product lifespans in professional audio, favoring modular amplifier and driver architectures.
- Content creator infrastructure:Podcast studios and streaming setups are driving interface and microphone sales as independent production displaces traditional broadcast facility dependency.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings and Chinese export licensing for driver magnets compress margin predictability for transducer manufacturers.
- Codec licensing stacking:Dolby Atmos, AptX Adaptive, and LC3plus royalty obligations accumulate per-device, raising effective cost floors for mid-tier wireless headphone producers.
- Substrate concentration:PCB and semiconductor packaging capacity in Taiwan and South Korea constrains amplifier module output during demand spikes.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting component assembly and acoustic testing facilities to Tamil Nadu and Karnataka clusters.
- Hearing health convergence:OTC hearing aid regulations by the FDA in the United States are collapsing the boundary between consumer earbuds and medical-grade amplification, opening retail pharmacy channels.
- Spatial audio in automotive:Cabin-specific head-tracking and seat-localized sound zones represent uncontracted white space as electric vehicle platforms prioritize interior differentiation.
Industry Challenges
- Auracast certification backlog:Bluetooth SIG qualification queues for broadcast audio implementations are delaying product launches by four to six months for tier-two manufacturers.
- Legacy DSP integration:Dante, AVB, and proprietary networked audio protocols require bridging hardware that complicates installed-base upgrades in commercial sound environments.
- Acoustic engineering scarcity:Transducer design and anechoic chamber testing expertise concentrates in Denmark, Germany, and Japan, constraining R&D scaling for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audio Devices and Components Market |
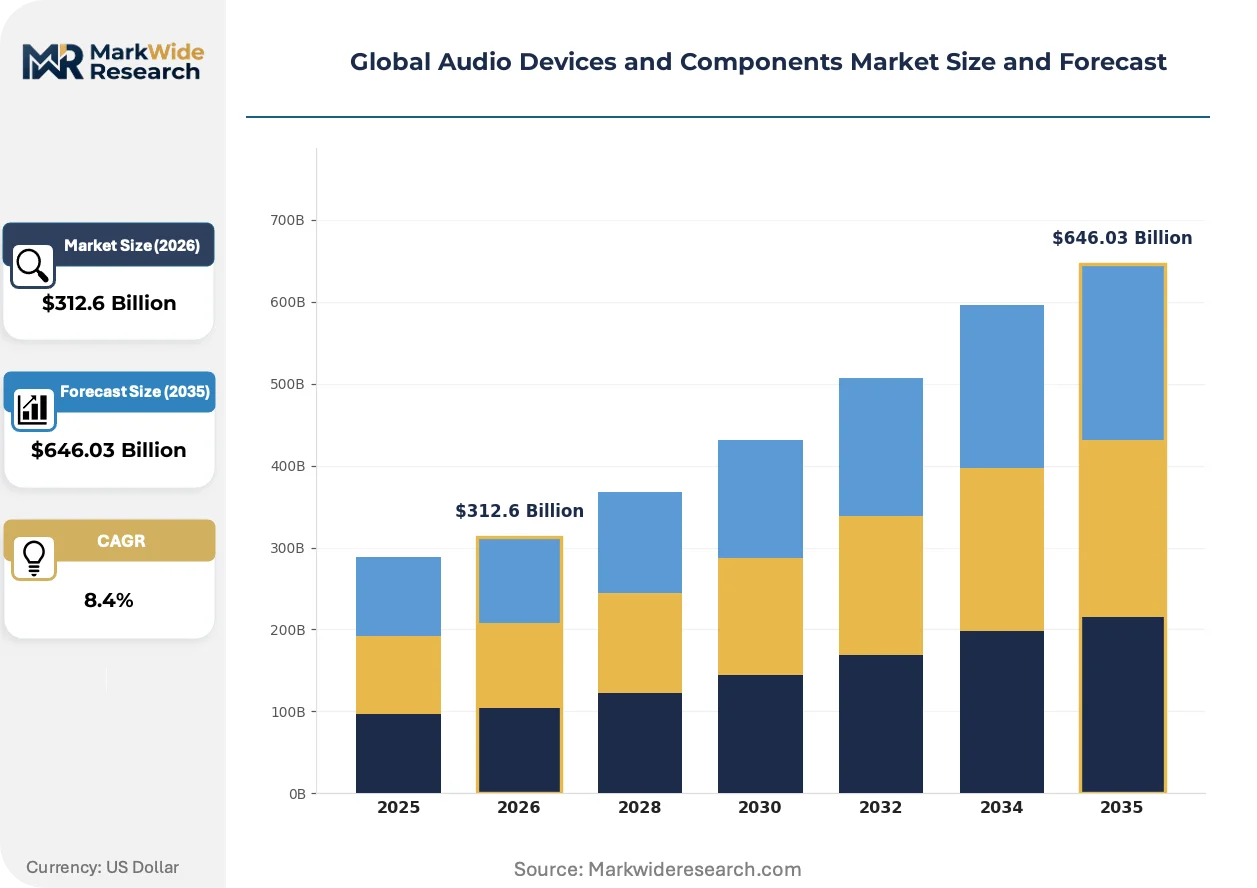
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headphones, Microphones, Speakers, Amplifiers, Audio Interfaces, DACs Technology: Bluetooth, Wired, Noise Cancellation, Voice Recognition, Dolby Atmos, AptX Application: Consumer Electronics, Professional Audio, Gaming, Virtual Reality, Broadcast, Sound Reinforcement End User: Recording Studios, Radio Stations, Post-Production Houses, Event Organizers, Content Creators, Educational Institutes |
| Companies Covered | L-Acoustics, d&b audiotechnik, Harman International, Klipsch, KEF, JBL, Meyer Sound, QSC, Bose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audio Devices and Components Market Shifts & Advancements
Wireless protocol unification and computational audio processing are collapsing hardware differentiation while regulatory repairability mandates force industrial-design reinvention across price tiers.
MEMS-based solid-state drivers are rendering obsolete traditional balanced-armature architectures in in-ear monitors. Audiophile and stage-monitor buyers in South Korea and the United States are adopting the technology within eighteen-month replacement cycles. The shift is compressing driver supplier margins as semiconductor fabrication economics displace precision mechanical assembly.
REACH substance restrictions and RoHS recast directives in Europe are banning specific phthalates in cable sheathing and beryllium in driver domes. Manufacturers serving EU distribution must validate alternative copper alloys and bio-based polymers through ECHA notification. Professional monitor and touring loudspeaker segments face the steepest reformulation timelines due to durability certification requirements.
Creator economy procurement now favors direct-to-manufacturer configuration tools over distributor-specified bundles. Microphone and interface buyers in Brazil, Mexico, and Indonesia are building signal chains through brand-owned web portals with thirty-day fulfillment guarantees. This pattern is eroding traditional pro-audio distributor margins in emerging markets where inventory carrying costs previously blocked tier-one brand penetration.
Global Audio Devices and Components Market Segmentation
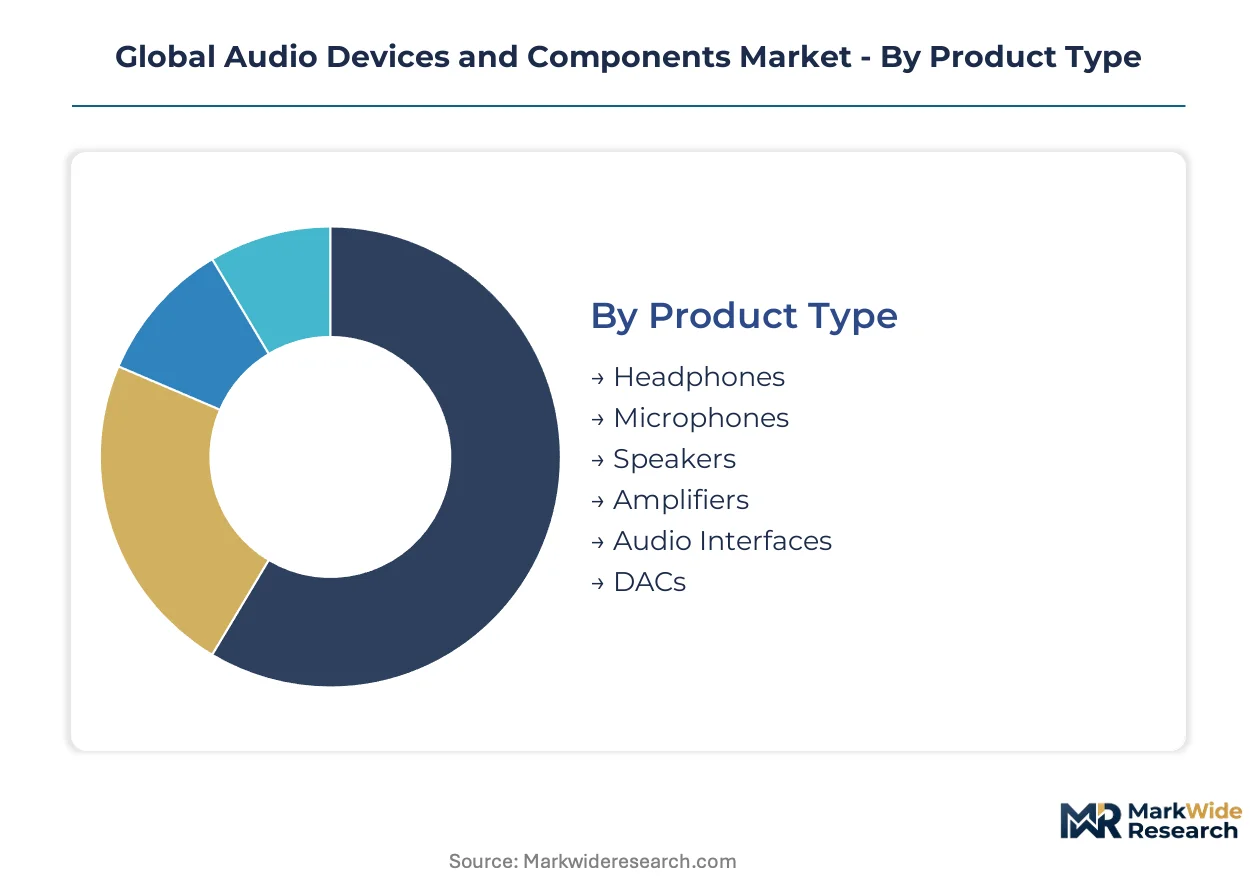
Audio devices and components segment along four critical dimensions that determine service intensity, margin structure, and replacement cycle velocity. Product type dictates acoustic engineering requirements, while technology selection governs interoperability certification burdens. Application context shapes durability specifications, and end-user profiles determine channel economics and support complexity.
Product Type:
After-sales service intensity varies dramatically across physical form factors, with portable devices requiring warranty logistics networks and installed systems demanding field calibration capabilities.
- Headphones:Encompass over-ear, on-ear, and in-ear configurations with driver diameters ranging from 8mm to 50mm. Demand concentrates in China's consumer electronics manufacturing clusters, where domestic brands like Xiaomi and Huawei compress replacement cycles through aggressive pricing. Bluetooth codec fragmentation and battery degradation drive warranty claim rates higher than other categories.
- Microphones:Span condenser, dynamic, and ribbon transducer architectures with capsule diameters from 6mm to 25mm. Podcast studios in the United States and Germany anchor professional demand, while TikTok and YouTube creators in Indonesia and Brazil drive USB condenser volume. MEMS integration is collapsing traditional electret supply chains.
- Speakers:Range from 3-inch desktop monitors to 18-inch subwoofers with enclosure designs spanning sealed, ported, and horn-loaded architectures. Automotive OEMs in Germany and Japan specify cabin-tuned systems with head-tracking compatibility.
- Amplifiers:Include Class A, Class AB, Class D, and Class H topologies with power ratings from 5W to 20,000W. Professional touring companies in the United Kingdom and Netherlands prioritize lightweight Class D modules with DSP integration.
- Audio Interfaces:Bridge analog transducers to digital workstations via USB, Thunderbolt, or Dante networking protocols. Remote production workflows in Canada and Australia drive multi-channel AD/DA converter demand.
- DACs:Convert digital bitstreams to analog signals with resolution spanning 16-bit/44.1kHz to 32-bit/768kHz. Audiophile markets in South Korea and Japan sustain premium discrete-component architectures.
Headphones hold the largest share; momentum sits with audio interfaces.
Technology:
Cost tier stratification separates premium licensed ecosystems from commodity wireless implementations, with royalty stacking determining viable price floors.
- Bluetooth:Standards span Classic, Low Energy, and LE Audio with Auracast broadcast capabilities. Smartphone OEMs in China and South Korea drive chipset volume, while FCC spectrum allocation constrains antenna design for US-bound products.
- Wired:Analog XLR, TRS, and digital AES/EBU connections persist in professional environments where latency tolerance approaches zero. Recording studios in Nashville and London maintain extensive cable infrastructure.
- Noise Cancellation:Feedforward, feedback, and hybrid architectures process ambient sound through dedicated DSP pipelines. Aviation and open-office applications in Japan and Germany specify adaptive algorithms with transparency modes.
- Voice Recognition:Far-field microphone arrays with beamforming algorithms enable hands-free control. Smart speaker OEMs in the United States and China integrate wake-word engines from Amazon and Baidu.
- Dolby Atmos:Object-based spatial audio rendering requires height channels and metadata-driven panning. Streaming services and cinema exhibitors in the United States and India drive encoder licensing volume.
- AptX:Qualcomm's proprietary codec family includes Adaptive, HD, and Lossless variants with latency profiles from 40ms to 80ms. Android device manufacturers pay per-unit royalties that accumulate with other codec obligations.
Bluetooth dominates volume; Dolby Atmos claims the steepest expansion trajectory in premium tiers.
Application:
Customer type determines margin capture, with professional buyers accepting 3-5 year depreciation schedules and consumer segments demanding annual feature refreshes.
- Consumer Electronics:Personal listening devices and home audio systems sold through retail and direct-to-consumer channels. E-commerce penetration in India and Mexico accelerates price transparency.
- Professional Audio:Studio monitors, mixing consoles, and mastering equipment with flat frequency response specifications. Post-production houses in Los Angeles and Mumbai require calibrated room correction systems.
- Gaming:Headsets with spatial audio positioning and bidirectional microphone arrays. Esports tournaments in South Korea and Denmark drive low-latency wireless demand.
- Virtual Reality:Head-mounted displays with integrated audio and external headphones with 3D spatial rendering. Meta and Sony hardware ecosystems in the United States and Japan anchor volume.
- Broadcast:RF microphone systems, intercoms, and commentary equipment with frequency coordination capabilities. Sports leagues in the United Kingdom and Brazil specify redundant wireless coverage.
- Sound Reinforcement:Line arrays, point-source loudspeakers, and stage monitors for live events. Rental companies in Germany and the United States prioritize rapid rigging and weather resistance.
Consumer electronics holds the largest share; sound reinforcement gains share fastest in post-pandemic live event recovery.
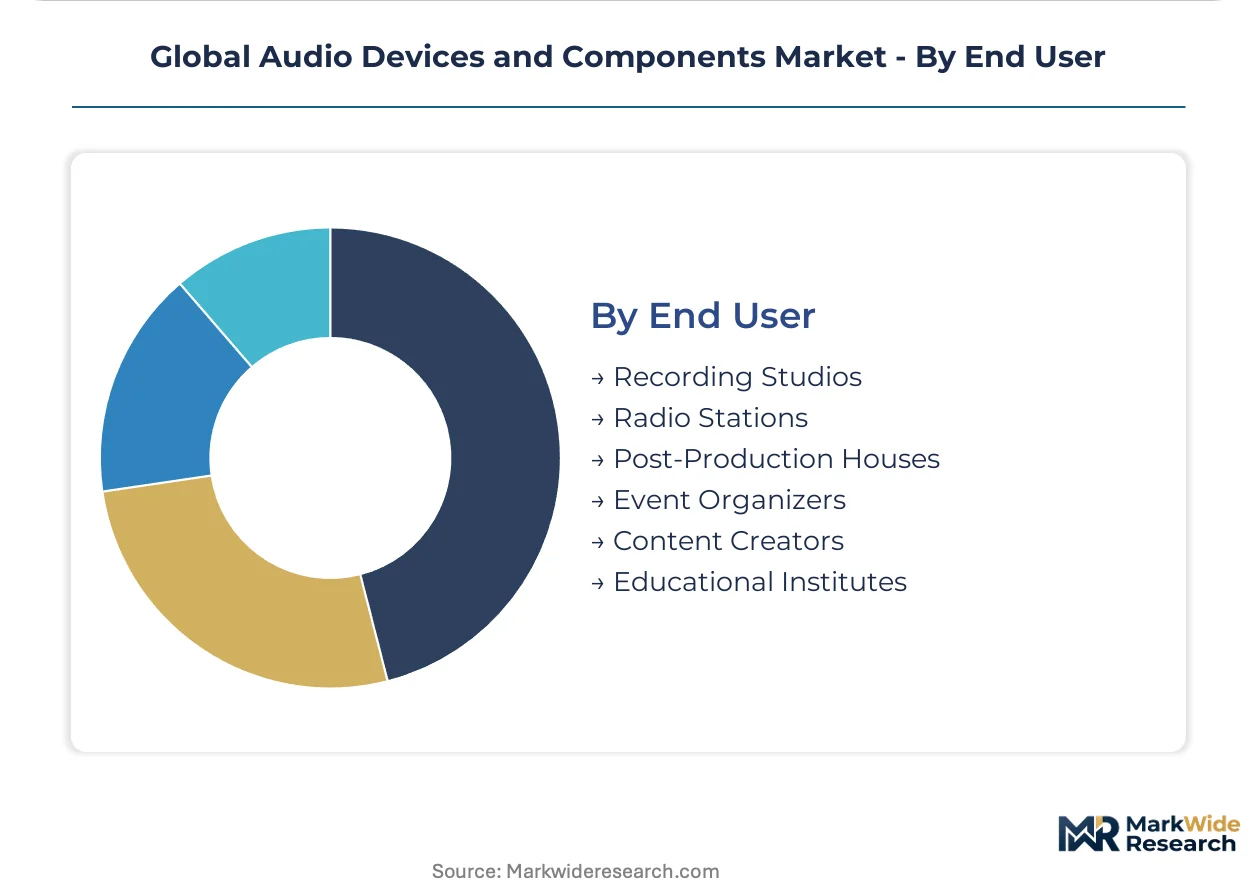
End User:
Geography shapes procurement patterns, with mature markets favoring distributor relationships and emerging markets accepting direct manufacturer engagement.
- Recording Studios:Commercial facilities with acoustic treatment and analog outboard equipment. Major hubs in London, New York, and Berlin maintain Neve and SSL console inventories.
- Radio Stations:Broadcast transmitters, on-air studios, and remote broadcast kits with IP codec connectivity. Public broadcasters in Germany and Japan sustain dedicated equipment upgrade cycles.
- Post-Production Houses:Film and television mixing stages with immersive audio dubbing capabilities. Facilities in Los Angeles, Mumbai, and Beijing handle streaming platform volume.
- Event Organizers:Rental companies and production firms supplying temporary sound systems for festivals and corporate events. Seasonal demand peaks in European summer circuits and Middle Eastern winter seasons.
- Content Creators:Independent podcasters, streamers, and YouTube producers with home studio configurations. Solo operators in Brazil, Indonesia, and Nigeria purchase through manufacturer direct channels.
- Educational Institutes:University media programs and conservatory training facilities with multi-room production suites. Institutions in South Korea and Australia invest in Dante-networked infrastructure.
Recording studios hold the largest share; content creators are climbing the fastest as independent production displaces traditional facility dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Chinese buyers cycle through budget wireless earbuds annually, while German and Japanese professional audio purchasers amortize studio monitors across five-year depreciation schedules.
United States
Content creators and podcast studios in Austin, Nashville, and Brooklyn drive interface and microphone procurement through direct manufacturer channels. The FCC governs Bluetooth and Wi-Fi spectrum allocation, constraining antenna configurations for domestic distribution. Los Angeles anchors post-production mixing stage concentration, where immersive audio dubbing for streaming platforms sustains equipment refresh cycles.
Germany
Automotive OEMs in Stuttgart and Munich specify cabin-tuned speaker systems with head-tracking spatial audio for electric vehicle differentiation. EU Ecodesign mandates under the Green Deal enforce repairability scoring and spare-part availability, favoring modular amplifier architectures. d&b audiotechnik anchors premium live-sound manufacturing in Backnang, supplying point-source and line-array systems to global touring circuits.
China
Domestic brands Xiaomi and Huawei compress consumer headphone replacement cycles through aggressive pricing in Shenzhen and Dongguan manufacturing clusters. MIIT enforces GB standards for electromagnetic compatibility that shape export-bound production protocols. Guangdong Province concentrates PCB assembly and acoustic testing capacity serving both domestic consumption and international supply chains.
Japan
Audiophile DAC markets in Tokyo and Osaka sustain premium discrete-component architectures with resolution demands extending to 32-bit/768kHz. METI oversees industrial standards coordination while JIS certification governs professional audio durability specifications. Kyushu hosts precision driver magnet processing facilities subject to rare earth export licensing volatility.
India
Electronics manufacturing incentives under the PLI scheme attract component assembly to Tamil Nadu and Karnataka clusters, with Tamil Nadu emerging as acoustic testing hub. TRAI regulates broadcast spectrum allocation affecting wireless microphone deployment for live events. Mumbai post-production houses handle streaming platform volume, driving calibrated monitor demand from domestic facilities.
Global Audio Devices and Components Market Competitive Landscape
Capability concentration sits with German-engineered premium live-sound specialists; scale advantage sits with vertically integrated consumer electronics conglomerates. The vendor base stratifies across three tiers: automotive-system integrators sustaining multi-price-tier dominance, professional audio specialists commanding installed-base loyalty through DSP-enabled platforms, and consumer brands competing on codec ecosystem access and manufacturing velocity. M&A activity concentrates in automotive audio verticals, while strategic partnerships proliferate around Auracast certification and spatial audio licensing.
Within the premium live-sound tier, d&b audiotechnik and L-Acoustics exemplify engineering-intensive positioning anchored in European manufacturing heritage. Harman International occupies a scale-driven position spanning automotive OEM supply and consumer brand portfolios. QSC represents the networked audio specialist archetype, with DSP-enabled amplification platforms serving installed commercial sound environments.
| Leading Market Players |
|---|
| L-Acoustics |
| d&b audiotechnik |
| Harman International |
| Klipsch |
| KEF |
| JBL |
| Meyer Sound |
| QSC |
| Bose |
| Others |
Supply & Pricing Matrix
Shanghai-Shenzhen freight corridors carry neodymium driver magnets and PCB assemblies from Guangdong clusters to export ports, with container rate volatility feeding directly into amplifier module cost floors and tiered pricing separation between premium audio interfaces and economy wireless earbuds.
Pricing Analysis
After-sales service revenue from field calibration contracts and spare-part availability programs drives lifetime value in professional installed audio, while consumer wireless segments operate on per-unit transactional models with razor-thin hardware margins. Price differentiation hinges on certification tier—FCC Part 15 compliance for US-bound Bluetooth products versus MIIT GB standard validation for domestic Chinese consumption—and brand premium capture in audiophile DAC markets. Pricing pressure stems from codec licensing stacking as Dolby Atmos, AptX Adaptive, and LC3plus royalties accumulate per device, compressing mid-tier headphone margins. Content creators and emerging market buyers exhibit highest price sensitivity, whereas German automotive OEMs and Japanese post-production houses accept extended depreciation schedules for calibrated monitoring systems.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Goertek, and Luxshare Precision in Dongguan and Shenzhen, handling acoustic assembly and MEMS driver integration for tier-one consumer brands. Raw material flows draw from Chinese rare earth processing for neodymium magnets, Taiwanese PCB substrate fabrication, and South Korean semiconductor packaging for DSP-enabled amplification modules. Single-source vulnerability in driver magnet supply chains exposes transducer manufacturers to Chinese export licensing volatility and price swings. Distribution runs through manufacturer-direct portals for content creator segments in Brazil and Indonesia, while professional audio channels in Germany and the United States maintain distributor relationships with field service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auracast broadcast audio and Bluetooth LE Audio standardization are collapsing proprietary wireless protocols into platform economics, with interoperability certification becoming the primary gatekeeper for hardware market access rather than proprietary technology differentiation.
For Market Incumbents: Entrench installed-base loyalty through DSP-enabled amplification platforms with Dante networking integration, defending against MEMS-based solid-state driver substitution by deepening backward integration into transducer magnet supply chains and acquiring Auracast certification capacity to compress tier-two competitor launch timelines. For New Entrants and Emerging Players: Pursue white space in OTC hearing aid convergence as FDA regulations collapse boundaries between consumer earbuds and medical-grade amplification, targeting retail pharmacy channels in the United States with direct-to-manufacturer configuration tools and thirty-day fulfillment guarantees that bypass traditional pro-audio distributor margins. For Investors and Strategic Acquirers: German-engineered premium live-sound specialists with anechoic chamber testing capabilities and point-source system IP represent the most defensible acquisition archetype in a five-to-ten-year window, with Auracast certification backlog duration and spatial audio automotive contract announcements serving as inflection indicators for platform economics tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Auracast Certification Investment | Bluetooth SIG qualification queues currently delay tier-two launches by four to six months. |
| Backward Integration into Rare Earth Magnet Supply | Kyushu processing facilities and Chinese export licensing volatility necessitate captive sourcing. |
| Direct-to-Manufacturer Portal Launch | Brazilian and Indonesian content creators now bypass distributors for microphone and interface procurement. |
| Automotive Spatial Audio Partnership | Stuttgart and Munich OEMs specify cabin-tuned systems with head-tracking for electric vehicle differentiation. |
| MEMS Driver Technology Acquisition | Solid-state architectures are displacing balanced-armature electret supply chains in South Korean and US in-ear monitor markets. |
Research Methodology
A spread of perspectives from acoustic engineering directors at German live-sound manufacturers, procurement leads at Chinese consumer electronics OEMs, broadcast engineers at UK sports leagues, and facility managers at Los Angeles post-production houses converged on the working assumptions underlying this analysis. Primary interview insights triangulated against secondary validation from FCC equipment authorization databases, MIIT GB standard filings, EU Ecodesign directive impact assessments, and customs records of neodymium magnet trade flows. Bottom-up segment sizing across product type, technology, application, and end-user dimensions combined with top-down macroeconomic anchoring to produce volume and value estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeling spanning headphones, microphones, speakers, amplifiers, audio interfaces, and DACs by Bluetooth, wired, noise cancellation, voice recognition, Dolby Atmos, and AptX technology tiers. CAGRs derived from replacement cycle velocity differentials between annual consumer wireless turnover and five-year professional equipment depreciation schedules, incorporating rare earth price volatility indices and Auracast deployment timelines as audio-specific forecast inputs.
Sensitivities concentrate around Chinese rare earth export licensing shifts, Auracast certification queue durations, and EU Ecodesign repairability mandate enforcement timelines as primary revision triggers for installed-base and replacement cycle assumptions. Quarterly review of Bluetooth SIG qualification wait times, MIIT electromagnetic compatibility standard updates, and FDA OTC hearing aid regulatory guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
North America Gaming Headsets Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Guitar Head Amplifiers Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Wireless Audio Products Market
Audio Equipment
Digital a/V Decoder Market
Audio Equipment
Soundbar Market
Audio Equipment
Professional Microphones Market
Audio Equipment
Audio Interface Market
Audio Equipment
Audio Kits Market
Audio Equipment
Speaker Cabinets, Grilles and Materials Market
Audio Equipment
Car Audio Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
Commercial Microphone Market
Audio Equipment
Radio Headset Market