
 Beeswax for Cosmetics Market | 2026-2036
Beeswax for Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Beeswax for Cosmetics Market Insights
Modular ingredient kits are repositioning how cosmetic manufacturers source beeswax, letting buyers swap between yellow, white, and refined grades within single procurement contracts. Koster Keunen leverages its Netherlands refining infrastructure to supply certified organic grades across European cosmetic manufacturers. Strahl & Pitsch anchors North American supply through its New York-based filtration and bleaching operations. Gustav Heess dominates German pharmaceutical and cosmetic-grade distribution with century-old quality protocols.
Beeswax for cosmetics comprises secretions from Apis mellifera honeybees, filtered to achieve melting points between 62°C and 65°C and used as an emulsifier, thickener, and moisture barrier in topical formulations. Yellow beeswax retains natural propolis and pollen residues preferred by organic cosmetic brands, while white and bleached variants serve color-sensitive applications in makeup and sun care where visual neutrality matters. Refined beeswax commands premium pricing in dermatology clinic channels demanding batch-traceable purity documentation.
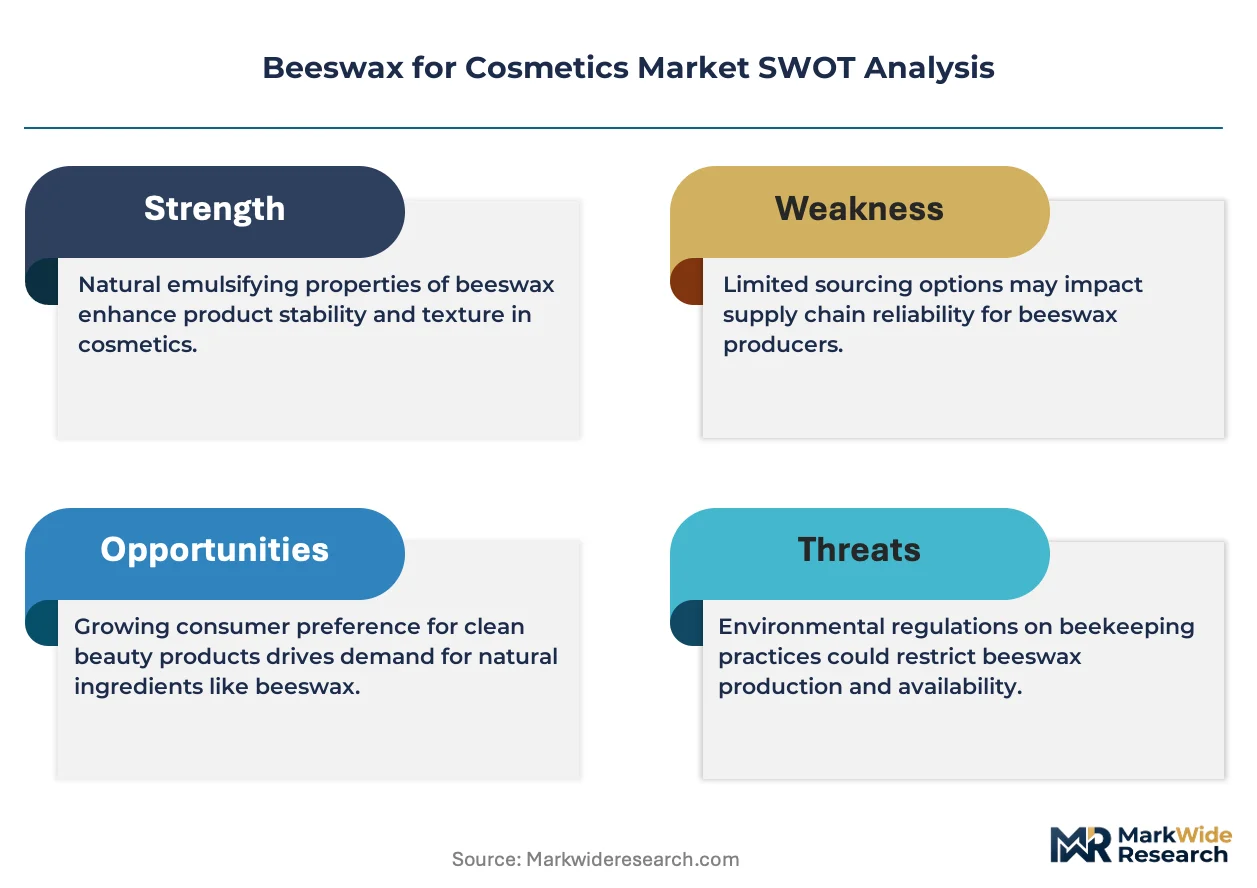
The EU Cosmetics Regulation and REACH govern beeswax purity thresholds, while the FDA oversees U.S. cosmetic ingredient safety under the Federal Food, Drug, and Cosmetic Act. These frameworks elevate compliance costs for unrefined imports but simultaneously create market access barriers that favor established European and North American refiners with documented supply chains. Stakeholders must monitor pollinator health regulations and colony collapse mitigation policies, as apiary output constraints could tighten raw material availability faster than synthetic alternatives achieve formulation parity.
Market Dynamics
Cosmetic-grade beeswax procurement is tightening around certified organic supply chains as EU REACH purity documentation requirements force reformulators to abandon spot-market sourcing in favor of batch-traceable contracts with established European refiners.
Growth Catalysts
- REACH compliance documentation:European cosmetic manufacturers now require full supply-chain traceability for beeswax imports, accelerating contract consolidation with certified Dutch and German refiners who maintain pharmaceutical-grade filtration infrastructure.
- BDIH and NaTrue label penetration:German natural cosmetics certification commands retail price premiums of 15-30% over conventional products, pulling formulation demand toward yellow beeswax grades that retain natural propolis markers.
- Emollient formulation innovation:Premium skincare brands are expanding beeswax loading in barrier creams and lip treatments, displacing petroleum-derived occlusives in clean-beauty positioning strategies.
Market Restraints
- Apiary output volatility:Colony collapse disorder and pollinator health regulations in France and Germany constrain raw beeswax harvest volumes, creating input scarcity that outpaces synthetic squalane and plant-derived candelilla wax scale-up.
- Refining capacity concentration:Pharmaceutical-grade filtration and bleaching infrastructure clusters in the Netherlands and upstate New York, limiting supply flexibility for cosmetic manufacturers outside these logistics radii.
- Import purity friction:Unrefined beeswax shipments from Eastern European and South American origins face elevated EU border testing for pesticide residues and heavy metals, extending customs clearance timelines by 4-8 weeks.
Strategic Opportunities
- Modular ingredient sourcing contracts:Procurement platforms now let cosmetic manufacturers swap between yellow, white, and refined beeswax grades within single agreements, reducing inventory carrying costs for seasonal formulation shifts.
- Dermatology clinic channel expansion:Post-procedure skincare lines in Switzerland and Austria are specifying batch-traceable refined beeswax for barrier repair formulations, creating premium pricing tiers above mass-market cosmetic applications.
- EU Green Deal bio-based targets:The European Commission's 2030 renewable materials mandate in personal care products creates regulatory tailwinds for beeswax against fossil-derived emulsifiers, with member states accelerating green public procurement criteria.
Industry Challenges
- Organic certification timeline compression:Cosmetic manufacturers face 18-24 month lead times for NaTrue and COSMOS organic beeswax qualification, delaying product launches and locking working capital in pre-approved inventory.
- Analytical chemistry skill scarcity:Batch testing for propolis fingerprinting and pesticide residue quantification requires specialized chromatography expertise that remains concentrated in German and Swiss contract laboratories, creating quality-control bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beeswax for Cosmetics Market |
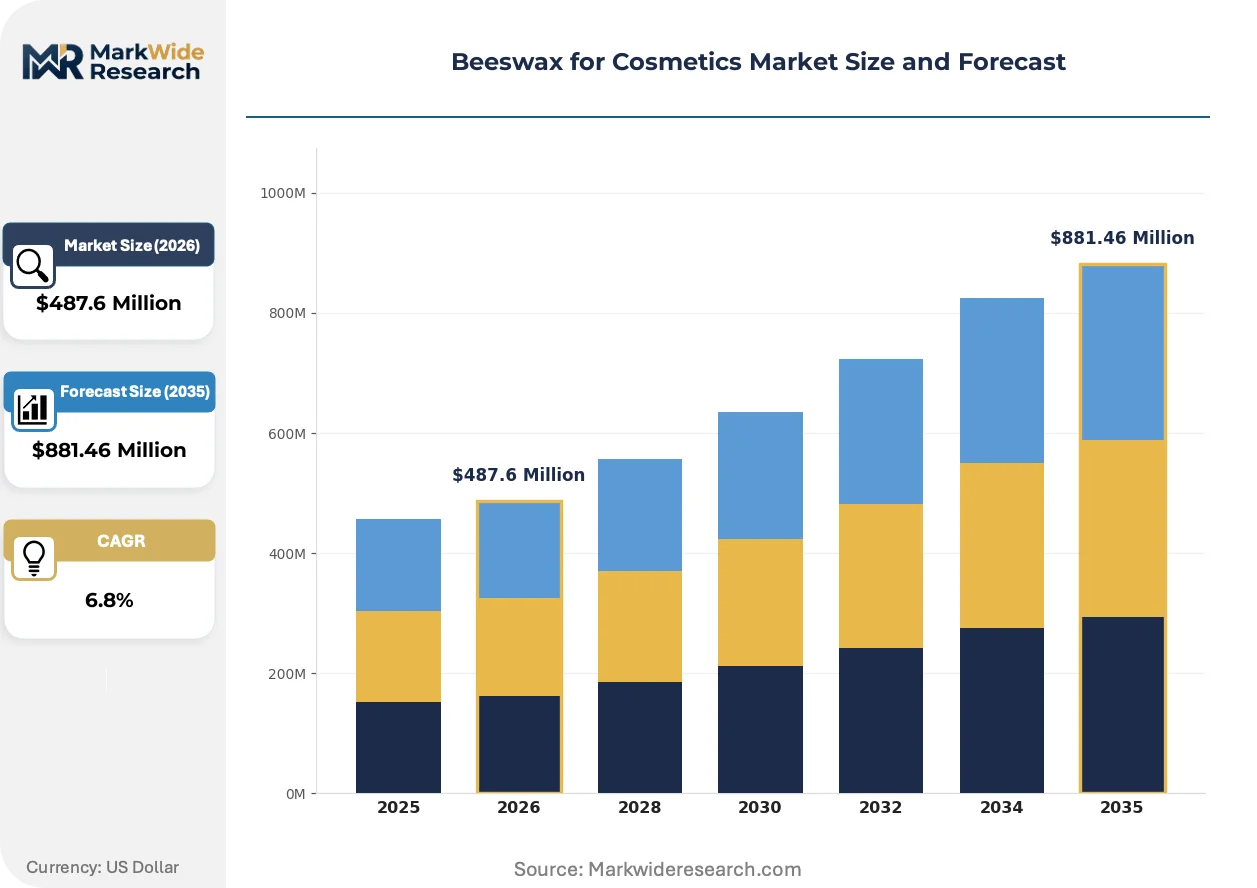
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yellow Beeswax, White Beeswax, Refined Beeswax, Organic Beeswax, Bleached Beeswax Application: Lip Care, Skincare, Hair Care, Makeup, Sun Care, Bath Products End User: Cosmetic Manufacturers, Personal Care Brands, Spas, Salons, Dermatology Clinics Packaging Type: Bulk Packs, Blocks, Pellets, Jars, Tubs |
| Companies Covered | Koster Keunen, Strahl & Pitsch, British Wax Refining Company, New Zealand Beeswax, Paramold Manufacturing, Gustav Heess, Alfa Chemical, Bulk Apothecary, Dabur India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beeswax for Cosmetics Market Trends and Innovations
Beeswax formulation is pivoting toward precision-grade customization as cosmetic manufacturers demand material properties tuned to specific emulsion rheology and sensory profiles rather than commodity-grade bulk supply.
Supercritical CO2 extraction for beeswax refinement is overtaking traditional solvent-based bleaching in premium cosmetic applications. This technology strips color bodies and odor compounds without thermal degradation of ester structures. Swiss and Austrian dermocosmetic brands are adopting CO2-refined grades for sensitive-skin formulations. The process is overtaking conventional methods by enabling sub-0.5% residual solvent levels that satisfy EU pharmaceutical excipient standards.
REACH Annex XVII restrictions on heavy metal contaminants in cosmetic ingredients are tightening testing protocols for beeswax imports. The European Chemicals Agency now requires documented chain-of-custody from hive to refinery for all cosmetic-grade shipments. German formulators are responding by consolidating procurement around Netherlands-based refiners with in-house ICP-MS testing capabilities, compressing spot-market participation.
Ingredient-as-a-service platforms are restructuring how mid-size cosmetic manufacturers access certified beeswax. These digital procurement hubs aggregate demand across multiple formulators to meet minimum order quantities for organic-grade supply, then fractionalize shipments with shared documentation costs. The model is most visible in France and Italy, where independent natural cosmetics brands lack direct contracts with major Dutch refiners.
Beeswax for Cosmetics Market Segmentation
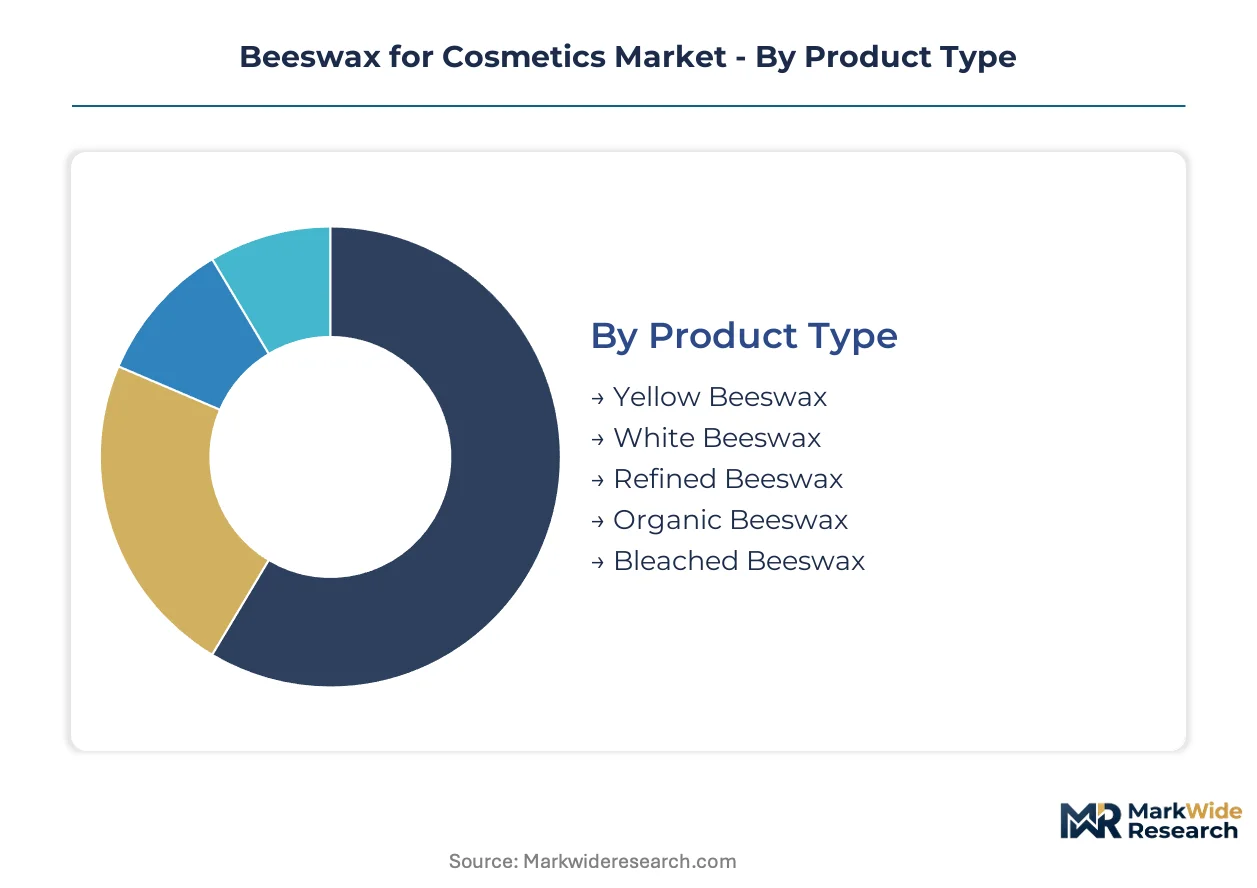
Beeswax procurement decisions in cosmetics hinge on certification pathways that determine regulatory clearance speed and retail positioning. Manufacturers navigate tiered compliance burdens across product grades, with organic and refined variants demanding documentary rigor that spot-market yellow grades bypass.
Product Type:
Certification intensity varies sharply across this category: NaTrue and COSMOS organic grades require 18-24 month qualification timelines, while conventional yellow beeswax moves through REACH documentation in weeks.
- Yellow Beeswax:Retains natural propolis and pollen residues with melting points between 62°C and 65°C. German natural cosmetics brands under BDIH and NaTrue labels concentrate procurement here, accepting visual inconsistency for organic credential integrity.
- Refined Beeswax:Pharmaceutical-grade filtration achieves batch-traceable purity documentation required by dermatology clinic channels in Switzerland and Austria. Swiss dermocosmetic formulators specify CO2-refined grades for post-procedure barrier repair lines.
- White Beeswax:Partially bleached through mechanical filtration, serving color-sensitive makeup formulations where visual neutrality matters.
- Organic Beeswax:Hive-to-refinery chain-of-custody documentation mandatory under EU Cosmetics Regulation Annex II.
- Bleached Beeswax:Solvent-based or hydrogen peroxide treatment for maximum color stripping in mass-market sun care.
Leading the category by volume: Yellow Beeswax. Growing fastest: Organic Beeswax.
Application:
Formulation loading rates and emulsion stability requirements create divergent cost tiers across cosmetic applications.
- Skincare:Barrier creams and emollient serums load beeswax at 3-8% concentration for occlusive performance. Premium skincare brands in Germany displace petroleum-derived alternatives in clean-beauty positioning strategies.
- Lip Care:Highest beeswax loading ratios (15-25%) create structural integrity for stick formats. BDIH-certified natural lip treatments command 15-30% retail premiums over conventional competitors.
- Hair Care:Pomades and waxes utilize beeswax for pliability control in styling formulations.
- Makeup:Mascara and lipstick applications demand white or bleached grades for color stability.
- Sun Care:Water-resistant film-forming properties leverage beeswax in mineral sunscreen sticks.
- Bath Products:Bath melts and oil beads incorporate beeswax for controlled release of fragrance oils.
Skincare dominates absolute consumption. Lip care delivers the highest per-unit margin contribution.
End User:
Customer type determines procurement contract structure, with dermatology clinics and personal care brands operating on opposite ends of the volume-documentation spectrum.
- Cosmetic Manufacturers:Large-scale formulators leverage modular ingredient contracts allowing grade swaps within single agreements. Netherlands-based refiners supply certified organic volumes through aggregated demand platforms.
- Dermatology Clinics:Swiss and Austrian post-procedure skincare lines specify batch-traceable refined beeswax with sub-0.5% residual solvent levels.
- Personal Care Brands:Mid-size natural cosmetics companies in France and Italy access organic grades through ingredient-as-a-service fractionalization.
- Spas:Treatment-grade bulk procurement for in-house formulation of massage balms and masks.
- Salons:Professional hair styling product manufacturers source white beeswax for pomade consistency control.
Cosmetic manufacturers absorb the largest volume share. Dermatology clinics generate the steepest pricing premiums.
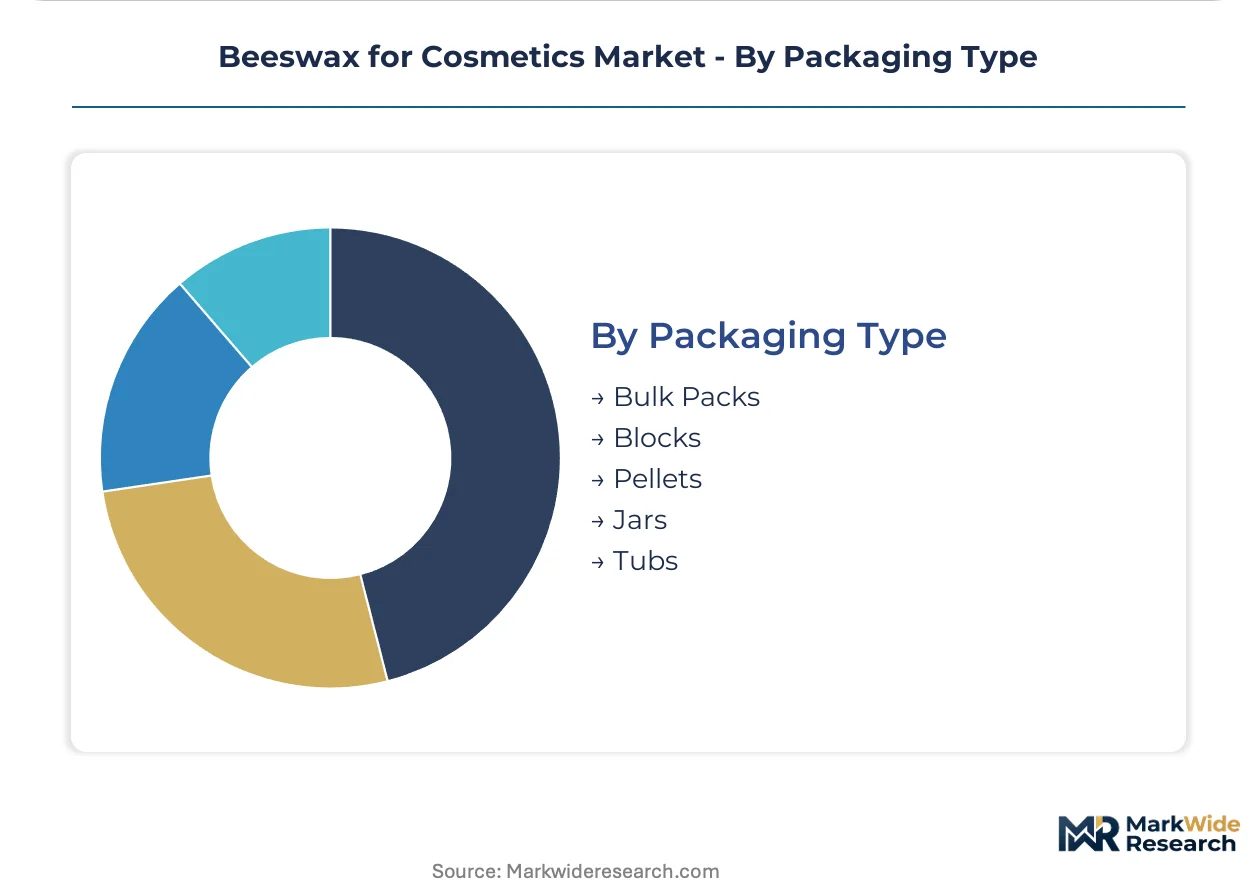
Packaging Type:
Logistics economics and handling automation requirements shape packaging selection across the value chain.
- Pellets:Standardized 3-5mm granulation enables automated metering in continuous emulsion production. German pharmaceutical-grade refiners supply pelletized organic beeswax with ICP-MS test documentation.
- Bulk Packs:25kg multi-wall bags serve high-volume cosmetic manufacturers with in-house melting and filtration infrastructure.
- Blocks:Traditional 1kg slabs retain preference among artisan formulators and small-batch natural cosmetics producers.
- Jars:Retail-ready 100-500g containers for direct-to-consumer ingredient sales and spa professional use.
- Tubs:Industrial 5-10kg pails for salon and spa back-bar formulation stations.
Pellets lead in volume throughput among automated manufacturers. Jars command the highest per-kilogram pricing in professional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Apiary output concentrates in Eastern European and South American origins, while pharmaceutical-grade refining infrastructure clusters in the Netherlands, Germany, and upstate New York. This geographic split between raw material harvest and purification capacity shapes procurement economics and compliance timelines for cosmetic manufacturers worldwide.
Germany
BDIH and NaTrue certification programs command 15-30% retail premiums for natural cosmetics, pulling formulation demand toward yellow beeswax grades with intact propolis markers. REACH Annex XVII documentation requirements compress spot-market sourcing in favor of batch-traceable contracts with established domestic distributors. Hamburg and Berlin anchor Germany's pharmaceutical-grade beeswax trade, with century-old quality protocols governing cosmetic and dermatology channel supply.
Netherlands
Rotterdam and Amsterdam host Europe's densest concentration of beeswax filtration and bleaching infrastructure, serving cosmetic manufacturers across the continent with certified organic grades. Koster Keunen leverages Dutch refining assets to supply NaTrue-qualified volumes under modular ingredient contracts. ECHA compliance documentation moves faster through Netherlands-based laboratories with in-house ICP-MS testing capabilities, shortening customs clearance timelines for cosmetic-grade imports.
United States
Clean-beauty positioning strategies in premium skincare displace petroleum-derived occlusives with beeswax loading in barrier creams and lip treatments. FDA oversight under the Federal Food, Drug, and Cosmetic Act elevates documentation burdens for unrefined imports from South American origins. Upstate New York filtration operations anchor North American pharmaceutical-grade supply, with Strahl & Pitsch maintaining regional bleaching and certification infrastructure.
Switzerland
Post-procedure skincare lines in Zurich and Geneva specify batch-traceable refined beeswax with sub-0.5% residual solvent levels for barrier repair formulations. Swissmedic pharmaceutical excipient standards exceed EU baseline requirements, creating premium pricing tiers above mass-market cosmetic applications. Supercritical CO2 extraction technology for beeswax refinement spreads from Swiss dermocosmetic brands into broader premium cosmetic adoption.
France
Independent natural cosmetics brands in Paris and Provence access organic-grade beeswax through ingredient-as-a-service platforms that aggregate demand and fractionalize shipments. ANSM oversight of cosmetic ingredient safety aligns with REACH documentation requirements for imported beeswax. French formulators face 18-24 month lead times for COSMOS organic qualification, locking working capital in pre-approved inventory ahead of product launches.
Beeswax for Cosmetics Market Competitive Landscape
The competitive structure tilts toward vertically integrated refiners with captive pharmaceutical-grade filtration infrastructure. Three to five specialized processors dominate certified organic supply, while commodity traders and regional distributors fill spot-market gaps for conventional yellow grades. Strategic archetypes include Netherlands-based organic specialists, North American pharmaceutical-grade refiners, and century-old German quality-protocol distributors. Competitive moves concentrate on modular ingredient contract innovation and supercritical CO2 extraction technology licensing.
Among European specialists, Koster Keunen occupies a position exemplifying Netherlands-based organic certification infrastructure, while Gustav Heess represents German pharmaceutical-grade distribution with documented quality protocols. Strahl & Pitsch anchors North American supply through New York-based operations. These three entities collectively illustrate how geographic concentration of refining assets shapes competitive positioning across the cosmetic-grade beeswax value chain.
| Leading Market Players |
|---|
| Koster Keunen |
| Strahl & Pitsch |
| British Wax Refining Company |
| New Zealand Beeswax |
| Paramold Manufacturing |
| Gustav Heess |
| Alfa Chemical |
| Bulk Apothecary |
| Dabur India |
| Others |
Pricing and Supply Chain Analysis
Chromatography expertise concentration in German and Swiss contract laboratories widens pricing spreads between certified organic and conventional yellow beeswax grades, as labor-cost differentials for propolis fingerprinting and pesticide residue quantification translate into tiered procurement economics for cosmetic manufacturers.
Pricing Analysis
Margin tightening in mass-market bleached grades traces to petroleum-derived occlusive displacement campaigns by clean-beauty brands. Pricing stratifies across premium, standard, and economy tiers based on certification grade and batch-traceability documentation. Cost-down pressure on unrefined imports accelerates because REACH Annex XVII testing extends customs clearance timelines. Personal care brands in France and Italy exhibit highest price sensitivity, while Swiss dermatology clinics absorb premium pricing for CO2-refined pharmaceutical grades.
Supply Chain Analysis
NaTrue and COSMOS qualification timelines gating supply access compress spot-market participation for mid-size formulators. Raw harvest concentrates in Eastern European and South American apiaries, while pharmaceutical-grade filtration infrastructure clusters in the Netherlands and upstate New York. Supply chains draw from honeybee colony outputs, supercritical CO2 extraction equipment, and ICP-MS testing capacity. Single-source vulnerability sits with Netherlands-based organic refiners. Distribution runs through ingredient-as-a-service platforms aggregating fractional demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apiary output volatility under colony collapse pressures props pricing power for established refiners with documented hive-to-laboratory chains, rewarding capacity holders against synthetic substitution threats.
For Market Incumbents: To counter synthetic squalane and plant-derived candelilla wax scale-up, deepen backward integration into Eastern European apiary networks and expand in-house ICP-MS testing capacity. Certification investment in COSMOS and NaTrue pre-qualification buffers spot-market abandonment. For New Entrants and Emerging Players: Independent natural cosmetics brands in France and Italy represent the most penetrable channel archetype, lacking direct contracts with major Dutch refiners. Ingredient-as-a-service platform partnerships offer fractionalized organic-grade access without minimum order quantity barriers. For Investors and Strategic Acquirers: Re-rating potential sits with Netherlands-based organic specialists given EU Green Deal bio-based procurement mandates accelerating regulatory tailwinds. Long-term viability hinges on captive pharmaceutical-grade filtration infrastructure. Colony collapse mitigation policy shifts signal inflection points for raw material availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Apiary Networks | Captive hive sourcing secures raw material flows against colony collapse pressures in France and Germany. |
| Supercritical CO2 Extraction Scale-Up | Sub-0.5% residual solvent levels satisfy Swissmedic pharmaceutical excipient standards for dermocosmetic channels. |
| NaTrue/COSMOS Pre-Qualification Investment | 18-24 month certification timelines lock competitor switching costs for organic-grade supply contracts. |
| Ingredient-as-a-Service Platform Launch | Aggregated demand fractionalization captures mid-size French and Italian brands outside major refiner direct contracts. |
| ICP-MS Testing Capacity Expansion | In-house heavy metal and pesticide residue documentation accelerates REACH Annex XVII compliance clearance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving apiary cooperative managers, cosmetic formulation chemists, NaTrue certification auditors, and Netherlands-based refinery procurement leads. ECHA substance registration databases, FDA cosmetic ingredient safety guidance, and German BDIH certification registries supplied documentary validation. Bottom-up volume estimates from hive-to-refinery flow tracking triangulated against top-down cosmetic manufacturer consumption surveys.
Product-grade granularity modeled yellow, white, refined, organic, and bleached variants across skincare, lip care, and dermatology clinic applications. Regional clusters captured German natural cosmetics certification penetration, Netherlands refining infrastructure concentration, and Swiss post-procedure skincare specification trends. CAGRs derived from segmented volume trajectory analysis incorporating apiary output constraints and synthetic substitution elasticity estimates.
Caveats apply where pollinator health regulation tightening or colony collapse disorder acceleration could materially shift the outlook for raw material availability. Forecasts reflect assumptions around REACH documentation burden stability and clean-beauty brand beeswax loading commitment durability. A model refresh is warranted upon material change in EU Green Deal bio-based procurement timeline acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Bath and Shower Products Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
France Sustainable Personal Care Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Europe Hair Conditioner Market