
 US Slip Resistant Shoes Market | 2026-2036
US Slip Resistant Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
US Slip Resistant Shoes Market Analysis
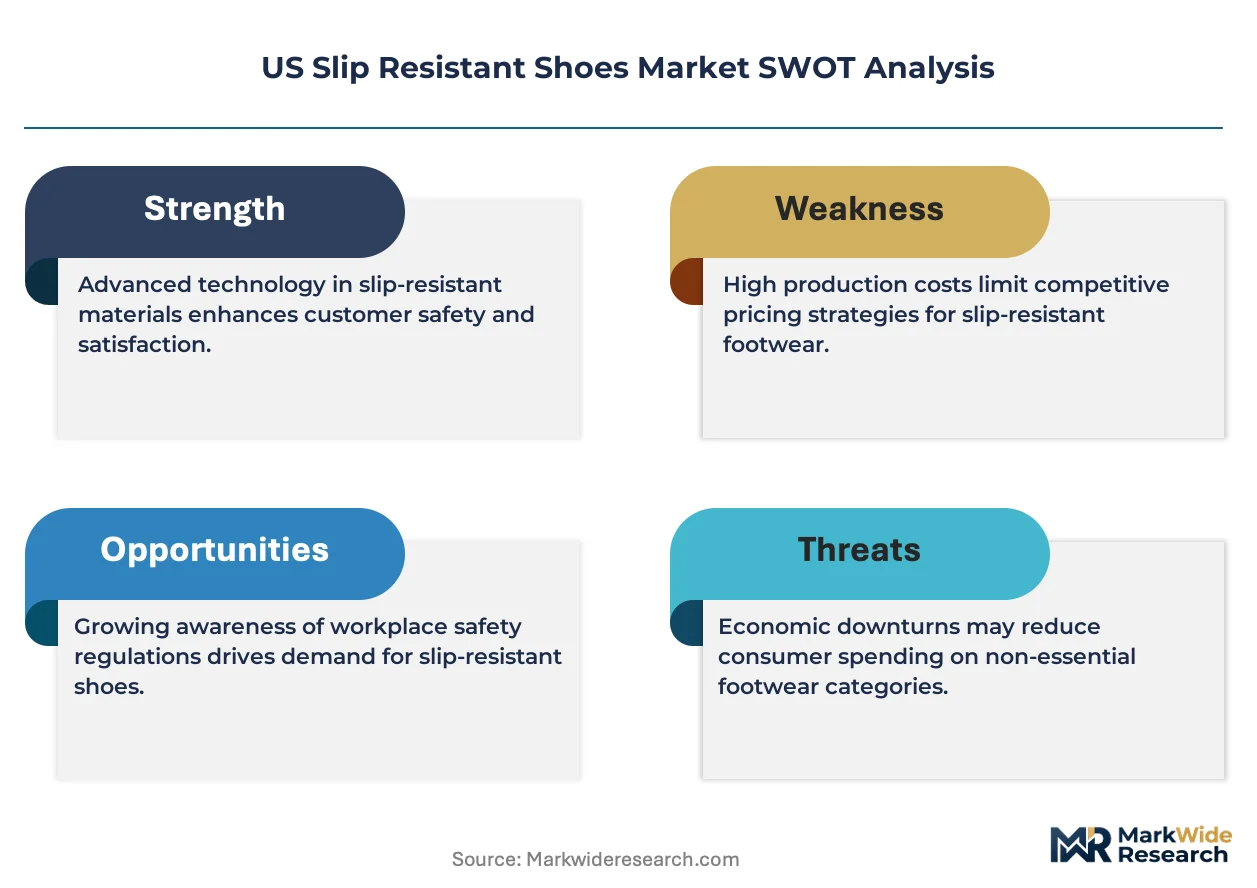
Skilled trade labor availability is bifurcating the US slip resistant shoes market into premium technical footwear and commoditized basic lines. Caterpillar leverages its construction heritage to anchor heavy-duty work boot credibility among unionized building trades. Shoes For Crews dominates food service channel control through direct corporate account relationships with national restaurant chains. New Balance competes in healthcare-oriented sneakers by sustaining domestic manufacturing scale for faster replenishment cycles.
Slip resistant shoes incorporate outsole compounds engineered to ASTM F2913 standards, utilizing rubber or polyurethane tread patterns with coefficient of friction thresholds exceeding 0.5 on contaminated steel surfaces to prevent workplace falls. Leather work boots retain the largest revenue pool among product types due to durability requirements in construction and industrial settings, though synthetic mesh sneakers targeting healthcare workers represent the fastest-expanding segment as hospital systems standardize lightweight protective footwear. Distribution through specialty shops captures higher margins from fitted work boot purchases, while online retail channels extend reach into replacement and repeat-buyer segments.
OSHA general industry standards and ASTM F2913-19 testing protocols shape product design mandates, with state-level workers compensation regimes in California, Texas, and Florida creating additional incentive structures for employer-funded footwear programs. The Department of Labor's enforcement posture on walking-working surface regulations directly affects procurement volume from large employers. Stakeholders must monitor evolving state OSHA plan adoptions and healthcare system consolidation patterns to anticipate volume concentration shifts in institutional purchasing.
Market Dynamics
OSHA enforcement intensity on walking-working surface violations is compressing employer procurement cycles and forcing standardization of ASTM F2913-certified footwear programs across institutional buyers.
Growth Catalysts
- Healthcare System Consolidation:Hospital network mergers in Sun Belt states are centralizing protective footwear procurement through system-wide vendor contracts, creating volume concentration for compliant suppliers.
- ASTM F2913-19 Testing Mandates:State OSHA plans in California, Texas, and Florida are incorporating the updated slip resistance protocol into workplace inspection checklists, mandating documented coefficient of friction thresholds.
- Aging Workforce Demographics:Workers over 55 now constitute the fastest-growing labor pool in food service and logistics, elevating employer liability exposure and accelerating adoption of fall-prevention footwear programs.
Market Restraints
- Petrochemical Input Volatility:Polyurethane and synthetic rubber compound costs fluctuate with crude oil derivatives, compressing margin stability for mid-tier manufacturers without backward integration into chemical supply.
- Domestic Manufacturing Concentration:ASTM-certified production facilities cluster in New England and upper Midwest industrial corridors, creating geographic supply risk and extended lead times for West Coast distribution.
- Leather Substitute Performance Gaps:Synthetic uppers in lightweight healthcare sneakers fail to match full-grain leather durability in construction environments, limiting cross-segment product portability.
Strategic Opportunities
- Telemedicine-Adjacent Home Healthcare:Visiting nurse associations and home health aides in Texas and Florida lack standardized footwear programs, representing an underpenetrated channel for lightweight slip-resistant sneakers.
- Last-Mile Delivery Expansion:E-commerce logistics hubs in Arizona and Nevada are hiring warehouse associates at scale without established protective footwear vendor relationships, creating first-mover positioning potential.
- Workers Compensation Premium Incentives:California's experience rating system grants premium reductions to employers with documented fall-prevention programs, directly subsidizing footwear program adoption.
Industry Challenges
- ASTM Certification Timeline Compression:Third-party testing laboratory capacity constraints in the US are extending product validation cycles from 8 to 14 weeks, delaying seasonal product launches.
- Multi-State Regulatory Fragmentation:Employers operating across state lines must reconcile varying state OSHA plan interpretations of footwear program documentation, complicating uniform procurement policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Slip Resistant Shoes Market |
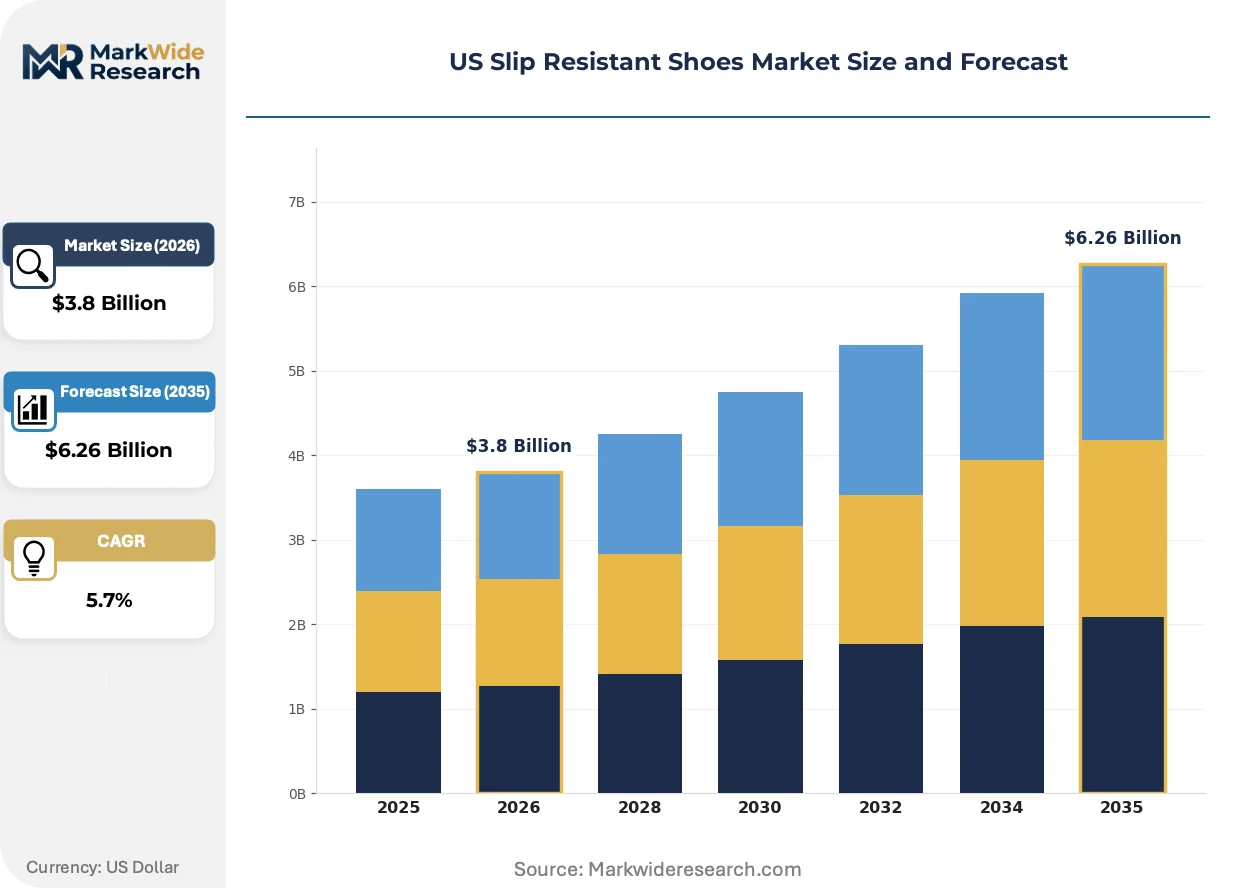
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Work Boots, Sneakers, Clogs, Sandals Material: Leather, Rubber, Synthetic, Mesh End User: Healthcare Workers, Chefs, Construction Workers, Service Staff Distribution Channel: Online Retail, Department Stores, Specialty Shops, Direct Sales |
| Companies Covered | Nike, Caterpillar, Shoes For Crews, Timberland, KEEN Utility, SR Max, New Balance, Reebok, Skechers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Slip Resistant Shoes Market Emerging Trajectories
Three distinct vectors are reshaping product architecture and go-to-market approaches: materials science advancement, regulatory protocol evolution, and institutional procurement centralization.
Microcellular polyurethane foam midsole technology is miniaturizing energy-return properties previously confined to athletic footwear into ASTM-compliant work shoes. Hospital systems in Florida are adopting these compounds for 12-hour nursing shifts, compressing the traditional trade-off between protective certification and wearer fatigue.
OSHA's National Emphasis Program on warehousing and distribution center safety is elevating documented footwear compliance to inspection priority status. Facility operators in California are responding by mandating color-coded sole inspection schedules, with red-tagged replacement triggers tied to tread depth measurements.
Corporate account direct purchasing is displacing distributor intermediaries in national restaurant chain procurement. Chains with 500-plus locations are negotiating system-wide pricing with manufacturers, consolidating what previously fragmented across regional supply houses in the Southeast and Southwest.
US Slip Resistant Shoes Market Segmentation
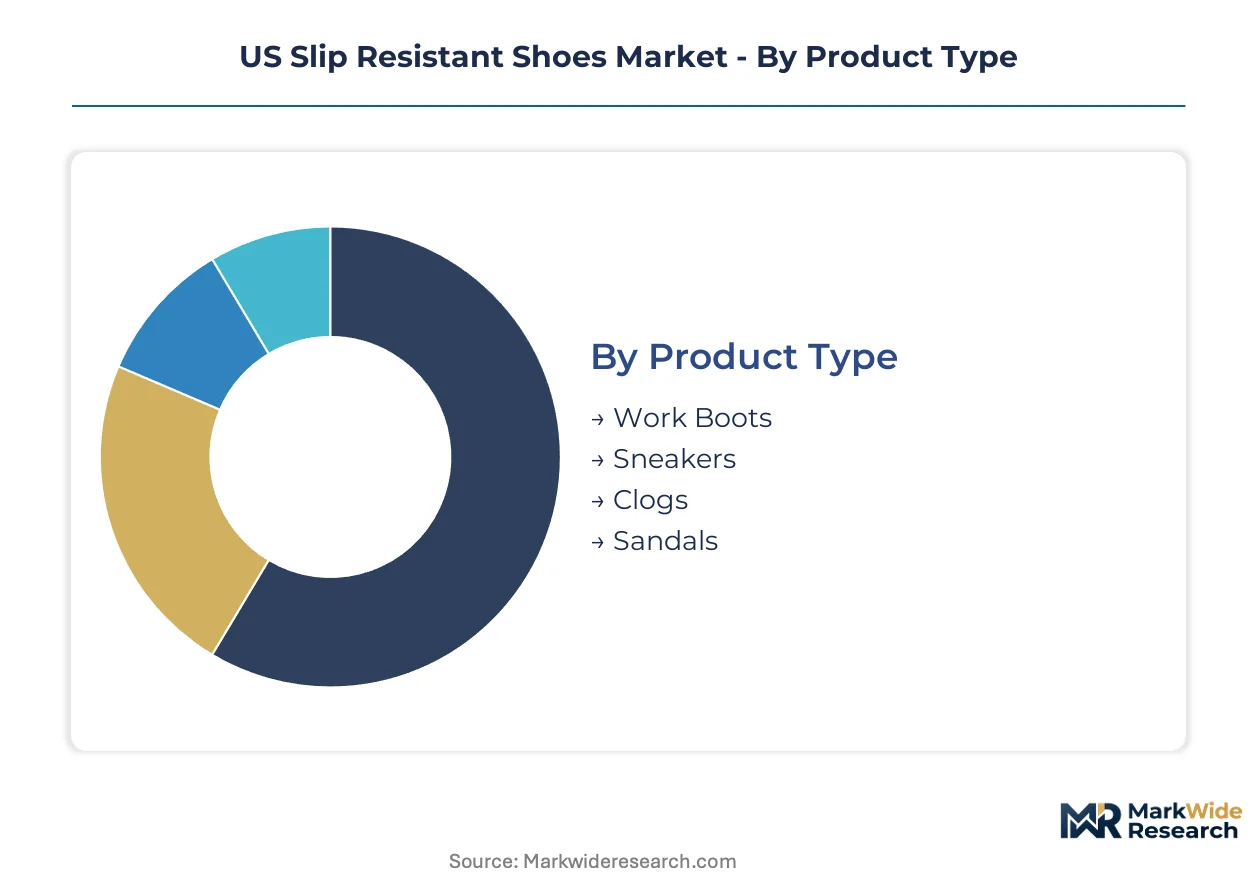
Segmentation in the US slip resistant shoes market reveals how ASTM F2913 compliance requirements, regional employment clusters, and institutional procurement patterns reshape demand across product architectures and channel structures. Understanding these divisions exposes where volume concentrates and where margin expansion remains possible.
Product Type:
Domestic production concentrates in New England and upper Midwest corridors, with work boots and clogs anchored by unionized manufacturing bases while sneakers and sandals increasingly rely on import supply chains for cost-sensitive healthcare and food service segments.
- Work Boots:Full-grain leather uppers with steel or composite toe caps dominate construction and industrial settings. Demand clusters in Texas and Florida where infrastructure spending and warehouse construction intersect with OSHA enforcement on walking-working surfaces. Unionized building trades specify American-made lines, preserving domestic manufacturing scale.
- Sneakers:Lightweight synthetic constructions with ASTM F2913-certified rubber outsoles target healthcare workers on 12-hour shifts. Hospital systems in California and Arizona are standardizing these for nursing staff, driven by workers compensation premium reduction programs and aging workforce demographics elevating fall-prevention priorities.
- Clogs:Polyurethane shell designs with closed-back variants serve kitchen and clinical environments requiring easy sanitization.
- Sandals:Open-heel configurations with slip-resistant soles address limited food service back-of-house and coastal hospitality applications where climate and dress codes permit.
Work Boots commands the established base. The steepest expansion runs through Sneakers.
Material:
Cost tier stratification separates premium full-grain leather from commodity synthetics, with raw material volatility in petrochemical derivatives compressing margin stability for mid-tier polyurethane and rubber compound suppliers.
- Leather:Full-grain hides from domestic tanneries supply work boot uppers meeting durability specifications in construction and industrial end-uses. Tight cattle supply and tanning capacity in the upper Midwest create input bottlenecks, elevating price premiums for ASTM-certified leather safety footwear.
- Synthetic:Polyurethane and thermoplastic polyurethane compounds enable lightweight sneaker midsoles with energy-return properties. California healthcare procurement is accelerating adoption as hospital systems prioritize wearer fatigue reduction alongside slip resistance compliance.
- Rubber:Nitrile and natural rubber blends form outsole compounds tested to ASTM F2913 coefficient of friction thresholds on contaminated steel.
- Mesh:Breathable synthetic knit uppers reduce weight in healthcare-oriented sneakers, though durability trade-offs limit construction segment penetration.
Leather retains the revenue core. Synthetic materials are climbing the fastest as healthcare procurement shifts toward lightweight certification.
End User:
Application-specific requirements fragment demand across institutional buyers with divergent procurement cycles, with healthcare system consolidation and restaurant chain corporatization concentrating volume for compliant suppliers.
- Healthcare Workers:Nurses, technicians, and support staff require 12-hour shift comfort combined with ASTM F2913 certification. Florida and Texas hospital network mergers are centralizing protective footwear procurement through system-wide vendor contracts, creating volume concentration for lightweight sneaker suppliers.
- Chefs:Commercial kitchen staff face grease-contaminated tile surfaces and hot liquid spill hazards. National restaurant chains with 500-plus locations are negotiating direct manufacturer relationships, displacing regional distributor intermediaries in the Southeast and Southwest.
- Construction Workers:Building trades mandate steel toe protection and electrical hazard ratings alongside slip resistance. Union specifications in California and New York preserve domestic work boot manufacturing.
- Service Staff:Hotel and retail front-of-house employees face lower hazard exposure but rising employer liability consciousness in Sun Belt hospitality markets.
Construction Workers anchor historical volume. Healthcare Workers are expanding most quickly as hospital system consolidation accelerates standardized program adoption.
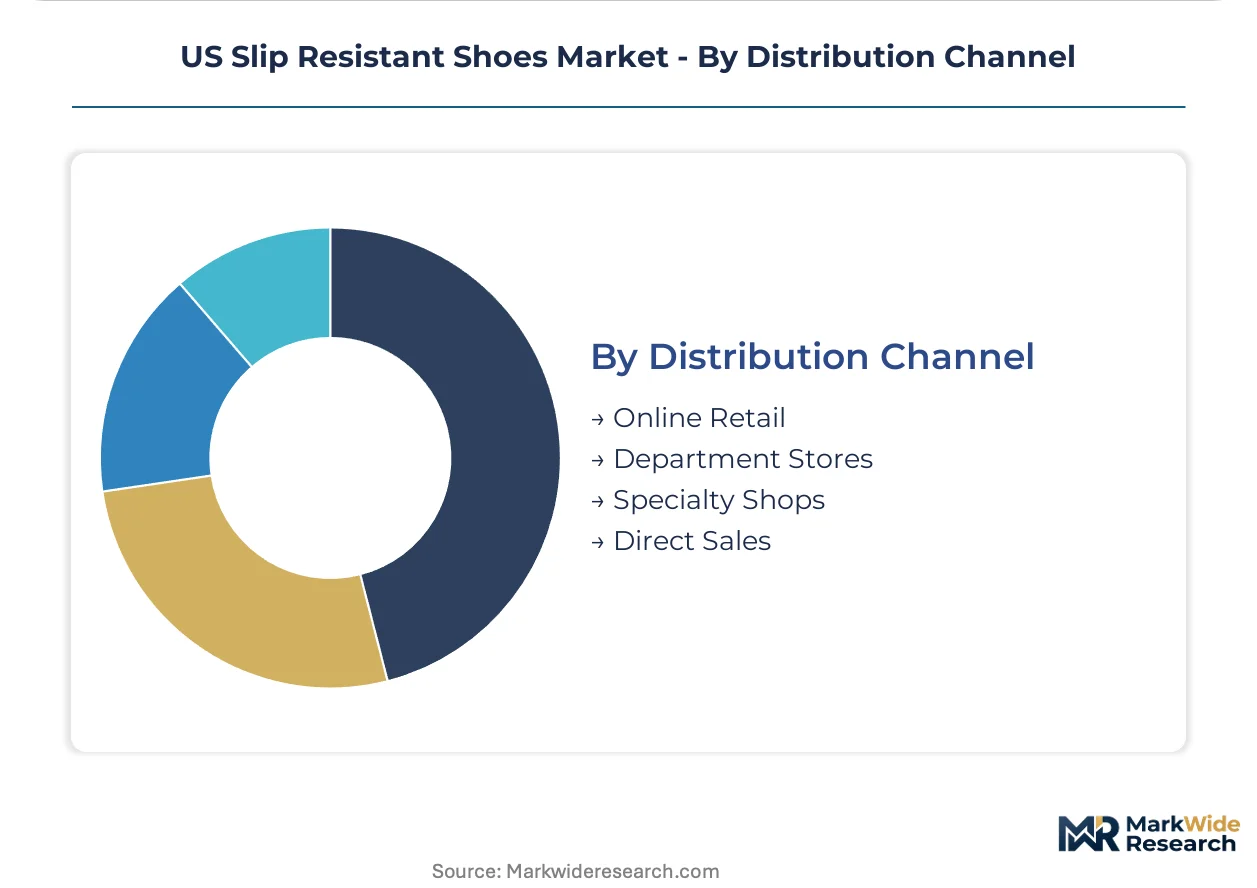
Distribution Channel:
Customer type and purchase occasion determine channel selection, with institutional direct purchasing displacing traditional retail for replacement and repeat-buyer segments while specialty shops retain fitted work boot margins.
- Direct Sales:Corporate account relationships with national restaurant chains and hospital systems enable system-wide pricing and compliance documentation. This channel is displacing distributor intermediaries as procurement centralizes.
- Online Retail:Replacement purchasing and repeat-buyer convenience drive volume in healthcare and food service segments where fit is standardized. Arizona and Nevada logistics hubs support West Coast fulfillment.
- Specialty Shops:Fitted work boot purchases with professional sizing retain higher margins in construction and industrial segments.
- Department Stores:Mass retail captures price-sensitive service staff demand with limited product differentiation.
Direct Sales is capturing institutional volume. Online Retail is gaining share fastest as replacement cycles compress and compliance documentation digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing premiums for ASTM F2913-certified work boots that California distributors cannot match due to freight differentials from New England manufacturing corridors. This geographic asymmetry reshapes procurement patterns across institutional buyers.
California
Healthcare system consolidation in Los Angeles and San Francisco Bay Area markets drives centralized sneaker procurement through system-wide vendor contracts. Cal/OSHA's adoption of ASTM F2913-19 testing protocols into workplace inspection checklists mandates documented coefficient of friction thresholds. Hospital networks in San Diego standardize lightweight protective footwear for nursing staff to capture workers compensation premium reductions.
Texas
Infrastructure spending and warehouse construction in Dallas-Fort Worth and Houston generate concentrated demand for leather work boots with steel toe protection. Texas maintains its state OSHA plan alignment with federal walking-working surface regulations. Unionized building trades in the Permian Basin specify American-made lines, preserving domestic manufacturing premiums.
Florida
Aging workforce demographics in Tampa and Orlando healthcare markets elevate employer liability exposure for fall-prevention footwear programs. The state's hospital network mergers centralize protective footwear procurement through single-source vendor relationships. Miami hospitality markets face rising slip-and-fall litigation, accelerating adoption of color-coded sole inspection schedules.
Arizona
E-commerce logistics hubs in Phoenix and Tucson hire warehouse associates at scale without established protective footwear vendor relationships. Arizona's state OSHA plan enforcement posture on distribution center safety elevates documented footwear compliance to inspection priority status. Last-mile delivery expansion creates first-mover positioning potential for lightweight sneaker suppliers.
Nevada
Las Vegas hospitality and Reno logistics markets intersect with limited regional distribution infrastructure for ASTM-certified footwear. The state's workers compensation regime creates incentive structures for employer-funded footwear programs in casino and warehouse operations. Colorado River water constraints on regional manufacturing limit local production alternatives.
US Slip Resistant Shoes Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the US slip resistant shoes market, with ASTM F2913 certification capabilities separating premium technical footwear from commoditized basic lines. The vendor base organizes into three strategic tiers: construction heritage brands anchoring unionized building trades, food service channel specialists controlling corporate account relationships, and athletic footwear manufacturers scaling domestic production for healthcare replenishment cycles. Dominant competitive moves include direct corporate account negotiations displacing distributor intermediaries and microcellular polyurethane foam technology licensing for energy-return midsole integration.
Within the construction heritage tier, Caterpillar Inc. and Timberland LLC exemplify heavy-duty work boot credibility anchored in industrial brand equity. KEEN Utility occupies a position bridging outdoor recreation technical expertise with ASTM-compliant work footwear. Among athletic footwear specialists, New Balance Athletics, Inc. represents domestic manufacturing scale advantages for faster replenishment cycles in healthcare procurement. Shoes For Crews anchors food service channel control through direct relationships with national restaurant chains. Nike Inc. and Skechers USA, Inc. exemplify volume-driven athletic crossover strategies targeting lightweight healthcare sneaker segments.
| Leading Market Players |
|---|
| Nike |
| Caterpillar |
| Shoes For Crews |
| Timberland |
| KEEN Utility |
| SR Max |
| New Balance |
| Reebok |
| Skechers |
| Others |
Supply Flow & Price Mechanics
Fourteen-week product validation cycles at third-party testing laboratories compress seasonal launch windows and amplify pricing power for manufacturers with captive ASTM F2913 certification capabilities in New England industrial corridors. This lead-time rigidity concentrates margin capture among vertically integrated suppliers while forcing cost pass-through downstream to institutional buyers.
Pricing Analysis
Texas distributors command price premiums for ASTM F2913-certified work boots that California buyers cannot match due to freight differentials from upper Midwest manufacturing clusters. Three-tier pricing structure across premium technical footwear, mid-tier certified lines, and economy imports separates union-specified domestic production from commoditized food service imports. Cost compression in mid-tier polyurethane compounds intensifies because petrochemical input volatility squeezes manufacturers without backward integration. National restaurant chains exhibit lowest price sensitivity through direct corporate account negotiations, while independent construction subcontractors face acute margin pressure.
Supply Chain Analysis
Inventory cycles stretching 14 weeks from ASTM certification submission to market release tether production scheduling to third-party laboratory capacity constraints in Massachusetts and Ohio. Domestic manufacturing concentrates in New England and upper Midwest corridors, drawing from cattle supply in the upper Midwest and petrochemical feedstocks from Gulf Coast refineries. Single-source vulnerability runs through concentrated tanning capacity for full-grain leather uppers. Distribution runs through direct corporate account relationships displacing regional distributor intermediaries in healthcare and food service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US slip resistant shoes market demands substitution defense against athletic footwear manufacturers repurposing running shoe platforms into lightweight ASTM-compliant healthcare sneakers. Incumbents must navigate this cross-category encroachment while preserving technical certification credibility.
For Market Incumbents: Fortify ASTM F2913 certification moats by accelerating third-party testing laboratory partnerships to compress validation timelines below competitor reach. Anchor domestic manufacturing scale in New England corridors to capture union-specified construction procurement and lock out import-dependent rivals. Certification investment serves as the priority lever against athletic crossover entrants lacking industrial safety credibility.
For New Entrants and Emerging Players: Lead with telemedicine-adjacent home healthcare segments in Texas and Florida where visiting nurse associations lack standardized footwear programs. Target last-mile delivery logistics hubs in Arizona and Nevada hiring warehouse associates at scale without established vendor relationships. A direct-to-institution sales model with rapid replenishment cycles penetrates faster than distributor-dependent incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because OSHA enforcement intensity on walking-working surface violations institutionalizes recurring procurement cycles for compliant suppliers. Acquisition targets center on mid-tier manufacturers with latent ASTM certification capabilities and underutilized New England production assets. The signal to watch is state OSHA plan adoption velocity in Sun Belt states accelerating procurement centralization.
| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Acceleration | Third-party laboratory partnerships compress validation cycles below 10 weeks, outpacing rival seasonal launches. |
| Direct Corporate Account Expansion | System-wide vendor contracts with hospital networks displace fragmented distributor relationships in Sun Belt states. |
| Microcellular Polyurethane Licensing | Energy-return midsole technology transfers athletic footwear comfort into 12-hour healthcare shift compliance. |
| West Coast Distribution Footprint | Arizona and Nevada logistics hubs reduce freight differentials eroding California pricing competitiveness. |
| Home Healthcare Channel Development | Visiting nurse associations in Texas and Florida represent underpenetrated volume for lightweight sneaker suppliers. |
Methodological Framework
A standing panel of protective footwear procurement managers, OSHA compliance officers, hospital system supply chain directors, third-party testing laboratory technicians, and unionized building trade stewards provided ongoing calibration across primary fieldwork. Secondary validation drew from ASTM International certification databases, OSHA enforcement action records, state workers compensation commission filings, hospital GPO contract disclosures, and customs import data for footwear HTS codes. Bottom-up volume estimates from end-user segment sizing triangulated against top-down manufacturer shipment data.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled segmentation dimensions spanning product architecture, material composition, end-user application, and distribution channel structure. CAGRs derived from compound growth mechanics applied to baseline volume and value estimates. Industry-specific forecast inputs incorporated hospital system merger timelines and state OSHA plan adoption schedules.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement posture or accelerated healthcare consolidation would require recalibration. Forecasts reflect documented assumptions about regulatory trajectory and institutional procurement centralization. Specific risk factors include petrochemical price volatility compressing mid-tier margins and third-party testing laboratory capacity constraints extending certification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Shoe Insoles Market
Footwear
Hiking Footwear Market
Footwear
Desert Boots Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Footwear Testing Services Market
Footwear
Europe Footwear Market
Footwear
Chunky Sneaker Market
Footwear
Flip Flops Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Kids Barefoot Shoes Market
Footwear
E-Commerce Footwear Market
Footwear
Sneakers Market
Footwear
Tennis Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Western Boots Market
Footwear
Equestrian Footwear Market