
 Banking Cyber Security Market | 2026-2036
Banking Cyber Security Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Cyber Security Market Intelligence
Revenue from managed security services is tilting the market's profit pools away from traditional on-premises software licensing. Cisco Systems leverages its extensive network infrastructure to integrate security features directly into its hardware and software offerings. CrowdStrike specializes in cloud-native endpoint protection, offering a distinct approach focused on threat intelligence and response. Palo Alto Networks competes by providing a comprehensive platform that spans network, cloud, and security operations.
Banking cyber security comprises technologies, processes, and controls designed to protect financial digital assets from attack. These systems use behavioral analytics and machine learning for real-time threat detection to ensure data confidentiality and prevent fraud. Identity & Access Management solutions represent a foundational security layer, with cloud-based deployment models showing significant adoption. While Commercial Banks constitute the largest customer base, FinTech companies are a key source of new, specialized demand.
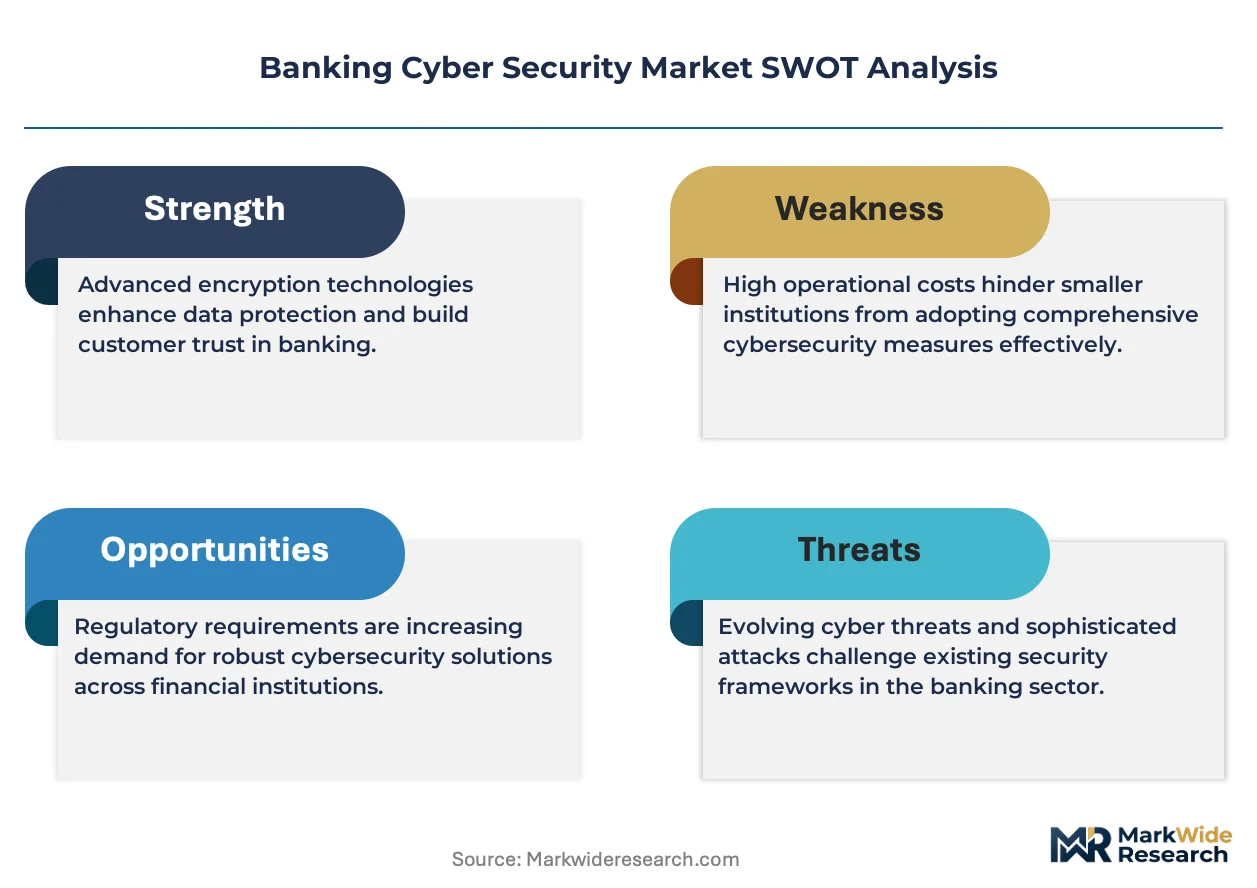
Regulatory frameworks such as the EU's GDPR and the U.S. SEC's cybersecurity disclosure rules are compelling financial institutions to invest heavily in compliance and reporting capabilities. These regulations establish stringent requirements for data protection, breach notification, and comprehensive risk management, directly shaping technology procurement decisions. Navigating the complex landscape of sovereign cloud requirements and data localization laws will be a critical strategic challenge for vendors and financial institutions alike.
Market Dynamics
The fundamental market dynamic is the tension between the rapid, technology-driven innovation cycles of FinTech companies and the slower, compliance-focused procurement of incumbent commercial banks, creating a dual-speed demand environment for cybersecurity vendors.
Growth Catalysts
- Regulatory Mandates:Stringent rules like the EU's GDPR and the U.S. SEC's cybersecurity disclosure requirements compel continuous investment in advanced compliance, reporting, and data protection technologies across the financial sector.
- FinTech Expansion:The proliferation of digital-native challenger banks and payment platforms creates a significant source of new demand for sophisticated, cloud-based fraud detection and identity management solutions.
- AI Integration:The embedding of artificial intelligence and machine learning into threat intelligence platforms enables real-time behavioral analytics, improving the detection of novel attacks and reducing false positives for security teams.
Market Restraints
- Legacy System Integration:The high cost and technical complexity of integrating modern cybersecurity platforms with aging mainframe and core banking systems present a significant barrier for many established financial institutions.
- Data Sovereignty Laws:Data localization requirements in jurisdictions such as India and China restrict the use of global, multi-tenant cloud security services, forcing costly and complex single-country deployments.
- Advanced Threat Sophistication:The increasing use of AI by malicious actors to generate novel phishing campaigns and polymorphic malware strains challenges the efficacy of existing signature-based and behavioral detection models.
Strategic Opportunities
- Underserved Segments:Developing scalable, cost-effective security solutions tailored for small and medium-sized credit unions and regional banks represents a significant white-space opportunity, particularly in North America.
- Securing Digital Currencies:The emergence of central bank digital currencies (CBDCs) and enterprise blockchain applications creates a new demand category for specialized cryptographic security and transaction monitoring tools.
- Managed Security Services:Expanding managed threat detection and response (MDR) services allows vendors to capture recurring revenue streams from financial institutions lacking sufficient in-house cybersecurity talent.
Industry Challenges
- Cybersecurity Talent Shortage:A persistent global deficit of professionals with dual expertise in financial services regulations and modern cloud security protocols constrains the ability of banks to manage and operate new systems effectively.
- Tool Sprawl and Complexity:Integrating dozens of disparate point solutions for endpoint, network, and cloud security into a unified security operations center (SOC) view remains a major operational hurdle for IT teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Cyber Security Market |
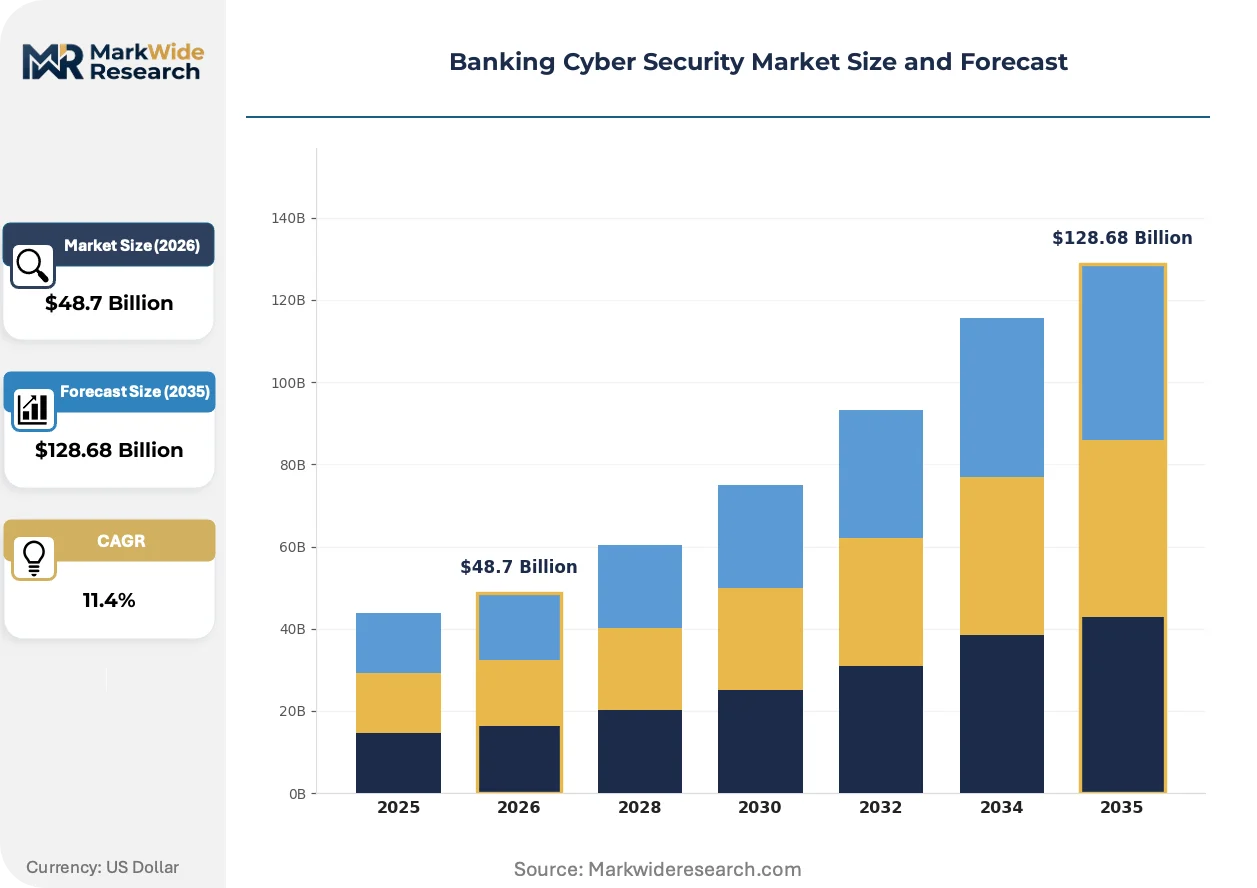
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Identity & Access Management, Threat Intelligence, Data Loss Prevention, Encryption, Fraud Detection, Network Security Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Security Services, Virtualized Security Application: Risk Management Systems, Payment Processing, Online Banking Security, Anti-Money Laundering, Mobile Banking Protections, Regulatory Compliance Customer Type: Commercial Banks, Credit Unions, Investment Firms, Insurance Companies, FinTech Companies, Microfinance Institutions |
| Companies Covered | Fortinet, Cisco Systems, Palo Alto Networks, Trellix, Rapid7, CrowdStrike, Microsoft Security, IBM Security, Check Point Software Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Cyber Security Market Strategic Shifts & Innovations
The market is reorienting from a focus on perimeter defense to an identity-centric security posture. This shift is a direct response to the dissolution of traditional network boundaries caused by cloud adoption and the need for more granular, intelligence-driven controls.
Identity and Access Management (IAM) solutions provide the foundational technology for controlling user privileges and enforcing access policies to critical digital assets. Large commercial banks and investment firms are accelerating their adoption of advanced IAM. The focus of security is migrating from defending the network perimeter to verifying every identity, device, and access request, embodying the principles of a Zero Trust architecture.
New regulations are actively shaping technology roadmaps and procurement priorities. The EU's Digital Operational Resilience Act (DORA) imposes strict rules on ICT risk management and third-party provider oversight for all financial entities. This forces institutions to conduct comprehensive threat-led penetration testing and enhance incident reporting capabilities. Investment firms and their cloud service providers are most affected, now required to prove operational resilience through rigorous testing.
Buying patterns are evolving from large, upfront capital expenditures to more flexible operational models. Financial institutions increasingly favor subscription-based pricing for cybersecurity software and managed services over traditional perpetual licenses. This change benefits cloud-native vendors and disrupts incumbents reliant on multi-year on-premises software deals. This trend is most visible among agile FinTech startups and neobanks in the United States and Europe.
Banking Cyber Security Market Segmentation
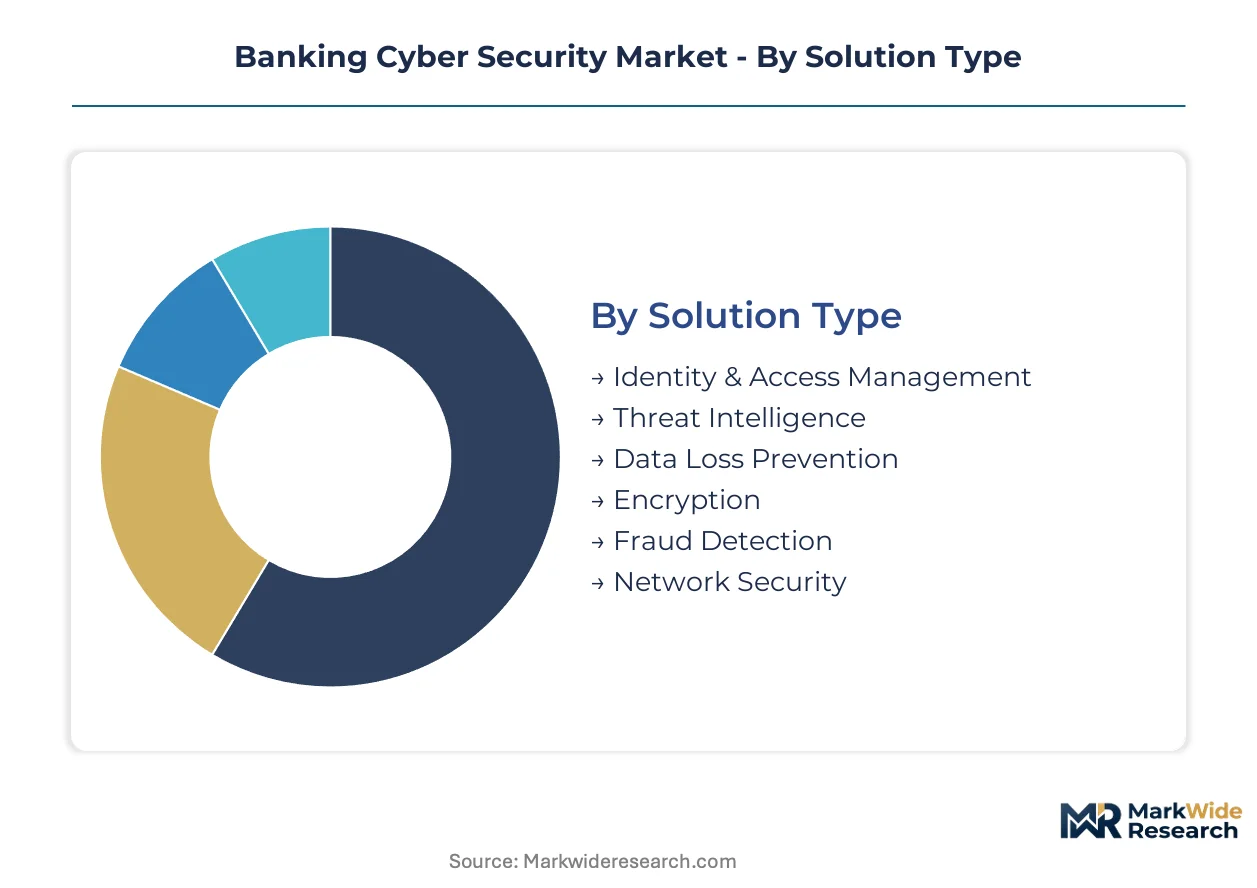
The Banking Cyber Security Market exhibits diverse segmentation across critical dimensions, reflecting the varied needs and operational structures of financial institutions. Understanding these distinct segments is essential for vendors to tailor solutions that address specific security challenges and compliance requirements within the financial sector.
Solution Type:
The maturity spectrum of cybersecurity solutions ranges from foundational identity management to advanced fraud detection capabilities.
- Identity & Access Management:These foundational security technologies control user privileges and enforce access policies for critical digital assets, ensuring only authorized personnel and systems can access sensitive financial data. Large commercial banks are accelerating their adoption of advanced IAM solutions to underpin Zero Trust architectures.
- Fraud Detection:Sophisticated systems employing behavioral analytics and machine learning identify and prevent fraudulent transactions and activities in real-time. FinTech companies are a significant source of new demand for these advanced solutions, driven by their digital-native operations.
- Threat Intelligence:Platforms that aggregate and analyze data on emerging cyber threats, providing actionable insights for proactive defense strategies.
- Data Loss Prevention:Technologies designed to prevent sensitive financial information from leaving the controlled network perimeter, whether intentionally or accidentally.
- Encryption:Cryptographic methods used to secure data at rest and in transit, protecting confidentiality and integrity across financial transactions and communications.
- Network Security:Measures and technologies protecting the underlying network infrastructure from unauthorized access, misuse, malfunction, modification, or destruction.
Identity & Access Management retains volume leadership; Fraud Detection holds the steepest expansion curve.
Deployment Model:
Operational model efficiency drives preferences in how cybersecurity solutions are implemented across financial entities.
- Cloud-Based:Security services hosted on cloud infrastructure, offering scalability, flexibility, and reduced on-premises hardware requirements. FinTech startups and neobanks in the United States and Europe favor cloud-native deployments for agility and cost efficiency.
- Managed Security Services:Outsourced cybersecurity functions, including monitoring, threat detection, and incident response, provided by third-party experts. Financial institutions lacking in-house cybersecurity talent are increasingly relying on these services for comprehensive protection.
- On-Premises:Security software and hardware installed and managed directly within an organization's own data centers. Established commercial banks often retain on-premises solutions for specific legacy systems and stringent data control requirements.
- Hybrid:A combination of both on-premises and cloud-based security solutions, allowing organizations to leverage benefits from both models.
- Virtualized Security:Security functions implemented as software-based virtual appliances, offering agility and resource optimization within virtualized environments.
Cloud-Based deployment models demonstrate significant adoption; Managed Security Services exhibit robust growth in operational efficiency.
Application:
Regulatory impact significantly shapes the demand for specific cybersecurity applications within the financial sector.
- Regulatory Compliance:Solutions designed to help financial institutions meet stringent regulatory requirements for data protection, breach notification, and risk management. The EU's GDPR and DORA directly shape technology procurement decisions in this area.
- Risk Management Systems:Technologies that identify, assess, and mitigate various financial and operational risks, including cyber risks. Investment firms are heavily investing in these systems to ensure operational resilience.
- Payment Processing:Security measures specifically applied to protect digital payment transactions from fraud, unauthorized access, and data breaches.
- Online Banking Security:Protections for web-based banking platforms, safeguarding customer accounts and sensitive transaction data.
- Anti-Money Laundering:Systems that detect and prevent illegal financial activities, such as money laundering and terrorist financing, through transaction monitoring and behavioral analysis.
- Mobile Banking Protections:Security features tailored for mobile applications, securing access and transactions performed on smartphones and tablets.
Regulatory Compliance applications are paramount for financial institutions; Risk Management Systems are pivotal for comprehensive risk mitigation.
Customer Type:
Demand velocity varies significantly across different customer segments within the banking cybersecurity market.
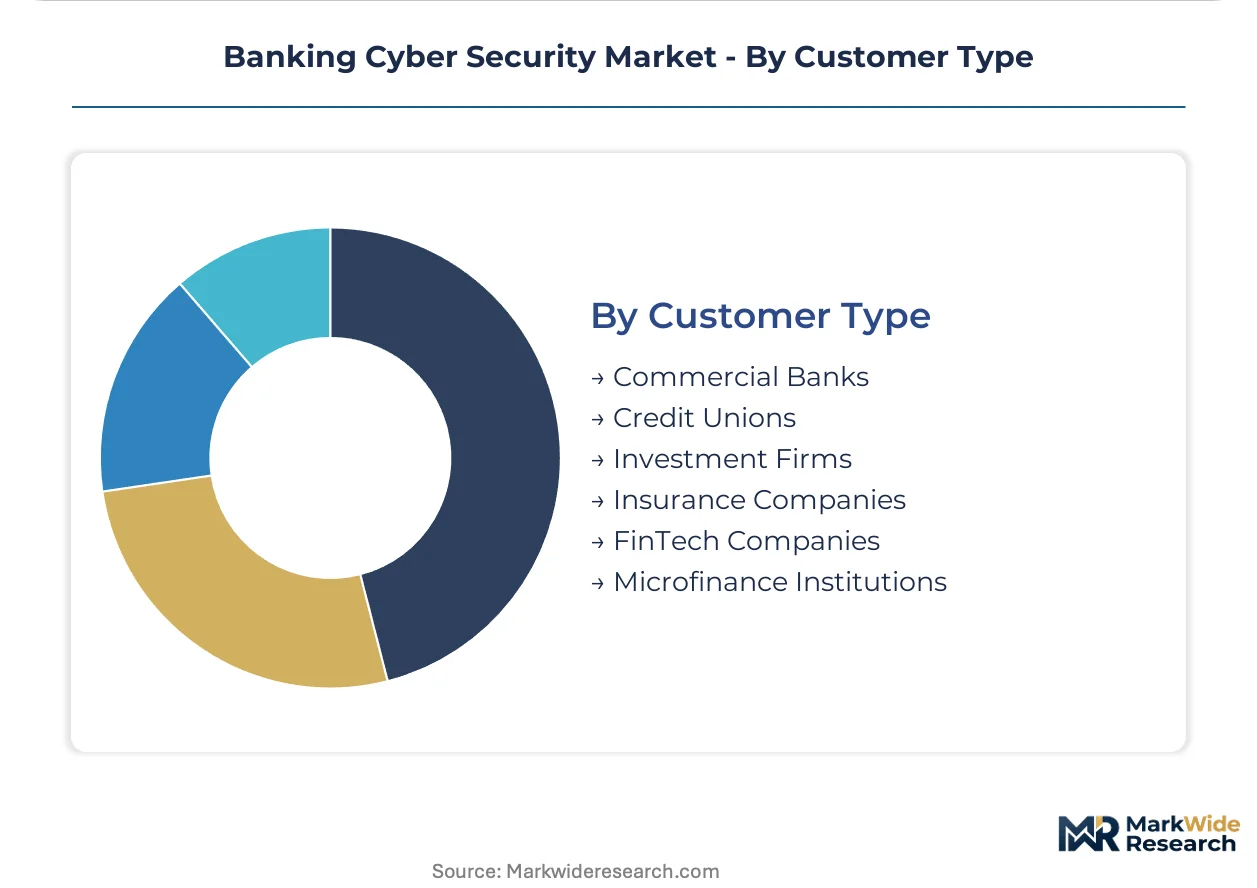
- Commercial Banks:Large, established financial institutions that constitute the largest customer base for cybersecurity solutions, focusing on comprehensive protection and regulatory adherence. These banks prioritize robust, integrated platforms.
- FinTech Companies:Digital-native challenger banks and payment platforms that are a key source of new, specialized demand for cloud-based fraud detection and identity management solutions. These companies drive innovation in security approaches.
- Credit Unions:Member-owned financial cooperatives requiring scalable, cost-effective security solutions, often seeking managed services due to limited in-house resources.
- Investment Firms:Institutions focused on asset management and trading, demanding advanced security for high-value transactions and sensitive client data.
- Insurance Companies:Organizations that protect vast amounts of personal and financial data, requiring robust data loss prevention and identity management.
- Microfinance Institutions:Entities providing financial services to low-income individuals, needing accessible and efficient security measures to protect their operations.
Commercial Banks represent the largest customer segment; FinTech Companies are significant innovation drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for banking cybersecurity solutions varies significantly by region, reflecting diverse regulatory pressures and technological maturity. While established financial hubs prioritize compliance and robust perimeter defense, emerging markets increasingly adopt cloud-native solutions for digital-first operations. This regional divergence shapes vendor strategies across the market.
United States
United States commercial banks drive strong demand for sophisticated fraud detection and identity management solutions. The U.S. SEC's cybersecurity disclosure rules mandate investments in robust compliance and reporting frameworks. New York City financial institutions accelerate the adoption of advanced security platforms.
British
British FinTech innovation and a mature financial sector fuel demand for cloud-based security and advanced threat intelligence. The GDPR and EU's DORA impose rigorous data protection and operational resilience standards. London's global financial hub attracts numerous cybersecurity vendors specializing in managed detection and response services.
German
German commercial banks prioritize robust network security and data loss prevention due to stringent national data protection requirements. The country's financial regulators emphasize sovereign cloud and data localization laws. Frankfurt's financial services sector invests in comprehensive risk management systems for operational resilience.
India
India experiences significant demand for payment processing security and mobile banking protections, driven by rapid digital adoption. The Reserve Bank of India (RBI) implements stringent cybersecurity guidelines for financial entities. Bangalore and Mumbai are developing advanced fraud detection capabilities.
Singapore
Singapore, as a premier financial hub, drives demand for sophisticated threat intelligence and risk management systems. The Monetary Authority of Singapore (MAS) enforces comprehensive technology risk management guidelines. The city-state’s digital innovation fosters advanced identity and access management solutions.
Banking Cyber Security Market Key Industry Players
Capability concentration sits with one tier of specialized cybersecurity firms, while scale advantage sits with another tier of diversified technology giants. The market structure exhibits a tiered consolidation, with large enterprises offering broad security platforms alongside agile specialists focusing on niche solutions. Strategic archetypes include comprehensive platform providers, cloud-native innovators, and managed security service specialists. Dominant competitive moves involve strategic partnerships for ecosystem expansion and continuous portfolio diversification to address evolving threats.
On the comprehensive platform vector, Fortinet, Cisco Systems, and Palo Alto Networks exemplify market leadership. These companies anchor the market for integrated security solutions, often blending hardware and software offerings. Cisco Systems leverages its extensive network infrastructure to embed security features directly into its core products. Palo Alto Networks occupies a position as a provider of a comprehensive platform spanning network, cloud, and security operations. Fortinet represents a strong presence in unified threat management and enterprise-grade security appliances, serving a broad customer base.
| Leading Market Players |
|---|
| Fortinet |
| Cisco Systems |
| Palo Alto Networks |
| Trellix |
| Rapid7 |
| CrowdStrike |
| Microsoft Security |
| IBM Security |
| Check Point Software Technologies |
| Others |
Cost & Logistics Intelligence
The global internet backbone's cost dynamics influence pricing differentiation for cloud-based cybersecurity services, impacting supply concentration among major hyperscale providers.
Pricing Analysis
Subscription-based pricing models dominate the banking cybersecurity market, reflecting a shift from traditional perpetual licenses. Customization levels for large commercial banks and after-sales managed services drive significant price differentiation. Pricing softness reflects intense competition among platform providers and the availability of open-source alternatives for basic functions. FinTech companies are typically more price-sensitive due to their agile operational models, while large commercial banks prioritize comprehensive features and robust service level agreements.
Supply Chain Analysis
Data sovereignty laws in India and China restrict the deployment of global cloud security services, creating localized supply chain complexities. The supply of advanced cybersecurity solutions relies heavily on skilled cybersecurity talent, secure global cloud infrastructure, and proprietary AI/ML algorithms. Geographic supply concentration includes the United States for software development, Ireland for EU data centers, and India for managed security services talent. Regulatory restrictions represent a critical structural risk, influencing where data can be processed and stored. Distribution runs through direct sales for large enterprises and cloud marketplaces for SaaS offerings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The banking cybersecurity market is currently in an early-cycle expansion phase, driven by the accelerating adoption of cloud-native security solutions across financial institutions.
For Market Incumbents:Entrench existing client relationships by integrating advanced AI-driven threat intelligence into core banking platforms. This counters the rapid innovation from digital-native FinTechs that target specific pain points. Incumbents should also pursue strategic acquisitions of niche cloud-native security specialists. Capacity additions in managed security services through talent development will reinforce market position against emerging threats.
For New Entrants and Emerging Players:Build out specialized security solutions targeting underserved segments like small credit unions and regional banks. North American regional banks represent a penetrable segment due to their limited in-house cybersecurity talent. Focus on subscription-based managed detection and response (MDR) services to offer cost-effective, scalable protection. This approach allows new entrants to gain market share by addressing specific compliance and resource constraints.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified technology giants seeking to divest non-core security assets. These opportunities offer strong long-term viability over the next five to ten years due to persistent threat landscapes. Focus on acquiring cloud-native endpoint protection providers or specialized fraud detection platforms with strong intellectual property. Increased M&A activity among smaller FinTech security vendors will signal market consolidation and mature investment prospects.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-driven Threat Intelligence Development | Enhances real-time detection capabilities against polymorphic malware. |
| Cloud-Native Platform Integration | Streamlines deployment and scalability for agile FinTech operations. |
| Managed Security Services Expansion | Addresses the cybersecurity talent shortage within financial institutions. |
| Zero Trust Architecture Adoption | Strengthens access controls and perimeter-less security for digital assets. |
| Regulatory Compliance Automation | Reduces manual effort and ensures adherence to evolving data protection laws. |
Research Approach
A spread of perspectives from Chief Information Security Officers, IT procurement heads, FinTech founders, and regulatory compliance officers converged on the working assumptions for this analysis. Primary interviews with these industry stakeholders were rigorously combined with secondary validation from SEC filings, RBI guidelines, and GDPR impact assessments. This approach incorporated both bottom-up market sizing and top-down validation against published financial industry reports, ensuring data robustness.
The demand-supply balance for banking cybersecurity solutions was modeled by assessing the evolving threat landscape against vendor capability development. This analytical framework projected market trajectory across the analysis window, segmenting by solution type, deployment model, customer type, application, and regional regulatory impact. Compound Annual Growth Rates were derived from historical growth trends and projected market drivers, including financial institution digital transformation rates and cyber insurance adoption.
Practitioners should monitor significant shifts in sovereign cloud requirements or the emergence of novel AI-driven attack vectors for early signals of market revision. Forecasts reflect current assumptions regarding regulatory stability and technological innovation, acknowledging potential impacts from unforeseen geopolitical events or rapid threat evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Cybersecurity in Gaming Market
Cybersecurity
Global Data Exfiltration Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Europe Software Defined Perimeter Market
Cybersecurity
Morocco Cybersecurity Market
Cybersecurity
Firewall-As-A-Service (Fwaas) Market
Cybersecurity
Cyber Deception Market
Cybersecurity
Netherlands Cybersecurity Market
Cybersecurity
Spear Phishing Solution Market
Cybersecurity
Turkey Cybersecurity Market
Cybersecurity
IoT Security Market
Cybersecurity
Kuwait Cybersecurity Market
Cybersecurity
Virtualization Security Tools Market
Cybersecurity
Europe Data Exfiltration Market
Cybersecurity
Cloud Authentication Market
Cybersecurity
Philippines Cybersecurity Market