
 India Communication Platform As a Service (Cpaas) Market | 2026-2036
India Communication Platform As a Service (Cpaas) Market Size, Share, and Industry Trends Forecast 2026-2036
India Communication Platform As a Service (Cpaas) Market Foresight
Platform licensing revenue is fragmenting across API monetization, managed services, and white-label infrastructure deployments. Tanla Platforms dominates domestic messaging aggregation with direct operator interconnects. Route Mobile sustains international voice termination dominance through carrier partnerships across the Middle East and Africa. Gupshup Technology anchors conversational commerce with its bot-builder ecosystem serving D2C brands.
Communication Platform as a Service denotes cloud-delivered middleware that exposes carrier-grade voice, messaging, and video capabilities through RESTful APIs and software development kits, typically processing millions of transactions via redundant data centers with sub-200-millisecond latency. The architecture enables enterprises to embed real-time communication into CRM, ERP, and mobile applications without owning telecom infrastructure. Public cloud deployments capture the majority of new workloads among mid-market retailers seeking elastic capacity during festive sales spikes. Voice API services retain the largest revenue pool though messaging APIs demonstrate the steepest growth trajectory among financial institutions implementing OTP and payment alert automation.
TRAI mandates sender ID registration and template-based content filtering under its distributed ledger technology framework for commercial communications. BIS cloud security guidelines and RBI's digital payment infrastructure directives shape data residency and encryption standards for financial services deployments. Stakeholders must monitor how the central bank's offline payment tokenization rules and anticipated data localization amendments alter API routing architectures and cross-border hosting strategies.
Market Dynamics
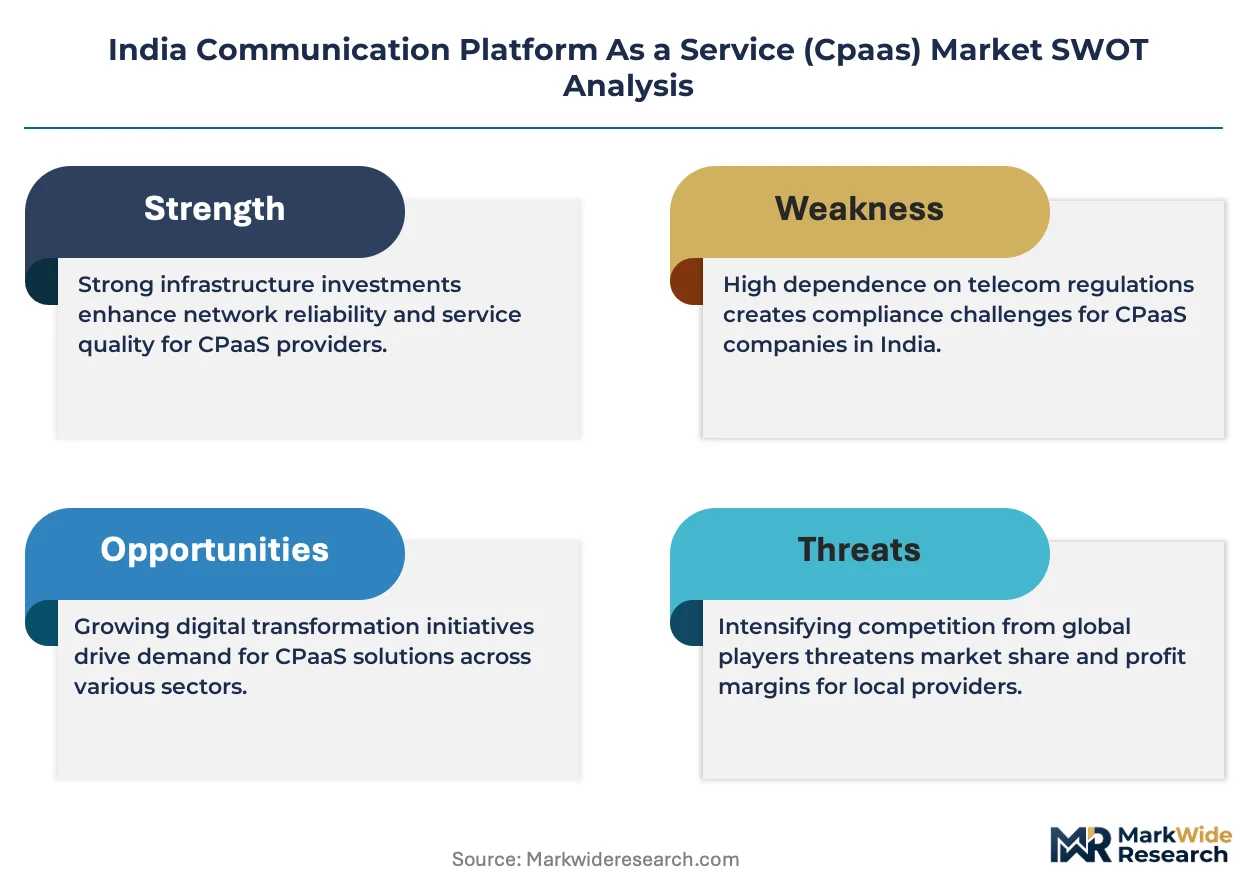
TRAI's distributed ledger mandate for commercial communications is forcing platform providers to re-architect routing infrastructure around template-based filtering and sender ID scrubbing, compressing margins for aggregators while elevating compliance-first vendors.
Growth Catalysts
- Video KYC automation:RBI's digital payment infrastructure directives mandate biometric verification for remote account opening, driving API consumption by banks and NBFCs seeking sub-200-millisecond latency guarantees.
- TRAI's blockchain scrubbing framework:Distributed ledger technology for bulk SMS verification creates captive demand for platforms with direct operator interconnects and real-time template validation.
- Maharashtra-Karnataka-Telangana cluster density:Fintech headquarters concentration in Mumbai, Bangalore, and Hyderabad generates localized API consumption spikes during festive commerce cycles.
Market Restraints
- Data localization hardware costs:RBI's encryption and residency requirements force redundant data center deployment, elevating capex intensity for cross-border platform operators.
- Operator interconnect concentration:Domestic messaging aggregation depends on direct relationships with Bharti Airtel, Jio, and Vodafone Idea, creating single-point-of-failure exposure in tier-2 cities.
- OTT messaging substitution:WhatsApp Business API and RCS messaging displace traditional SMS for promotional campaigns among D2C brands with sub-50,000 customer bases.
Strategic Opportunities
- Conversational commerce AI convergence:Bot-builder ecosystems integrating natural language processing with payment APIs capture wallet share from retailers seeking unified customer service and checkout flows.
- Telangana's emerging SaaS corridor:Hyderabad's Gachibowli and Hitech City districts host underpenetrated mid-market enterprises migrating from on-premise contact centers to elastic cloud capacity.
- BIS cloud security certification tailwind:Mandatory security guidelines for financial services cloud deployments create compliance-based differentiation for platforms with pre-certified infrastructure stacks.
Industry Challenges
- DevOps-telecom skill hybridization:Platform engineering teams require rare combinations of RESTful API architecture expertise and SS7/SIGTRAN protocol knowledge, elongating hiring cycles in Bangalore and Pune.
- Legacy CRM integration friction:Enterprise deployments face middleware complexity connecting modern CPaaS stacks to decade-old SAP and Oracle systems common in Mumbai's manufacturing conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Communication Platform As a Service (Cpaas) Market |
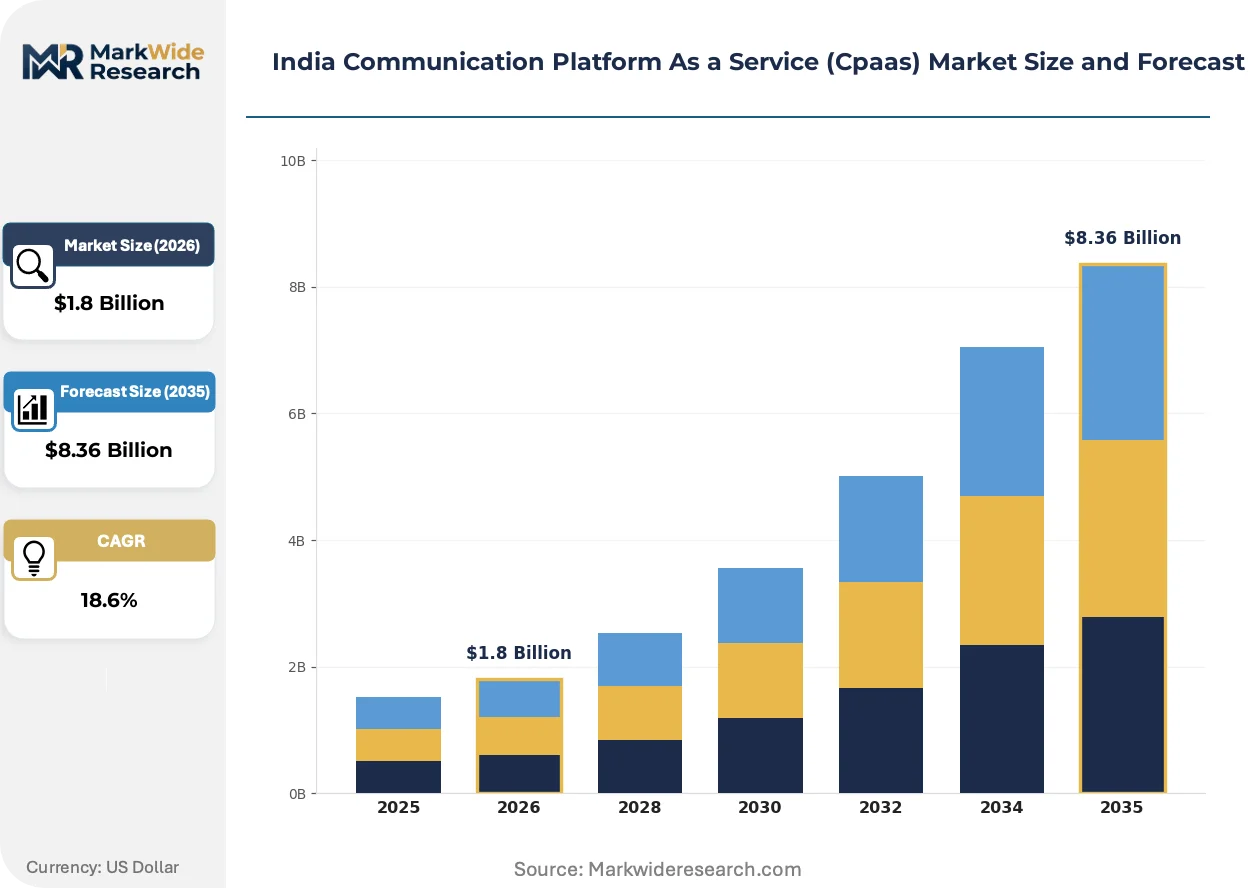
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises Service Type: Voice API, Messaging API, Video API, Authentication API End User: Healthcare Providers, Financial Institutions, Retailers, Telecom Operators Pricing Strategy: Pay-as-you-go, Subscription-based, Free Tier, Enterprise Plans |
| Companies Covered | Tanla Platforms Limited, Route Mobile Limited, Gupshup Technology India Private Limited, Twilio Inc., Infobip Ltd., Exotel, Pulse Telesystems, Tata Communications, Netcore Cloud, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Communication Platform As a Service (Cpaas) Market Shifts & Advancements
Artificial intelligence and edge computing architectures are compressing the traditional separation between communication infrastructure and application logic, enabling real-time personalization that was previously confined to hyperscaler environments.
Containerized microservices for voice processing are virtualizing the traditional hardware-dependent session border controller stack. Mid-market retailers deploying elastic capacity during Diwali and Republic Day sales cycles adopt Kubernetes-orchestrated voice APIs to avoid stranded infrastructure investments. This shift is virtualizing the capital expenditure model that previously locked smaller competitors out of carrier-grade telephony.
TRAI's phased implementation of distributed ledger technology for commercial communications imposes template pre-registration and dynamic scrubbing on all bulk messaging flows. Financial institutions consuming OTP and payment alert APIs must now integrate real-time validation hooks, increasing engineering overhead but reducing fraud vectors. Banks in Maharashtra and Karnataka are responding by consolidating vendor relationships around platforms with native blockchain verification layers.
Enterprise procurement of communication infrastructure is fragmenting from monolithic annual contracts toward consumption-based metering tied to transaction volumes. System integrators and ISVs are displacing traditional direct sales relationships as the primary channel for mid-market customer acquisition. This pattern concentrates in Bangalore's software exporter ecosystem, where IT services firms bundle CPaaS APIs into broader digital transformation engagements.
India Communication Platform As a Service (Cpaas) Market Segmentation
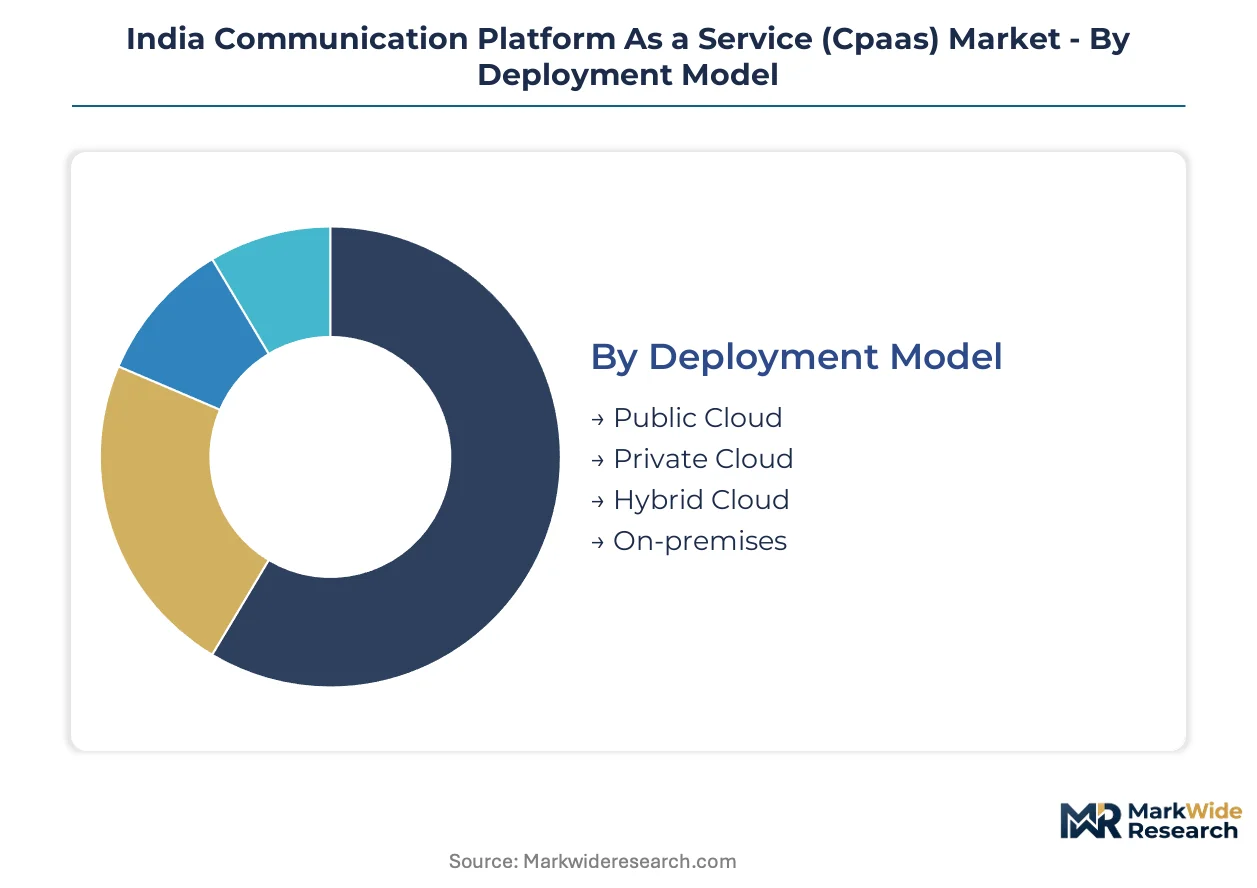
Segmentation in the India CPaaS market exposes divergent infrastructure requirements across regulated industries and deployment preferences. Financial institutions and healthcare providers impose distinct compliance burdens that reshape platform architecture choices. Understanding these fault lines clarifies where API consumption concentrates and which pricing models capture enterprise versus mid-market spend.
Deployment Model:
Public cloud deployments turn over fastest during festive commerce spikes, while on-premises installations cycle slowest due to hardware procurement timelines and BIS certification requirements.
- Public Cloud:Elastic capacity provisioning via hyperscaler infrastructure supports Mumbai and Bangalore retailers during Diwali transaction surges. Maharashtra fintech clusters favor this model for sub-200-millisecond latency guarantees without stranded capital.
- Private Cloud:Dedicated single-tenant environments isolate sensitive workloads for Hyderabad pharmaceutical companies and Chennai manufacturing conglomerates navigating RBI data residency directives. Capex intensity runs higher but satisfies auditor scrutiny.
- Hybrid Cloud:Split architectures route transactional SMS through public pipes while retaining voice recordings in private stacks. Delhi-NCR enterprises adopt this pattern to balance cost elasticity against litigation hold requirements.
- On-premises:Fully captive infrastructure persists among Pune defense contractors and Kochi port authorities with air-gapped security mandates. Procurement cycles stretch 18-24 months due to CDSCO and BIS hardware clearances.
Public cloud anchors the volume base while hybrid cloud gains share at the steepest rate as regulated enterprises seek compromise positions between agility and compliance.
Service Type:
Cost tier differentiation separates commodity messaging from premium video APIs, with authentication services commanding the highest per-transaction pricing due to fraud liability exposure.
- Voice API:Carrier-grade telephony exposed through RESTful endpoints enables interactive voice response for Bangalore contact centers and Pune NBFC collections operations. Latency sensitivity drives demand for direct operator interconnects with Bharti Airtel and Jio.
- Messaging API:Template-scrubbed SMS and RCS flows process OTP and payment alerts for Maharashtra banking networks under TRAI's distributed ledger framework. Volume concentration here exceeds all other service categories combined.
- Video API:WebRTC-based real-time communication supports remote KYC verification mandated by RBI for account opening. Telangana and Karnataka banks consume these APIs to satisfy biometric capture requirements without branch infrastructure.
- Authentication API:Multi-factor verification combining SMS OTP, voice fallback, and push notifications protects high-value transactions. Premium pricing reflects fraud indemnification and SEBI-mandated security standards for securities trading platforms.
Messaging API anchors the volume base while video API climbs the fastest as RBI's digital payment infrastructure directives harden biometric verification requirements.
End User:
Application-specific requirements fragment procurement patterns, with financial institutions prioritizing audit trails while retailers optimize for conversion funnel integration.
- Healthcare Providers:Appointment reminders, telemedicine consultation links, and prescription alerts flow through HIPAA-aligned messaging stacks. CDSCO oversight of clinical communication imposes template pre-registration burdens distinct from commercial messaging rules.
- Financial Institutions:Transaction notifications, fraud alerts, and video KYC sessions dominate API consumption. RBI's offline payment tokenization rules and data localization amendments force continuous re-architecture of routing logic.
- Retailers:Promotional campaigns and order tracking messages drive seasonal volume spikes. D2C brands in Bangalore and Delhi shift from traditional SMS to WhatsApp Business API for sub-50,000 customer bases.
- Telecom Operators:Wholesale voice termination and messaging aggregation services leverage direct interconnects. Route Mobile and Tanla Platforms compete for carrier partnership slots across Middle East and Africa corridors.
Financial institutions anchor the volume base while healthcare providers are expanding most quickly as CDSCO telemedicine guidelines mature.
Pricing Strategy:
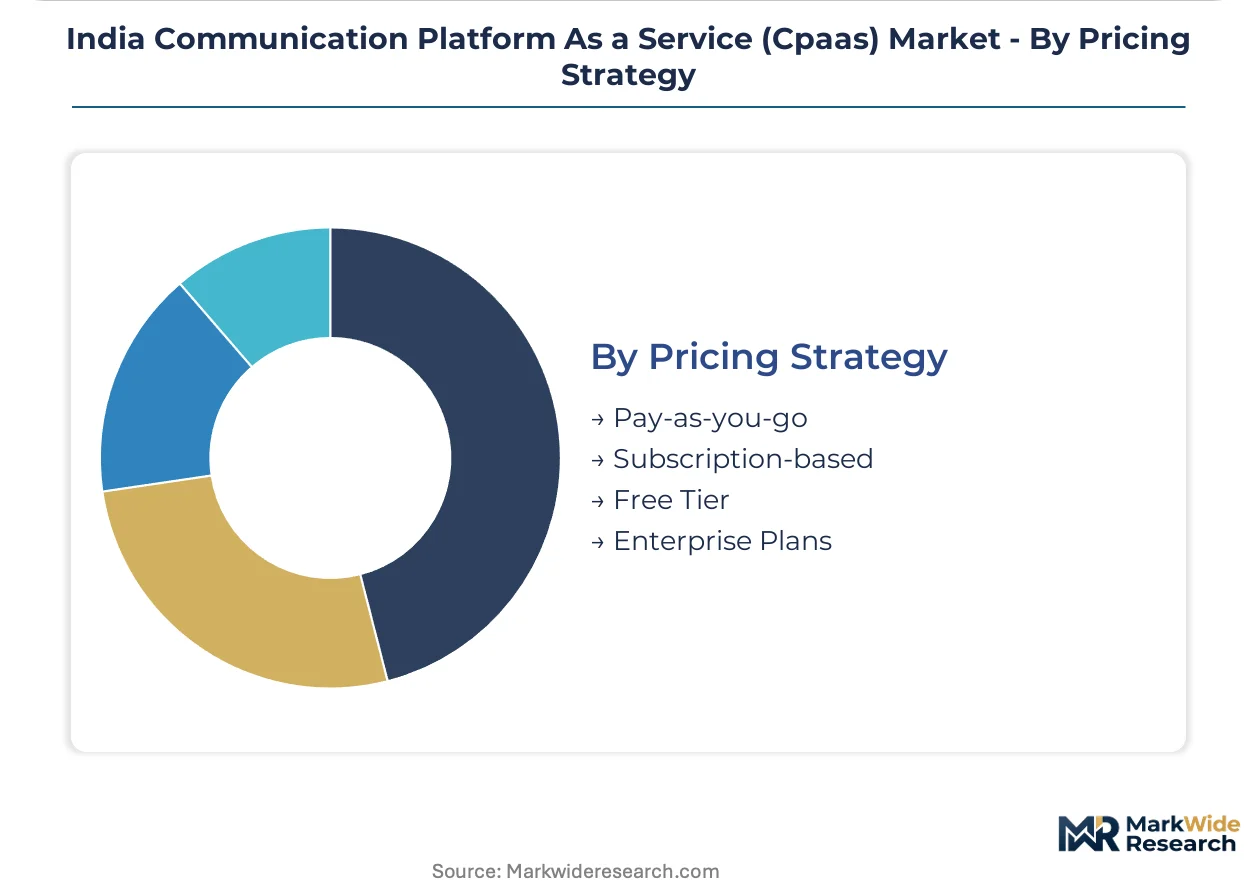
Customer type and transaction predictability determine model selection, with enterprise plans capturing committed spend from conglomerates and pay-as-you-go serving experimental deployments.
- Pay-as-you-go:Metered consumption without minimum commitments suits Bangalore SaaS startups and Chennai e-commerce ventures testing CPaaS integration. Variable costs align with venture-funded growth curves.
- Subscription-based:Fixed monthly fees for bundled API volumes attract Mumbai mid-market retailers with predictable seasonal patterns. Discounted per-unit rates reward volume commitment.
- Free Tier:Limited-volume developer access seeds ecosystem adoption. Gupshup Technology and competitor bot-builder platforms use this hook to capture D2C brand experimentation before scaling to paid conversational commerce features.
- Enterprise Plans:Custom-negotiated contracts with dedicated support and SLA guarantees lock in HDFC Bank, ICICI, and similar institutions. Multi-year terms include price protection and priority capacity allocation during infrastructure stress.
Enterprise plans anchor the volume base while pay-as-you-go shows the steepest expansion trajectory as cloud-native startups proliferate across Telangana's emerging SaaS corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure concentrates in three southern and western states where fintech headquarters and enterprise IT operations cluster. API consumption patterns track closely to state-level digital payment penetration and banking license density.
Maharashtra
Mumbai's financial district generates the heaviest transactional messaging volumes as HDFC Bank, ICICI Bank, and Axis Bank route OTP flows through local data centers. TRAI's distributed ledger mandate for commercial communications forces template pre-registration through Maharashtra-registered aggregators. The Mumbai-Pune corridor hosts the densest concentration of enterprise contact centers migrating from legacy PBX systems to cloud voice APIs.
Karnataka
Bangalore's software exporter ecosystem bundles CPaaS APIs into digital transformation contracts for mid-market retailers. RBI's video KYC directives drive biometric verification API consumption among neobanks headquartered in Koramangala and Indiranagar. The city's Kubernetes-orchestrated voice deployments spike 400% during Diwali sales cycles as e-commerce platforms elasticize capacity.
Telangana
Hyderabad's Gachibowli and Hitech City districts shelter underpenetrated mid-market enterprises abandoning on-premise infrastructure. BIS cloud security certification requirements filter vendor selection for pharmaceutical companies in Genome Valley seeking HIPAA-aligned messaging stacks. The state's emerging SaaS corridor attracts consumption-based metering models from API-first platforms.
Delhi-NCR
Gurgaon and Noida host manufacturing conglomerates deploying hybrid cloud architectures to balance cost elasticity against litigation hold requirements. CDSCO oversight of clinical communication imposes template burdens distinct from TRAI's commercial messaging rules on healthcare providers in Faridabad. Defense contractors in Delhi maintain air-gapped on-premise installations with 18-24 month procurement cycles.
Tamil Nadu
Chennai's automotive and electronics manufacturing base consumes authentication APIs for supply chain verification under SEBI-mandated security standards. The city's SaaS startups favor pay-as-you-go metering without minimum commitments during venture-funded growth phases. Coimbatore's textile exporters adopt WhatsApp Business API for sub-50,000 customer bases, displacing traditional SMS promotional flows.
India Communication Platform As a Service (Cpaas) Market Competitive Landscape
Domestic messaging aggregators and international API platforms split the market along regulatory compliance and global scale vectors. Direct operator interconnects with Bharti Airtel, Jio, and Vodafone Idea create defensive moats for India-based players, while cross-border voice termination relationships favor carriers with Middle East and Africa corridor presence. Three archetypes dominate: compliance-first domestic aggregators, global API hyperscalers, and conversational commerce specialists. Consolidation pressure intensifies through strategic partnerships between banks and pre-certified infrastructure providers, plus vertical integration into managed services and white-label deployments.
Within the domestic aggregator tier, Tanla Platforms and Route Mobile anchor platform licensing revenue across API monetization and managed services. Gupshup Technology occupies the conversational commerce vector, exemplifying bot-builder ecosystem strategies that capture D2C brand experimentation before scaling to paid features. These three represent distinct competitive positions: Tanla leverages direct operator interconnects, Route sustains international voice dominance, and Gupshup anchors natural language processing integration with payment flows.
| Leading Market Players |
|---|
| Tanla Platforms Limited |
| Route Mobile Limited |
| Gupshup Technology India Private Limited |
| Twilio Inc. |
| Infobip Ltd. |
| Exotel |
| Pulse Telesystems |
| Tata Communications |
| Netcore Cloud |
| Others |
Supply & Pricing Matrix
Mumbai-JNPT port freight corridors anchor cost dynamics for hardware-dependent private cloud deployments, compressing margins for cross-border platform operators while amplifying price differentiation between domestic aggregators with direct operator interconnects and international hyperscalers bearing redundant data center capex.
Pricing Analysis
TRAI's distributed ledger mandate for commercial communications dictates the pricing tier structure across the India CPaaS landscape. Three-tier pricing structure across enterprise plans, subscription-based bundles, and pay-as-you-go metering separates committed volume buyers from experimental startups. Price differentiation rests on BIS cloud security certification status and direct operator interconnect relationships with Bharti Airtel, Jio, and Vodafone Idea. Cost compression in the messaging aggregation tier is intensifying because template pre-registration engineering overhead elevates compliance costs. SaaS startups in Bangalore exhibit highest price sensitivity, while HDFC Bank and ICICI lock in multi-year enterprise plans with SLA guarantees.
Supply Chain Analysis
Single-source vulnerability in domestic operator interconnects dominates supply chain risk architecture for India CPaaS providers. Hardware supply draws from Taiwan for server components, China for networking equipment, and USA for specialized encryption modules. Redundant data center deployment hinges on real estate availability in Maharashtra, Karnataka, and Telangana. Distribution runs through system integrators and ISVs displacing traditional direct sales relationships, with Bangalore software exporters bundling APIs into broader digital transformation engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Maharashtra and Karnataka banking networks consolidating vendor relationships around pre-certified infrastructure providers, fragmenting procurement patterns and elevating compliance-first platforms over pure-play aggregators.
For Market Incumbents: Entrench defensive positioning through backward integration into managed services and white-label infrastructure deployments. Deepen direct operator interconnects with Bharti Airtel, Jio, and Vodafone Idea to create captive capacity allocation during festive commerce spikes. Counter WhatsApp Business API substitution threat by embedding conversational AI capabilities before D2C brands migrate promotional flows. For New Entrants and Emerging Players: Mid-market enterprises in Hyderabad's Gachibowli and Hitech City districts represent the most penetrable entry point, with underpenetrated contact centers abandoning on-premise PBX systems for elastic cloud capacity. Target consumption-based metering models that align with venture-funded SaaS startup growth curves. Lead with Kubernetes-orchestrated voice APIs to avoid stranded infrastructure investments during Diwali transaction surges. For Investors and Strategic Acquirers: Compliance-first domestic aggregators with native blockchain verification layers and BIS pre-certified infrastructure stacks offer superior long-term viability through regulatory tightening windows. Monitor TRAI's anticipated data localization amendments as the critical inflection signal for cross-border hosting strategy viability. Material shifts in RBI offline payment tokenization rules would require updated calibration of platform routing architecture valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Operator Interconnect Expansion | Captive capacity allocation with Bharti Airtel, Jio, and Vodafone Idea hardens defensive moats during infrastructure stress. |
| Native Blockchain Verification Layer Development | Real-time template validation under TRAI's distributed ledger mandate reduces fraud vectors for Maharashtra banking networks. |
| Conversational Commerce AI Convergence | Bot-builder ecosystems integrating natural language processing with payment APIs capture unified customer service and checkout flows. |
| BIS Cloud Security Certification Investment | Pre-certified infrastructure stacks create compliance-based differentiation for financial services deployments. |
| Kubernetes-Orchestrated Voice API Deployment | Containerized microservices virtualize session border controller capital expenditure for mid-market retailers. |
Research Methodology
Desk research of TRAI regulatory filings, RBI digital payment infrastructure directives, BIS cloud security guidelines, and hyperscaler capex disclosures preceded structured interviews with platform engineering heads, API product managers, bank digital transformation leads, NBFC collections operations directors, and system integrator partnership executives. Primary fieldwork combined with secondary validation across SEC filings of listed aggregators, telecom operator interconnect agreements, and CDSCO telemedicine communication standards. Bottom-up transaction volume modeling triangulated against top-down market sizing from fintech cluster density analysis.
Forecasts hold constant TRAI's phased distributed ledger implementation timeline and RBI's current data residency requirements while varying adoption curves across public, private, hybrid, and on-premises deployment models. Segmentation dimensions include service type, end-user vertical, pricing strategy, and state-level fintech headquarters concentration. CAGRs derive from elasticity modeling of festive commerce spikes and biometric verification API consumption patterns. Voice API latency benchmarks and messaging template scrubbing compliance rates serve as industry-specific forecast inputs across the projection horizon.
Practitioners should monitor TRAI data localization amendment proposals and RBI offline payment tokenization rule refinements for early signals of routing architecture disruption. Forecasts reflect assumptions regarding regulatory implementation timelines and operator interconnect stability. Material shifts in BIS cloud security certification requirements or CDSCO clinical communication template rules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Video Conferencing Market
Communication Services
Web Conferencing Market
Communication Services
Industrial Communication Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Global Critical Communication Market
Communication Services
Managed Communication Services Market
Communication Services
Latin America Postal Service Market
Communication Services
Consumer Communication Services Market
Communication Services
Dispatch Console Market
Communication Services
Speech to Speech Translation Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Voip Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Enterprise Communication Infrastructure Market