
 Bromine Market | 2026-2036
Bromine Market Size, Share, and Industry Trends Forecast 2026-2036
Bromine Market Intelligence
A transition from multi-source procurement to single-source, long-term contracts for high-purity bromine is shifting competitive dynamics. This change favors large-scale producers with consistent output and quality control. For instance, ICL Group Ltd. leverages its access to Dead Sea brine, a major natural source of bromine. LANXESS specializes in bromine derivatives and flame retardants for specialized industrial applications. Albemarle Corporation sustains its market position through extensive production capacity and a global distribution network.
Bromine is a halogen element, existing as a fuming reddish-brown liquid at room temperature, and is highly reactive. Its primary industrial purpose lies in creating organobromine compounds used as intermediates and end products across various sectors. While brominated flame retardants for the electronics industry constitute a major demand segment, the use of bromine compounds in pharmaceutical synthesis is expanding rapidly. Application in oilfield drilling fluids remains a mature but high-volume category, critical for pressure control in deep wells.
Regulatory frameworks significantly influence market access and product formulation. The EU's REACH and RoHS directives restrict the use of certain brominated flame retardants, pushing innovation toward compliant alternatives. In parallel, China's MEE enforces stringent environmental standards on bromine production and wastewater discharge. Stakeholder decisions will hinge on navigating these divergent environmental regulations while securing stable supply from geographically concentrated sources.
Market Dynamics
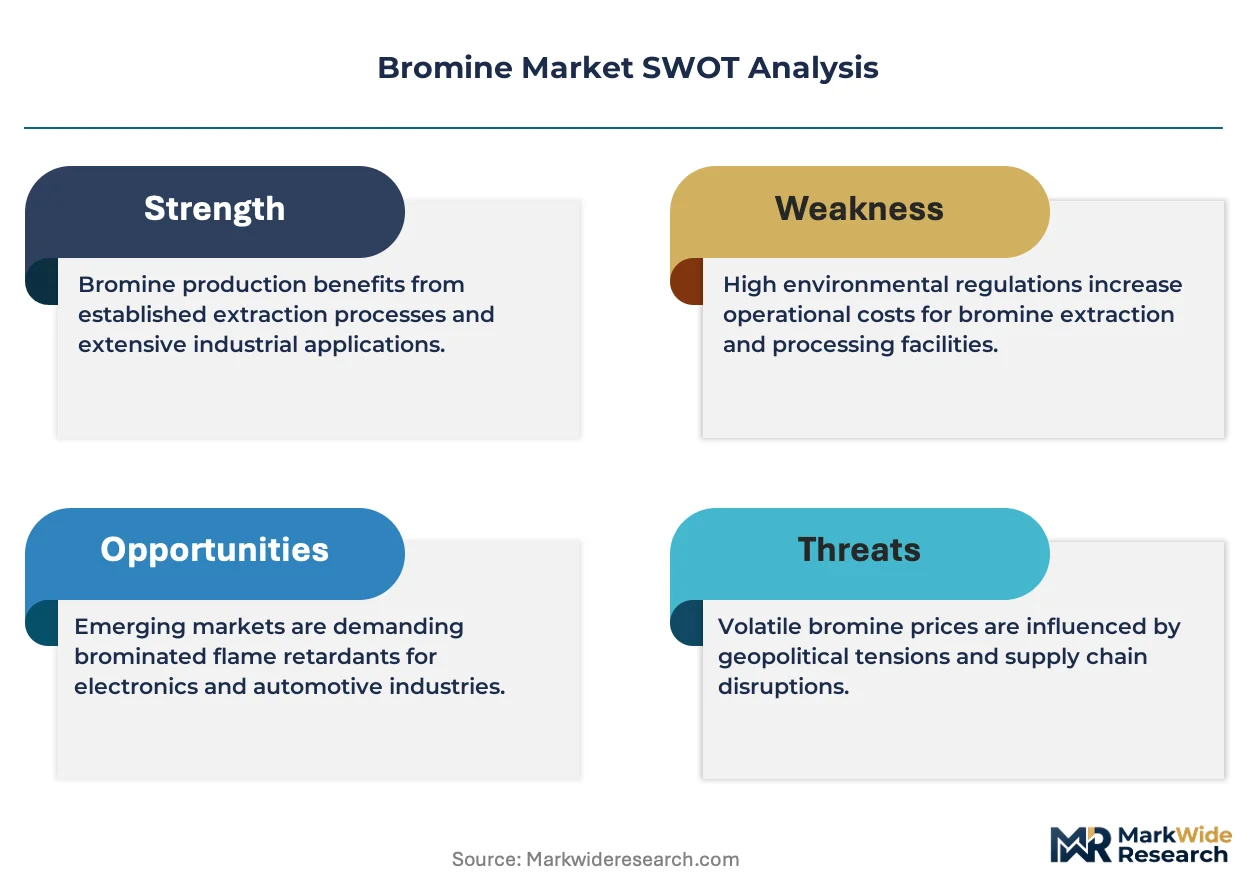
The central tension in the bromine market stems from the geographic concentration of supply, primarily from Dead Sea brine, clashing with increasingly divergent and stringent environmental regulations across key consumer markets like China and the European Union.
Growth Catalysts
- Fire Safety Regulations:Stricter mandates for fire safety in construction materials and consumer electronics globally are driving the use of brominated flame retardants to meet compliance standards.
- Oil and Gas Exploration:The demand for calcium bromide, sodium bromide, and zinc bromide fluids for controlling pressure in deep-sea and high-pressure oil and gas wells remains a significant volume driver.
- Chemical Synthesis in China:China's vast chemical industry consumes large volumes of bromine as a key raw material and intermediate for producing a wide array of downstream products, from agrochemicals to pharmaceuticals.
Market Restraints
- Regulatory Scrutiny:Environmental and health regulations, such as the EU's REACH and RoHS directives, restrict or ban certain brominated flame retardants, compelling reformulation and product replacement.
- Substitution with Alternatives:In applications like electronics and textiles, a persistent threat comes from non-halogenated alternatives, including phosphorus-based compounds and mineral-based flame retardants.
- Supply Source Concentration:Heavy reliance on brine from a few locations, notably the Dead Sea, creates vulnerability to geopolitical instability, logistical disruptions, and production fluctuations in that region.
Strategic Opportunities
- Pharmaceutical Intermediates:The expanding role of organobromine compounds as reagents and building blocks in the synthesis of active pharmaceutical ingredients (APIs) presents a high-value growth avenue.
- Energy Storage Systems:Bromine's application in flow batteries, such as zinc-bromine and vanadium-bromine systems, offers a new frontier for growth as demand for grid-scale energy storage increases.
- Water Treatment and Biocides:Growing global water scarcity and stricter sanitation standards are increasing the use of bromine-based biocides for industrial water purification, cooling towers, and desalination plants.
Industry Challenges
- Capital-Intensive Extraction:The development and maintenance of bromine extraction facilities, which require specialized, corrosion-resistant equipment for handling brine, demand significant upfront capital investment.
- Hazardous Material Logistics:Transporting elemental bromine, a highly corrosive and toxic substance, involves complex and costly logistics governed by stringent international and national hazardous materials regulations.
- Divergent Compliance Pathways:Producers must navigate a complex web of differing environmental standards, such as China's MEE wastewater rules versus the EU's ECHA chemical registration, increasing compliance costs and time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromine Market |
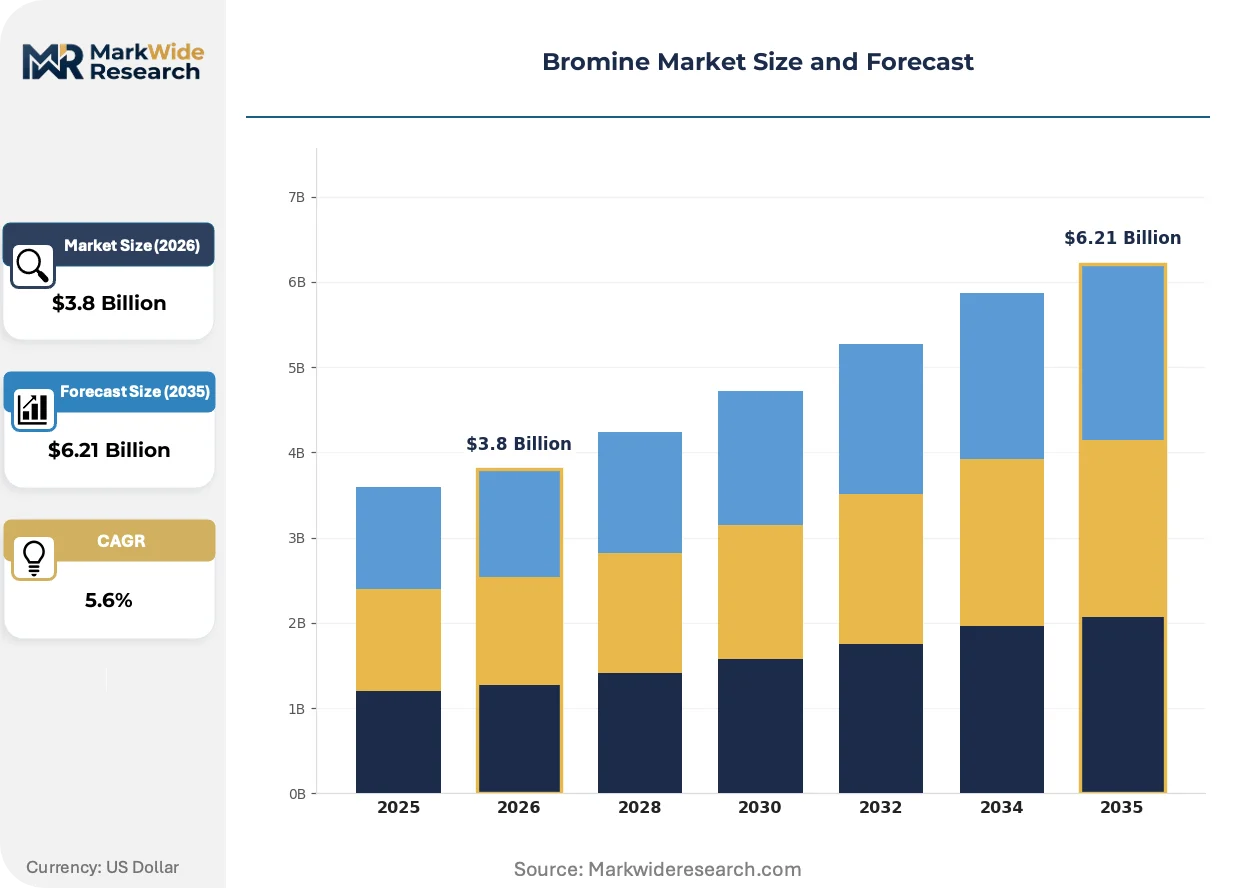
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Bromine, Bromine Compounds, Brominated Flame Retardants, Potassium Bromide, Others Application: Water Treatment, Pharmaceutical Synthesis, Agricultural Chemicals, Oilfield Drilling Fluids, Photographic Chemicals, Dye Manufacturing Production Method: Inorganic Process, Organic Process, Extraction from Seawater, Chemical Synthesis End User Industry: Chemical Manufacturing, Pharmaceutical Formulation, Agriculture, Oil & Gas Exploration, Electronics Production |
| Companies Covered | Albemarle Corporation, ICL Group Ltd., LANXESS, Jordan Bromine Company, Tosoh Corporation, Gulf Resources Inc., TETRA Technologies Inc., Tata Chemicals Ltd., Hindustan Salts Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromine Market Strategic Shifts & Innovations
Innovation in the bromine market is defined by a push toward higher-performance, environmentally acceptable compounds. This evolution is a direct response to divergent regulatory pressures and a demand-side shift favoring supply chain security over spot-market pricing.
Polymeric flame retardants represent a significant product evolution. These are large molecules where bromine is chemically bonded within a polymer structure, preventing it from leaching into the environment. The electronics and building materials sectors are steadily adopting these materials to meet stricter environmental health standards. This technology is integrating superior fire safety with improved environmental profiles, systematically replacing older additive-type flame retardants.
China's Ministry of Ecology and Environment (MEE) has enacted rigorous new standards impacting the entire bromine production lifecycle. These rules impose strict limits on wastewater discharge and air emissions, forcing producers to invest in costly pollution abatement and recycling technologies. The nation's domestic chemical manufacturing sector is most affected, leading to a consolidation of the market as smaller firms unable to meet the high capital costs for compliance are forced to exit.
A clear behavioral change in procurement is evident as major consumers move toward single-supplier, multi-year contracts. This model is supplanting traditional purchasing on the volatile spot market, as buyers in critical industries prioritize supply stability and consistent quality. This trend is most pronounced in the pharmaceutical and specialty electronics industries, where material traceability and unwavering purity are essential for final product integrity.
Bromine Market Segmentation
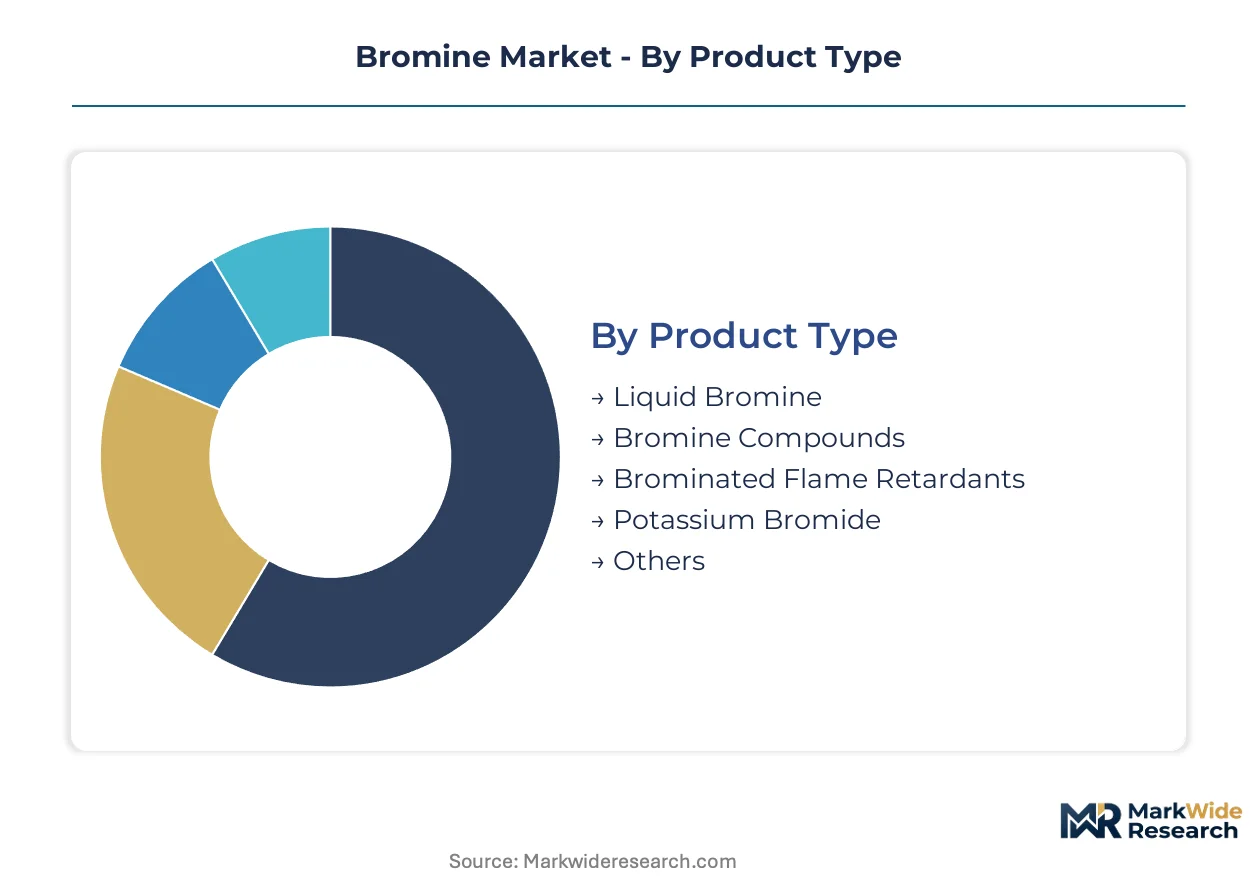
The bromine market's segmentation highlights the distinct drivers and applications shaping demand across various product forms and end-use sectors. Understanding these segments is crucial for identifying areas of sustained growth and pinpointing where regulatory shifts or technological advancements are creating new opportunities.
Product Type:
The segmentation by product type highlights the ongoing evolution from foundational bromine forms to specialized derivatives, driven by performance demands and regulatory shifts.
- Brominated Flame Retardants:These compounds are integrated into materials to inhibit or delay the spread of fire, finding primary application in electronics and construction to meet increasingly stringent global fire safety regulations. Innovation in this segment focuses on polymeric forms that offer improved environmental profiles.
- Bromine Compounds:This broad category encompasses various inorganic and organic bromine derivatives, serving as intermediates in chemical synthesis for a wide range of downstream products, with significant demand originating from China's chemical manufacturing industry.
- Liquid Bromine:Elemental bromine exists as a fuming reddish-brown liquid at room temperature, primarily utilized as a raw material for producing its various compounds and derivatives.
- Potassium Bromide:This inorganic salt is employed in various applications, including pharmaceutical formulations as a sedative, and in photographic processing.
- Others:This segment includes less common or niche bromine products and specialized derivatives used in specific industrial processes.
Volume placements concentrate in Bromine Compounds; the faster expansion belongs to Brominated Flame Retardants.
Application:
Application segmentation reveals the diverse utility of bromine across industrial processes, each with distinct performance requirements.
- Oilfield Drilling Fluids:Bromine compounds like calcium bromide, sodium bromide, and zinc bromide are critical components in completion and workover fluids, used to control pressure in deep-sea and high-pressure oil and gas wells. These fluids are essential for safe and efficient drilling operations.
- Pharmaceutical Synthesis:Organobromine compounds serve as vital reagents and building blocks in the synthesis of active pharmaceutical ingredients (APIs), facilitating the creation of complex molecular structures for new drug development. This application area is expanding due to increasing pharmaceutical research.
- Water Treatment:Bromine-based biocides are used for industrial water purification, cooling towers, and desalination plants, providing effective disinfection against a broad spectrum of microorganisms.
- Agricultural Chemicals:Bromine derivatives are utilized in the production of fumigants, pesticides, and herbicides, protecting crops and enhancing agricultural productivity.
- Photographic Chemicals:Bromine compounds, particularly silver bromide, historically played a central role in traditional photographic film and paper development due to their light-sensitive properties.
- Dye Manufacturing:Bromine is incorporated into certain dyes to achieve specific colors and improve colorfastness in textile and pigment production.
High-volume demand remains with Oilfield Drilling Fluids, while Pharmaceutical Synthesis is gaining share fastest.
Production Method:
The market's production method segmentation reflects varying levels of technological maturity and resource dependency for bromine extraction.
- Extraction from Seawater:This method involves extracting bromine from natural brine sources, primarily the Dead Sea, leveraging its high bromine concentration for large-scale production by companies like ICL Group Ltd.
- Inorganic Process:This traditional method involves chemical reactions to produce bromine compounds from various inorganic raw materials, often used for specific derivative production.
- Organic Process:The organic process focuses on synthesizing bromine derivatives through reactions involving organic precursors, allowing for the creation of complex organobromine compounds.
- Chemical Synthesis:This method encompasses the controlled laboratory or industrial creation of bromine compounds through specific chemical reactions, often for high-purity or specialized products.
Extraction from Seawater provides the largest supply volumes, with Chemical Synthesis showing a steeper expansion trajectory for specialized needs.
End User Industry:
End user industry segmentation illustrates how concentrated supply chains meet varied industrial requirements for bromine-derived products.
- Chemical Manufacturing:This industry represents the largest consumer of bromine, utilizing it as a foundational raw material and intermediate for producing a vast array of chemicals, including agrochemicals and specialty chemicals, particularly in China.
- Oil & Gas Exploration:The sector relies heavily on bromine compounds for drilling fluids, which are essential for pressure control and well integrity in challenging deep-well environments.
- Pharmaceutical Formulation:Bromine compounds are crucial for synthesizing active pharmaceutical ingredients (APIs) and other excipients used in drug development and manufacturing.
- Electronics Production:Brominated flame retardants are incorporated into electronic components and casings to enhance fire safety, meeting regulatory standards for consumer electronics.
- Agriculture:The agricultural sector uses bromine in the formulation of pesticides, herbicides, and soil fumigants to protect crops from pests and diseases.
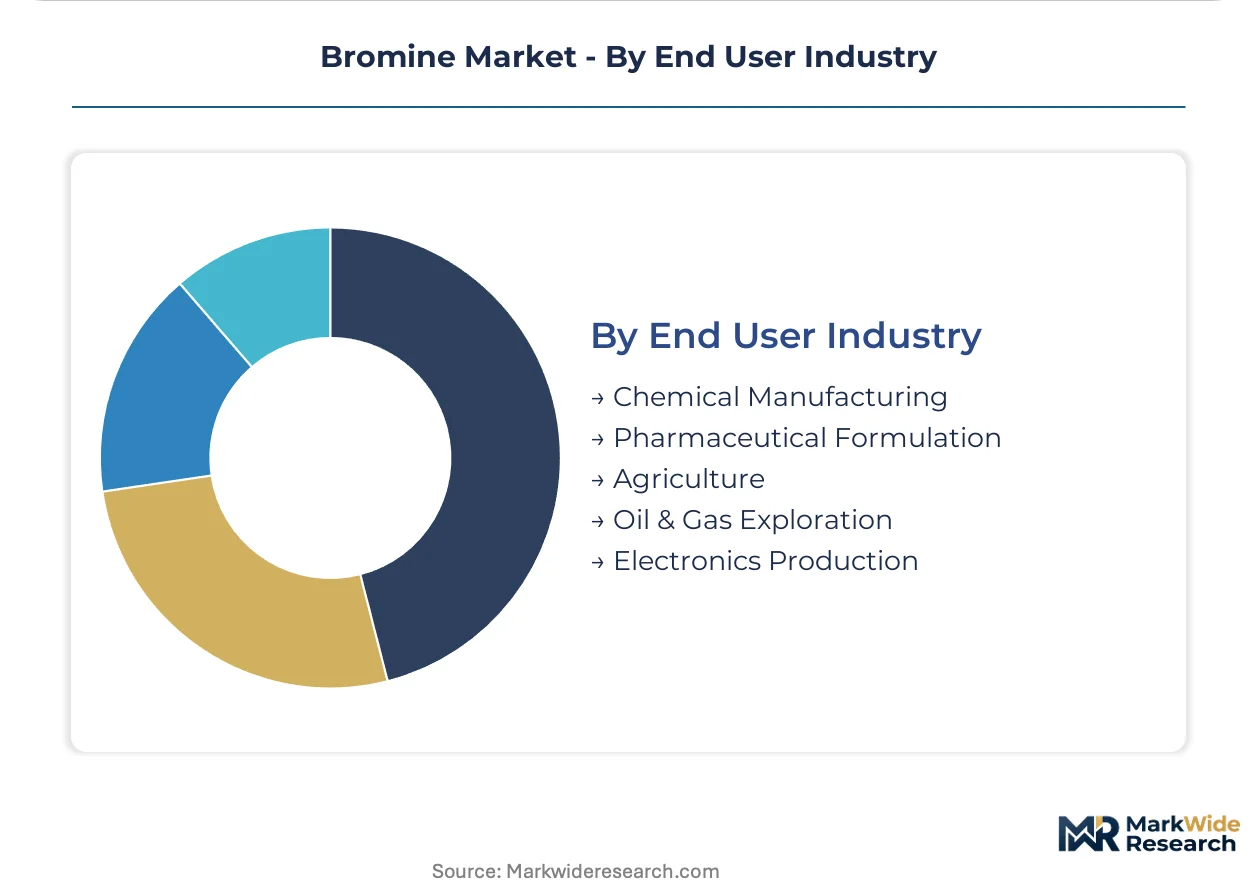
Chemical Manufacturing absorbs the largest volumes of bromine, and Pharmaceutical Formulation exhibits robust growth for high-purity grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for bromine compounds is evident across key industrial hubs, creating distinct regional market dynamics. Geographically concentrated supply sources, such as the Dead Sea, serve a diverse global application base. Navigating varied environmental regulations in major consumer markets like China and the European Union remains a central challenge for producers.
China
China's chemical manufacturing industry drives substantial bromine consumption for agrochemicals and specialty chemicals. The Ministry of Ecology and Environment (MEE) enforces stringent environmental standards on bromine production and wastewater discharge. The Yangtze River Delta region, a major chemical production cluster, sees significant investment in pollution abatement technologies.
United States
Demand for oilfield drilling fluids, particularly calcium bromide and zinc bromide, remains high in the United States for deep-well operations. The Environmental Protection Agency (EPA) regulates the use and disposal of industrial chemicals, including bromine compounds. The Gulf Coast petrochemical industry continues to rely on bromine intermediates for various downstream products.
Germany
European regulatory frameworks, including ECHA's REACH and RoHS directives, influence bromine use in Germany, particularly for flame retardants. Innovation focuses on polymeric flame retardants to meet stricter environmental profiles in electronics and construction. The Rhine-Ruhr chemical park is a hub for developing and adopting these advanced material solutions.
Israel
Access to Dead Sea brine makes Israel a critical global source of elemental bromine, supporting large-scale production. Environmental protection laws govern the sustainable extraction and processing of these natural resources. The Dead Sea region hosts primary producers like ICL Group Ltd., leveraging its unique geological advantage for consistent supply.
India
India's expanding pharmaceutical sector increasingly demands organobromine compounds for active pharmaceutical ingredient (API) synthesis. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical products, including bromine derivatives. The Gujarat chemical industry is a significant consumer, contributing to the nation's growing pharmaceutical manufacturing base.
Bromine Market Key Industry Players
Capacity expansion dominates the current competitive landscape, driven by the need for consistent output and quality control. The market features a tiered structure, with large-scale producers anchoring the supply of elemental bromine and specialty chemical manufacturers focusing on derivatives. Strategic partnerships and long-term contracts are becoming crucial competitive moves, prioritizing supply chain security.
Large-scale producers like ICL Group Ltd. and Albemarle Corporation exemplify the archetype of integrated suppliers with extensive production capacities and global distribution networks. LANXESS, a specialty chemical company, occupies a position focused on bromine derivatives and advanced flame retardant solutions for specialized industrial applications. These companies represent the shift towards single-source, long-term procurement models, particularly in industries demanding high purity and traceability.
| Leading Market Players |
|---|
| Albemarle Corporation |
| ICL Group Ltd. |
| LANXESS |
| Jordan Bromine Company |
| Tosoh Corporation |
| Gulf Resources Inc. |
| TETRA Technologies Inc. |
| Tata Chemicals Ltd. |
| Hindustan Salts Ltd. |
| Others |
Cost & Logistics Intelligence
Major consumers' shift to single-supplier, multi-year contracts for high-purity bromine is reshaping supply chain dynamics. This procurement change prioritizes stability and consistent quality, influencing pricing structures away from volatile spot markets.
Pricing Analysis
High-volume commodity bromine sales operate on thinner margins compared to specialized derivatives. Pricing for elemental bromine often follows a contract-based long-term offtake model, reflecting the capital-intensive extraction costs and stable supply needs. Price differentiation stems from purity levels and specific chemical formulations, with pharmaceutical-grade compounds commanding higher premiums. Buyers in the oilfield drilling fluids sector exhibit higher price sensitivity than those sourcing for pharmaceutical synthesis, who prioritize unwavering purity.
Supply Chain Analysis
Regional distribution centers facilitate the movement of bromine compounds from concentrated production hubs to diverse end-use markets. Supply concentrates heavily in Israel, leveraging Dead Sea brine, with significant contributions from China for chemical manufacturing. Raw material dependencies center on natural brine sources and specialized chemical precursors for derivatives. Single-source vulnerability from geopolitical instability in the Dead Sea region represents a structural risk. Downstream distribution runs through a network of specialized chemical distributors and direct bulk deliveries to large industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bromine market is navigating a technology-transition phase, driven by the systematic replacement of older additive-type flame retardants with polymeric flame retardants. This evolution responds to stricter environmental health standards and regulatory pressures.
For Market Incumbents:Hedge against regulatory shifts like the EU's REACH and RoHS directives by accelerating investment in compliant polymeric flame retardants. Consolidate market position through long-term supply agreements with key pharmaceutical and electronics buyers, ensuring consistent output and quality control. Vertical integration into specialized derivatives offers a lever against margin pressure from commodity bromine price fluctuations. Capacity additions in regions with stable regulatory environments, such as the United States, can mitigate single-source vulnerability.
For New Entrants and Emerging Players:A price-point gap exists between high-purity pharmaceutical-grade bromine and standard industrial compounds, offering a white-space target. Focus on specialized organobromine compounds for API synthesis, which represents the fastest-growing application segment. Target the expanding pharmaceutical manufacturing base in India with high-purity, traceable products. A direct-to-customer sales model emphasizing technical support and supply chain transparency can penetrate this niche effectively.
For Investors and Strategic Acquirers:The window for entry favors specialty chemical manufacturers with established R&D capabilities in advanced brominated derivatives. Long-term viability rests on securing access to stable, environmentally compliant production capacity for polymeric flame retardants and pharmaceutical intermediates. Acquire mid-sized players possessing proprietary synthesis technologies or strong intellectual property in niche organobromine applications. The signal to watch is the acceleration of regulatory approvals for new, non-additive flame retardant solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Polymeric Flame Retardant R&D | Develop compliant materials for electronics and construction, meeting EU RoHS directives. |
| Secure Long-Term Supply Contracts | Ensure stable bromine access for pharmaceutical synthesis, mitigating geopolitical supply risks. |
| Expand API Intermediate Production | Capitalize on the robust growth in pharmaceutical formulation, particularly in India. |
| Upgrade Wastewater Treatment Facilities | Comply with China's MEE environmental standards, avoiding production shutdowns and fines. |
| Diversify Brine Sourcing | Reduce reliance on Dead Sea brine, enhancing supply chain resilience against regional instability. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, validated through primary interviews with industry stakeholders. We engaged with plant managers, procurement leads from chemical manufacturers, technical R&D directors, and environmental compliance officers. This approach involved extensive analysis of SEC 10-K filings, chemical industry reports, and environmental agency disclosures from EPA and MEE. Both bottom-up market sizing and top-down validation ensured data integrity.
Data-stream reconciliation integrated historical trends with projected market shifts across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, production method, and end-user industry, alongside regional regulatory clusters. Compound annual growth rates derived from a weighted average of historical performance and anticipated future drivers. Key forecast inputs included projected oil and gas exploration activity and pharmaceutical R&D spending.
Inputs from published company reports and regulatory databases were available through the study window; gaps in real-time supply chain disruption data introduce uncertainty bands. Forecasts reflect assumptions regarding geopolitical stability and technological adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
North America and Europe Palm Derivatives Market
Bulk Chemicals
Global Anthracite Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
Barite Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Coal Tar Pitch Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Cobalt (II) Sulfate Market