
 United States Mobile Payment Market | 2026-2036
United States Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Mobile Payment Market Intelligence
Tokenized credential architecture is tilting the mobile payment stack away from card-present rails toward device-bound authentication. Apple Pay leverages its Secure Element hardware to dominate in-store proximity transactions. PayPal sustains checkout button supremacy across e-commerce merchant sites. Cash App competes by anchoring its ecosystem in direct deposit and peer-to-peer social payments.
Mobile payment systems transmit encrypted financial credentials between consumer devices and merchant terminals via near-field communication, QR code scanning, or cloud-hosted token vaults, with primary commercial purpose being friction reduction at transaction points. Digital wallets capture the deepest margin pools through stored-value float and interchange optimization, while contactless payments lead transaction volume growth in physical retail environments. Peer-to-peer services remain structurally constrained by monetization challenges despite high user engagement.
The Federal Reserve's FedNow instant payment infrastructure, the CFPB's open banking rulemaking under Section 1033 of Dodd-Frank, and state-level money transmission licensing collectively shape product architecture and market access requirements. NIST cybersecurity frameworks influence tokenization standards that vendors must implement to maintain bank partnerships. Stakeholders must monitor whether FedNow's real-time settlement capabilities disintermediate card network economics or become co-opted within existing wallet architectures.
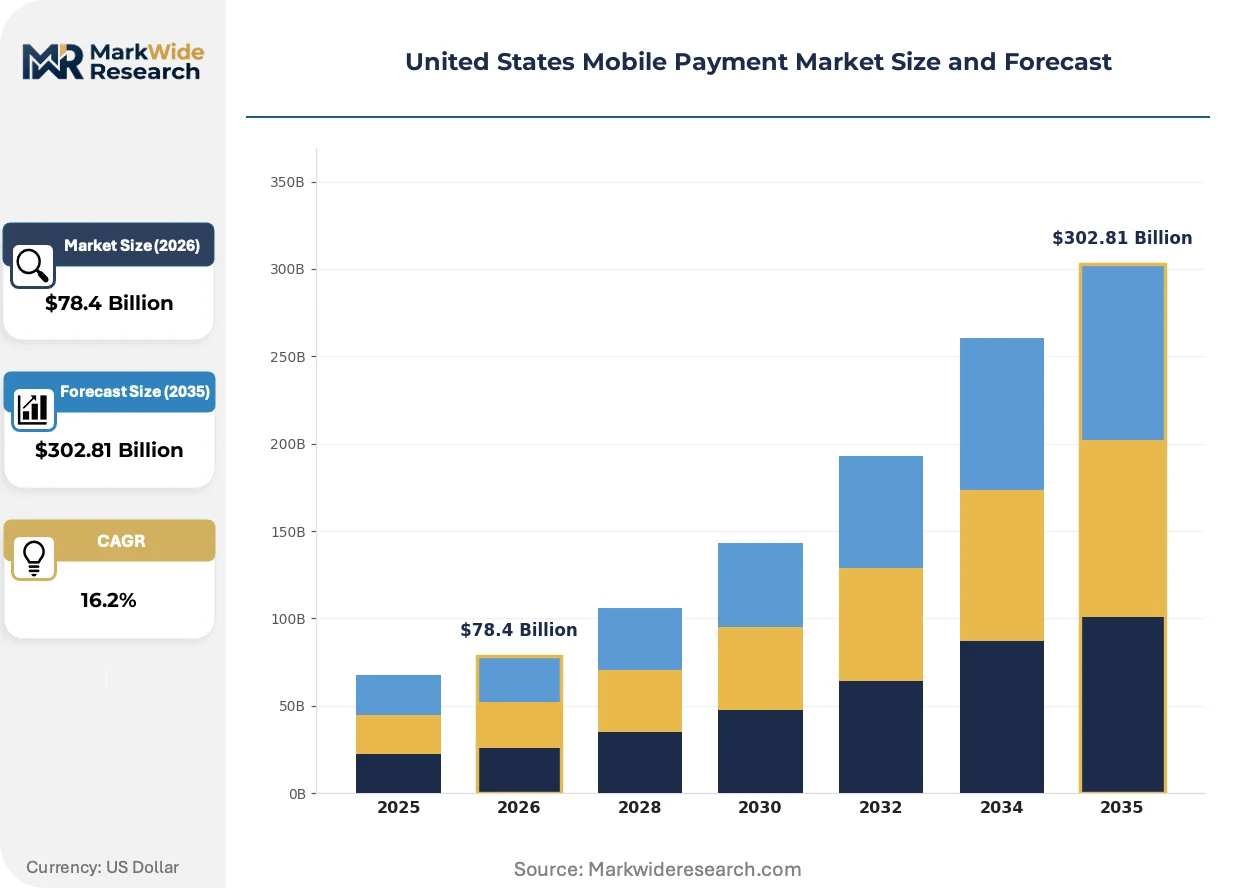
Market Dynamics
Tokenized credential architecture is compressing transaction friction while the CFPB's Section 1033 open banking rulemaking restructures data portability obligations for non-bank wallet providers.
Growth Catalysts
- Merchant hardware substitution:Small businesses are replacing dedicated point-of-sale terminals with smartphone-based acceptance systems, eliminating upfront equipment costs and reducing onboarding friction.
- FedNow instant settlement:The Federal Reserve's real-time payment infrastructure enables wallet providers to offer immediate fund availability, accelerating merchant adoption of digital payment rails.
- Transit system integration:Dense urban merchant networks in California and New York are driving transaction frequency through transportation wallet compatibility.
Market Restraints
- State licensing fragmentation:Money transmission requirements vary across all 50 states, creating compliance overhead that constrains provider expansion into new jurisdictions.
- Bank partnership dependency:Wallet providers remain captive to sponsor bank relationships for network access, concentrating supplier power among a limited number of chartered institutions.
- Device-bound authentication limits:Secure Element hardware requirements exclude older smartphone models from contactless functionality, capping addressable consumer base.
Strategic Opportunities
- Underpenetrated rural corridors:Merchant acceptance gaps across the Midwest and Mountain West regions present whitespace for smartphone-based point-of-sale deployment.
- Payroll-to-wallet direct deposit:Wage disbursement integration creates stored-value float opportunities while reducing churn through primary financial relationship anchoring.
- NIST cybersecurity framework alignment:Tokenization standard certification opens procurement pathways with federal agencies and defense contractors requiring FIPS-compliant payment systems.
Industry Challenges
- Legacy core banking integration:Wallet providers face API fragmentation and batch-processing delays when connecting to regional bank cores built on decades-old architecture.
- Qualified security assessor scarcity:PCI-DSS Level 1 certification timelines extend 12-18 months due to limited auditor capacity, delaying product launches for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Mobile Payment Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $302.81 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Digital Wallets, Mobile Banking, Contactless Payments End User: Retail Consumers, Small Businesses, Large Enterprises, E-commerce Platforms Technology: QR Code, NFC, Cloud-Based, SMS Distribution Channel: App Store, Direct Download, Online Retail, Third-Party Platforms |
| Companies Covered | PayPal, Apple Pay, Venmo, Google Pay, Cash App, Zelle, Samsung Pay, Chase Pay, Masterpass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Mobile Payment Market Strategic Shifts & Innovations
Authentication architecture is migrating from card-present rails toward device-bound credential vaults, compressing interchange economics while expanding merchant acceptance modalities.
Biometric verification is migrating from fingerprint sensors to facial recognition systems in proximity payment workflows. Transit authorities in New York and Los Angeles are deploying camera-based authentication for fare gates. This migration from hardware-token to software-credential verification is compressing terminal upgrade cycles while enabling account-based ticketing without physical card issuance.
The CFPB's open banking rulemaking under Section 1033 of Dodd-Frank mandates standardized data sharing APIs for consumer financial information. Wallet providers must implement interoperable interfaces that reduce switching costs between competing services. Non-bank payment applications face the steepest compliance burden as they retrofit proprietary data architectures to meet structured access requirements.
Merchant acquisition patterns are fragmenting across vertical-specific software platforms. Food service operators now demand integrated payment acceptance within point-of-sale systems rather than standalone terminals. Independent software vendors in restaurant and retail verticals are bundling embedded finance capabilities, displacing traditional independent sales organization distribution channels in metropolitan markets.
United States Mobile Payment Market Segmentation
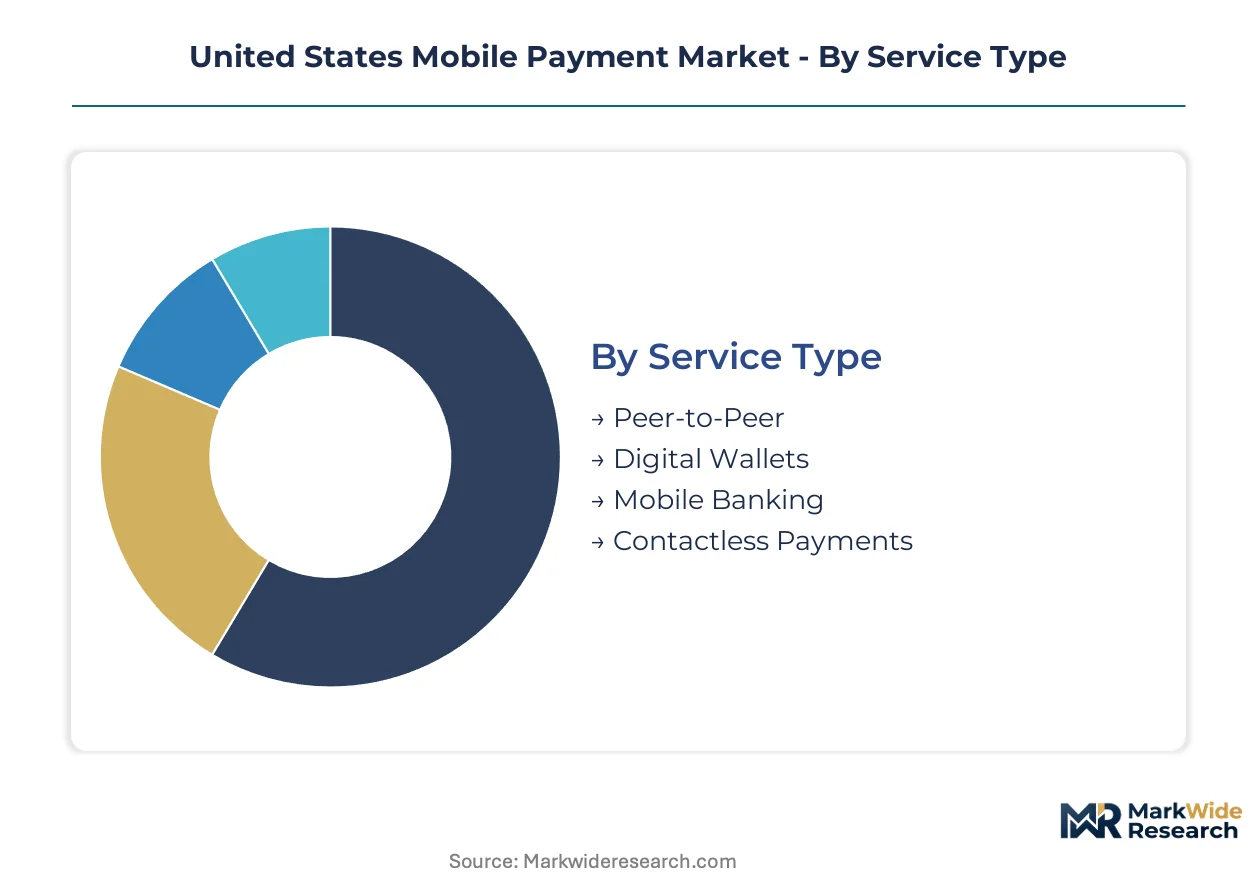
Segmentation in the United States mobile payment market reveals how transaction infrastructure fragments across use-case intensity, technical sophistication, and merchant scale. Each dimension carries distinct margin profiles and regulatory exposure that shape provider strategy.
Service Type:
Transaction velocity and float economics vary sharply across the use-case spectrum from casual social transfers to high-frequency commercial acceptance.
- Peer-to-Peer:Direct person-to-person transfers anchor user acquisition through social network effects. California and New York users drive frequency via splitting shared expenses, though monetization remains structurally constrained by low interchange capture on non-commercial flows.
- Digital Wallets:Stored-value architectures concentrate the deepest margin pools through deposit float and network interchange optimization. Small business adoption in dense urban corridors accelerates as merchants replace dedicated terminals with smartphone acceptance.
- Mobile Banking:Chartered institution apps dominate balance-heavy relationships with integrated bill pay and remote deposit capture.
- Contactless Payments:NFC-enabled proximity transactions lead physical retail volume growth, constrained by Secure Element hardware requirements excluding older devices.
Established volume favors contactless payments; emerging adoption favors digital wallets.
End User:
Customer scale determines integration complexity and pricing power across the acceptance stack.
- Retail Consumers:Individual users select wallets based on funding source flexibility and merchant acceptance breadth. Transit system integration in California and New York drives habitual usage patterns that reduce churn.
- Small Businesses:Merchants under $10M annual revenue are accelerating smartphone-based point-of-sale deployment, eliminating upfront hardware costs and compressing onboarding timelines.
- Large Enterprises:Treasury departments demand API-based reconciliation and multi-entity reporting that legacy cores struggle to support.
- E-commerce Platforms:Checkout button providers sustain supremacy through one-click credential storage, though CFPB Section 1033 data portability mandates threaten switching-cost moats.
Merchant acquisition concentrates on small businesses; enterprise integration faces legacy core friction.
Technology:
Authentication architecture migration from card-present rails to device-bound credentials reshapes terminal upgrade cycles and network economics.
- QR Code:Optical scanning enables acceptance on legacy hardware without NFC capability. Underpenetrated rural corridors across the Midwest present whitespace for low-cost deployment without terminal replacement.
- NFC:Near-field communication dominates in-store proximity with sub-100 millisecond transaction times. Tokenized credential transmission via Secure Element hardware tilts the stack toward device-bound authentication.
- Cloud-Based:Host card emulation removes hardware dependency but introduces latency and connectivity failure modes.
- SMS:Text-based initiation persists for feature phone compatibility and emergency fallback scenarios.
NFC retains transaction density leadership; QR code deployment expands fastest in hardware-constrained environments.
Distribution Channel:
Acquisition pathway determines customer quality and platform dependency risk for wallet providers.
- App Store:Apple and Google marketplaces dominate consumer discovery with built-in trust signaling and review infrastructure. CFPB oversight of non-bank providers tightens compliance requirements for listing eligibility.
- Direct Download:Enterprise and payroll-integrated wallets bypass store fees through sideloading or mobile device management deployment.
- Online Retail:E-commerce checkout flows embed wallet enrollment with transactional intent, improving activation rates versus organic discovery.
- Third-Party Platforms:Vertical software vendors in food service and retail bundle payment acceptance, displacing traditional independent sales organization channels.
App store dependency concentrates consumer acquisition; direct download gains traction in B2B and payroll-anchored segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States mobile payment market exhibits strong domestic service orientation with limited cross-border payment flows, as wallet providers concentrate infrastructure investment on domestic settlement rails and merchant acceptance networks rather than international remittance corridors.
California
Transit system integration across Bay Area Rapid Transit and Los Angeles Metro drives habitual wallet usage among urban commuters. The California Department of Financial Protection and Innovation enforces money transmission licensing that exceeds federal baseline requirements. Silicon Valley fintech clusters in San Francisco and San Jose anchor product development for device-bound authentication technologies.
New York Metro
Density of small business merchant networks accelerates smartphone-based point-of-sale deployment in Manhattan and Brooklyn corridors. The New York State Department of Financial Services maintains BitLicense and money transmitter frameworks that filter non-bank provider market entry. MTA contactless fare payment adoption across subway and bus lines cements daily wallet engagement patterns.
Texas
Payroll-to-wallet direct deposit growth concentrates in Houston and Dallas-Fort Worth energy sector employment bases. The Texas Department of Banking coordinates with federal regulators on non-bank payment provider supervision. Austin fintech incubators support emerging wallet providers targeting underpenetrated rural merchant corridors.
Illinois
Legacy core banking integration challenges emerge as Chicago-based regional banks modernize batch-processing infrastructure for real-time settlement. The Illinois Department of Financial and Professional Regulation administers money transmission licensing with reciprocity provisions. Chicago transit authority payment integration drives commuter wallet adoption across metropolitan rail networks.
Florida
Tourism and hospitality merchant sectors in Miami and Orlando drive seasonal transaction volume spikes for contactless payment acceptance. The Florida Office of Financial Regulation enforces consumer protection standards for digital wallet disclosures. Retirement community demographics in Southwest Florida present stored-value float opportunities through pension disbursement anchoring.
United States Mobile Payment Market Key Industry Players
On the supply side, the industry is consolidating around technology platform owners with device distribution control and banking partnerships. Three archetypes dominate competitive positioning: hardware-integrated wallet providers leveraging Secure Element architecture, bank consortium platforms with direct deposit anchoring, and independent fintech applications competing through social payment network effects. Dominant competitive moves include strategic partnerships with transit authorities for habit formation and vertical software vendor integration for merchant acquisition displacement.
Within the hardware-integrated tier, Apple Pay and Samsung Pay exemplify device-bound authentication dominance through Secure Element control. PayPal occupies a position spanning both consumer wallet and merchant services archetypes with checkout button supremacy across e-commerce flows. Cash App represents the fintech-native model competing through peer-to-peer social engagement and direct deposit relationship anchoring.
| Leading Market Players |
|---|
| PayPal |
| Apple Pay |
| Venmo |
| Google Pay |
| Cash App |
| Zelle |
| Samsung Pay |
| Chase Pay |
| Masterpass |
| Others |
Cost & Logistics Intelligence
The Los Angeles-Long Beach port complex cost dynamics compress margins for Secure Element hardware imports while amplifying price differentiation between NFC-enabled terminals and legacy QR-based acceptance systems across merchant tiers.
Pricing Analysis
The technology-generation pricing gap separates Secure Element-enabled proximity systems from host card emulation alternatives and legacy magnetic stripe terminals. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade against NIST cybersecurity framework alignment and volume commitment scale. Pricing pressure stems from small business merchant consolidation around smartphone-based acceptance eliminating dedicated hardware procurement. Retail consumers exhibit highest price sensitivity to transaction fees, while large enterprise treasury departments prioritize API integration reliability over per-unit cost.
Supply Chain Analysis
Export-control regime restrictions under the Department of Commerce's Entity List constrain semiconductor foundry access for advanced Secure Element fabrication. Taiwan, South Korea, and China concentrate supply for NFC controller chips, tokenization processors, and terminal display components. Raw material dependencies center on rare earth elements for antenna substrates, lithium-ion cells for portable terminals, and specialized polymers for card-body manufacturing. Single-source vulnerability concentrates in TSMC's advanced node capacity for cryptographic processors. Distribution runs through sponsor bank procurement networks, independent sales organizations, and vertical software vendor bundling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States mobile payment market is recovering from pandemic-era transaction volume troughs as transit system integration and payroll-to-wallet anchoring restore habitual usage frequency.
For Market Incumbents: Harden device-bound authentication moats through deeper Secure Element hardware integration while accelerating FedNow real-time settlement certification to preempt fintech-native competitors. Consolidate sponsor bank relationships against emerging charter applicants threatening network access economics. Prioritize NIST cybersecurity framework certification to lock out non-compliant challengers from federal procurement pathways. For New Entrants and Emerging Players: Pursue underpenetrated rural merchant corridors across the Midwest and Mountain West where QR-code deployment bypasses NFC terminal replacement costs. Target payroll-integrated wallet anchoring in Texas energy sector employment bases where direct deposit relationships reduce customer acquisition friction. Lead with vertical software vendor partnerships in food service and retail to displace traditional independent sales organization distribution. For Investors and Strategic Acquirers: Bank-sponsored fintech platforms with existing money transmission licenses and FedNow connectivity represent the most defensible acquisition archetype against regulatory fragmentation. Long-term viability hinges on whether real-time payment infrastructure disintermediates card network economics or becomes co-opted within existing wallet architectures. Watch CFPB Section 1033 implementation timelines as the signal for data portability cost structures and switching-cost erosion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FedNow Certification Acceleration | Real-time settlement capability from the Federal Reserve disintermediates legacy batch-processing delays for merchant fund availability. |
| Transit Authority Partnership | MTA and BART system integration cements daily wallet engagement patterns that reduce customer churn through habitual usage. |
| NIST Framework Alignment | Cybersecurity standard certification opens federal agency and defense contractor procurement pathways requiring FIPS-compliant systems. |
| Vertical Software Bundling | Restaurant and retail point-of-sale integration displaces traditional independent sales organization merchant acquisition channels. |
| Payroll Direct Deposit Anchoring | Wage disbursement integration creates stored-value float opportunities while reducing churn through primary financial relationship capture. |
Research Approach
Cross-validation between primary interviews with digital wallet product executives, sponsor bank partnership leads, transit authority procurement managers, and merchant acquiring specialists anchors the qualitative findings against secondary validation from CFPB rulemaking dockets, Federal Reserve payment system reports, SEC 10-K filings from listed providers, and state money transmission licensing databases. Bottom-up merchant adoption modeling and top-down transaction volume triangulation reconcile segment-level estimates.
Calibration against historical adoption curves for contactless payment infrastructure and peer-to-peer wallet penetration shapes the analytical framework across the projection horizon. Segmentation dimensions include service type, end user scale, authentication technology, and distribution channel complexity. CAGRs derive from regression analysis of merchant terminal replacement cycles, smartphone upgrade rates, and regulatory compliance cost trajectories. FedNow adoption velocity and CFPB Section 1033 implementation scope serve as primary forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, small business formation rates, and regional bank consolidation velocity would shift the trajectory. Forecasts reflect assumptions regarding regulatory timeline adherence and hardware cost curves. Material shifts in CFPB enforcement posture or FedNow fee structure would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Norway POS Terminals Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Mexico Payments Market
Payments
Global Accounts Payable Automation Market
Payments
Fuel and Convenience Store POS Market
Payments
South Africa Gift Card and Incentive Card Market
Payments
Argentina Payments Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Bitcoin Payments Market
Payments
Cloud Billing Market
Payments
Voice-Based Payments Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Dual Interface Payment Card Market
Payments
E-Wallet Market
Payments
Mpos Terminals Market
Payments
Fuel Cards Market