
 Consumer Mobile Payment Market | 2026-2036
Consumer Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Mobile Payment Market Analytics
Asian fintech infrastructure is shifting toward open banking rails and real-time settlement protocols. Alipay leverages its merchant network density to sustain dominance in offline-to-online transaction loops. Apple competes through hardware-integrated tokenization that controls the security layer across iOS devices. PayPal anchors cross-border remittance corridors with specialized currency conversion engines.
Consumer mobile payment denotes funds transfer initiated from a personal handheld device using encrypted wireless communication protocols with tokenized credential substitution for primary account numbers. The system relies on near-field communication chips operating at 13.56 MHz or host card emulation software to execute proximity transactions within four centimeters. Digital wallet segments lead transaction volume globally as embedded finance supplants standalone banking applications. QR code technology occupies the fastest growth trajectory in emerging markets where merchant acquisition costs for dedicated terminals remain prohibitive. NFC penetration concentrates in premium smartphone-installed bases across North American and European retail environments.
FDA oversight of health-related payment data intersects with HIPAA privacy mandates when mobile wallets process medical service transactions in the United States. The EU AI Act and GDPR frameworks constrain biometric authentication deployment in European consumer payment flows, forcing algorithmic transparency and explicit consent architectures. China's SAMR and PBOC jointly govern third-party payment institution licensing and reserve requirements. Stakeholders must monitor regulatory divergence between data localization mandates and cross-border interoperability standards as compliance architecture becomes the primary competitive moat.
Market Dynamics
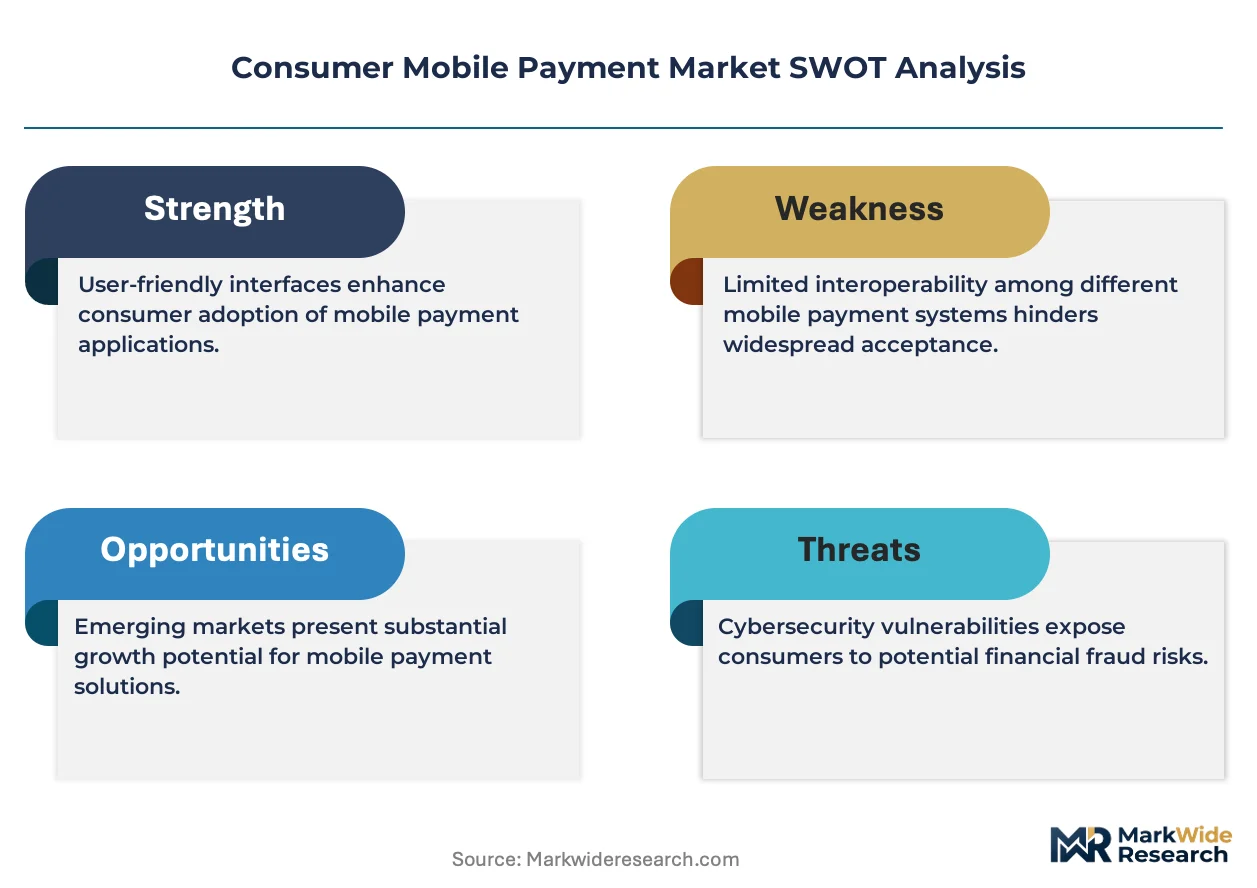
Real-time settlement rails and open banking APIs are dismantling traditional payment processor intermediation, forcing wallet providers to compete on data velocity rather than transaction volume alone.
Growth Catalysts
- India's RBI Interoperability Mandate:Digital wallet providers must integrate unified payment interface protocols, dissolving platform silos and expanding merchant acceptance networks across tier-two and tier-three urban centers.
- QR Code Infrastructure:Low-cost merchant acquisition in Indonesia, Vietnam, and Philippines accelerates cash displacement without requiring dedicated NFC terminal deployment.
- Biometric Authentication Standards:Fingerprint and facial recognition integration into smartphone secure elements reduces friction in high-frequency micro-transaction environments.
Market Restraints
- Data Localization Requirements:China's PBOC and SAMR joint licensing frameworks mandate domestic server architecture, fragmenting cross-border wallet operability and raising compliance overhead for foreign entrants.
- Merchant Discount Rate Compression:Regulatory caps on interchange fees in India and Southeast Asian markets squeeze platform revenue per transaction.
- Smartphone Penetration Ceilings:Rural segments in South Asia and sub-Saharan Africa lack NFC-enabled device density, constraining contactless adoption outside urban corridors.
Strategic Opportunities
- Embedded Finance Convergence:Ride-hailing and food delivery super-apps in Southeast Asia integrate payment, lending, and insurance within single user interfaces, capturing lifetime transaction value.
- Cross-Border Remittance Corridors:Gulf Cooperation Council to South Asia worker remittance flows demand real-time settlement with competitive foreign exchange spreads.
- Offline QR Networks:Street vendors and informal merchants in Indonesia and Philippines represent untapped volume requiring minimal hardware investment.
Industry Challenges
- Legacy Core Banking Integration:Regional banks in Southeast Asia maintain decades-old batch processing systems that conflict with real-time wallet settlement requirements.
- Certification Timeline Variability:EMVCo tokenization compliance and local regulator security audits create unpredictable go-to-market delays across ASEAN member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Mobile Payment Market |
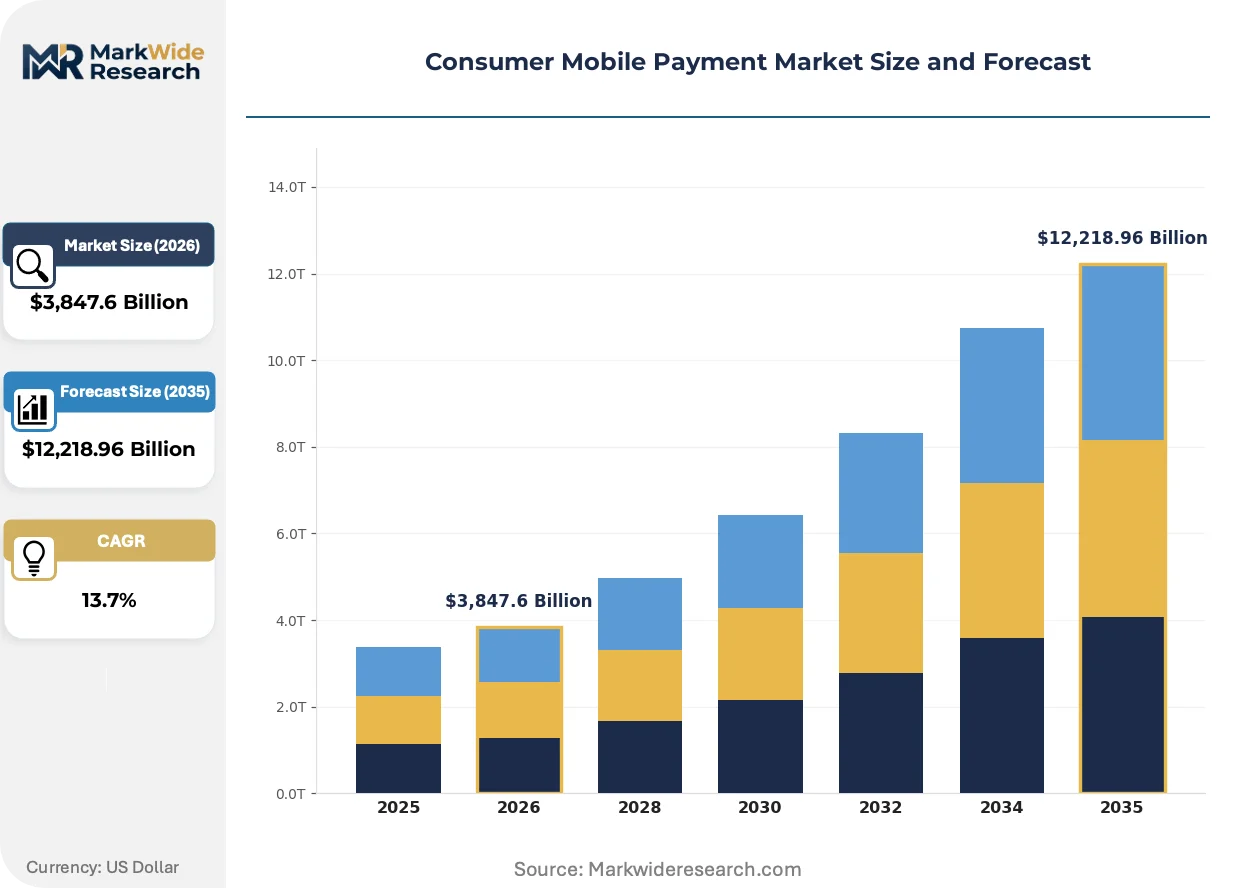
| Market Size in 2026 | $3,847.6 Billion |
| Market Size in 2035 | $12,218.96 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer Technology: NFC, QR Code, BLE, Biometrics End User: Retail Customers, Businesses, E-commerce Platforms, Service Providers Integration Type: Third-Party Integrations, In-House Solutions, Open API, Legacy Systems |
| Companies Covered | Alipay (Ant Group), Apple (Apple Pay), Google (Google Pay), PayPal Holdings, Samsung Electronics (Samsung Pay), Tencent Holdings (WeChat Pay), Visa, Mastercard, Amazon.com (Amazon Pay), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Mobile Payment Market Evolving Landscape
Payment authentication is migrating from knowledge-based credentials toward behavioral biometrics and device-bound cryptographic keys, compressing transaction authorization windows to sub-second intervals.
Host card emulation software is rewriting proximity payment economics by eliminating dedicated secure element hardware requirements. Mid-tier smartphone manufacturers in India and Southeast Asia embed HCE protocols to enable NFC functionality without premium chipset costs. This compression expands contactless acceptance to price-sensitive merchant segments previously excluded by terminal acquisition barriers.
Europe's GDPR and AI Act frameworks constrain facial recognition deployment in payment flows, forcing explicit consent architectures and algorithmic transparency documentation. Wallet providers serving EU markets must maintain separate authentication stacks from biometric-heavy Asian implementations. This regulatory friction segments product development roadmaps and raises compliance engineering headcount.
Super-app ecosystems in China's tier-one cities now bundle payments, wealth management, and municipal services within single interfaces. Users execute utility bill settlements, transit fares, and insurance premiums without exiting the primary application. This behavioral consolidation displaces standalone banking applications and concentrates transaction data within platform operators.
Consumer Mobile Payment Market Segmentation
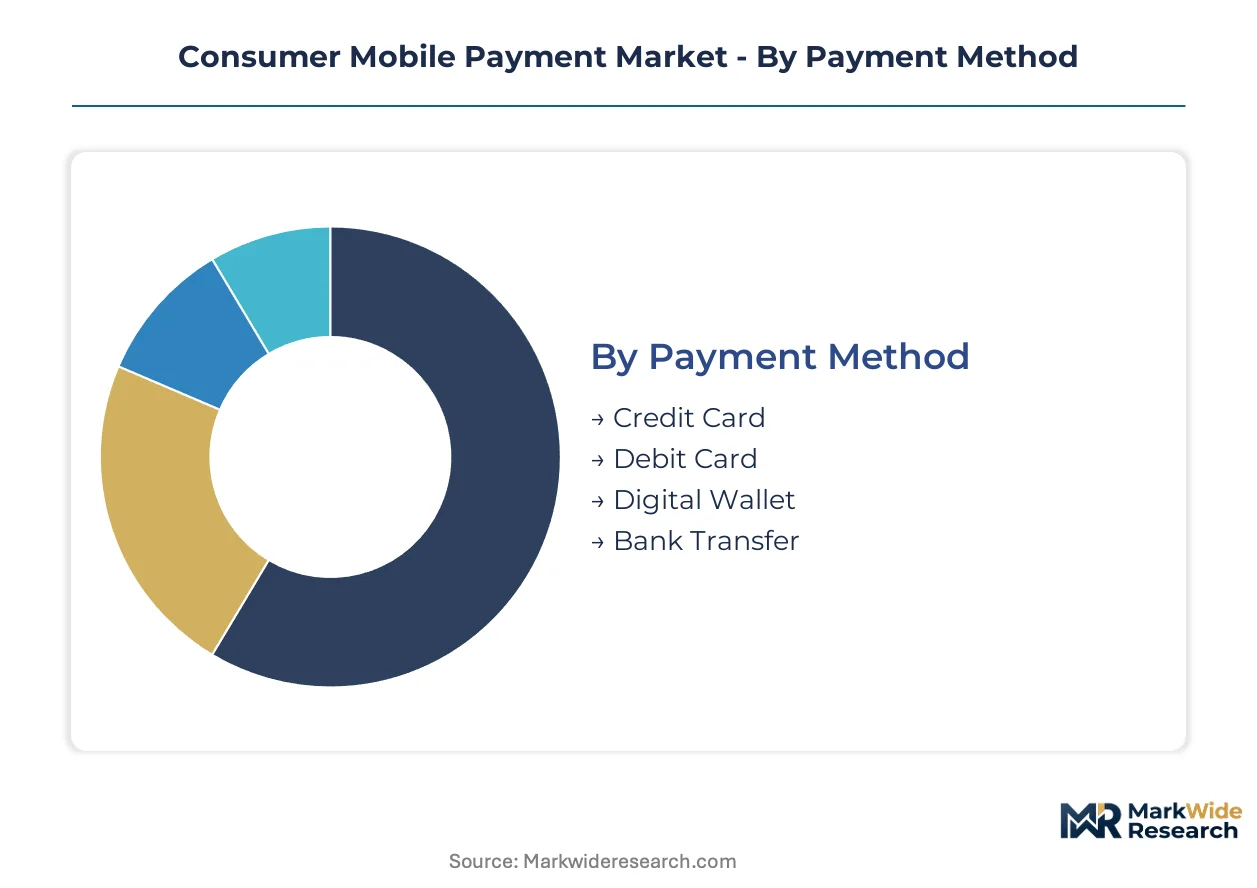
Mobile payment infrastructure fragments across four critical dimensions that determine capital deployment, regulatory exposure, and merchant acquisition economics. Technology choices dictate hardware requirements while integration architectures shape compliance overhead and time-to-market velocity.
Payment Method:
Capital intensity varies dramatically across payment rails, with digital wallets demanding platform-scale investment while bank transfers leverage existing infrastructure.
- Credit Card:Tokenized credential substitution replaces primary account numbers through EMVCo-compliant encryption protocols. Issuer networks in the United States and European Union concentrate transaction volume where interchange fee structures sustain premium reward programs.
- Debit Card:Real-time balance verification through banking rails eliminates credit risk but requires direct issuer integration. India's UPI-linked debit flows demonstrate fastest expansion where regulatory mandates force interoperability.
- Digital Wallet:Closed-loop ecosystems with stored value functionality.
- Bank Transfer:Account-to-account settlement bypassing card networks entirely.
Digital wallets absorb the bulk of installed capacity; credit card tokenization is expanding most quickly.
Technology:
Merchant acquisition cost structures diverge sharply between proximity protocols, with QR deployment requiring minimal hardware versus NFC's secure element dependencies.
- NFC:Near-field communication chips operating at 13.56 MHz enable contactless transactions within four centimeter proximity. Premium smartphone penetration in North American and European retail environments sustains deployment where merchant terminal density supports acceptance.
- QR Code:Optical scanning infrastructure eliminates dedicated terminal requirements through smartphone camera integration. Indonesia, Vietnam, and Philippines street vendor networks demonstrate steepest adoption curves where hardware acquisition barriers exclude NFC deployment.
- BLE:Bluetooth Low Energy beacons enabling proximity detection without physical tap.
- Biometrics:Fingerprint and facial recognition integrated into secure elements.
NFC dominates transaction value concentration; QR code networks are gaining share fastest.
End User:
Customer acquisition economics and transaction frequency profiles separate consumer-facing applications from B2B payment flows.
- Retail Customers:Individual consumers executing peer-to-peer transfers and merchant purchases through personal handheld devices. China's tier-one city super-app ecosystems concentrate daily transaction behavior within single interfaces.
- Businesses:Corporate treasury functions and supplier payment automation.
- E-commerce Platforms:Checkout integration for online merchant acceptance.
- Service Providers:Utility, insurance, and municipal bill settlement functionality.
Retail customer interfaces command the largest installed base; e-commerce platform integration is climbing the fastest.
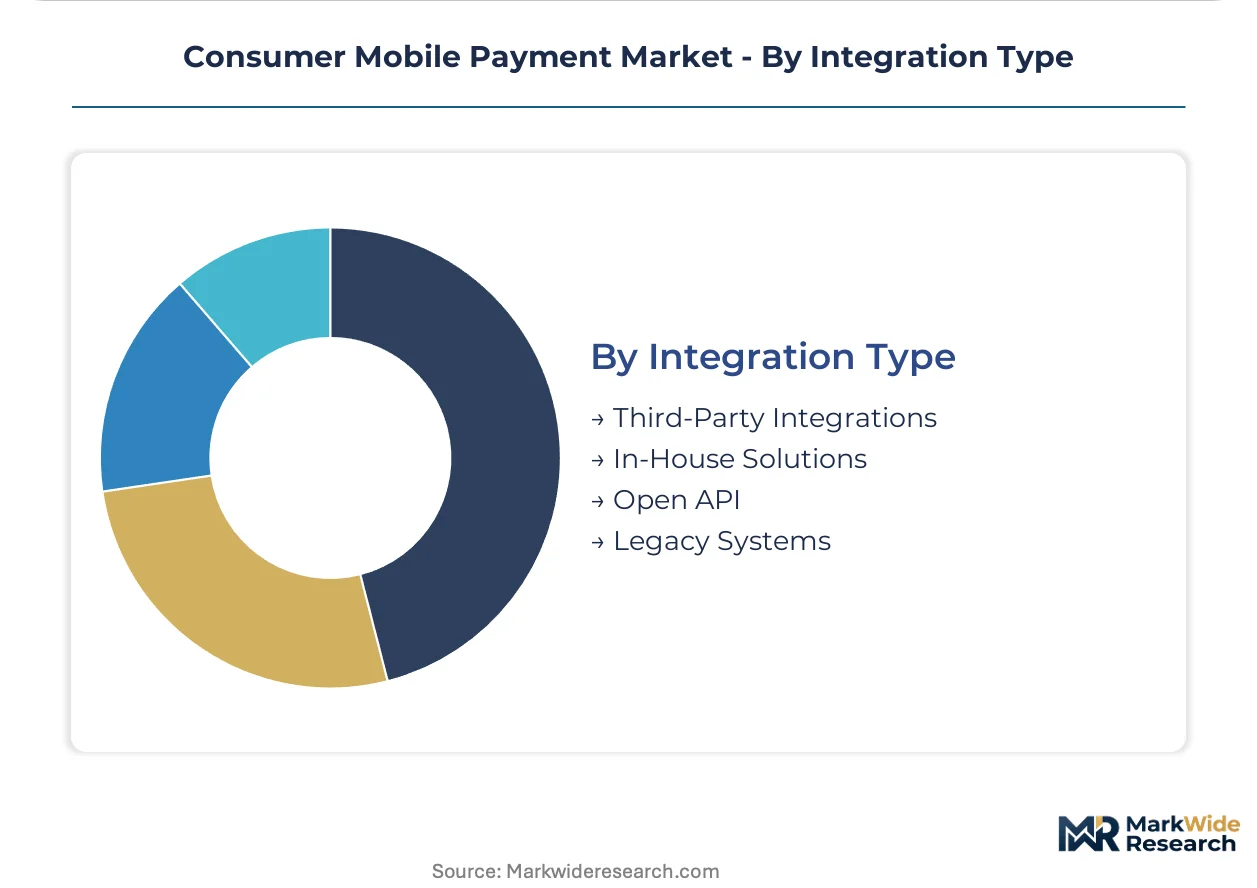
Integration Type:
Technical debt and compliance architecture requirements create divergent investment profiles across implementation approaches.
- Third-Party Integrations:Pre-certified payment service provider plugins reducing development overhead. Southeast Asian ride-hailing super-apps leverage these modules to compress time-to-market for embedded finance deployment.
- In-House Solutions:Proprietary development with full control over security layer and data architecture.
- Open API:Standardized interfaces enabling modular service composition.
- Legacy Systems:Decades-old batch processing infrastructure requiring middleware adaptation.
Third-party integrations capture the majority of new deployment; open API architectures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's venture capital concentration anchors mobile payment innovation infrastructure, while Shenzhen's hardware manufacturing clusters supply NFC chipsets and secure element components to global device manufacturers.
China
Super-app ecosystems in Shanghai and Beijing bundle payments with wealth management and municipal services within single interfaces. SAMR and PBOC joint licensing frameworks mandate domestic server architecture and reserve requirements for third-party payment institutions. The Yangtze River Delta concentrates merchant network density where Alipay leverages offline-to-online transaction loops.
India
Tier-two and tier-three urban centers drive volume expansion as digital wallet providers integrate unified payment interface protocols per RBI mandates. The central bank's interoperability guidelines dissolve platform silos and expand merchant acceptance networks. Mumbai and Bangalore anchor fintech development clusters where real-time settlement rails dismantle traditional processor intermediation.
United States
Premium smartphone penetration in New York and San Francisco retail environments sustains NFC deployment where merchant terminal density supports acceptance. FDA oversight intersects with HIPAA privacy mandates when mobile wallets process medical service transactions. The Federal Reserve's FedNow instant payment infrastructure reshapes settlement velocity expectations.
Indonesia
Street vendor networks in Jakarta and Surabaya demonstrate steepest QR code adoption curves where hardware acquisition barriers exclude NFC deployment. GoTo and Grab super-apps integrate payment, lending, and insurance within single user interfaces. Bank Indonesia's regulatory sandbox accelerates licensed e-money provider expansion into informal merchant segments.
Germany
GDPR and EU AI Act frameworks constrain biometric authentication deployment in payment flows, forcing explicit consent architectures. Berlin and Munich anchor fintech clusters where open banking APIs enable account-to-account settlement bypassing card networks. The Bundesbank's oversight of payment systems ensures compliance with European Central Bank settlement standards.
Consumer Mobile Payment Market Competitive Landscape
Global majors compete with regional champions across technology integration and merchant network density, creating a tiered structure where hardware-integrated tokenization battles platform-scale ecosystem lock-in. Market concentration varies by geography: super-app dominance in China contrasts with fragmented wallet competition in Southeast Asia. Three archetypes define competitive positioning: technology giants leveraging device-installed bases, financial networks anchoring cross-border corridors, and regional super-apps capturing embedded finance convergence. Dominant competitive moves include strategic partnerships with ride-hailing and delivery platforms, plus regulatory compliance architecture investments that create moats against foreign entrants.
Within the technology-integrated tier, Apple and Google exemplify hardware-bound security layer control across iOS and Android device ecosystems. PayPal occupies a distinct position anchoring cross-border remittance corridors with specialized currency conversion capabilities. Ant Group's Alipay represents the super-app archetype where merchant network density sustains dominance in offline-to-online transaction loops. These three anchors illustrate how competitive positioning depends on whether players control devices, financial networks, or merchant relationships.
| Leading Market Players |
|---|
| Alipay (Ant Group) |
| Apple (Apple Pay) |
| Google (Google Pay) |
| PayPal Holdings |
| Samsung Electronics (Samsung Pay) |
| Tencent Holdings (WeChat Pay) |
| Visa |
| Mastercard |
| Amazon.com (Amazon Pay) |
| Others |
Value Network & Pricing Analysis
Platform operators backed by sovereign wealth and private-equity rollups dominate merchant acquisition infrastructure, compressing interchange economics while consolidating tokenization certification costs across Southeast Asian payment corridors.
Pricing Analysis
Service-bundling separates tokenization-as-a-service packages from unbundled per-transaction processing. Three-tier pricing structure across premium, standard, and economy levels reflects EMVCo certification grade and real-time settlement velocity. Pricing pressure stems from India's regulatory caps on merchant discount rates. Tier-two urban merchants exhibit highest price sensitivity; multinational retail chains absorb premium tiers for cross-border FX optimization.
Supply Chain Analysis
Reverse-logistics for NFC secure element chipsets and terminal refurbishment flows concentrate in Shenzhen, Seoul, and Taipei. Taiwan Semiconductor Manufacturing and Samsung Foundry supply 13.56 MHz proximity chips. Supply chain risk centers on single-source vulnerability for EMVCo-certified secure elements. Distribution runs through OEM device manufacturers and certified payment terminal assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum favors merchant network ownership and proprietary tokenization stacks as the decisive upstream lever in mobile payment infrastructure competition.
For Market Incumbents: Extend merchant density in Indonesia and Philippines through QR-code interoperability investments. Consolidate certification timelines across ASEAN regulators to neutralize emerging super-app challengers. Prioritize backward integration into host card emulation software to reduce secure element dependency costs. For New Entrants and Emerging Players: Street vendors in Vietnam's informal economy represent the most penetrable buyer archetype with minimal hardware acquisition barriers. Capture offline-to-online transaction loops through ride-hailing platform partnerships. Deploy white-label wallet infrastructure to compress regulatory compliance timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional payment processors with existing SAMR licenses in China's Yangtze River Delta corridor. Five-to-ten year viability hinges on data localization compliance architecture rather than transaction volume scale alone. Monitor RBI interoperability mandate enforcement intensity as the inflection signal for Indian market consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Network Acquisition | Alipay's Yangtze River Delta density demonstrates offline-to-online loop monetization. |
| EMVCo Certification Investment | Tokenization compliance creates regulatory moats against unlicensed wallet entrants. |
| Cross-Border Remittance Partnership | PayPal's GCC-to-South Asia corridors anchor foreign exchange spread capture. |
| Host Card Emulation Deployment | India's mid-tier smartphone manufacturers bypass premium NFC chipset costs. |
| Super-App Embedded Finance Integration | Grab and GoTo bundle lending and insurance within Jakarta ride-hailing interfaces. |
Research Methodology
Independent corroboration across payment processor executives, EMVCo certification auditors, and central bank fintech policy officers underwrites the qualitative findings. Secondary validation draws from RBI circulars, PBOC licensing disclosures, SEC 10-K filings by listed payment networks, and ASEAN regulatory sandbox announcements. Bottom-up merchant adoption modeling triangulates against top-down transaction volume estimates across the analysis window.
Comparable-period anchoring weights historical UPI transaction velocity and NFC terminal deployment curves against projected QR-code merchant acquisition rates. Segmentation dimensions span payment method, proximity technology protocol, end-user archetype, and integration architecture complexity. CAGR derivation incorporates real-time settlement rail penetration and biometric authentication adoption curves as industry-specific forecast inputs.
Revisions become necessary when central bank interoperability mandates accelerate or data localization requirements fragment cross-border wallet operability. Forecasts reflect assumptions regarding merchant discount rate stability and secure element supply continuity. Practitioners should monitor SAMR licensing enforcement intensity and FedNow adoption velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Payment Security Software Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Bulgaria POS Terminals Market
Payments
Denmark Payments Market
Payments
Middle East and Africa Real Time Payments Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Instant Payments Market
Payments
Bill Splitting Apps Market
Payments
Global Digital Wallets Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Global Master Card Market
Payments
Buy Now Pay Later Platform Market
Payments
Germany POS Terminal Market
Payments
Argentina Mobile Wallet Market
Payments
Africa Mobile Money Market
Payments
Electronic Bill Presentment and Payment (EBPP) Market