
 China Retail Market | 2026-2036
China Retail Market Size, Share, and Industry Trends Forecast 2026-2036
China Retail Market Insights
China's dual carbon goals under MEE oversight is broadening retailer investment in green logistics and low-emission last-mile networks. JD.com Inc. anchors its competitive edge through captive warehousing and automated sorting centers spanning provincial hubs. Alibaba Group Holding Ltd. leverages Taobao Live and Tmall ecosystems to merge content commerce with instant fulfillment. MINISO Group Holding Limited differentiates via tightly curated SKU velocity and direct sourcing from Guangdong manufacturing belts.
China Retail encompasses the sale of finished consumer goods through physical and digital channels to individual buyers, spanning inventory management, merchandising, payment processing, and delivery coordination with real-time demand forecasting algorithms. The sector serves household consumption, urban lifestyle upgrading, and rural market penetration objectives. Groceries and Electronics distribution channels command the deepest margin pools as Hema Fresh and community group-buy models consolidate fresh produce procurement. Fashion and Home Goods within the Premium price tier attract rising Gen Z spending on domestic designer labels and smart appliance integration.
MIIT data governance rules and SAMR anti-monopoly enforcement shape platform commission structures, merchant data usage, and cross-border e-commerce documentation requirements. GB standards for product labeling and food safety certification under SAMR dictate inventory eligibility for both online marketplaces and physical supermarket chains. Stakeholders must monitor how NMPA and MEE intersecting mandates on packaging recyclability and carbon disclosure reshape supplier qualification protocols and regional distribution licensing.
Market Dynamics
Live-stream commerce integration and MEE carbon mandates are compressing fulfillment timelines while forcing warehouse retrofits across Yangtze River Delta logistics corridors.
Growth Catalysts
- Rural E-commerce Penetration:Tier-three and tier-four city consumers accelerate digital adoption through community group-buy platforms and mobile-first interfaces.
- Dual Carbon Policy Framework:MEE oversight on carbon disclosure drives retailer investment in electric last-mile fleets and renewable-powered distribution centers.
- Live-stream Commerce Infrastructure:Real-time video selling platforms merge content creation with instant checkout, collapsing traditional marketing-to-purchase funnels.
Market Restraints
- Logistics Real Estate Scarcity:Prime warehouse space near Shanghai and Hangzhou commands premium lease rates, squeezing margin structures for mid-market operators.
- GB Standards Compliance Burden:SAMR-mandated product labeling and food safety certification create inventory eligibility bottlenecks for cross-provincial sellers.
- Data Governance Friction:MIIT rules on merchant data usage and platform commission transparency limit algorithmic personalization capabilities.
Strategic Opportunities
- Green Logistics Differentiation:NMPA and MEE intersecting mandates on packaging recyclability create first-mover advantage for retailers with certified circular supply chains.
- Fresh Produce Consolidation:Hema Fresh models demonstrate captive sourcing from agricultural cooperatives, bypassing traditional wholesale layers.
- Smart Appliance Integration:Gen Z households in Guangdong and Jiangsu provinces drive demand for connected home goods with embedded e-commerce reordering.
Industry Challenges
- Cold Chain Talent Scarcity:Fresh grocery expansion requires specialized logistics managers with temperature-controlled inventory expertise that outpaces vocational training output.
- Legacy System Integration:Traditional department store operators struggle to merge ERP architectures with live-stream commerce APIs and real-time inventory APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Retail Market |
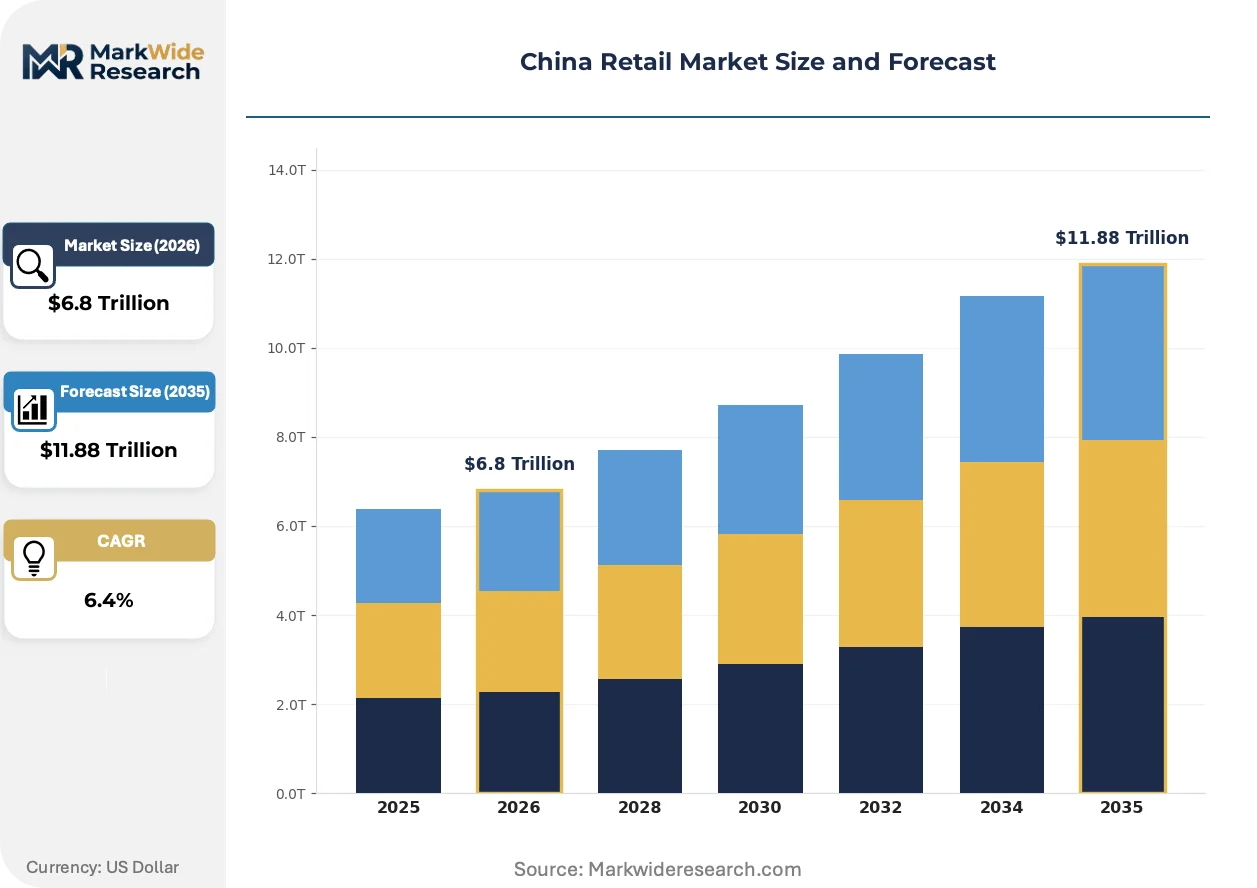
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $11.88 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fashion, Electronics, Home Goods, Groceries Customer Type: Millennials, Gen Z, Baby Boomers, Families Distribution Channel: Online, Supermarkets, Department Stores, Specialty Retailers Price Tier: Premium, Mid-Range, Discount, Luxury |
| Companies Covered | Walmart Inc., China Resources Ng Fung Co. Ltd., Alibaba Group Holding Ltd., MINISO Group Holding Limited, Yonghui Superstores Co. Ltd., JD.com Inc., Pinduoduo Inc., Hema Fresh, Meituan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Retail Market Trends and Innovations
Retail technology deployment is compressing the path from discovery to delivery while regulatory pressure on carbon intensity reshapes physical infrastructure priorities.
Automated sorting centers with robotic pick-and-pack systems are rewriting fulfillment economics for apparel and electronics categories. JD.com and regional logistics operators deploy these systems across Jiangsu and Zhejiang provincial hubs to same-day delivery standards. Labor cost arbitrage that once favored manual warehouses is collapsing as robotic throughput scales.
MIIT data governance rules now require explicit consumer consent for cross-platform data sharing, fragmenting the unified customer profiles that powered recommendation engines. Retailers must rebuild segmentation models on first-party data collected through loyalty programs and direct app engagement. Fashion and beauty segments face the steepest reconfiguration as personalized marketing effectiveness degrades.
Community group-buy models displace traditional supermarket trips in tier-three cities, replacing individual basket economics with collective procurement at neighborhood scale. Neighborhood leaders aggregate orders through WeChat mini-programs, triggering consolidated delivery drops. This pattern concentrates in Henan and Sichuan provinces where household density and price sensitivity align.
China Retail Market Segmentation
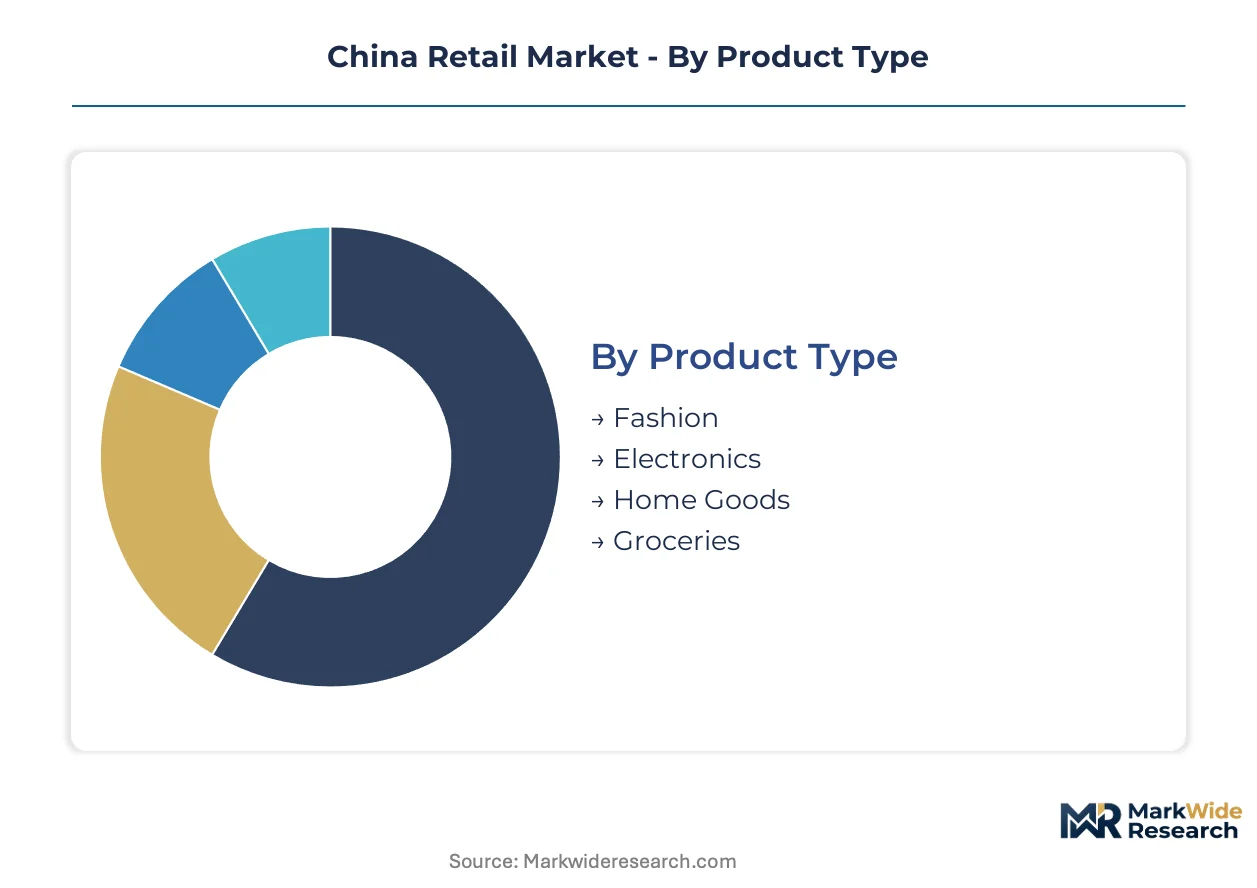
Retail segmentation in China maps purchasing power against infrastructure maturity, revealing where live-stream commerce penetration and cold-chain density create executable market entry points. Distinct consumer cohorts and channel economics demand tailored inventory and fulfillment strategies across provincial markets.
Product Type:
Supply concentration for finished goods clusters around Guangdong manufacturing belts for electronics and Zhejiang textile hubs for fashion, with perishables requiring dispersed cold-chain nodes.
- Electronics:Smartphones, wearables, and home appliances dominate SKU velocity through Tmall and JD flagship stores. Shanghai and Shenzhen households drive replacement cycles for 5G-enabled devices with embedded IoT reordering capabilities.
- Groceries:Fresh produce, packaged foods, and beverages command the steepest logistics investment for temperature-controlled last-mile networks. Hema Fresh and community group-buy platforms consolidate procurement from agricultural cooperatives in Shandong and Sichuan provinces, bypassing traditional wholesale layers.
- Fashion:Apparel and accessories with domestic designer labels gaining share among urban consumers.
- Home Goods:Furniture, decor, and smart appliances integrating with connected home ecosystems.
Today's leader: Groceries. Tomorrow's challenger: Electronics.
Customer Type:
Generational spending patterns diverge sharply on platform preference, with mobile-native cohorts bypassing traditional discovery channels entirely.
- Gen Z:Digital-first consumers born 1997-2012 with highest live-stream commerce engagement and domestic brand affinity. Guangdong and Jiangsu province urban clusters show concentrated demand for limited-edition drops and KOL-curated assortments.
- Families:Multi-generational households with consolidated purchasing authority and bulk-buying behavior. Community group-buy platforms in tier-three cities capture their price-sensitive grocery and household replenishment needs through WeChat mini-programs.
- Millennials:Professionals balancing convenience premium with quality thresholds in childcare and wellness categories.
- Baby Boomers:Retirees with growing digital adoption for health products and traditional retail loyalty.
Gen Z commands platform innovation budgets. Families drive volume consolidation.
Distribution Channel:
Fulfillment economics split between asset-heavy captive networks and platform-mediated marketplace models.
- Online:E-commerce platforms, brand direct-to-consumer sites, and social commerce integrations. JD's automated sorting centers and Alibaba's instant delivery infrastructure anchor same-day service standards in Yangtze River Delta metropolitan clusters.
- Specialty Retailers:Category-focused chains with curated assortments and experiential formats. MINISO's tightly controlled SKU velocity and direct Guangdong sourcing demonstrate margin capture through manufacturing belt proximity.
- Supermarkets:Full-format and community-sized stores with fresh produce emphasis.
- Department Stores:Legacy anchors struggling to merge ERP systems with live-stream commerce APIs.
Online absorbs capital expenditure. Specialty Retailers extract margin through sourcing control.
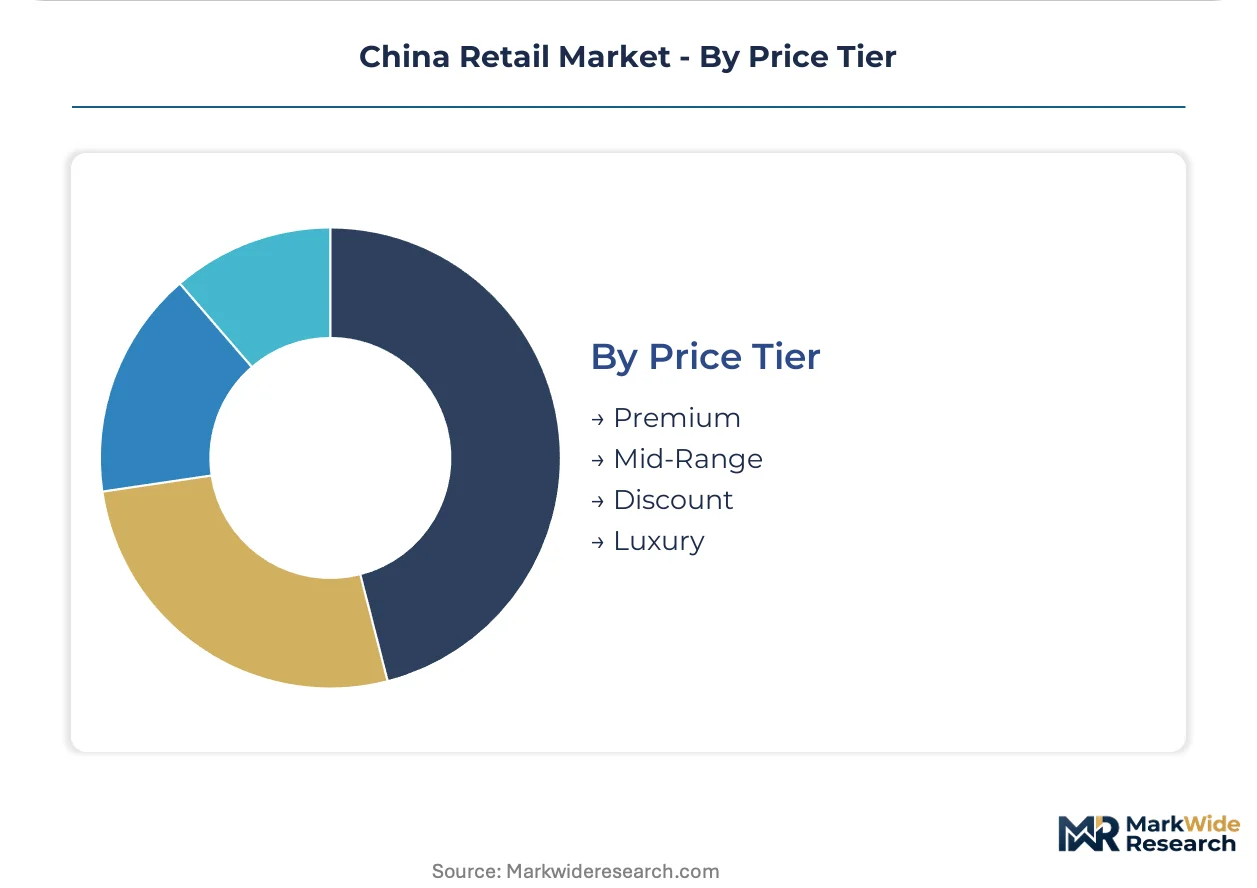
Price Tier:
Certification grade and carbon disclosure status increasingly stratify pricing architecture under SAMR and MEE mandates.
- Premium:Mid-to-high positioning with verified quality credentials and sustainability claims. Domestic designer labels and smart appliance integrations attract Yangtze River Delta households upgrading lifestyle categories.
- Discount:Value-focused positioning through private label and factory-direct sourcing. Community group-buy platforms and Pinduoduo ecosystem penetration in Henan and Sichuan provinces demonstrate volume-at-scale economics.
- Luxury:Ultra-high positioning with heritage positioning and exclusive distribution.
- Mid-Range:Mass-market positioning balancing quality signals with accessibility.
Premium captures margin expansion. Discount gains volume through rural penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Logistics talent pools concentrate around Shanghai and Hangzhou, anchoring automated fulfillment networks that service the broader Yangtze River Delta metropolitan cluster. These skilled workforces enable same-day delivery standards that tier-three cities now demand. Provincial governments compete to attract distribution center investment through specialized vocational training programs.
Yangtze River Delta
Shanghai and Hangzhou households drive premium electronics replacement cycles and fresh grocery consolidation through Hema Fresh flagship stores. MEE carbon disclosure mandates accelerate warehouse retrofits toward renewable-powered operations. Suzhou and Ningbo logistics corridors host JD.com's automated sorting centers that anchor regional same-day delivery standards.
Pearl River Delta
Guangdong manufacturing belts supply MINISO's tightly curated SKU velocity and direct sourcing advantages for consumer goods. SAMR-mandated GB standards for product labeling create inventory eligibility protocols for cross-provincial sellers. Shenzhen and Guangzhou urban clusters demonstrate concentrated Gen Z demand for limited-edition domestic designer labels.
Sichuan-Chongqing
Community group-buy platforms capture price-sensitive household replenishment needs through WeChat mini-programs in dense Chengdu neighborhoods. MIIT data governance rules require explicit consumer consent for cross-platform data sharing, fragmenting unified customer profiles. Chongqing's inland port infrastructure supports distribution reach into western provinces with lower logistics real estate costs.
Shandong Peninsula
Agricultural cooperatives in Shandong province supply Hema Fresh and community group-buy platforms with captive fresh produce sourcing. SAMR food safety certification under GB standards dictates inventory eligibility for temperature-controlled distribution. Qingdao and Jinan logistics nodes demonstrate expanding cold-chain density for perishable goods penetration.
Henan Province
Tier-three city consumers in Zhengzhou and surrounding satellite cities accelerate digital adoption through Pinduoduo ecosystem penetration and mobile-first interfaces. Dual carbon policy framework under MEE oversight drives retailer investment in electric last-mile fleets. The province's central geographic position supports consolidated delivery drops for community group-buy models.
China Retail Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's retail sector, with captive warehousing networks facing platform-mediated marketplace models. The market structure splits between asset-intensive logistics operators and ecosystem orchestrators that outsource fulfillment. Three archetypes dominate: integrated captive networks, platform marketplaces with instant delivery infrastructure, and specialty retailers with manufacturing belt proximity. Competitive moves concentrate on warehouse automation deployment and green logistics certification under MEE mandates.
Within the integrated logistics tier, JD.com Inc. anchors automated fulfillment economics through provincial hub coverage. Alibaba Group Holding Ltd. and Pinduoduo Inc. occupy positions as ecosystem orchestrators merging content commerce with merchant marketplaces. MINISO Group Holding Limited exemplifies the specialty retail archetype through Guangdong manufacturing belt proximity and tightly controlled SKU velocity. These three patterns represent the dominant strategic configurations reshaping competitive positioning.
| Leading Market Players |
|---|
| Walmart Inc. |
| China Resources Ng Fung Co. Ltd. |
| Alibaba Group Holding Ltd. |
| MINISO Group Holding Limited |
| Yonghui Superstores Co. Ltd. |
| JD.com Inc. |
| Pinduoduo Inc. |
| Hema Fresh |
| Meituan |
| Others |
Pricing and Supply Chain Analysis
Gen Z households in Guangdong and Jiangsu provinces anchor premium-tier spending on domestic designer labels and smart appliance integrations, compressing margin structures for mid-market operators unable to match certification-grade positioning under SAMR mandates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market, with certification grade under GB standards and volume scale driving differentiation. Premium tiers capture margin expansion through verified sustainability claims and NMPA packaging compliance, while discount positioning gains volume via Pinduoduo ecosystem penetration in Henan and Sichuan provinces. Cost compression in mid-market tiers is intensifying because logistics real estate scarcity near Shanghai and Hangzhou squeezes fulfillment economics. Families in tier-three cities demonstrate highest price sensitivity through community group-buy aggregation, whereas Yangtze River Delta urban clusters show lowest sensitivity for instant delivery premiums.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong manufacturing belts for electronics and Zhejiang textile hubs for fashion, where concentrated production of semiconductors, display panels, and synthetic fabrics feeds national distribution networks. Raw material dependencies span rare earth elements from Jiangxi province, agricultural outputs from Shandong cooperatives, and petrochemical feedstocks from Ningbo refining complexes. Tariff exposure on cross-provincial inventory movements under evolving MIIT data governance rules creates compliance friction for marketplace sellers. Distribution runs through JD.com's automated provincial hubs and Alibaba's instant delivery infrastructure, with last-mile density determining service-tier eligibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China Retail operates as a stable compounder, with rural e-commerce penetration across tier-three and tier-four cities providing steady volume expansion underpinned by MEE carbon policy enforcement.
For Market Incumbents: Hedge against margin erosion by securing captive warehousing in lower-cost Chongqing and Henan logistics corridors before prime Yangtze River Delta real estate premiums escalate further. Invest in NMPA-certified circular supply chains to preempt competitor green logistics differentiation under tightening MEE packaging mandates. Channel control through direct agricultural cooperative sourcing, as demonstrated by Hema Fresh models, defends against community group-buy platform disintermediation. For New Entrants and Emerging Players: Live-stream commerce infrastructure offers the most penetrable wedge for building audience-to-purchase funnels without legacy ERP integration burdens. Target tier-three city family segments in Henan and Sichuan provinces where price-sensitive bulk-buying behavior concentrates through WeChat mini-programs. A mobile-first community leader recruitment strategy bypasses capital-intensive captive fulfillment networks. For Investors and Strategic Acquirers: Domestic consumer goods conglomerates with manufacturing belt proximity are the most active acquirers in this space, seeking SKU velocity control and direct sourcing advantages. Long-term viability favors asset-light platform orchestrators over capital-heavy logistics operators as robotic automation scales. Watch for MEE carbon disclosure mandate acceleration as the inflection signal for green logistics certification premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Green Logistics Certification | NMPA and MEE packaging mandates reward first-movers with verified circular supply chains in Yangtze River Delta corridors. |
| Automated Sorting Deployment | JD.com's robotic pick-and-pack systems in Jiangsu and Zhejiang hubs rewrite fulfillment economics for same-day delivery standards. |
| Community Group-Buy Expansion | WeChat mini-program aggregation in Henan and Sichuan provinces displaces traditional supermarket trips through collective procurement. |
| Direct Agricultural Sourcing | Hema Fresh captive procurement from Shandong cooperatives bypasses wholesale layers and secures temperature-controlled inventory. |
| Live-Stream Commerce Integration | Taobao Live and KOL-curated assortments collapse marketing-to-purchase funnels for Gen Z limited-edition drops. |
Research Methodology
Multiple input streams — executive interviews with retail operations directors and logistics planners, merchant platform data from marketplace operators, and regulatory filings with SAMR and MIIT — were reconciled against customs records and provincial economic statistics. Primary engagement spanned category buyers at supermarket chains, cold-chain logistics managers, and community group-buy neighborhood leaders across tier-three cities. Secondary validation drew from NMPA packaging standards documentation, MEE carbon disclosure protocols, and Yangtze River Delta logistics corridor investment disclosures. Bottom-up SKU velocity modeling and top-down metropolitan consumption clustering were triangulated to anchor projections.
Reconciliation of demand-side survey data with supply-side capacity announcements generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, customer generation cohort, distribution channel economics, and price tier certification status. CAGRs were derived from trend extrapolation of rural digital adoption curves and logistics automation deployment schedules. Forecast inputs incorporated MEE policy implementation timelines and MIIT data governance enforcement patterns.
The model holds under continued dual carbon policy enforcement and stable provincial logistics investment; deviation in SAMR anti-monopoly escalation or logistics real estate supply shocks would shift trajectory bounds. Forecasts reflect documented assumptions on live-stream commerce penetration rates and cold-chain talent pipeline expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retailing
Philippines Retail Industry Market
Retailing
Electronics Retailing Market
Retailing
Gift Baskets Market
Retailing
Subscription Box Market
Retailing
Out-Door Signage Market
Retailing
Consumer Products and Retail Market
Retailing
Retail Signage Market
Retailing
Global Food and Non-Food Retail Market
Retailing
Floor Mat Rental Service Market
Retailing
United Kingdom Hardware Stores Retail Market
Retailing
In Store Signage Market
Retailing
Floor Displays Market
Retailing
Vietnam Retail Market
Retailing
Qatar Retail Market
Retailing
Furniture Rental Service Market
Retailing
Asia-Pacific Duty-Free Retailing Market