
 United States Telehealth Pre-Natal Services Market | 2026-2036
United States Telehealth Pre-Natal Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Telehealth Pre-Natal Services Market Insights
Texas is narrowing its maternal care access gap through telehealth infrastructure investments in Houston and Dallas-Fort Worth hospital networks. Maven Clinic Co. leverages employer-sponsored benefit channels to reach working mothers across Fortune 500 companies. Pomelo Care, Inc. specializes in value-based contracts with Medicaid managed care organizations. MCH Ventures, Inc. (Mahmee) anchors its platform on care coordination between patients and community health workers.
Telehealth pre-natal services encompass remote clinical consultations, biometric monitoring, and patient education delivered through digital channels during pregnancy, typically integrating HIPAA-compliant video platforms with FDA-cleared wearable devices for blood pressure and fetal heart rate tracking. Virtual consultations occupy the largest service type segment due to established reimbursement codes, while remote monitoring represents the fastest-expanding category as connected device accuracy improves. Mobile apps dominate the technology dimension through patient engagement scale, though wearable devices command premium pricing through hardware-software integration.
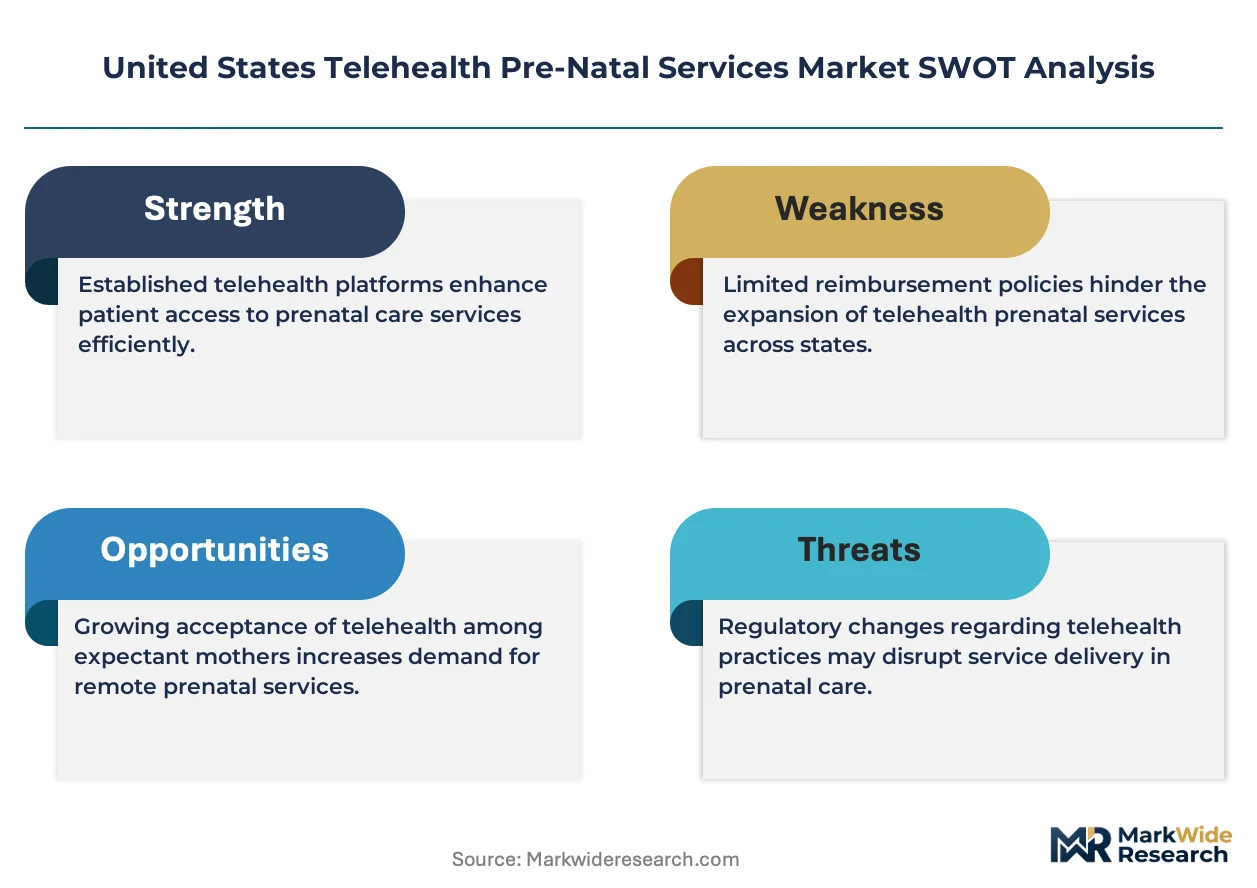
FDA oversight of Software as a Medical Device (SaMD) and CMS telehealth reimbursement rules shape product development timelines and market access pathways for platform vendors. HIPAA security requirements and state-level medical licensing compacts create compliance complexity that favors established operators with legal infrastructure. Stakeholders must monitor state Medicaid waiver expansions and FDA guidance on AI-enabled fetal monitoring algorithms to anticipate competitive positioning shifts.
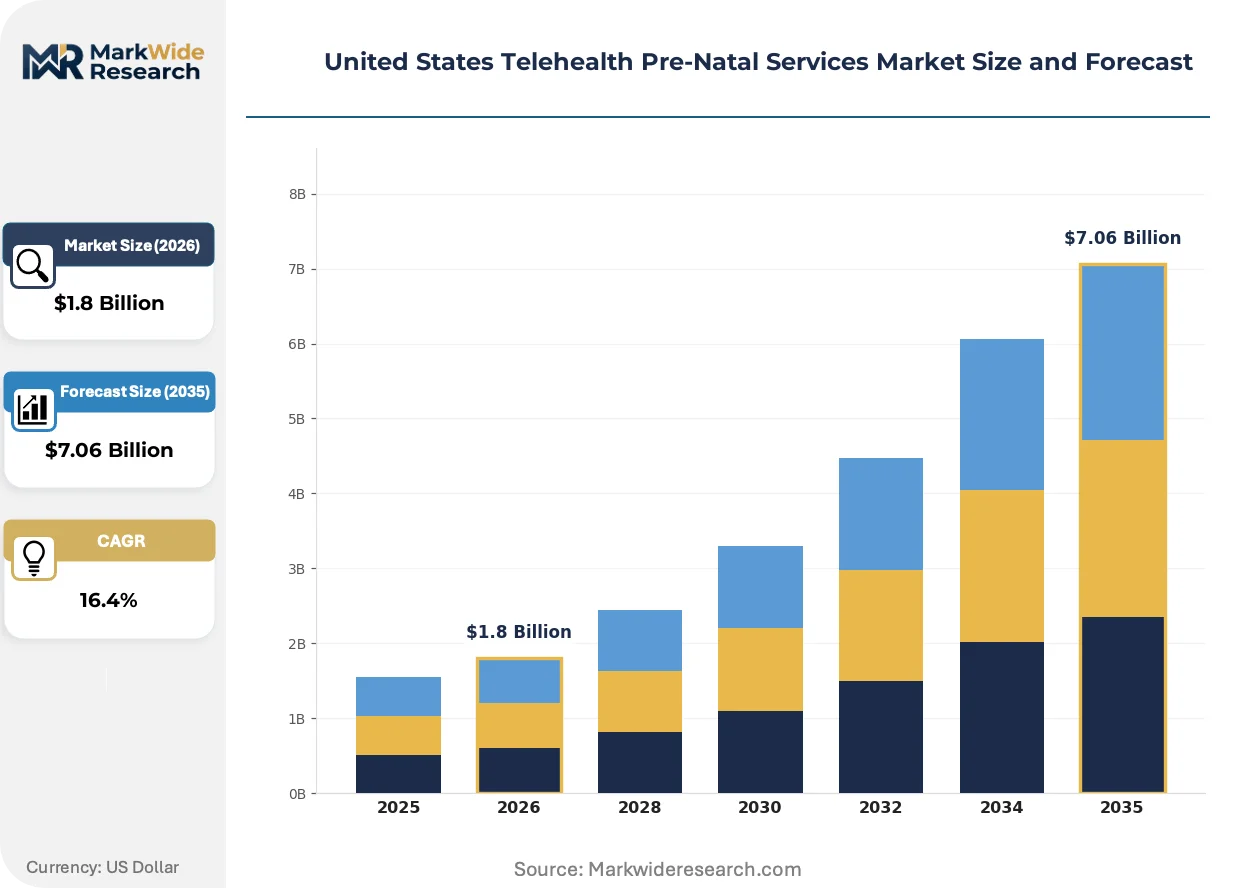
Market Dynamics
Medicaid reimbursement parity under CMS is compressing the activation energy required for hospital systems to launch virtual prenatal programs, pulling capital toward platform infrastructure and away from physical clinic expansion.
Growth Catalysts
- CMS Telehealth Reimbursement Parity:Federal policy alignment between virtual and in-person prenatal visit rates removes the primary financial disincentive for OB-GYN practices adopting remote care models.
- Maternity Care Deserts:Closure of rural obstetric units across Mississippi, Alabama, and Georgia is forcing health systems to deploy remote monitoring as the only viable coverage mechanism.
- Bluetooth-Enabled Blood Pressure Cuffs:FDA-cleared wearable accuracy improvements allow home-based preeclampsia surveillance to replace weekly in-office monitoring for high-risk pregnancies.
Market Restraints
- State Medical Licensing Compacts:Incomplete adoption of the Interstate Medical Licensure Compact restricts multi-state telehealth practice, fragmenting provider pool availability.
- Broadband Infrastructure Gaps:FCC broadband deployment maps reveal persistent connectivity deserts in rural Texas and Appalachia that degrade video consultation quality.
- Software as Medical Device Classification:FDA SaMD oversight of AI-enabled fetal heart rate interpretation extends product development timelines by 18-24 months for algorithm-dependent platforms.
Strategic Opportunities
- Medicaid Managed Care Waivers:State-level 1115 waiver expansions in Tennessee and South Carolina create value-based contracting pathways for comprehensive virtual prenatal bundles.
- Community Health Worker Integration:CMS-funded CHW reimbursement codes enable platform vendors to embed local navigators into remote care workflows for Medicaid populations.
- Remote Patient Monitoring CPT Codes:New CMS billing categories for continuous glucose and blood pressure monitoring create sustainable revenue streams beyond synchronous video visits.
Industry Challenges
- HIPAA-Compliant Platform Architecture:Small regional health systems lack internal cybersecurity expertise to evaluate vendor security postures, slowing procurement cycles.
- Interoperability with EHR Systems:Epic and Cerner integration requirements demand costly API development that strains mid-size telehealth platform budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Telehealth Pre-Natal Services Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Consultations, Remote Monitoring, Educational Workshops, Mental Health Support Technology: Mobile Apps, Video Conferencing, Wearable Devices, Cloud Platforms Delivery Mode: Synchronous, Asynchronous, Blended Learning, Group Sessions End User: Pregnant Women, Healthcare Providers, Family Members, Care Coordinators |
| Companies Covered | Maven Clinic Co., Pomelo Care, Inc., MCH Ventures, Inc. (Mahmee), Cayaba Care, Labcorp (Ovia Health), Delfina, Oula Health, Inc., Babyscripts, Teleperinatal, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Telehealth Pre-Natal Services Market Trends and Innovations
Platform architectures are migrating from transactional video visit models toward continuous care coordination systems that embed remote monitoring, asynchronous messaging, and automated risk stratification into unified workflows.
Fetal heart rate monitoring is migrating from clinic-based cardiotocography to consumer wearable patches that transmit continuous data streams to maternal-fetal medicine specialists. High-risk pregnancy centers at Baylor College of Medicine and Emory University are piloting these devices for home antenatal testing. This shift is migrating from episodic in-person surveillance toward distributed monitoring models that compress specialist consultation cycles from weeks to hours.
CMS guidance on remote therapeutic monitoring is expanding reimbursable service categories beyond synchronous consultation toward asynchronous data review and care coordination. The policy revision enables platform vendors to bill for clinician time spent analyzing biometric trends and adjusting care plans. Medicaid managed care organizations in Texas and Florida are restructuring provider contracts to capture these expanded reimbursement pathways.
Employer-sponsored benefits are displacing direct-to-consumer channels as the primary patient acquisition vector for virtual prenatal platforms. Fortune 500 HR departments in technology and financial services verticals are contracting comprehensive maternal health benefits that bundle telehealth access with care navigation. This procurement pattern concentrates most visibly in California and New York metropolitan employment centers before diffusing to secondary markets.
United States Telehealth Pre-Natal Services Market Segmentation
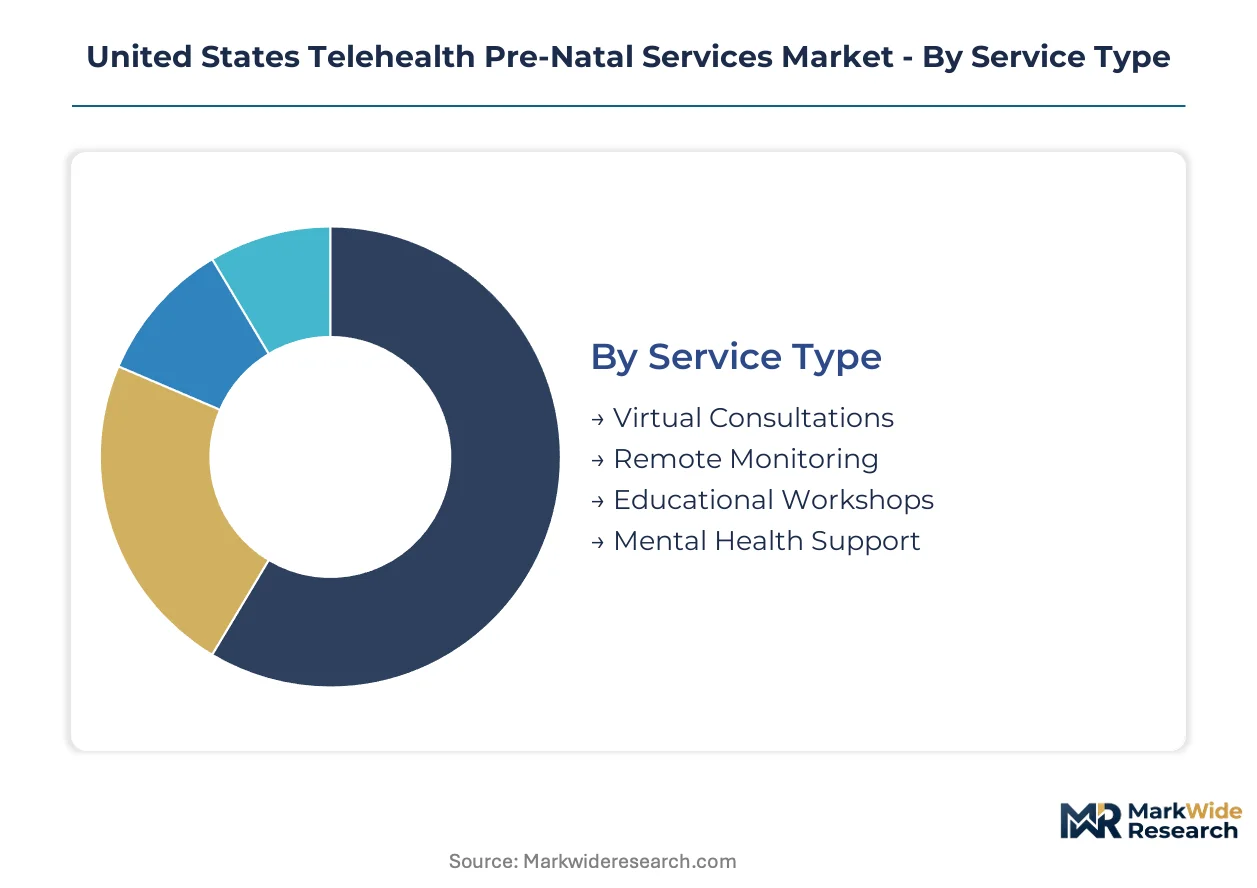
Telehealth pre-natal services fragment across four operational dimensions that determine reimbursement pathways, technology procurement cycles, and patient engagement intensity. Each segmentation layer carries distinct margin profiles and regulatory exposure that shape vendor positioning strategies.
Service Type:
Virtual consultations turn over fastest with weekly visit cadences, while educational workshops cycle quarterly and mental health support programs extend across trimesters.
- Virtual Consultations:Real-time video encounters between OB-GYNs and patients for routine prenatal checkups, symptom triage, and medication management. Demand concentrates in Medicaid managed care populations across Texas and Florida where clinic deserts force remote-first care models under CMS reimbursement parity.
- Remote Monitoring:Continuous biometric surveillance through FDA-cleared blood pressure cuffs and fetal heart rate patches transmitting data to maternal-fetal medicine specialists. Southeast health systems deploy these for preeclampsia surveillance in high-risk pregnancies where weekly in-office visits prove logistically impossible.
- Educational Workshops:Structured curricula covering nutrition, labor preparation, and newborn care delivered through scheduled virtual sessions.
- Mental Health Support:Perinatal depression and anxiety interventions through licensed behavioral health providers integrated into prenatal care teams.
Virtual consultations anchor the volume base while remote monitoring gains share at the steepest rate.
Technology:
Mobile apps command the lowest per-unit deployment cost, wearable devices carry premium hardware margins, and cloud platforms require the longest enterprise sales cycles.
- Mobile Apps:Patient-facing interfaces for appointment scheduling, symptom tracking, and asynchronous messaging with care teams. These platforms scale most efficiently across employer-sponsored benefit programs targeting working mothers in California and New York metropolitan employment centers.
- Wearable Devices:Bluetooth-enabled blood pressure monitors and fetal heart rate patches with FDA 510(k) clearance for home-based clinical surveillance. Accuracy improvements now allow these devices to replace clinic-based cardiotocography for antenatal testing at Baylor College of Medicine and Emory University pilot programs.
- Video Conferencing:HIPAA-compliant platforms enabling synchronous clinical encounters with integrated EHR documentation workflows.
- Cloud Platforms:Backend infrastructure for data aggregation, risk stratification algorithms, and population health analytics serving health system clients.
Mobile apps dominate patient touchpoint volume while wearable devices expand most quickly through value-based contracting with Medicaid managed care organizations.
Delivery Mode:
Synchronous delivery demands real-time provider capacity, asynchronous models compress labor costs per encounter, and blended approaches require the most complex care coordination infrastructure.
- Synchronous:Real-time video or audio encounters requiring immediate provider availability and scheduled appointment slots. This mode captures the majority of reimbursable telehealth encounters under existing CMS billing codes.
- Asynchronous:Store-and-forward consultations where patients submit symptoms or images for delayed clinician review and response. CMS remote therapeutic monitoring guidance now enables billing for clinician time spent analyzing biometric trends outside live encounters.
- Blended Learning:Hybrid models combining self-paced educational modules with scheduled live check-ins and automated risk alerts.
- Group Sessions:Multi-patient virtual gatherings for childbirth education, breastfeeding support, and peer community building.
Synchronous delivery anchors reimbursement revenue while asynchronous models climb the fastest as platforms restructure workflows around continuous rather than episodic care.
End User:
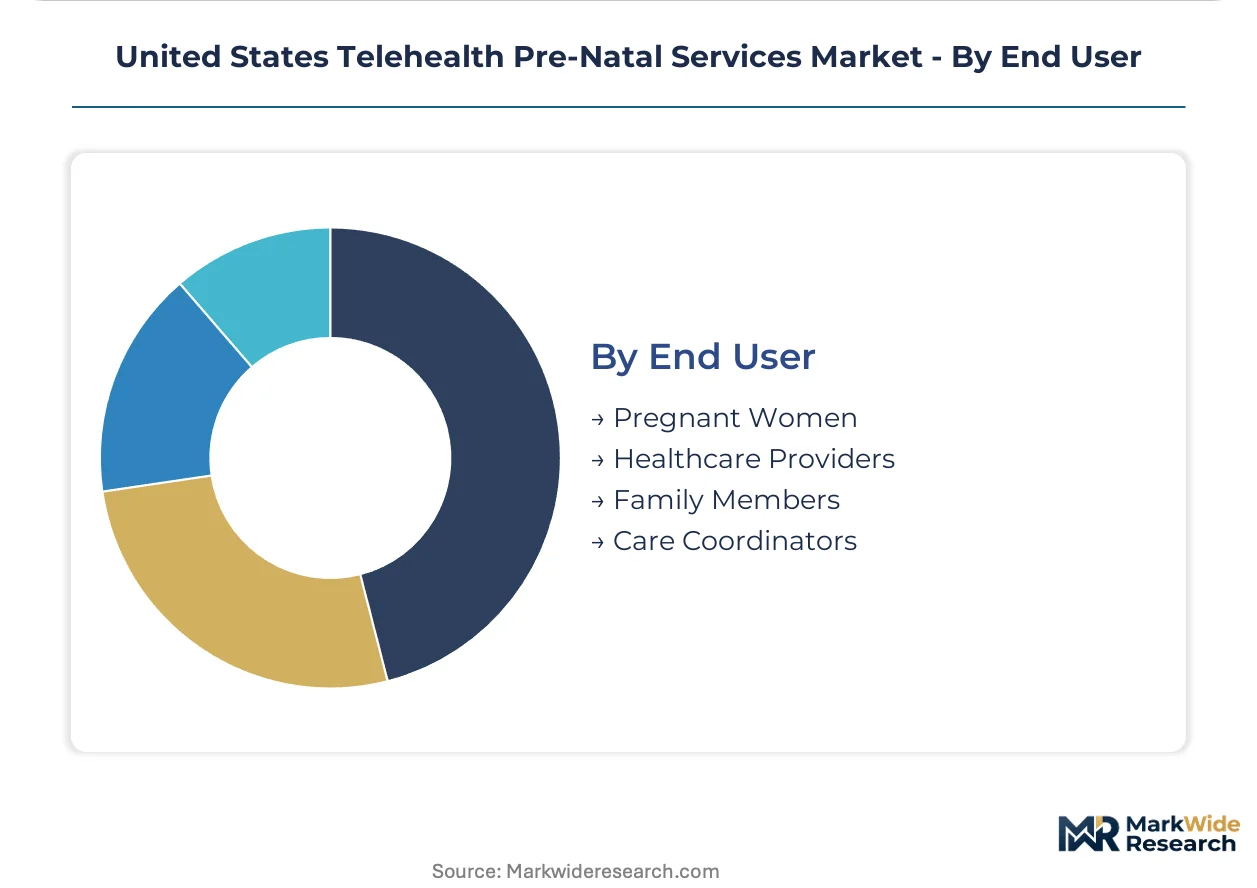
Pregnant women drive direct utilization metrics, healthcare providers control procurement decisions, and care coordinators determine platform stickiness through workflow integration depth.
- Pregnant Women:Primary service recipients accessing consultations, monitoring devices, and educational content through employer benefits or Medicaid programs. Rural Mississippi and Alabama populations represent concentrated demand where maternity care deserts eliminate in-person alternatives.
- Healthcare Providers:OB-GYNs, maternal-fetal medicine specialists, and nurse midwives utilizing platforms for patient management and clinical documentation. Epic and Cerner integration requirements dominate their procurement criteria.
- Family Members:Partners and extended family participating in educational workshops and supporting remote monitoring adherence.
- Care Coordinators:Community health workers and case managers embedded in Medicaid workflows through CMS-funded reimbursement codes.
Pregnant women generate the utilization base while care coordinators represent the steepest expansion trajectory as states deploy CHW integration for Medicaid population management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of Software as a Medical Device and CMS telehealth reimbursement parity anchor the United States market, with state-level Medicaid waivers creating divergent access pathways across sub-regional healthcare systems.
Southeast
Maternity care deserts across Mississippi, Alabama, and Georgia drive telehealth adoption as rural obstetric unit closures eliminate in-person alternatives. CMS-funded community health worker reimbursement codes enable Medicaid managed care organizations to embed local navigators into remote prenatal workflows. Emory University in Atlanta pilots FDA-cleared fetal heart rate patches for home-based antenatal testing of high-risk pregnancies.
Texas
Houston and Dallas-Fort Worth hospital networks deploy remote monitoring infrastructure to narrow maternal care access gaps in rural counties. Texas Medicaid 1115 waiver expansions create value-based contracting pathways for comprehensive virtual prenatal bundles with managed care organizations. Baylor College of Medicine anchors high-risk pregnancy telehealth pilots that compress specialist consultation cycles from weeks to hours.
California
Employer-sponsored benefit channels concentrate patient acquisition for virtual prenatal platforms among Fortune 500 technology and financial services workforces. HIPAA-compliant platform vendors scale mobile app deployments across Los Angeles and San Francisco metropolitan employment centers. State-level medical licensing requirements interact with incomplete Interstate Medical Licensure Compact adoption to fragment multi-state provider pool availability.
Florida
Medicaid managed care organizations restructure provider contracts to capture expanded CMS remote therapeutic monitoring reimbursement pathways for asynchronous data review. Rural connectivity gaps in the Panhandle degrade video consultation quality despite FCC broadband deployment initiatives. Miami-Dade and Tampa hospital systems integrate remote blood pressure surveillance for preeclampsia management in high-risk populations.
Northeast Corridor
New York metropolitan HR departments contract comprehensive maternal health benefits bundling telehealth access with care navigation for working mothers. Epic and Cerner EHR integration requirements dominate procurement criteria for OB-GYN practices selecting platform vendors. Incomplete Interstate Medical Licensure Compact participation across New York, New Jersey, and Pennsylvania restricts multi-state telehealth practice for maternal-fetal medicine specialists.
United States Telehealth Pre-Natal Services Market Competitive Landscape
Employer-sponsored benefit specialists and Medicaid value-based contractors split the market into distinct procurement channels with divergent margin profiles and contract structures. Platform vendors face tiered competitive pressure based on EHR integration depth, FDA device clearance portfolios, and care coordination workflow sophistication. Two archetypes dominate: technology-enabled care delivery platforms and clinical service organizations with embedded digital infrastructure. Competitive moves concentrate on strategic partnerships with health systems and portfolio diversification into remote patient monitoring hardware.
Within the employer benefit channel, Maven Clinic Co. and Ovia Health represent archetypes of scale-driven platform deployment, while Pomelo Care, Inc. and Mahmee occupy positions within Medicaid-centric value-based contracting. Babyscripts exemplifies hardware-software integration approaches through its remote monitoring device deployments. These named entities anchor industry-level commentary on how vendor positioning stratifies across reimbursement pathway specialization rather than technology differentiation alone.
| Leading Market Players |
|---|
| Maven Clinic Co. |
| Pomelo Care, Inc. |
| MCH Ventures, Inc. (Mahmee) |
| Cayaba Care |
| Labcorp (Ovia Health) |
| Delfina |
| Oula Health, Inc. |
| Babyscripts |
| Teleperinatal, Inc. |
| Others |
Pricing and Supply Chain Analysis
Interstate freight corridors linking Shenzhen manufacturing hubs to Los Angeles and Long Beach ports transmit cost volatility through Bluetooth-enabled blood pressure cuff and fetal heart rate patch supply chains, concentrating hardware margins among FDA-cleared device vendors while compressing software platform pricing power across Medicaid managed care contracting channels.
Pricing Analysis
Geographic price spreads between employer-sponsored benefit channels in California and Medicaid reimbursement pathways in Mississippi and Alabama exceed threefold for equivalent virtual consultation bundles. Pricing stratifies across premium hardware-software integrated tiers, standard SaaS subscription models, and economy per-visit transactional structures. Cost compression in the economy tier intensifies as rural health systems consolidate procurement through group purchasing organizations. Medicaid managed care organizations exhibit highest price sensitivity, while Fortune 500 HR departments demonstrate lowest sensitivity due to care navigation bundling.
Supply Chain Analysis
Tariff exposure between China and the United States dominates component cost planning for wearable device manufacturers sourcing Bluetooth modules and biometric sensors. Hardware assembly concentrates in China, Mexico, and Malaysia, while cloud infrastructure rests on domestic hyperscaler capacity. Raw material dependencies span lithium-ion battery cells, medical-grade silicone, and semiconductor wafers. Single-source vulnerability persists for FDA-cleared fetal heart rate patch substrates. Distribution runs through health system procurement committees and direct-to-employer benefit platform sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth pre-natal services fragment across reimbursement pathway specialization, creating niches for vendors that align platform architecture with either employer benefit procurement cycles or Medicaid value-based contracting workflows.
For Market Incumbents: Insulate core revenue streams by deepening Epic and Cerner EHR integration moats against emerging API-native competitors, and secure backward integration into FDA-cleared remote monitoring hardware to capture device margins currently leaking to third-party suppliers. The threat of algorithm-native platforms with superior risk stratification capabilities demands preemptive investment in AI-enabled fetal monitoring R&D pipelines. For New Entrants and Emerging Players: Establish a beachhead in community health worker-embedded care coordination workflows across Tennessee and South Carolina Medicaid 1115 waiver expansions, where incumbent footprint remains light and CMS reimbursement codes create immediate revenue viability. The perinatal mental health support segment offers the most penetrable white space, with employer-sponsored benefit channels in secondary metropolitan markets representing the optimal go-to-market angle. For Investors and Strategic Acquirers: Platform vendors with demonstrated value-based contract performance in Texas and Florida Medicaid managed care organizations present the most compelling acquisition target archetype for long-term viability across the 5-10 year reimbursement policy horizon. The signal to watch is state-level 1115 waiver expansion velocity, which serves as the inflection indicator for addressable market step-function growth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | FDA clearance for fetal heart rate patches unlocks Medicare and Medicaid reimbursement at Baylor College of Medicine pilot sites. |
| Hospital System Partnership | Emory University and Houston Methodist partnerships validate remote monitoring efficacy for high-risk pregnancy management. |
| Software Companion Development | Epic-integrated risk stratification modules reduce clinician workflow friction and accelerate procurement cycles. |
| Reimbursement Strategy | CMS remote therapeutic monitoring billing category capture enables sustainable revenue beyond synchronous video visits. |
| Geographic Expansion | Southeast maternity care desert penetration leverages Mississippi and Alabama clinic closures for first-mover positioning. |
Research Methodology
A spread of perspectives from maternal-fetal medicine specialists, Medicaid managed care contract officers, employer benefits directors, and telehealth platform product managers converged on the working assumptions underpinning this analysis. Primary interviews with clinicians at Baylor College of Medicine and Emory University supplemented secondary validation through FDA 510(k) device clearance databases, CMS telehealth reimbursement guidance documents, and state Medicaid waiver filing records. Bottom-up sizing of virtual consultation volumes and remote monitoring device deployments triangulated against top-down health system IT spending allocations.
Demand-supply balance across synchronous provider capacity and asynchronous workflow automation shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompass service type, technology platform, delivery mode, and end-user archetype, with regional Medicaid policy variation as the industry-specific dimension. CAGRs derived from provider adoption curve analysis and reimbursement code expansion trajectories, incorporating continuous glucose monitoring CPT code uptake and fetal heart rate patch clinical validation timelines as forecast inputs.
Sensitivities concentrate around FDA SaMD classification delays for AI-enabled monitoring algorithms and state Medicaid waiver approval velocity. Forecasts reflect documented assumptions regarding CMS reimbursement parity maintenance and Interstate Medical Licensure Compact adoption rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine Service Market
Telemedicine
India Telehealth Services Market
Telemedicine
Global Telepsychiatry Market
Telemedicine
Telehealth Kiosk Market
Telemedicine
Global Telehealth Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Global Telemedicine Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
India Telemedicine Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
US Virtual Visits Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Tele-Care Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Oceania Telemedicine Market