
 In-Ear-Monitors (Iems) Market | 2026-2036
In-Ear-Monitors (Iems) Market Size, Share, and Industry Trends Forecast 2026-2036
In-Ear-Monitors (Iems) Market Foresight
Acoustic engineering talent is collapsing across Western audio hubs, forcing manufacturers to redistribute R&D functions. 64 Audio leverages its Colorado-based custom-lab infrastructure to sustain artisanal fitting workflows that Asian competitors struggle to replicate. Shure dominates stage-monitor procurement channels for touring musicians, while Empire Ears specializes in hybrid driver configurations that command premium positioning among audiophile collectors.
In-ear monitors are precision-fit electroacoustic transducers that seal within the ear canal to deliver isolated, high-fidelity audio reproduction, typically employing multiple balanced armature drivers or hybrid dynamic armature architectures with crossover networks dividing frequency bands. Wired configurations remain the margin pool for professional stage use where latency tolerance is zero, while wireless Bluetooth codecs are displacing cable dependency among casual listeners. Balanced armature technology leads in multi-driver customs for musicians, whereas planar magnetic drivers represent the fastest-growing niche among audiophiles seeking ultra-low distortion.
FCC equipment authorization governs wireless IEM transmission bands in the United States, directly constraining product architectures for unlicensed stage monitoring. The EU's CE marking and RoHS substance restrictions shape driver magnet materials and solder compositions for all products entering European distribution. Stakeholders must monitor regulatory divergence between RF spectrum allocations in North America and Asia-Pacific markets when planning wireless platform roadmaps.
Market Dynamics
Balanced armature driver production concentrates in Shenzhen's manufacturing corridor, forcing Western brands to negotiate component allocation against domestic Chinese IEM makers who receive preferential supply access.
Growth Catalysts
- RoHS substance restrictions:The EU directive banning lead and cadmium in electronics is accelerating magnet material substitution toward rare-earth alternatives, opening procurement contracts for compliant foundries.
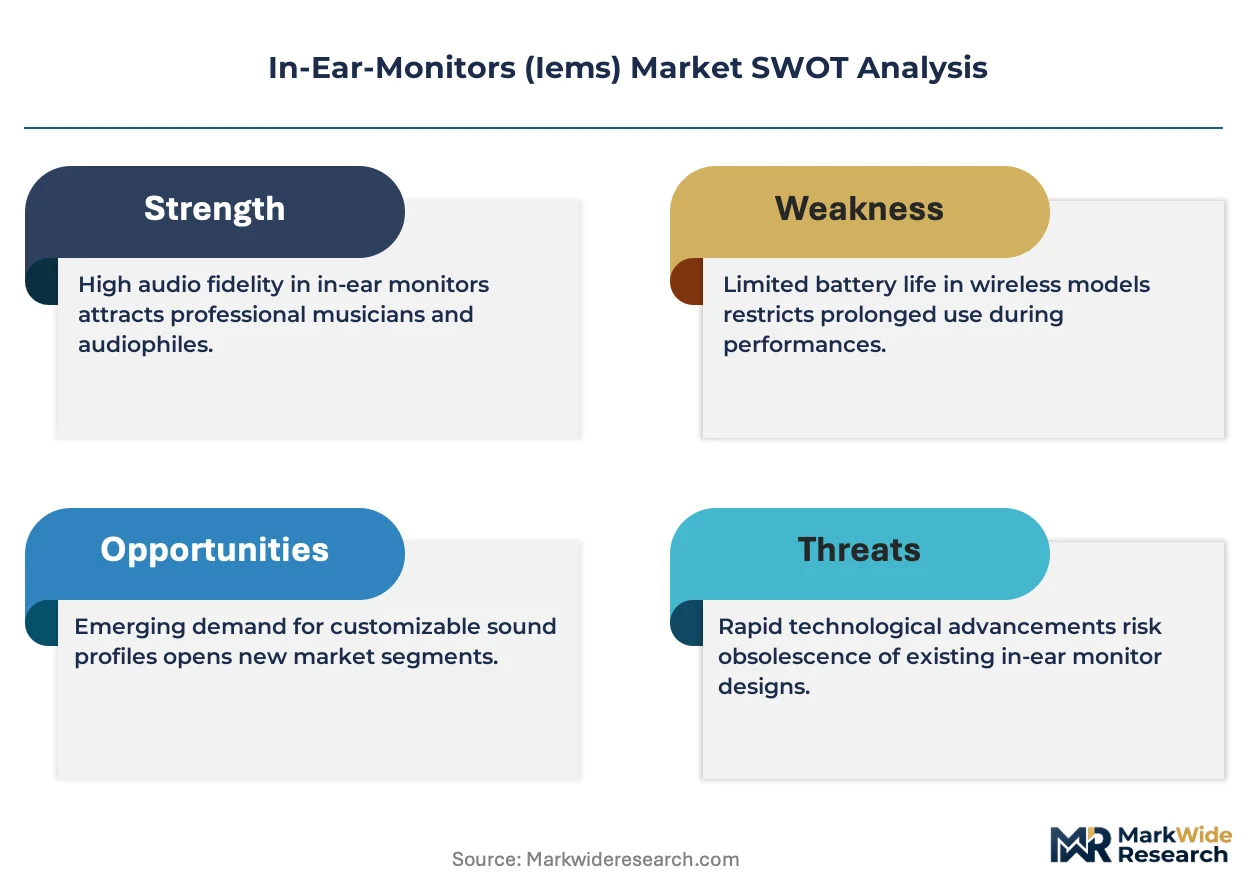
- Live touring resurgence:Professional audio engineers on concert circuits demand zero-latency wired monitors, sustaining premium SKU volumes despite consumer wireless migration.
- Hybrid driver architectures:Combining dynamic woofers with balanced armature tweeters is expanding frequency response capabilities for audiophile collectors seeking studio-grade fidelity.
Market Restraints
- Neodymium price volatility:Rare-earth magnet costs fluctuate with Chinese export quotas, compressing margins for multi-driver customs requiring six to twelve armatures per earpiece.
- Shenzhen supply concentration:Over 70 percent of balanced armature output originates from three contract manufacturers, creating single-source vulnerability for brands lacking captive production.
- Bluetooth codec latency:Consumer wireless adoption faces hard technical ceilings for stage monitoring, where aptX and LDAC protocols still introduce perceptible delay.
Strategic Opportunities
- India's BIS certification pathway:New mandatory electronics testing standards create first-mover advantage for brands establishing compliant distribution before local competitors scale.
- Planar magnetic convergence:Thin-film diaphragm technology adapted from headphone engineering is penetrating IEM form factors, offering ultra-low distortion differentiation.
- Direct-to-audiophile channels:Crowdfunding platforms and Discord community pre-orders are displacing traditional distributor markups for boutique custom-lab operators.
Industry Challenges
- Acoustic engineering scarcity:Colorado and California talent pools for precision ear-impression interpretation are shrinking, forcing manufacturers to relocate fitting workflows to Asia or automate with 3D scanning.
- FCC equipment authorization timelines:Wireless IEM transmitters face 90-180 day review queues for unlicensed spectrum certification, delaying product launches against faster CE-marking competitors.
- Crossover network integration:Multi-driver designs require precise passive filter tuning that resists automation, constraining production scaling for hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Ear-Monitors (Iems) Market |
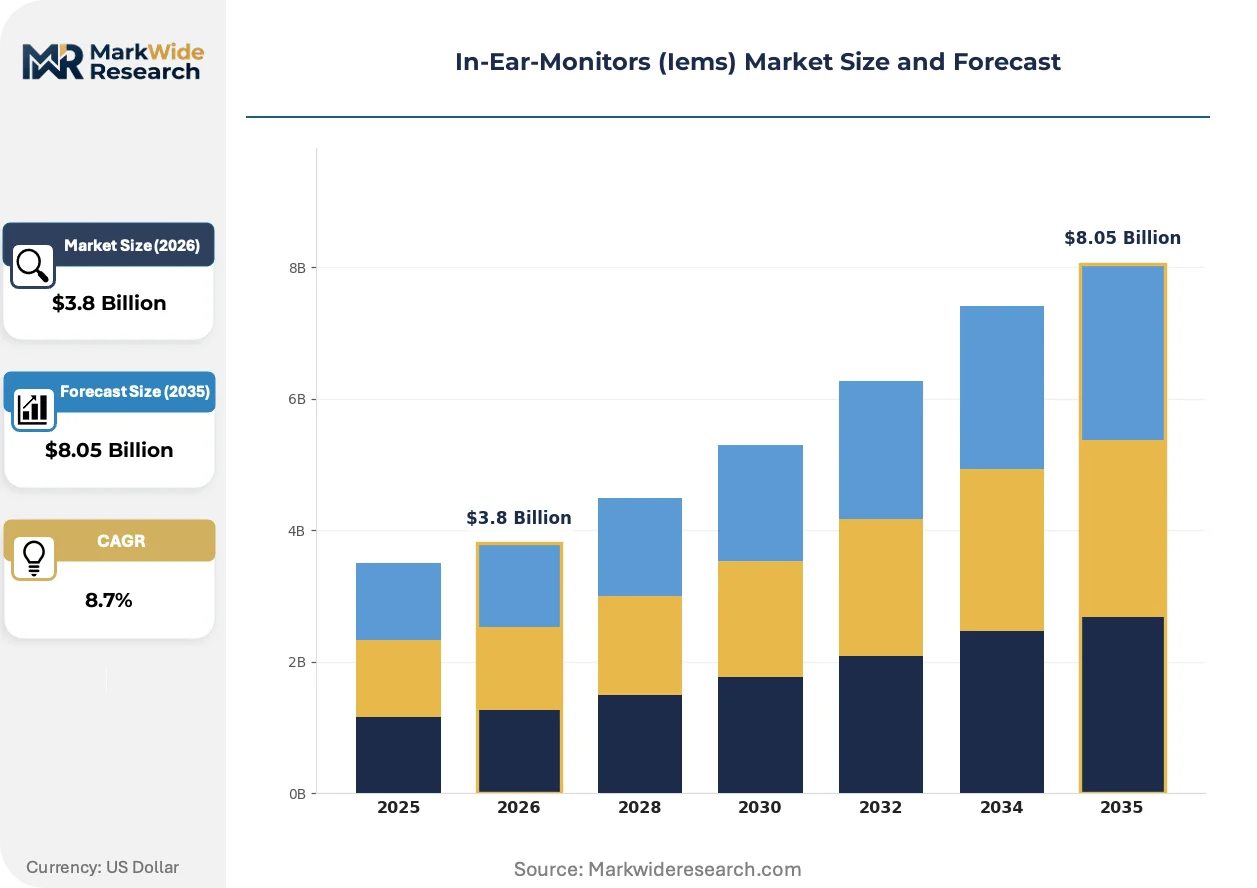
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Noise Cancelling, Sports Target Audience: Musicians, Audiophiles, Casual Listeners, Professionals Technology: Balanced Armature, Dynamic, Hybrid, Planar Magnetic Form Factor: Over-Ear, In-Ear, On-Ear, Custom-Fit |
| Companies Covered | Ultimate Ears, 64 Audio, Sennheiser, Westone Audio, Shure, Etymotic, Empire Ears, Harman International, JH Audio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Ear-Monitors (Iems) Market Shifts & Advancements
Driver topology experimentation is accelerating as planar magnetic and electrostatic technologies challenge balanced armature dominance in premium tiers.
Planar magnetic miniaturization is fragmenting the high-end IEM category. Thin-film diaphragm arrays now fit canal-fitting shells while maintaining sub-0.5% distortion metrics. Audiophile collectors in Japan and South Korea are driving adoption of these exotic configurations. The technology is fragmenting price segmentation by creating a super-premium tier above traditional multi-armature flagships.
REACH substance restrictions are reshaping solder and magnet supply chains. The EU regulation's expanded candidate list now screens beryllium copper alloys common in driver springs. Manufacturers serving European distribution are reformulating contact materials to maintain CE marking compliance. German and Dutch importers are demanding full material disclosure documentation from Shenzhen suppliers.
Community-driven development platforms are altering how boutique IEM makers validate designs. Discord servers and Head-Fi forum threads now function as real-time focus groups for tuning feedback. Small Colorado and California labs leverage this channel to refine signature profiles before committing to production runs. Japan's audiophile community particularly influences final voicing decisions for export-bound customs.
In-Ear-Monitors (Iems) Market Segmentation
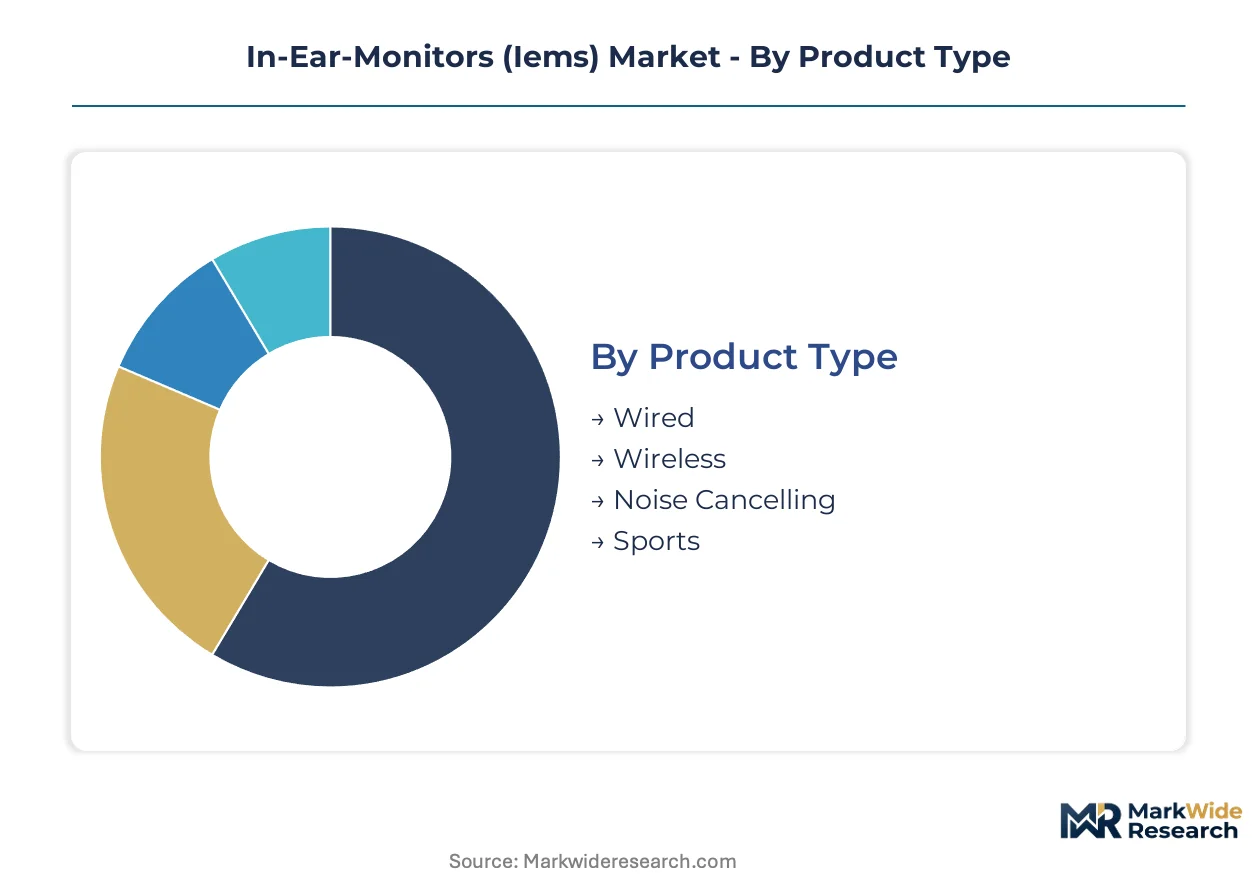
IEM segmentation reveals divergent supply chain footprints across product architectures. Each dimension carries distinct geographic demand signatures and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Wired configurations dominate export-led procurement for professional stage monitoring, while wireless variants concentrate in domestic consumer markets across North America and Western Europe.
- Wired:Zero-latency transmission protocols sustain professional audio engineer procurement for live touring circuits. Demand concentrates in Nashville, Los Angeles, and London where venue technical riders specify cable-dependent reliability.
- Wireless:Bluetooth codec integration faces FCC equipment authorization timelines of 90-180 days for unlicensed spectrum certification. Consumer adoption in Germany and France accelerates despite stage-monitoring latency ceilings.
- Noise Cancelling:Active cancellation DSP architectures target commuter rail users in Japan and air travel segments.
- Sports:Sweat-resistant IPX ratings dominate gym and running applications in Australia and California.
Wired commands the established base. The steepest expansion runs through wireless.
Target Audience:
Professional segments drive premium pricing power, while casual listener volume concentrates through mass-market retail channels in urban China and India.
- Musicians:Custom-fit workflows require precision ear-impression interpretation that Colorado and California acoustic engineering talent pools sustain. Tour procurement channels in Nashville and London maintain zero-defect reliability standards.
- Audiophiles:Collector communities in Tokyo and Seoul drive planar magnetic and electrostatic topology experimentation. Discord server feedback loops now validate tuning profiles before production commitment.
- Casual Listeners:Bluetooth convenience dominates smartphone accessory bundling in Shenzhen retail.
- Professionals:Broadcast and studio monitoring applications in Burbank and Mumbai require flat frequency response calibration.
Musicians anchor premium margin capture. Audiophile collectors deliver the fastest share gains.
Technology:
Balanced armature production concentrates in Shenzhen's manufacturing corridor, while planar magnetic R&D disperses across Japanese and South Korean engineering centers.
- Balanced Armature:Multi-driver crossover networks divide frequency bands across six to twelve armatures per earpiece. Shenzhen contract manufacturers control over seventy percent of global output, creating single-source vulnerability.
- Dynamic:Single-driver simplicity targets entry-tier price points in Indian and Indonesian mass markets.
- Hybrid:Dynamic woofers paired with balanced armature tweeters expand frequency response for studio-grade fidelity demands in Berlin and New York mastering facilities.
- Planar Magnetic:Thin-film diaphragm miniaturization achieves sub-0.5% distortion metrics in canal-fitting shells. Japanese and South Korean collectors drive adoption of these exotic configurations.
Balanced armature underpins volume scale. Planar magnetic claims the steepest technology trajectory.
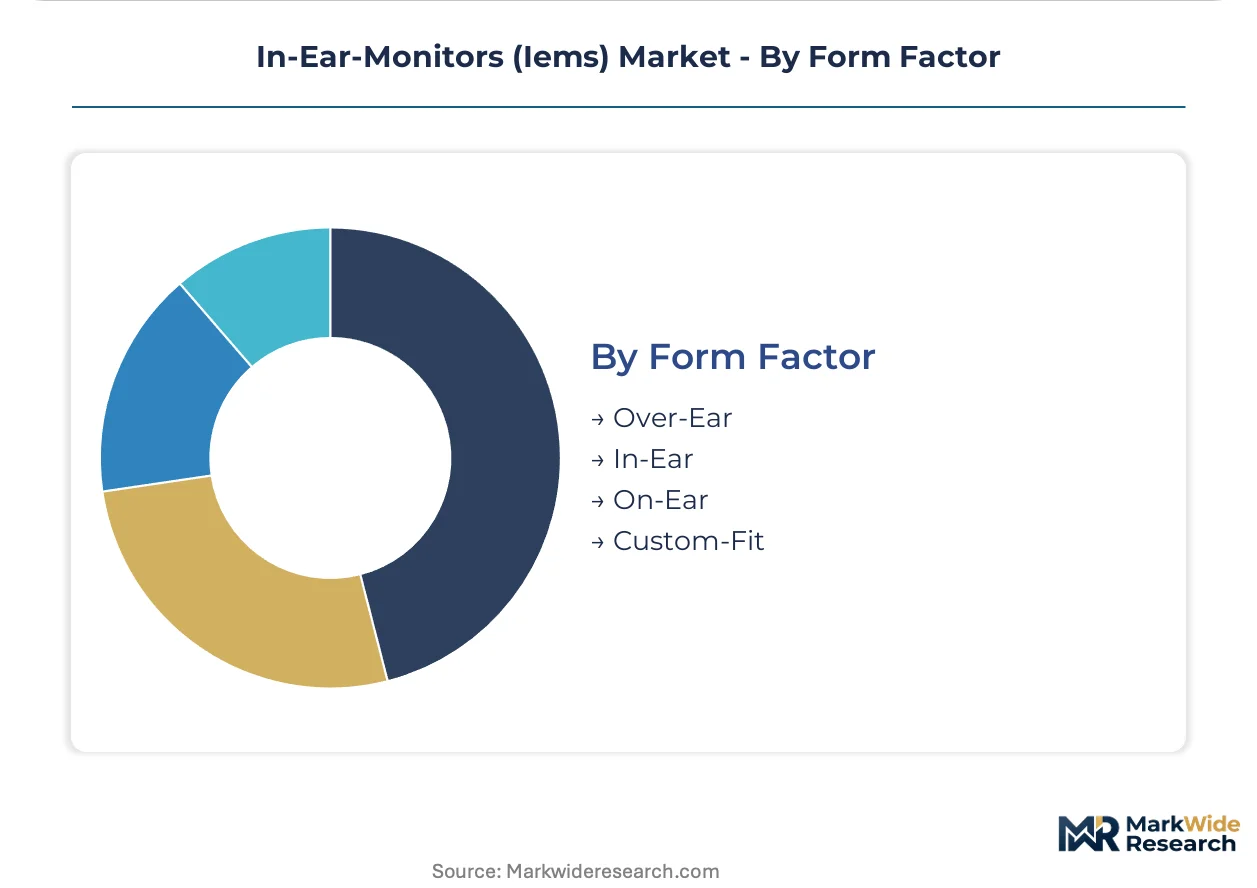
Form Factor:
Custom-fit workflows retain artisanal production in Western labs, while universal-fit manufacturing scales through Asian contract assembly.
- Custom-Fit:Precision ear-impression interpretation requires acoustic engineering talent that 64 Audio's Colorado infrastructure preserves. Asian competitors struggle to replicate artisanal fitting workflows at equivalent quality thresholds.
- In-Ear:Canal-sealing universal designs dominate mass-market distribution through Amazon and AliExpress channels.
- Over-Ear:Circumaural isolation competes with IEMs in broadcast monitoring applications.
- On-Ear:Supra-aural portability targets mobile professionals in London and Singapore financial districts.
Custom-fit commands absolute premium positioning. In-ear universal designs scale fastest through e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Professional musicians in the United States and United Kingdom prioritize zero-latency wired monitors for live touring, while consumers in China and South Korea drive wireless Bluetooth adoption. Japanese collectors fuel demand for exotic planar magnetic configurations.
United States
Nashville and Los Angeles anchor professional stage-monitoring procurement where venue technical riders mandate cable-dependent reliability. FCC equipment authorization governs wireless IEM transmission bands, constraining unlicensed spectrum architectures with 90-180 day review timelines. Colorado's acoustic engineering cluster sustains artisanal custom-fit workflows that Asian competitors struggle to replicate.
China
Shenzhen's manufacturing corridor dominates balanced armature driver output, supplying over seventy percent of global production. MIIT radio regulations shape domestic wireless certification pathways distinct from FCC or CE frameworks. The Pearl River Delta concentrates contract assembly for both domestic IEM brands and Western OEM procurement.
Germany
Berlin and Hamburg mastering facilities drive hybrid driver adoption for studio-grade fidelity applications. REACH substance restrictions and RoHS directives reshape solder and magnet supply chains entering European distribution. Bavarian audio engineering centers influence tuning profiles for export-bound premium customs.
Japan
Tokyo and Osaka collectors represent the fastest-growing demand vector for planar magnetic miniaturization in canal-fitting shells. METI standards govern domestic wireless transmission protocols. The Kanto region's audiophile community validates final voicing decisions through Discord feedback loops before production commitment.
United Kingdom
London's live touring circuit sustains wired monitor procurement alongside broadcast monitoring applications in Burbank-scale facilities. CE marking requirements align product architectures with EU RoHS and REACH compliance. British distributors increasingly demand full material disclosure documentation from Shenzhen suppliers.
In-Ear-Monitors (Iems) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. The upper tier captures premium positioning through captive R&D and custom-lab infrastructure, while mid-tier specialists compete on driver topology experimentation and community-validated tuning. Three archetypes dominate: vertically integrated Western labs with artisanal fitting workflows, Shenzhen-scale contract manufacturers with component allocation advantages, and hybrid-focused boutiques serving audiophile collectors. Capacity expansion in planar magnetic miniaturization and strategic partnerships for rare-earth magnet procurement represent the dominant competitive moves.
Within the integrated Western lab archetype, 64 Audio exemplifies Colorado-based custom-fit infrastructure preservation, while Ultimate Ears anchors the touring musician procurement channel. Shure occupies a position representing stage-monitor reliability standards for professional audio engineers. These three companies illustrate how geographic clustering of acoustic engineering talent creates defensible positioning against Asian manufacturing scale.
| Leading Market Players |
|---|
| Ultimate Ears |
| 64 Audio |
| Sennheiser |
| Westone Audio |
| Shure |
| Etymotic |
| Empire Ears |
| Harman International |
| JH Audio |
| Others |
Supply & Pricing Matrix
Component-scale economies in Shenzhen's balanced armature corridor concentrate manufacturing leverage among three contract suppliers, compressing price floors for Western brands while elevating margin capture for domestic Chinese IEM makers with preferential allocation rights.
Pricing Analysis
Long-term offtake contracts dominate procurement between established brands and Shenzhen foundries, insulating volume buyers from spot-market neodymium volatility while smaller boutiques face project-based spot exposure. Three-tier pricing structure across premium, standard, and economy levels separates custom-fit artisanal workflows from universal-fit mass production and entry-tier dynamic driver alternatives. Cost compression in the mid-tier intensifies because hybrid driver architectures require precision crossover tuning that resists automation. Casual listeners in urban China and India exhibit highest price sensitivity, whereas touring musicians in Nashville and London accept premium positioning for zero-defect reliability.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Western custom-lab operators who lack captive foundry capacity, while strategic stockpiling of rare-earth magnet alloys characterizes vertically integrated players hedging against Chinese export quota volatility. Component sourcing draws from China's Pearl River Delta for balanced armature drivers, Japan for thin-film diaphragm substrates, and Germany for REACH-compliant solder formulations. Single-source vulnerability concentrates in Shenzhen's three dominant contract manufacturers controlling over seventy percent of armature output. Distribution runs through direct-to-audiophile crowdfunding channels for boutique Colorado and California labs, while mass-market volume flows through Amazon and AliExpress retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ear-impression rescanning services and driver upgrade programs represent expanding recurring-revenue layers growing faster than hardware unit sales, converting one-time custom purchases into multi-year service relationships.
For Market Incumbents: Consolidate captive control over rare-earth magnet procurement through backward integration into compliant foundries or exclusive offtake partnerships, defending against margin compression from neodymium price volatility. Lock in acoustic engineering talent pools in Colorado and California through apprenticeship pipelines before automation displaces artisanal fitting workflows entirely.
For New Entrants and Emerging Players: Lead with planar magnetic miniaturization for Japanese and South Korean collector communities where exotic topology experimentation commands premium positioning unavailable to balanced armature incumbents. Target India's BIS certification pathway before local competitors scale compliant distribution, leveraging Discord community pre-orders to validate tuning profiles without traditional distributor markups.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom-lab operators with established ear-impression databases and upgrade service attach rates. Five-to-ten year viability favors vertically integrated players combining captive driver production with direct-to-consumer channel control. Monitor FCC equipment authorization queue lengths as inflection indicator for wireless platform launch velocity relative to faster CE-marking competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Planar Magnetic Miniaturization | Thin-film diaphragm penetration into canal-fitting shells opens super-premium tier above multi-armature flagships in Tokyo and Seoul. |
| Rare-Earth Magnet Procurement Partnership | Exclusive offtake agreements with compliant foundries insulate margins against Chinese export quota volatility. |
| Direct-to-Audiophile Channel Expansion | Crowdfunding and Discord pre-orders displace traditional distributor markups for boutique Colorado custom-labs. |
| REACH Compliance Reformulation | Beryllium copper alloy substitution preserves CE marking access for European distribution against ECHA candidate list expansion. |
| Acoustic Engineering Talent Pipeline | Apprenticeship programs in Colorado and California defend artisanal fitting workflows against Asian automation replication. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with acoustic engineers, custom-lab operators, touring audio technicians, and Shenzhen contract manufacturing executives; and secondary validation through FCC equipment authorization filings, MIIT radio regulations, REACH substance restriction updates, and Head-Fi forum sentiment tracking. Bottom-up driver production estimates from Shenzhen manufacturing clusters were triangulated against top-down retail channel audits across Amazon, AliExpress, and audiophile specialty distributors.
Across the projection horizon, the analytical framework modeled segmentation across product architecture (wired, wireless, hybrid, planar magnetic), target audience (musicians, audiophiles, casual listeners, professionals), and regional regulatory cluster (FCC-governed, CE-marking, MIIT-regulated, METI-standardized). CAGRs were derived from fitted growth curves incorporating live touring circuit recovery trajectories, Bluetooth codec adoption ceilings, and planar magnetic technology penetration rates in Japanese and South Korean collector markets.
Forecasts assume regulatory continuity in FCC spectrum allocation, EU RoHS and REACH substance restrictions, and Chinese MIIT radio certification pathways; material policy shifts in rare-earth export controls or wireless transmission band reallocations would require re-modeling. Practitioners should keep alternative scenarios live as neodymium supply volatility and acoustic engineering talent scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Keycap Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Wireless Mouse Market
Consumer Electronics
Gaming PC Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Smart Mirror TV Market