
 Gaming Phone Market | 2026-2036
Gaming Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming Phone Market Insights
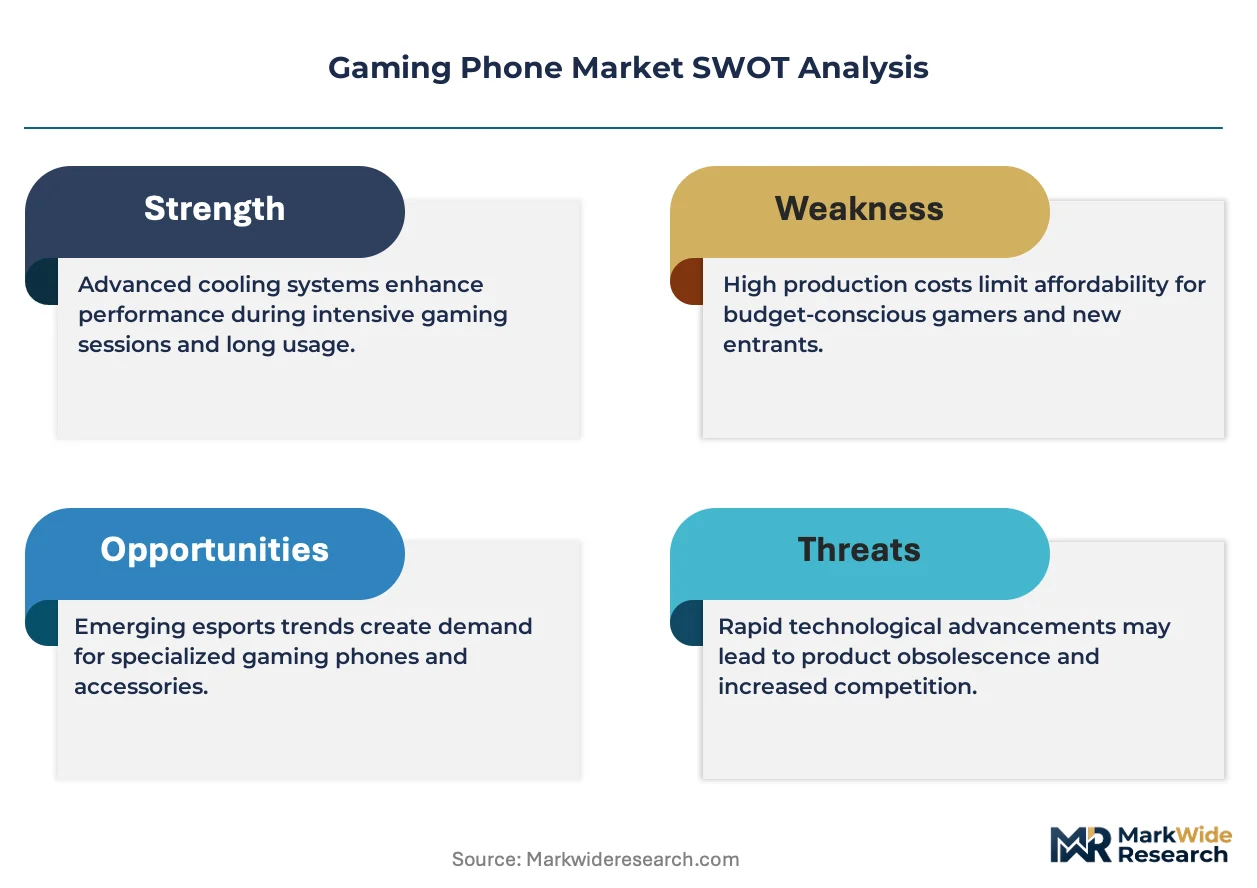
Specialty gaming retail is fragmenting as flagship electronics chains, carrier stores, and direct-to-consumer platforms compete for the same enthusiast base. ASUS leverages its ROG Phone sub-brand to sustain premium positioning through thermal engineering and display refresh rate leadership. Xiaomi competes aggressively on price-performance ratios, while Nubia's RedMagic line anchors itself in dedicated cooling hardware and physical trigger mechanisms.
Gaming phones are purpose-built mobile devices integrating high-refresh-rate OLED panels, vapor chamber cooling, and touch sampling rates exceeding standard smartphones to sustain intensive graphical workloads. These specifications serve competitive mobile gaming and live streaming where frame stability and input latency determine user experience. Smartphones command the dominant value share, while accessories and controllers capture expanding margin pools as peripheral ecosystems deepen. Professional gamers and streamers represent the fastest-expanding end-user category, outpacing casual gamers in per-unit spending and replacement frequency.
FCC certification requirements in the United States govern radio frequency emissions and device safety testing for all gaming phone imports. China's MIIT enforces network access licenses and GB standards compliance, creating a dual-track regulatory burden for manufacturers serving both markets. ISO quality management frameworks additionally shape supplier qualification processes across assembly partners. Stakeholders must monitor how divergent electromagnetic compatibility standards between North America and Asia affect unified product platform strategies.
Market Dynamics
Esports tournament procurement is compressing hardware refresh cycles while China's NMPA content approval delays force manufacturers to decouple software launch timing from device releases. This dual pressure reshapes inventory planning across assembly networks.
Growth Catalysts
- Esports infrastructure investment:Tournament organizers in South Korea and the United States are mandating standardized mobile hardware for competitive integrity, creating institutional demand pools.
- MIIT network license acceleration:China's streamlined GB standards compliance pathways reduce time-to-market for domestic manufacturers serving local 5G networks.
- Vapor chamber thermal diffusion:Advanced cooling architectures now sustain 120Hz+ refresh rates during sustained GPU loads, enabling broadcast-quality mobile streaming.
Market Restraints
- AMOLED panel supply concentration:Samsung Display and BOE control premium high-refresh-rate substrate output, creating single-source vulnerability for tier-two manufacturers.
- FCC electromagnetic certification timelines:United States import testing adds 8-14 weeks to product launches, compressing effective selling seasons.
- Standard smartphone performance convergence:Flagship consumer devices from Apple and Samsung now match gaming-specific touch sampling rates, eroding dedicated hardware justification.
Strategic Opportunities
- India's TRAI spectrum allocation:mmWave 5G rollouts in Mumbai and Bangalore create addressable infrastructure for low-latency competitive gaming hardware.
- Cloud gaming service bundling:Microsoft's Xbox Cloud Gaming and NVIDIA GeForce Now partnerships with carriers transform device economics through subscription attach.
- ISO 9241-410 ergonomics certification:Physical trigger mechanisms and haptic feedback systems qualify for premium positioning in professional player segments.
Industry Challenges
- Touch controller IC firmware integration:Coordinating 720Hz+ sampling rate validation across Qualcomm Snapdragon platforms and panel driver stacks extends QA cycles.
- Dual-track electromagnetic compliance:Engineers must reconcile FCC Part 15 emissions limits with MIIT GB/T radio frequency specifications without hardware variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming Phone Market |
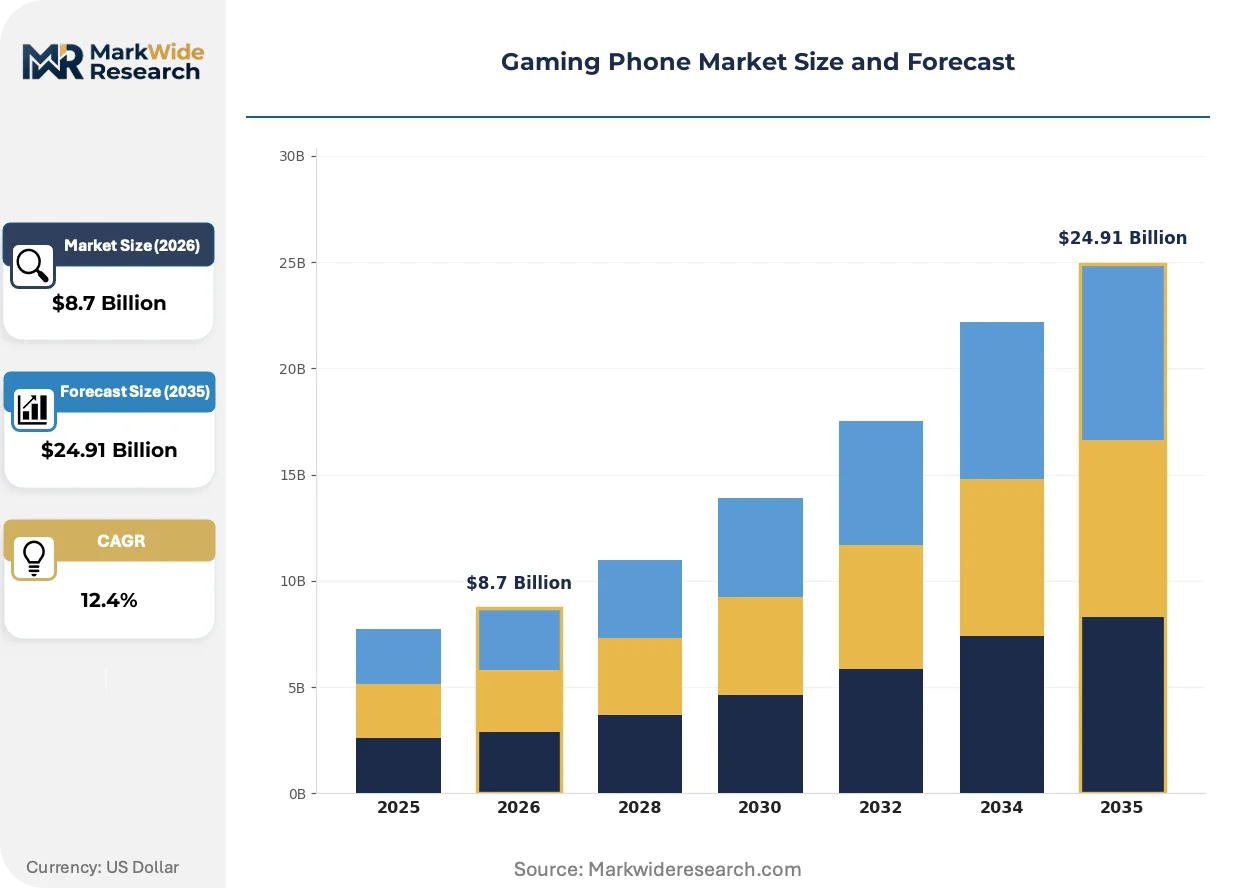
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $24.91 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Accessories, Controllers, Headsets End User: Casual Gamers, Professional Gamers, Streamers, Developers Technology: Cloud Gaming, Augmented Reality, Virtual Reality, Mobile Graphics Distribution Channel: Online Retail, Offline Retail, Direct Sales, E-commerce |
| Companies Covered | ASUS, Samsung Electronics, Nubia, RedMagic, Xiaomi, ZTE, Black Shark, ROG Phone, Lenovo Legion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming Phone Market Trends and Innovations
Active cooling subsystems are migrating from aftermarket accessories to native device architecture, while regulatory divergence between North American and Asian certification regimes forces modular radio designs. These shifts compress development timelines and expand addressable use cases beyond traditional gaming.
Shoulder-mounted physical trigger mechanisms with Hall-effect sensors are digitizing input latency benchmarks for competitive mobile titles. Professional esports leagues in Shenzhen and Los Angeles now mandate sub-20ms touch-to-display response as a eligibility standard. This specification is digitizing procurement criteria for tournament-grade hardware, forcing OEMs to vertically integrate controller IC validation.
REACH substance restrictions on fluorinated cooling compounds are compelling manufacturers to reformulate thermal interface materials for European Union imports. The ECHA authorization process adds six to nine months to material qualification, compressing product launch windows for global SKUs. Gaming phone vendors serving Germany and France are responding with graphene-alternative vapor chamber designs.
Live streaming creators now prioritize broadcast-ready HDMI-out and dedicated audio DSPs over raw compute benchmarks, shifting hardware evaluation criteria. Specialty retailers in Tokyo's Akihabara district and carrier flagship stores in Seoul report attachment rates for external capture cards declining as native streaming silicon proliferates. This preference rotation is most visible among 18-24 year old content creators monetizing through platform partner programs.
Gaming Phone Market Segmentation
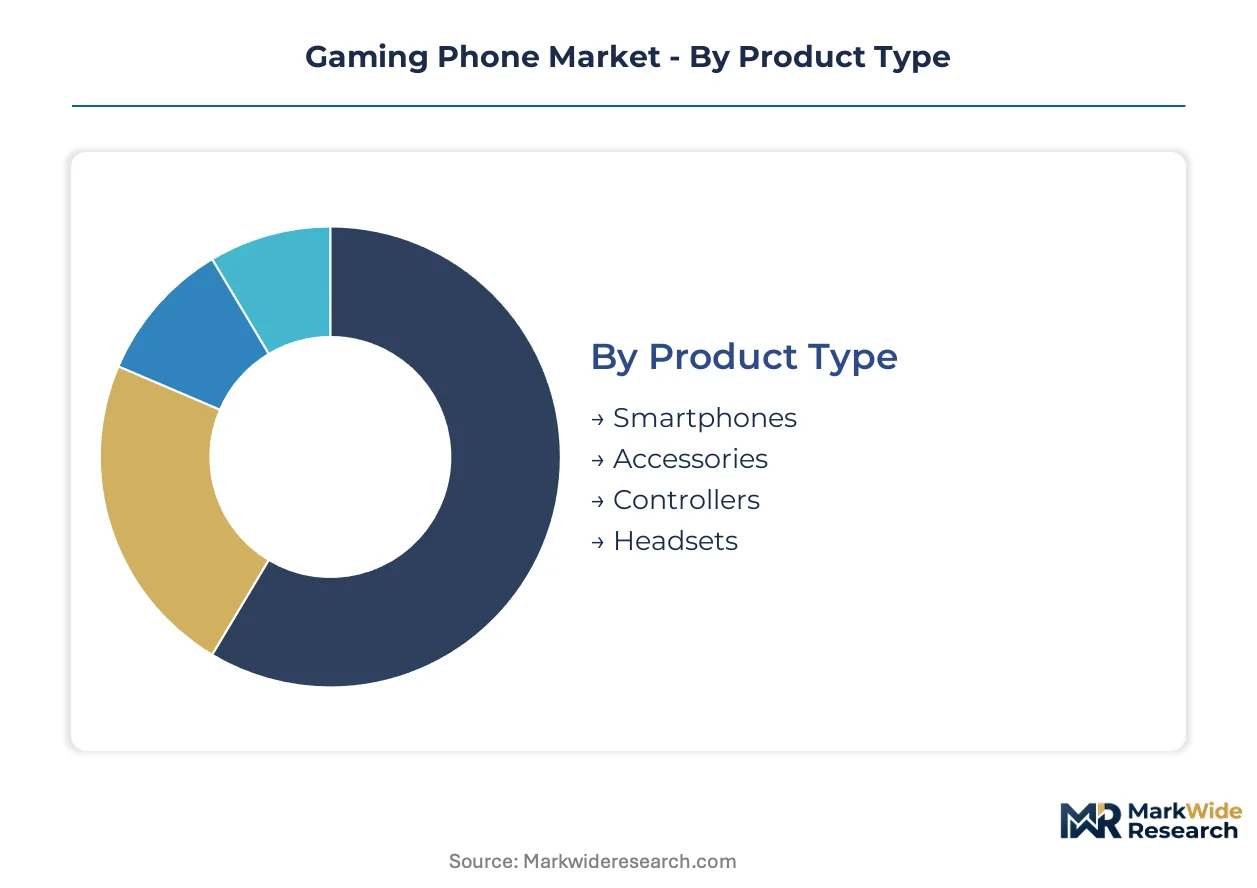
Gaming phone segmentation reflects divergent hardware requirements across competitive intensity levels and content creation workflows. Distinct thermal, display, and input specifications separate casual consumption from professional esports and broadcast use cases.
Product Type:
The use-case spectrum spans integrated devices through peripheral ecosystems, with hardware architecture determining performance ceilings.
- Smartphones:Purpose-built mobile devices integrate high-refresh-rate OLED panels, vapor chamber cooling, and touch sampling rates exceeding 720Hz. Demand concentrates in China where MIIT network license acceleration compresses domestic manufacturer release cycles. NMPA content approval delays force decoupling of hardware launches from software availability.
- Accessories:External cooling fans, protective cases with thermal dissipation channels, and battery expansion packs extend device endurance during tournament play. Procurement from esports organizers in South Korea and the United States is compressing refresh cycles as institutional standardization mandates proliferate.
- Controllers:Physical input devices with Hall-effect triggers and low-latency Bluetooth connectivity address precision requirements in first-person shooter titles.
- Headsets:Audio peripherals with dedicated DSPs and low-latency codecs serve streamers requiring broadcast-quality voice isolation.
Established volume favors Smartphones; emerging adoption favors Accessories.
End User:
Customer-type stratification separates price-sensitive recreational users from performance-prioritizing professionals with accelerated replacement cycles.
- Casual Gamers:Recreational users prioritizing mainstream titles and social gameplay experiences. Replacement cycles extend 24-36 months as standard smartphone performance convergence erodes dedicated hardware justification.
- Professional Gamers:Competitive players requiring sub-20ms touch-to-display response for tournament eligibility. Shenzhen and Los Angeles esports leagues now mandate specific hardware certifications, institutionalizing procurement demand.
- Streamers:Content creators monetizing through platform partner programs prioritize native HDMI-out and dedicated audio DSPs over raw compute benchmarks. This segment is expanding most quickly as 18-24 year old creators in Tokyo and Seoul drive attachment rate growth.
- Developers:Technical users requiring debugging interfaces and thermal profiling tools for game optimization.
Per-unit spending peaks with Professional Gamers; volume scale concentrates with Casual Gamers.
Technology:
Maturity gradients separate established mobile rendering from emerging immersive and cloud-distributed architectures.
- Cloud Gaming:Streaming-based delivery decouples local compute requirements from display quality, enabling carrier bundling partnerships with Xbox Cloud Gaming and NVIDIA GeForce Now. India's TRAI mmWave spectrum allocations in Mumbai and Bangalore create infrastructure for low-latency deployment.
- Augmented Reality:Overlay graphics integration requires specialized sensor arrays and spatial computing silicon. Adoption remains constrained by thermal budgets and battery chemistry limitations.
- Virtual Reality:Fully immersive mobile VR demands dual-display architectures and precise head tracking. Content availability lags hardware capability.
- Mobile Graphics:Native GPU rendering on Snapdragon and MediaTek platforms remains the dominant technical foundation. Vapor chamber thermal diffusion now sustains 120Hz+ refresh rates during sustained workloads.
Deployment scale favors Mobile Graphics; investment intensity concentrates on Cloud Gaming.
Distribution Channel:
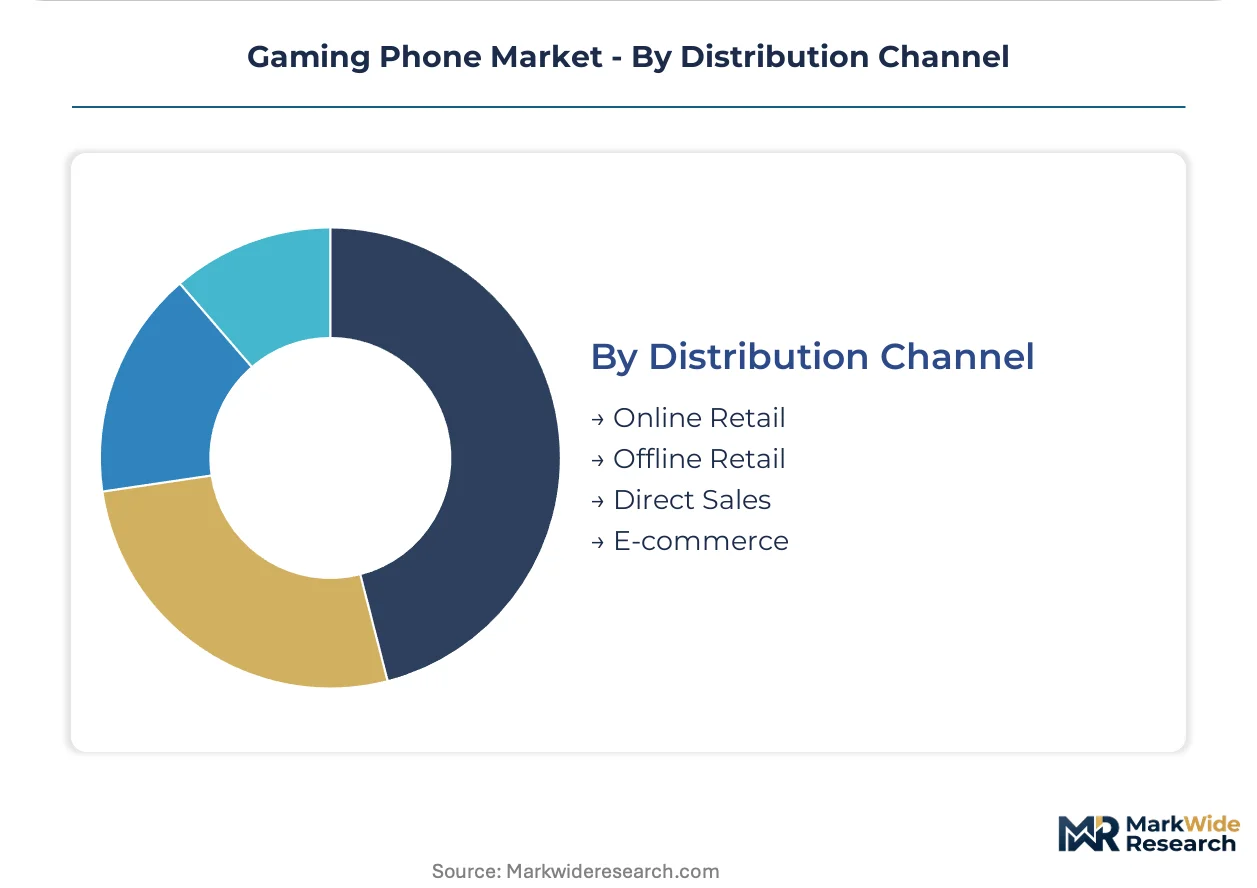
Channel economics reflect margin compression as flagship electronics chains, carrier stores, and direct platforms compete for enthusiast segments.
- Online Retail:Specialty gaming platforms and marketplace aggregators serve price-comparison shoppers. Geographic reach spans regulatory jurisdictions with divergent electromagnetic compliance requirements.
- Offline Retail:Carrier flagship stores in Seoul and electronics districts like Tokyo's Akihabara provide hands-on thermal and display evaluation. FCC certification timelines compress effective selling seasons for US-bound inventory.
- Direct Sales:Manufacturer-controlled channels capture margin and enable subscription bundling with cloud gaming services.
- E-commerce:Platform-native storefronts leverage algorithmic discovery and flash promotion mechanics.
Margin retention favors Direct Sales; volume throughput concentrates in E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningbo-Zhoushan Port handles the majority of high-refresh-rate display substrate imports for gaming phone assembly, underwriting the country's dominance in finished device exports. This maritime infrastructure connects Samsung Display and BOE supply lines to Shenzhen and Dongguan manufacturing clusters.
China
Domestic brands command local distribution through MIIT-accelerated network licensing pathways. NMPA content approval timelines continue pressuring hardware release cycles, forcing decoupled launch strategies. Shenzhen's Huaqiangbei electronics corridor concentrates vapor chamber thermal component sourcing for tier-one manufacturers.
United States
Esports tournament procurement in Los Angeles and Seattle generates institutional demand for sub-20ms touch response certification. FCC Part 15 electromagnetic testing adds 8-14 weeks to import timelines, compressing selling seasons. Carrier flagship stores in Manhattan and Chicago serve hands-on evaluation for enthusiast segments.
South Korea
Seoul-based esports leagues mandate standardized mobile hardware for competitive integrity, creating recurring institutional procurement. Samsung Display controls premium AMOLED substrate output from Gumi and Asan facilities. Busan port logistics link domestic panel production to regional assembly networks.
India
TRAI mmWave spectrum allocations in Mumbai and Bangalore enable low-latency infrastructure for competitive gaming hardware deployment. BIS certification requirements govern local 5G device compliance. Noida and Sri City manufacturing zones attract assembly investment for domestic market supply.
Japan
Tokyo's Akihabara district reports declining external capture card attachment rates as native streaming silicon proliferates. METI industrial standards shape thermal interface material specifications for premium device imports. Osaka-based component distributors coordinate supply for Asia-Pacific peripheral ecosystems.
Gaming Phone Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in display, thermal, and controller IC supply. The vendor base concentrates around three archetypes: thermal engineering specialists leveraging vapor chamber architectures, price-performance optimizers competing on specification-per-dollar metrics, and esports-focused brands integrating physical trigger mechanisms. Competitive moves center on carrier bundling partnerships with cloud gaming services and backward integration into high-refresh-rate panel sourcing.
Within the thermal engineering tier, ASUS anchors premium positioning through its ROG Phone sub-brand. Xiaomi and Nubia occupy adjacent positions representing divergent strategic bets—Xiaomi on aggressive specification democratization, Nubia on dedicated cooling hardware specialization. These three exemplify how competitive differentiation fragments across thermal architecture, display leadership, and input latency optimization rather than converging on uniform excellence.
| Leading Market Players |
|---|
| ASUS |
| Samsung Electronics |
| Nubia |
| RedMagic |
| Xiaomi |
| ZTE |
| Black Shark |
| ROG Phone |
| Lenovo Legion |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's Huaqiangbei electronics corridor concentrates vapor chamber thermal component sourcing, compressing procurement timelines for domestic manufacturers while amplifying their pricing leverage against foreign rivals dependent on cross-border supply lines. This geographic clustering enables tier-one OEMs to negotiate volume-based component discounts that tier-two manufacturers cannot replicate, widening cost-performance gaps across product tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships, with esports tournament organizers commanding steepest discounts through institutional standardization mandates. Pricing stratifies across premium certification tiers, ISO 9241-410 ergonomics qualification, and thermal performance benchmarks rather than raw specifications alone. Cost compression in the mid-tier intensifies as standard smartphone performance convergence erodes dedicated hardware justification. Casual gamers exhibit highest price sensitivity, while professional esports leagues prioritize sub-20ms response certification over per-unit cost.
Supply Chain Analysis
Foxconn and BYD Electronics hold dominant contract manufacturing capacity for gaming phone assembly, with secondary concentration at Pegatron and Wistron facilities. Component sourcing draws from China for vapor chambers and thermal interface materials, South Korea for premium AMOLED substrates, and Taiwan for touch controller ICs. Single-source vulnerability in high-refresh-rate display panels from Samsung Display and BOE creates procurement risk. Distribution runs through carrier flagship stores in Seoul and direct-to-consumer platforms capturing margin from specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as live streaming creators, competitive esports leagues, and cloud gaming services generate divergent hardware requirements, creating specialized niches beyond uniform flagship positioning. This demand-side splintering rewards targeted product architecture over specification maximization.
For Market Incumbents:Pre-empt margin erosion from standard smartphone convergence by deepening thermal engineering differentiation and securing exclusive high-refresh-rate panel allocations through multi-year supply agreements. Capture institutional procurement demand from Shenzhen and Los Angeles esports leagues through dedicated tournament-grade certification programs. Prioritize backward integration into vapor chamber manufacturing to defend cost position against price-performance challengers.
For New Entrants and Emerging Players:India's TRAI mmWave spectrum allocations in Mumbai and Bangalore represent underpenetrated infrastructure for low-latency competitive gaming hardware deployment. Target cloud gaming service bundling partnerships with carriers as the most penetrable entry vector, leveraging subscription attach economics to offset upfront hardware margins. Pursue ISO 9241-410 ergonomics certification as differentiated positioning against specification-focused incumbents.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified electronics conglomerates with underutilized gaming phone divisions lacking dedicated thermal R&D investment. Long-term viability hinges on sustained esports institutionalization and content creator monetization platform growth. Monitor NMPA content approval timeline volatility as inflection indicator for hardware launch cadence disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Cloud Gaming Bundling | Subscription attach economics from Xbox Cloud Gaming and NVIDIA GeForce Now partnerships transform device profitability models. |
| Thermal Architecture Specialization | Graphene-alternative vapor chamber designs address REACH fluorinated compound restrictions for European Union market access. |
| Esports Certification Integration | Sub-20ms touch-to-display response mandates from Shenzhen and Los Angeles leagues institutionalize procurement demand pools. |
| Direct-to-Consumer Channel Expansion | Manufacturer-controlled platforms capture margin from fragmenting specialty retail and enable subscription service integration. |
| mmWave 5G Hardware Optimization | TRAI spectrum allocations in Mumbai and Bangalore create addressable infrastructure for low-latency competitive gaming deployment. |
Research Methodology
Operator-level perspectives from esports tournament organizers, carrier procurement executives, thermal component suppliers, and live streaming platform engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from MIIT network license filings, FCC Part 15 certification databases, esports league hardware mandate documentation, and carrier partnership disclosure statements. Bottom-up demand modeling across end-user segments triangulated against top-down supply chain capacity assessments from Shenzhen and Dongguan manufacturing clusters.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for NMPA approval timeline volatility and AMOLED panel supply disruption. Segmentation dimensions modeled include product type, end-user category, technology architecture, and distribution channel, with additional granularity on thermal solution tier and certification status. CAGRs derived from installed base growth rates, replacement cycle compression, and per-unit spending trajectory across professional and casual user archetypes. Cloud gaming service attach rates and carrier bundling penetration served as industry-specific demand amplifiers.
Practitioners should monitor NMPA content approval delays, REACH substance restriction expansions, and mmWave infrastructure rollout pace for early signals of forecast revision. Assumptions underlying projections reflect current regulatory trajectories and esports institutionalization trends. Quarterly review of esports league hardware mandate updates, carrier partnership announcements, and thermal component supply allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Mexico Smart TV Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
True Wireless Stereo Market
Consumer Electronics
Shoe Shining Machine Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Global Laptop Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Europe Stylus Pen Market