
 Ereader and Enotetaking Devices Market | 2026-2036
Ereader and Enotetaking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ereader and Enotetaking Devices Market Foresight
High-resolution E-Ink Carta 1200 displays is reorganizing the premium tier of the ereader category. Amazon.com, Inc. leverages its Kindle ecosystem and content lock-in to dominate mass-market distribution. Rakuten Kobo Inc. competes through open-format support and library integration across multiple English-speaking markets. Onyx International Inc. specializes in large-format E-Ink tablets that target academic researchers and legal professionals needing A4-sized document review.
Ereader and enotetaking devices combine reflective display technology with stylus-enabled input surfaces to deliver paper-like reading and handwriting experiences with minimal eye strain and weeks-long battery endurance. E-Ink panels utilize microcapsule electrophoretic technology where charged pigment particles rearrange under electric fields to form images without backlight emission, making the technology suitable for prolonged text consumption in varied lighting conditions. Smart notebooks and digital pens are capturing margin pools in the professional application segment as enterprises seek paperless workflows with handwritten authenticity. Tablets running E-Ink technology are gaining traction among creative workers who require sketching precision without LCD fatigue.
FCC equipment authorization requirements govern wireless-enabled ereader sales in the United States, while EU RoHS and REACH frameworks restrict hazardous substances in device manufacturing and batteries for European market access. ECHA substance restrictions on heavy metals in electronics are pushing manufacturers toward alternative solder compositions and recyclable chassis materials. Stakeholders must monitor how emerging right-to-repair legislation across multiple jurisdictions reshapes warranty structures and component sourcing strategies for stylus assemblies and display modules.
Market Dynamics
E-Ink color panel production capacity constraints are compressing supply availability for premium ereader tiers while university procurement cycles accelerate demand concentration in North American higher education. This structural tension between display technology maturation and institutional purchasing timelines defines current competitive positioning.
Growth Catalysts
- REACH substance restrictions:ECHA mandates on heavy metal reduction in electronics are accelerating manufacturer migration toward recyclable chassis materials and lead-free solder compositions, opening certification-compliant product lines for European market entry.
- Stylus latency reduction:Sub-30ms response time improvements in EMR digitizer technology are enabling handwriting experiences indistinguishable from paper, pulling legal professionals and medical residents into large-format E-Ink tablet adoption.
- Corporate wellness subsidies:Knowledge worker reimbursement programs in the United States are defraying device costs for employees seeking reduced screen fatigue, expanding addressable volume beyond traditional book-reading demographics.
Market Restraints
- E-Ink Holdings supply concentration:Single-source dependency on Taiwan-based electrophoretic display manufacturing creates vulnerability to foundry capacity allocation decisions and geopolitical transit disruptions.
- Lithium-ion cell cost volatility:Battery raw material price swings directly compress margin structures for devices marketed on multi-week endurance claims requiring high-capacity cells.
- LCD-OLED hybrid substitutes:Low-power reflective LCD technologies from Sharp and Japan Display are encroaching on price-sensitive segments with comparable daylight readability at lower unit costs.
Strategic Opportunities
- Indian higher education digitization:National Digital Library infrastructure investments and BIS electronics certification streamlining are creating first-mover advantage for localized ereader distribution partnerships.
- K-12 annotation mandates:Curriculum standards requiring handwritten feedback loops in primary education are opening device procurement channels previously dominated by Chromebook tablet deployments.
- Right-to-repair legislative tailwinds:State-level repairability scorecard requirements in California and New York are rewarding modular stylus assembly designs and swappable battery architectures with preferential institutional purchasing.
Industry Challenges
- FCC equipment authorization timelines:Wireless-enabled ereader certification delays of 12-16 weeks are compressing seasonal launch windows and forcing inventory pre-positioning ahead of academic purchasing cycles.
- EMR digitizer integration complexity:Harmonizing Wacom and proprietary stylus protocols with E-Ink driver stacks requires specialized firmware engineering talent concentrated in Shenzhen and Hsinchu technology corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ereader and Enotetaking Devices Market |
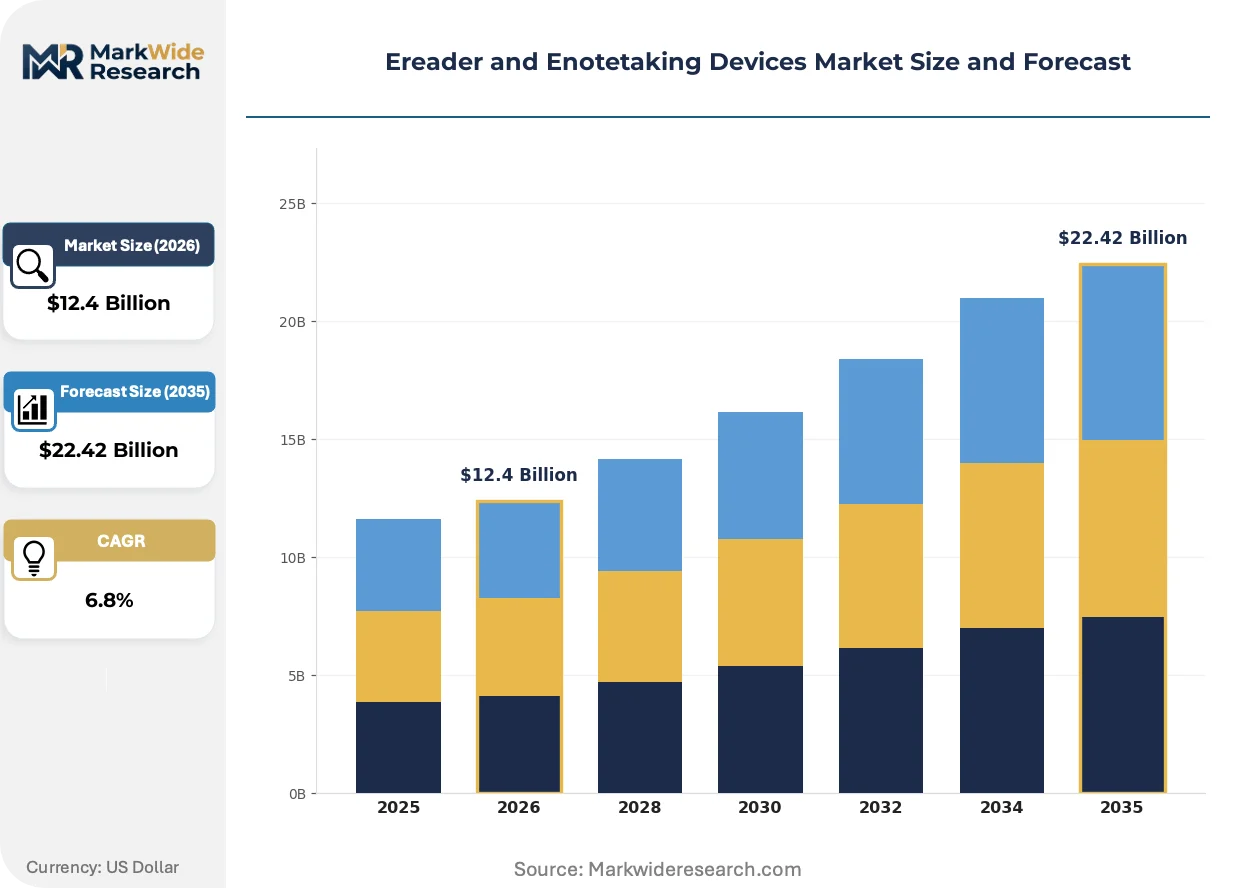
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ereaders, Smart Notebooks, Digital Pens, Tablets Technology: E-Ink, LCD, OLED, Capacitive Touch Application: Education, Professional, Leisure, Creative Work End User: Students, Writers, Educators, Business Professionals |
| Companies Covered | Amazon.com, Inc., Rakuten Kobo Inc., Onyx International Inc., PocketBook International SA, Barnes & Noble, Inc., Remarkable AS, Hanvon Technology Co., Ltd., Bigme, reMarkable, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ereader and Enotetaking Devices Market Shifts & Advancements
Reflective display technology trajectories and input surface architectures are diverging simultaneously, creating multiple viable product-formula bets rather than a single dominant design. Vendors must now select specialization paths across color fidelity, stylus precision, and form-factor extremes.
Kaleido 3 and Gallery 3 color E-Ink implementations are fragmenting the premium tier into photography-optimized versus document-optimized use cases. Magazine publishers and graphic novel distributors are piloting these panels for faithful color reproduction, while academic journal platforms prioritize faster refresh variants for mixed text-image layouts. This technical bifurcation is fragmenting R&D investment across incompatible electrophoretic formulations rather than consolidating behind one standard.
EU right-to-repair directives and accompanying CSRD sustainability disclosure requirements are mandating seven-year spare parts availability for battery and display modules. Manufacturers serving European higher education procurement are reconfiguring supply contracts to guarantee component sourcing timelines that exceed typical consumer electronics obsolescence cycles. German university purchasing consortia are now embedding repairability score thresholds as mandatory bid evaluation criteria.
Enterprise volume purchasing is displacing individual retail acquisition as the dominant channel for large-format E-Ink tablets. Legal discovery departments and pharmaceutical regulatory affairs teams are consolidating device procurement through centralized IT asset management rather than departmental expense authorization. This concentration is most visible in United States professional services firms where standardized annotation workflows require fleet-wide stylus protocol consistency.
Ereader and Enotetaking Devices Market Segmentation
E-Ink display certification requirements and stylus protocol standards fragment procurement pathways across institutional and consumer channels. Product positioning must align with specific regulatory frameworks governing electromagnetic emissions and hazardous substance restrictions in target markets.
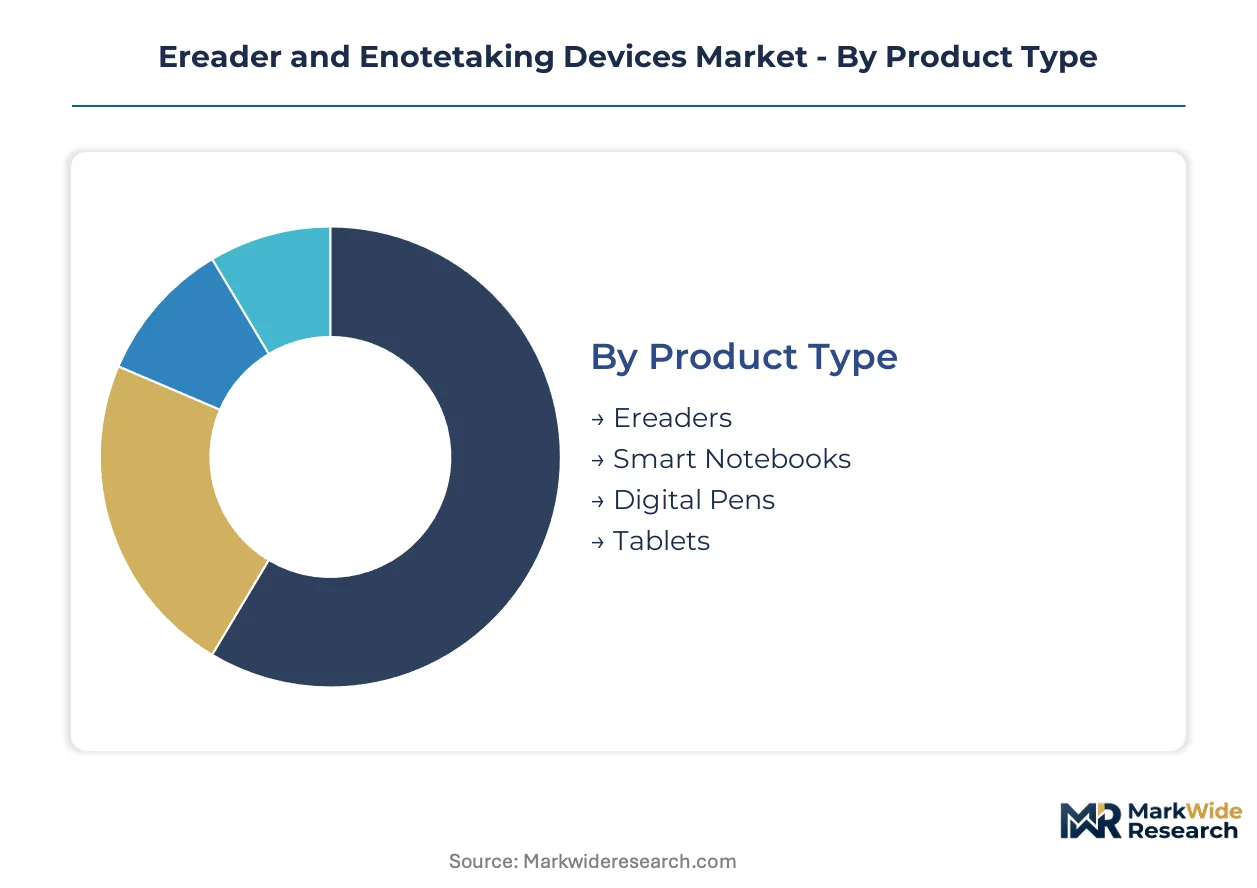
Product Type:
FCC equipment authorization timelines and EU RoHS substance restrictions create divergent compliance burdens for wireless-enabled versus passive-input devices. Battery-integrated form factors face stricter ECHA scrutiny on lithium-cell chemistry disclosures.
- Ereaders:Monochrome E-Ink Carta panels dominate this segment with weeks-long battery endurance. United States university adoption programs concentrate demand for 6-inch and 7-inch form factors with frontlight systems. REACH-compliant chassis materials are becoming mandatory for European higher education procurement.
- Smart Notebooks:EMR digitizer layers enable stylus handwriting capture on paper-like surfaces. Legal discovery departments and pharmaceutical regulatory teams in the United States drive fleet purchasing for annotation workflows. Modular battery architectures satisfy emerging right-to-repair scorecard requirements in California and New York.
- Digital Pens:Active stylus technologies transmit pressure and tilt data to companion tablets or paper substrates.
- Tablets:Large-format E-Ink displays serve academic researchers requiring A4 document review capabilities.
Ereaders handle the majority of throughput; smart notebooks are climbing the fastest on share as enterprise wellness subsidies expand.
Technology:
Cost tier differentiation separates premium electrophoretic implementations from commodity LCD alternatives in price-sensitive education contracts.
- E-Ink:Microcapsule electrophoretic technology rearranges charged pigment particles without backlight emission. German university purchasing consortia now mandate seven-year spare parts availability for E-Ink display modules under CSRD sustainability disclosure rules. Sub-30ms refresh rate improvements are pulling medical residents into large-format adoption.
- LCD:Reflective LCD panels from Sharp and Japan Display encroach on budget segments with comparable daylight readability at lower unit costs. Indian K-12 procurement channels favor these alternatives for cost-constrained district deployments under BIS electronics certification.
- OLED:Emissive display technology remains marginal in this market due to eye strain concerns during prolonged text consumption.
- Capacitive Touch:Finger-input layers enable basic navigation without stylus precision for casual reading applications.
E-Ink dominates installed base; reflective LCD alternatives are expanding most quickly in emerging market education tenders.
Application:
Volume concentration in North American higher education procurement cycles creates demand spikes that strain color E-Ink panel production capacity.
- Education:Lecture capture and collaborative annotation requirements drive smart notebook deployment across United States colleges. K-12 curriculum standards mandating handwritten feedback loops are opening procurement channels previously dominated by Chromebook tablets.
- Professional:Corporate wellness initiatives subsidize device purchases for knowledge workers seeking reduced screen fatigue.
- Leisure:Consumer book-reading demographics remain the core addressable market for dedicated ereader hardware.
- Creative Work:Sketching precision without LCD fatigue attracts designers and illustrators to E-Ink tablet form factors.
Education absorbs the largest procurement volumes; professional applications are gaining share fastest as enterprise IT asset management consolidates purchasing.
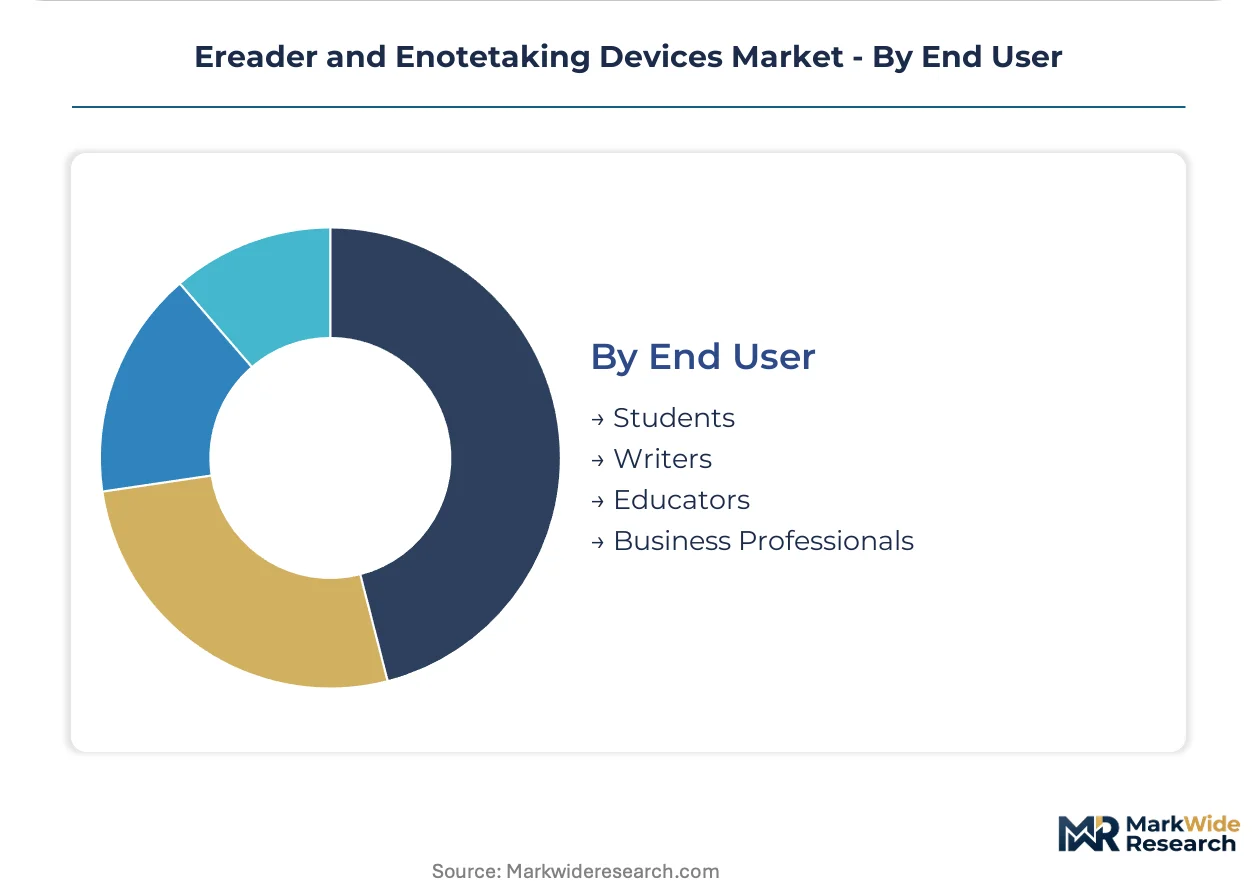
End User:
Customer type determines stylus protocol requirements and fleet management complexity in institutional deployment scenarios.
- Students:Higher education institutions expand procurement of smart notebooks for lecture capture. United States university adoption programs subsidize device costs through centralized technology fee structures.
- Writers:Long-form composition workflows prioritize distraction-minimized E-Ink interfaces with minimal notification interruption.
- Educators:Handwritten feedback loop requirements in primary education standards drive annotation-capable device selection.
- Business Professionals:Legal discovery departments and pharmaceutical regulatory affairs teams standardize on fleet-wide stylus protocol consistency.
Students represent the deepest volume base; business professionals are the steepest expansion trajectory as enterprise reimbursement programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-Ink display module production concentrates in Taiwanese foundry corridors, creating geographic dependency for finished device assembly across consumer and institutional channels. University procurement cycles in multiple markets now synchronize with these supply constraints.
United States
FCC equipment authorization governs wireless-enabled ereader distribution, with certification timelines compressing seasonal launch windows. Corporate wellness subsidies defray device costs for knowledge workers seeking reduced screen fatigue. Boston and San Francisco technology corridors host fleet procurement coordination for legal discovery and pharmaceutical regulatory teams.
Germany
CSRD sustainability disclosure rules mandate seven-year spare parts availability for E-Ink display modules in higher education procurement. German university purchasing consortia embed repairability score thresholds as mandatory bid evaluation criteria. Bavaria and Baden-Württemberg manufacturing clusters supply precision EMR digitizer components to assembly partners.
China
GB standards and MIIT certification frameworks regulate domestic electronics manufacturing for both local consumption and export assembly. Shenzhen and Hsinchu technology corridors concentrate firmware engineering talent for E-Ink driver stack harmonization. Yangtze River Delta facilities manage color panel production capacity allocation decisions.
India
BIS electronics certification streamlining supports National Digital Library infrastructure investments for higher education digitization. Maharashtra and Karnataka technology hubs develop localized distribution partnerships for first-mover market entry. CDSCO and TRAI frameworks govern wireless device compliance for institutional deployment.
Japan
METI industrial policy and JIS standards guide reflective LCD technology development from Sharp and Japan Display as E-Ink alternatives. Kansai and Chubu manufacturing regions produce low-power display panels for cost-sensitive education tenders. PMDA regulatory frameworks remain peripheral for this consumer electronics category.
Ereader and Enotetaking Devices Market Competitive Landscape
Concentration sits with ecosystem-integrated technology conglomerates and specialized E-Ink hardware fabricators. Amazon.com leverages content lock-in and mass-market distribution infrastructure to dominate consumer-facing channels. Rakuten Kobo competes through open-format support and library integration across English-speaking markets. Strategic moves center on color panel production capacity pre-positioning and university procurement cycle alignment ahead of academic purchasing windows.
Within the ecosystem-integrated tier, Amazon.com, Inc. and Rakuten Kobo Inc. represent contrasting approaches to content distribution and hardware margins. Onyx International Inc. occupies a position among large-format specialists targeting academic researchers and legal professionals with A4-sized document review requirements. These three anchors illustrate how competitive positioning fragments across mass-market lock-in, open-format flexibility, and professional-use specialization rather than consolidating behind a single dominant design.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Rakuten Kobo Inc. |
| Onyx International Inc. |
| PocketBook International SA |
| Barnes & Noble, Inc. |
| Remarkable AS |
| Hanvon Technology Co., Ltd. |
| Bigme |
| reMarkable |
| Others |
Supply & Pricing Matrix
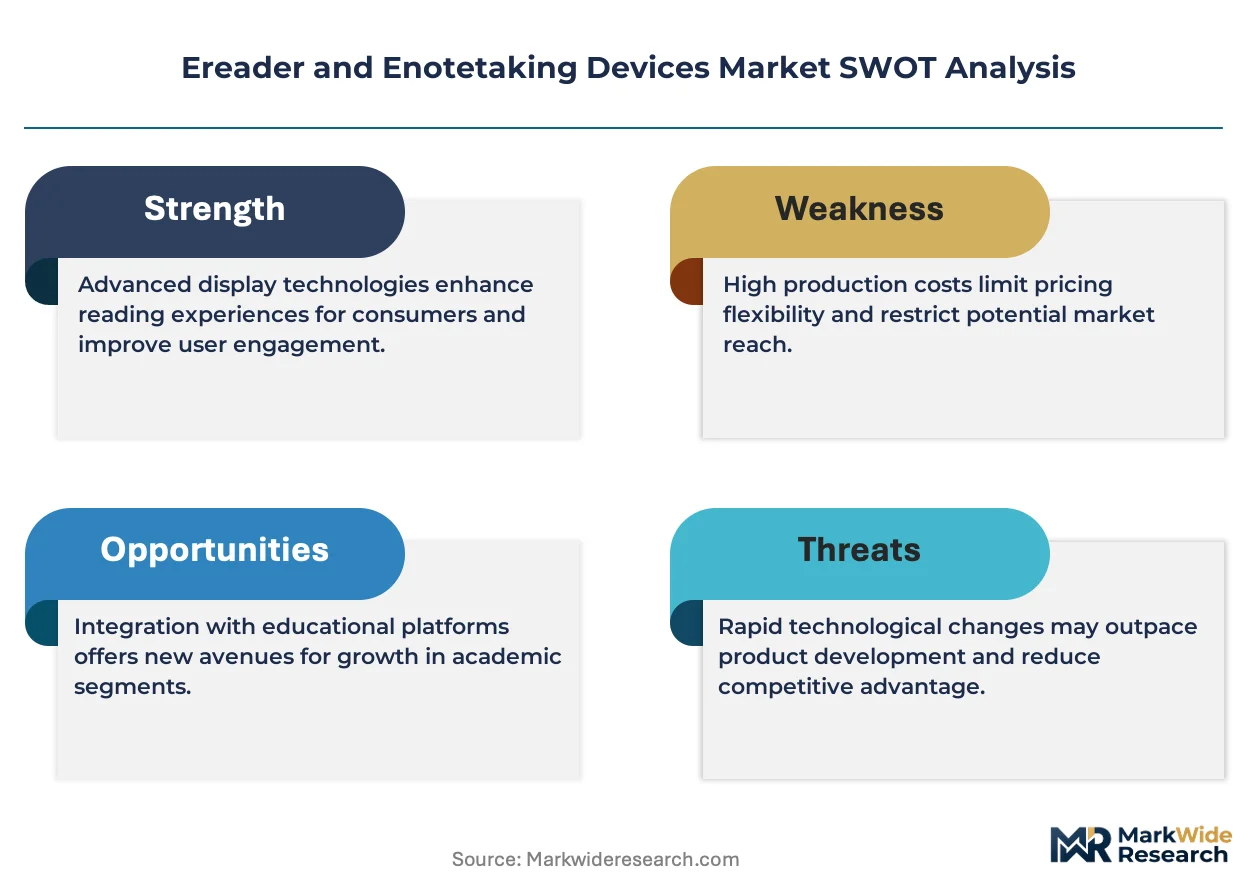
E-Ink Holdings foundry scale economies in Taiwan establish minimum viable production volumes that compress margin flexibility for mid-tier device assemblers. REACH compliance costs and FCC certification timelines further stratify pricing floors between institutional and consumer channels.
Pricing Analysis
FCC equipment authorization dictates the pricing tier structure for wireless-enabled ereaders, separating premium fleet-deployed tablets from entry-level reading devices. Pricing stratifies across premium, standard, and economy tiers based on EMR digitizer certification grade and volume procurement scale. Cost compression in the standard tier intensifies because reflective LCD alternatives from Sharp and Japan Display erode E-Ink's daylight-readability advantage. K-12 procurement channels exhibit highest price sensitivity, while legal discovery departments prioritize stylus protocol consistency over unit cost.
Supply Chain Analysis
Strategic stockpiling of E-Ink display modules ahead of academic purchasing cycles dominates inventory strategy over just-in-time preferences. Taiwan, China, and Germany anchor component sourcing, with Yangtze River Delta facilities managing color panel allocation and Bavarian clusters supplying EMR digitizer components. Manufacturing rests on lithium-ion cell supply from South Korea and Japan, plus microcapsule electrophoretic materials from single-source Taiwan foundries. Geopolitical transit disruptions through the Taiwan Strait constitute the primary structural risk. Distribution runs through university purchasing consortia and enterprise IT asset management channels rather than retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection favors ecosystem-integrated vendors as content lock-in and stylus protocol standardization displace hardware-only differentiation. Interoperability between annotation workflows and learning management systems now determines institutional procurement outcomes.
For Market Incumbents: Secure multi-year color panel production allocation from E-Ink Holdings ahead of university procurement cycles. Deepen backward integration into EMR digitizer firmware engineering to reduce dependency on Shenzhen and Hsinchu talent concentration. Defend against reflective LCD substitutes by embedding stylus latency performance into enterprise wellness subsidy negotiations. For New Entrants and Emerging Players: Lead with modular battery architectures and repairability score optimization to exploit California and New York right-to-repair thresholds in institutional bidding. Indian higher education digitization under National Digital Library infrastructure offers the most penetrable geography. Pursue localized distribution partnerships with Maharashtra and Karnataka technology hubs rather than direct retail presence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized large-format E-Ink fabricators with captive academic and legal verticals over mass-market consumer hardware. Long-term viability hinges on seven-year spare parts guarantee capabilities under EU CSRD sustainability disclosure rules. Watch for color E-Ink production capacity allocation decisions as the inflection signal for premium tier supply constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Color E-Ink Panel Pre-Positioning | Secures supply allocation from Taiwan foundries ahead of North American academic procurement windows. |
| EMR Digitizer Firmware Integration | Reduces stylus latency below 30ms threshold required by medical resident and legal professional adoption. |
| Repairability Score Optimization | Qualifies devices for German university consortium bid evaluation under mandatory sustainability criteria. |
| Enterprise Wellness Channel Development | Captures knowledge worker reimbursement programs defraying device costs in United States professional services. |
| Indian Distribution Partnership | Establishes first-mover position under streamlined BIS certification for National Digital Library deployments. |
Research Methodology
Cross-validation between primary interviews with university procurement officers and secondary analysis of FCC equipment authorization filings anchors the qualitative findings. Conversations with EMR digitizer engineers, legal discovery department IT managers, pharmaceutical regulatory affairs specialists, and E-Ink panel supply chain coordinators informed technology trajectory assessments. Secondary sources include ECHA substance restriction databases, BIS electronics certification records, CSRD sustainability disclosure frameworks, and higher education technology fee structure documentation. Bottom-up demand modeling from institutional procurement cycles triangulates against top-down market sizing from display panel production capacity data.
Sensitivity analysis around E-Ink Holdings foundry allocation decisions and lithium-ion raw material cost volatility shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, display technology tier, application vertical, end-user archetype, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, university adoption program expansion rates, and enterprise wellness subsidy penetration. Industry-specific forecast inputs incorporate color E-Ink refresh rate improvement trajectories and right-to-repair legislative passage timelines.
Underlying assumptions cover stable geopolitical transit conditions for Taiwan-origin display modules, with deviation risk concentrated in single-source electrophoretic manufacturing concentration. Forecasts reflect these documented conditions without scenario-weighting. Revision becomes warranted when E-Ink Holdings capacity allocation shifts toward alternative display applications or when EU spare parts availability mandates extend beyond seven-year thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Headsets for PC Market
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Smart Home Projector Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Wrist Dive Computer Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Personal Computer Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Gaming Phone Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
United States Gaming Peripherals Market