
 Europe Gaming Headset Market | 2026-2036
Europe Gaming Headset Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gaming Headset Market Insights
Market Context
CE marking compliance for radio equipment is collapsing the vendor landscape, as manufacturers must demonstrate conformity with RED 2014/53/EU before placing wireless headsets on the European market. SteelSeries leverages its Danish engineering base to sustain rapid certification cycles across multiple product lines. Sennheiser anchors its position through precision acoustic R&D facilities in Germany that compete on audiophile-grade reproduction standards.
Technical Definition and Segment Structure
A gaming headset is an audio peripheral combining circumaural or supra-aural earcups with an integrated boom microphone, engineered for low-latency voice communication and positional audio rendering in interactive software environments. The device serves competitive and immersive gaming applications where acoustic spatialization and noise-isolated voice capture directly influence user performance. Wireless product types are capturing disproportionate growth momentum as latency compression technologies mature, while over-ear configurations dominate the premium tier where extended session comfort determines repurchase behavior. Professional gamers and esports teams represent the most concentrated margin pool, as these buyers prioritize tournament-grade reliability over price sensitivity.
Regulatory Framework
EMA guidelines on acoustic exposure do not directly govern consumer electronics, but EU REACH restrictions on phthalates in PVC cabling and RoHS substance limits shape material selection across headset supply chains. ECHA substance evaluations are forcing reformulation of soft-touch plastics and cable sheathing used in mid-range and premium units. Stakeholders must monitor evolving EU battery regulations for wireless models, as replaceable cell requirements could reshape industrial design priorities and warranty cost structures across the value chain.
Market Dynamics
CE marking requirements under RED 2014/53/EU are compressing time-to-market cycles, forcing manufacturers to front-load compliance costs and consolidate certification resources ahead of product launches.
Growth Catalysts
- Esports professionalization:Tournament organizations are mandating standardized gear specifications, creating institutional procurement pipelines for certified equipment across Germany, France, and Nordic markets.
- REACH-driven material innovation:ECHA evaluations on phthalate alternatives are accelerating adoption of bio-based cable sheathing and thermoplastic elastomers in premium product lines.
- Low-latency wireless protocols:Proprietary 2.4 GHz transmission stacks are eliminating perceptible audio delay, erasing the performance gap that previously favored wired configurations in competitive environments.
Market Restraints
- Lithium supply concentration:Cell production for wireless headsets depends on Asian cathode material processors, exposing European assemblers to input volatility and forced stockpiling.
- Acoustic driver fabrication bottlenecks:Precision neodymium magnet sourcing remains concentrated among a limited supplier base, constraining unit volume scaling for mid-tier manufacturers.
- EU battery regulation uncertainty:Pending replaceable cell mandates threaten to obsolete current sealed-unit industrial designs and inflate warranty cost structures across the value chain.
Strategic Opportunities
- Modular architecture platforms:Swappable microphone booms and earcup cushions enable aftermarket revenue streams while extending product lifecycles under circular economy frameworks.
- Cloud gaming infrastructure expansion:Latency-tolerant streaming services are democratizing high-fidelity audio requirements, opening addressable demand among casual users previously priced out of dedicated hardware.
- France's esports federation accreditation:National certification programs are creating preferential procurement channels for vendors meeting domestic competitive standards.
Industry Challenges
- Acoustic engineering talent scarcity:Spatial audio algorithm development requires rare cross-disciplinary expertise combining psychoacoustics and real-time processing optimization.
- RoHS substance compliance verification:Supply chain auditing for restricted heavy metals in solder and plating adds documentation burden and extends qualification timelines for new component vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gaming Headset Market |
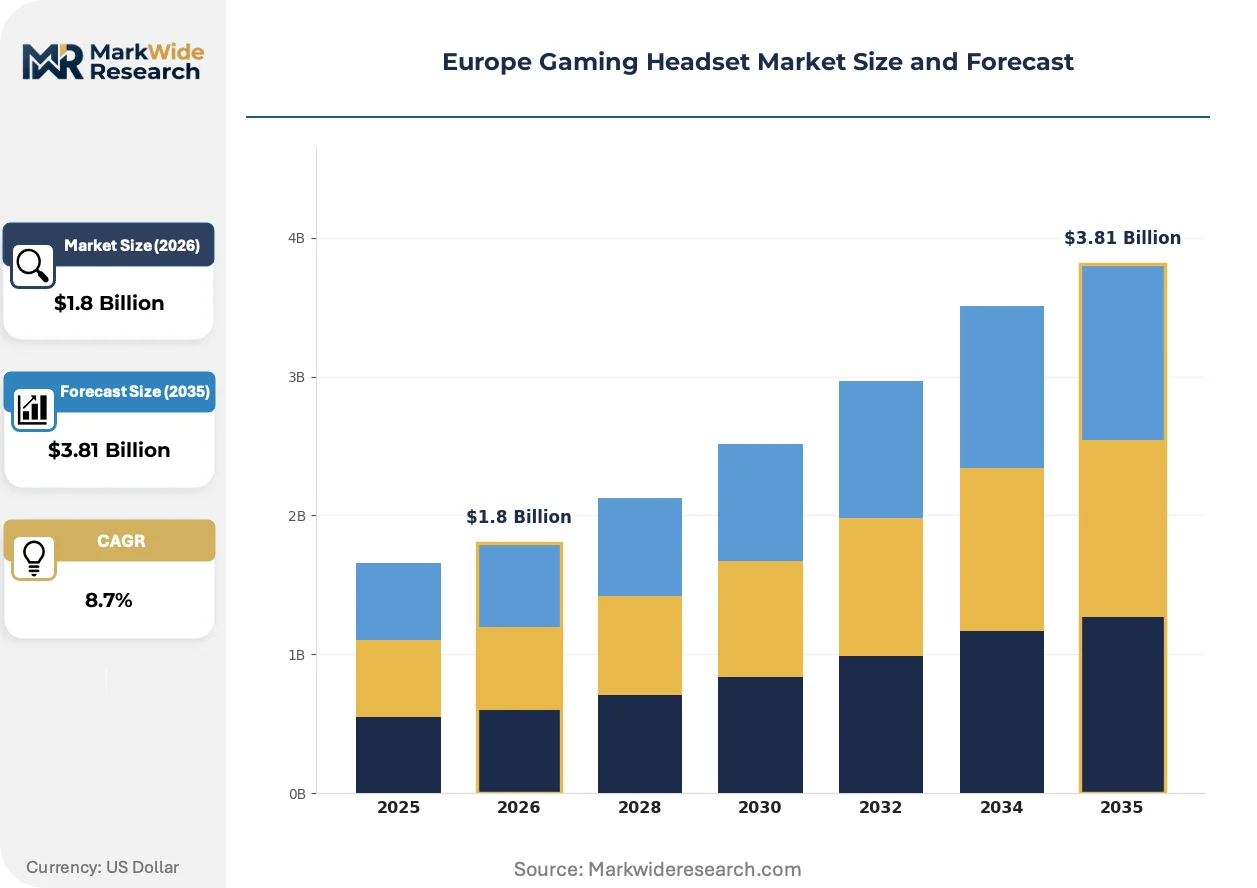
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, On-ear, Over-ear End User: Professional Gamers, Casual Gamers, Streamers, Esports Teams Feature: Noise Cancellation, Surround Sound, Built-in Microphone, RGB Lighting Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | SteelSeries, Sennheiser, Logitech International S.A., HyperX, Sony, Corsair Gaming, Inc., Turtle Beach Corporation, Beyerdynamic, Razer Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gaming Headset Market Trends and Innovations
Wireless latency compression is eroding the last technical justification for wired peripherals, while regulatory pressure on material composition is forcing concurrent redesign of mechanical and electronic subsystems.
Beamforming microphone arrays are displacing traditional unidirectional boom designs in tournament-grade equipment. Esports organizations in Germany and the Netherlands are adopting these configurations for broadcast-grade voice isolation without mechanical obtrusion. This shift is displacing incumbent electret condenser architectures and compressing the supplier base toward MEMS fabrication specialists with RF integration capabilities.
EU battery regulations are mandating user-replaceable power cells for wireless consumer electronics by mid-decade. Industrial design teams must now accommodate cell compartment access without compromising acoustic isolation or structural integrity. Premium manufacturers with Danish and German engineering bases are responding with tool-less latch mechanisms that preserve IP ratings.
Direct-to-team procurement contracts are consolidating purchasing authority away from retail channels. Esports organizations in France and Spain are negotiating volume agreements with manufacturers for standardized squad equipment, bypassing distributor markups. This concentration is most visible in Germany's Bundesliga-affiliated gaming divisions, where gear standardization supports coaching consistency and reduces compatibility failures during international travel.
Europe Gaming Headset Market Segmentation
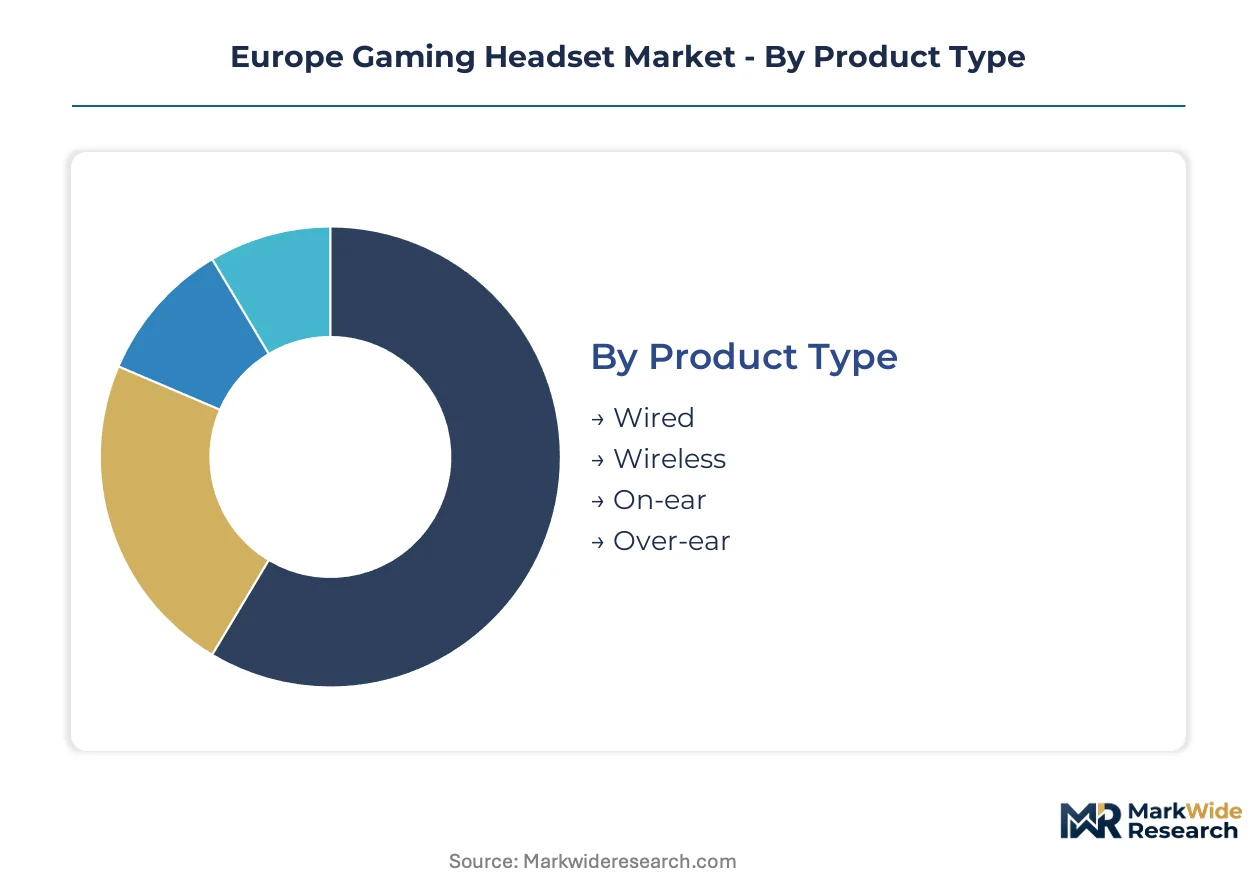
Segmentation in the Europe Gaming Headset Market reveals how margin pools concentrate around wireless protocols and professional-grade specifications. Procurement patterns diverge sharply between institutional buyers and individual consumers, with regulatory compliance costs reshaping viable competitive positions across each slice.
Product Type:
Margin pools concentrate in wireless configurations where low-latency engineering commands sustained price premiums, while over-ear designs dominate session-comfort monetization.
- Wired:USB and 3.5mm analog connections deliver uncompressed audio streams with zero transmission latency. Tournament organizers in Germany specify wired backup configurations for championship finals where RF interference risks disqualification. Budget-tier manufacturers in Eastern Europe maintain volume production here as CE marking complexity stays minimal.
- Wireless:Proprietary 2.4 GHz transmission stacks from Danish engineering houses eliminate perceptible delay while preserving mobility. French esports federations mandate wireless certification for squad equipment standardization. Battery cell sourcing from Asian cathode processors constrains margin expansion despite retail price premiums.
- On-ear:Supra-aural designs prioritize portability for mobile gaming and co-working environments. Italian commuter gaming segments show residual demand here.
- Over-ear:Circumaural isolation dominates premium tier comfort engineering. Extended session wearability drives repurchase loyalty among German PC gaming enthusiasts.
Wired holds installed capacity in tournament infrastructure. Wireless is rotating up the share rankings as latency compression matures.
End User:
Application intensity varies from institutional procurement with multi-year replacement cycles to impulse-driven individual purchases.
- Professional Gamers:Individual competitors operating outside formal team structures prioritize personal equipment consistency across practice and tournament environments. Precision acoustic R&D from German facilities shapes their driver selection criteria. Sponsorship dependency creates volatile replacement timing.
- Casual Gamers:Weekend and evening players constitute volume demand but exhibit extreme price elasticity. Cloud gaming service expansion in Spain and Portugal is democratizing hardware requirements for this cohort. Retail channel promotions drive seasonal purchasing spikes.
- Streamers:Broadcast-quality microphone performance and aesthetic customization dominate specification sheets. RGB lighting integration and boom arm compatibility differentiate viable products.
- Esports Teams:Institutional buyers in France, Germany, and the Netherlands negotiate direct manufacturer contracts bypassing distributor markups. Standardized squad equipment reduces coaching friction and travel compatibility failures.
Esports teams concentrate procurement authority. Streamers are climbing the fastest as content monetization professionalizes.
Feature:
Technology integration costs determine which capabilities sustain premium pricing versus commoditization.
- Noise Cancellation:Active acoustic suppression requires dedicated DSP hardware and multiple microphone arrays. Battery drain tradeoffs limit deployment in wireless tournament-grade units.
- Surround Sound:Spatial audio algorithms from Scandinavian psychoacoustics labs create positional accuracy advantages in competitive first-person environments. Head-related transfer function personalization remains niche.
- Built-in Microphone:MEMS fabrication specialists with RF integration capabilities are displacing traditional electret condenser architectures. Beamforming arrays in Dutch and German tournament equipment isolate voice without mechanical boom obtrusion.
- RGB Lighting:Addressable LED ecosystems synchronize with peripheral ecosystems for streamer aesthetic requirements. Power consumption engineering constrains wireless implementations.
Built-in microphone holds installed capacity in team specifications. Surround sound is gaining share fastest as spatial audio training professionalizes.
Price Tier:
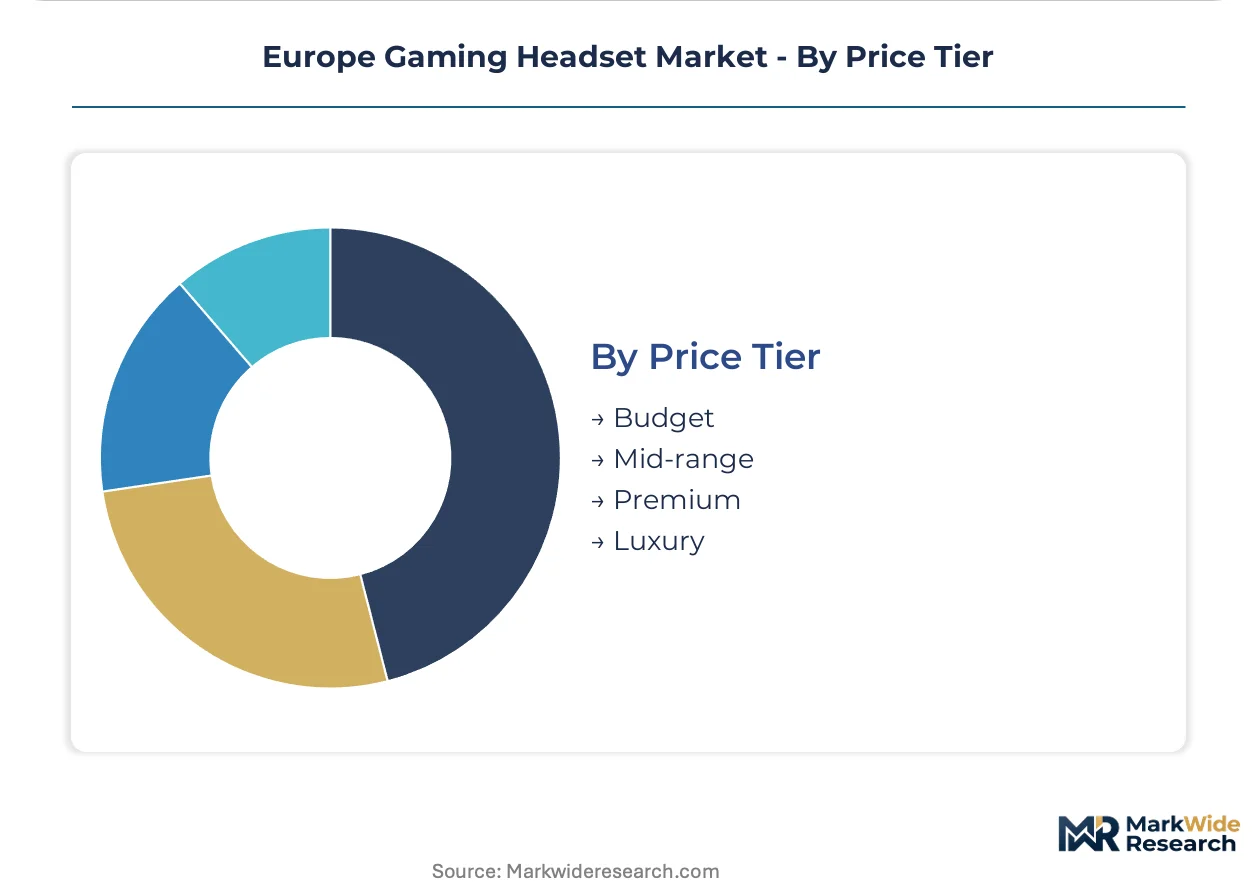
Cost stratification aligns with certification burden and material composition complexity under REACH and RoHS frameworks.
- Budget:PVC cabling and standard neodymium drivers dominate bill-of-materials. ECHA phthalate restrictions are forcing rapid supply chain reformulation.
- Mid-range:Thermoplastic elastomer sheathing and modular cushion architectures extend product lifecycles. Bio-based cable materials from Nordic suppliers penetrate here first.
- Premium:Tool-less battery access mechanisms preserve IP ratings under pending EU replaceable cell mandates. Danish and German engineering bases lead industrial design responses.
- Luxury:Audiophile-grade driver matching and limited material runs target collector segments. Sennheiser's precision acoustic R&D facilities in Germany anchor this tier.
Premium holds installed capacity in professional procurement. Mid-range is rotating up the share rankings as REACH compliance costs compress budget viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Central Europe's role as the continent's logistics backbone for consumer electronics distribution, connecting assembly hubs to retail channels across ten member states.
Germany
PC gaming hardware spending outpaces all European markets, with esports team procurement professionalizing gear standards nationwide. CE marking requirements under RED 2014/53/EU compress time-to-market for wireless headset launches. Precision acoustic R&D facilities in Hamburg and Berlin compete on audiophile-grade reproduction standards.
France
The national esports federation operates accreditation programs creating preferential procurement channels for certified equipment. REACH restrictions on phthalates in PVC cabling force reformulation of soft-touch plastics used in mid-range units. Industrial design clusters in Lyon respond with bio-based thermoplastic elastomer innovations.
Netherlands
Rotterdam's port infrastructure handles cathode material imports for wireless headset battery cells, exposing assemblers to lithium supply volatility. ECHA substance evaluations drive adoption of alternative cable sheathing compounds. Eindhoven's MEMS fabrication specialists supply beamforming microphone arrays for tournament-grade equipment.
United Kingdom
Post-Brexit regulatory divergence complicates CE marking alignment for products entering both UK and EU markets. Streamer content monetization professionalizes demand for broadcast-quality microphone performance. Greater Manchester's peripheral manufacturing base concentrates on RGB lighting ecosystem integration.
Denmark
Danish engineering houses sustain rapid certification cycles across multiple wireless product lines, leveraging proximity to EU regulatory bodies. Pending replaceable cell mandates under EU battery regulations reshape industrial design priorities. Copenhagen-based firms pioneer tool-less latch mechanisms preserving IP ratings.
Europe Gaming Headset Market Competitive Landscape
Listed leaders compete with private specialists across certification velocity and acoustic engineering depth, creating a tiered structure where scale advantages clash with boutique precision. The vendor base segments between mass-market distributors and premium-tier specialists. Two strategic archetypes dominate: Scandinavian engineering houses optimizing regulatory compliance speed, and German precision audio laboratories competing on driver matching standards. Competitive moves concentrate on modular architecture platforms enabling aftermarket revenue, and direct-to-team procurement contracts bypassing retail markups.
Within the precision audio tier, Sennheiser exemplifies engineering-led positioning through its German GmbH structure and heritage acoustic facilities. SteelSeries anchors the Nordic compliance-velocity archetype as a Danish specialist. Logitech International S.A. represents the scale-driven listed competitor with Swiss-incorporated operations spanning mass-market distribution. These three occupy distinct competitive spaces rather than direct confrontation.
| Leading Market Players |
|---|
| SteelSeries |
| Sennheiser |
| Logitech International S.A. |
| HyperX |
| Sony |
| Corsair Gaming, Inc. |
| Turtle Beach Corporation |
| Beyerdynamic |
| Razer Inc. |
| Others |
Pricing and Supply Chain Analysis
Bio-based thermoplastic elastomers replacing phthalate-laden PVC cabling simultaneously relocate cable sheathing production toward Nordic chemical clusters and compress margin viability in budget-tier assemblies dependent on legacy materials. This substitution dynamic concentrates pricing power with REACH-compliant material suppliers while forcing mid-range manufacturers to absorb reformulation costs or retreat from contested price bands.
Pricing Analysis
Certification level under RED 2014/53/EU creates the primary spread between premium wireless configurations and budget wired alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects divergent compliance burdens, with CE marking velocity commanding sustained premiums from Danish engineering houses. Cost compression in the economy tier intensifies as ECHA phthalate restrictions eliminate low-cost cable sourcing from Eastern European compounders. Esports teams exhibit minimal price sensitivity while casual gamers in Southern Europe demonstrate extreme elasticity, concentrating volume discounting pressure in retail channels.
Supply Chain Analysis
China and South Korea anchor cathode material processing for lithium-ion cells, while Taiwan and Japan concentrate precision neodymium magnet fabrication for acoustic drivers. European assemblers draw from these Asian inputs for wireless headset production, exposing margin structures to lithium carbonate volatility and rare earth export licensing shifts. Single-source vulnerability in MEMS microphone arrays from Dutch fabrication specialists threatens tournament-grade equipment availability. Distribution runs through Rotterdam port infrastructure into Rhine-Main-Danube logistics corridors serving German retail concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular aftermarket ecosystems represent a service-attach opportunity expanding faster than hardware unit sales, as replaceable battery compartments and swappable earcup cushions generate recurring revenue streams under circular economy frameworks.
For Market Incumbents: Consolidate certification velocity advantages by embedding Danish regulatory affairs teams within product development cycles, preempting CE marking delays that expose market share to nimbler competitors. Deepen backward integration into bio-based cable sheathing through Nordic supplier partnerships, securing REACH-compliant material allocation before capacity constraints tighten. Prioritize tool-less battery access mechanisms that preserve IP ratings under pending EU mandates. For New Entrants and Emerging Players: Anchor in France's esports federation accreditation programs, exploiting preferential procurement channels for certified equipment that bypasses established distributor relationships. Target streamer segments in Spain and Portugal where content monetization professionalization outpaces hardware vendor coverage. Pursue cloud gaming service bundling arrangements that reduce customer acquisition costs versus retail channel entry. For Investors and Strategic Acquirers: Pending EU battery regulations mandating user-replaceable cells reshape the acquisition landscape toward industrial design capabilities rather than pure acoustic engineering depth. Five-to-ten-year viability favors targets with modular architecture platforms and established aftermarket revenue streams over sealed-unit specialists facing obsolescence risk. Monitor ECHA substance evaluation timelines as inflection indicators for material cost restructuring across portfolio holdings.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration Program | Danish engineering houses compress certification cycles ahead of RED 2014/53/EU enforcement windows. |
| Modular Platform Architecture | Tool-less battery compartments and swappable cushions extend product lifecycles under circular economy frameworks. |
| Direct-to-Team Procurement Contracts | French and German esports organizations bypass distributor markups through volume standardization agreements. |
| Bio-Based Material Integration | Nordic suppliers of thermoplastic elastomer sheathing capture share from phthalate-dependent PVC compounders. |
| Beamforming Microphone Adoption | Dutch MEMS fabrication specialists displace electret condenser architectures in tournament-grade equipment. |
Research Methodology
A spread of perspectives from product managers at Danish engineering houses, regulatory affairs specialists navigating ECHA evaluations, procurement directors at French esports federations, and acoustic R&D leads at German precision audio laboratories converged on the working assumptions. Primary interview insights combined with secondary validation from EU regulatory filings, REACH substance restriction updates, customs trade data for lithium cell imports, and esports tournament equipment specifications. Bottom-up unit demand modeling triangulated against top-down market sizing from peripheral hardware spending surveys.
Segmentation dimensions modeled include wireless versus wired connectivity protocols, over-ear versus on-ear form factors, professional versus casual end-user archetypes, and premium versus budget price tiers across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns of low-latency wireless technologies and esports professionalization indicators. Forecast inputs incorporated REACH compliance cost trajectories and EU battery regulation implementation uncertainty.
Material uncertainties — lithium supply disruption, ECHA substance evaluation acceleration, and esports federation accreditation program expansion — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline stability and cathode material pricing continuity. Recalibration cycles align with material shifts in regulatory enforcement intensity and wireless protocol adoption inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Global Digital Watch Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Gaming Laptop Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Tablet Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Chromebook Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
DVD Remote Controls Market