
 Global Monitor Headphones (in-Ear Monitors) Market | 2026-2036
Global Monitor Headphones (in-Ear Monitors) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monitor Headphones (in-Ear Monitors) Market Outlook
Professional audio buyer concentration is consolidating around touring companies, broadcast networks, and large venue operators that negotiate fleet-scale IEM deployments. Shure leverages its decades-long relationships with major touring artists to sustain channel dominance in North American live sound. Sennheiser competes through precision-engineered driver architectures that anchor its position in European broadcast and classical recording segments. Ultimate Ears differentiates via custom-molded earpiece manufacturing that controls the premium musician tier.
Monitor headphones, specifically in-ear monitors, are sealed or vented ear-canal devices housing balanced-armature or dynamic drivers with frequency responses typically spanning 20 Hz to 20 kHz, engineered to deliver isolated reference audio to performers and engineers during live monitoring or critical listening sessions. Wired IEM configurations still dominate professional stage applications where latency tolerance approaches zero, while wireless Bluetooth and active noise cancellation segments are expanding fastest among audiophile and commuter-adjacent general consumers who accept slight fidelity trade-offs for cable-free mobility. Sound engineers and musicians represent the deepest margin pools, as these buyers prioritize driver-matching precision and custom fit over unit economics.
The Federal Communications Commission governs wireless transmission bands for IEM systems in the United States, forcing manufacturers to navigate spectrum reallocation and interference management in RF-dependent product lines. Japan's Ministry of Economy, Trade and Industry and Germany's Federal Network Agency impose parallel equipment authorization frameworks that shape regional product certification roadmaps. South Korea's radio regulatory authority and Brazil's national telecommunications agency add further compliance layers for brands distributing across Asia-Pacific and Latin American touring circuits. Stakeholders must monitor spectrum policy harmonization and driver miniaturization trajectories to anticipate where wireless IEM architectures displace traditional wired monitoring infrastructure.
Market Dynamics
Bluetooth LE Audio and Auracast broadcast protocols are fragmenting connectivity architectures across professional and consumer IEM tiers, forcing manufacturers to dual-develop wired RF and native wireless product lines while spectrum reallocation pressures compound hardware design complexity.
Growth Catalysts
- Live touring recovery:Concert and festival production volumes in the United States, Germany, and Brazil are rebuilding artist monitor inventory cycles, with fleet-scale procurement returning to pre-pandemic replacement cadences.
- REACH substance restrictions:European chemical compliance mandates are accelerating driver diaphragm material substitutions toward bio-based polymers that reduce unit weight and improve extended-wear comfort for stage performers.
- Balanced-armature miniaturization:Knowles and Sonion multi-driver configurations now enable five-way crossover designs in compact universal-fit shells, democratizing custom-tier acoustic performance.
Market Restraints
- Rare-earth magnet volatility:Neodymium price swings tied to Chinese export quotas compress margin stability for dynamic driver manufacturers reliant on permanent magnet assemblies.
- RF spectrum congestion:FCC 600 MHz band reclamation and parallel European reallocations force hardware redesigns and limit available wireless channel density for large-venue IEM deployments.
- Custom-mold production bottlenecks:Audiologist network capacity constraints in secondary touring markets extend fulfillment timelines for personalized earpiece manufacturing.
Strategic Opportunities
- India live entertainment infrastructure:Arena and auditorium construction in Mumbai, Delhi, and Bangalore is creating first-time installed base demand for venue-owned monitor systems.
- Bluetooth Auracast venue broadcasting:Direct-to-listener multicast protocols enable hearing-accessibility compliance and open auxiliary revenue streams for theaters and houses of worship.
- South Korea broadcast standardization:KBS and MBC network specifications for immersive audio production are mandating multi-channel monitor compatibility in studio procurement tenders.
Industry Challenges
- Acoustic engineer scarcity:Specialized crossover tuning expertise for multi-BA configurations concentrates among legacy hearing-aid industry talent pools, constraining product development velocity.
- Certification timeline fragmentation:Divergent RF equipment authorization pathways across Japan's TELEC, South Korea's RRA, and Brazil's Anatel extend regional launch windows by 8-14 months.
- Legacy wired infrastructure compatibility:Touring rental houses maintain substantial inventory of analog bodypack systems, complicating wireless-native product adoption and hybrid system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monitor Headphones (in-Ear Monitors) Market |
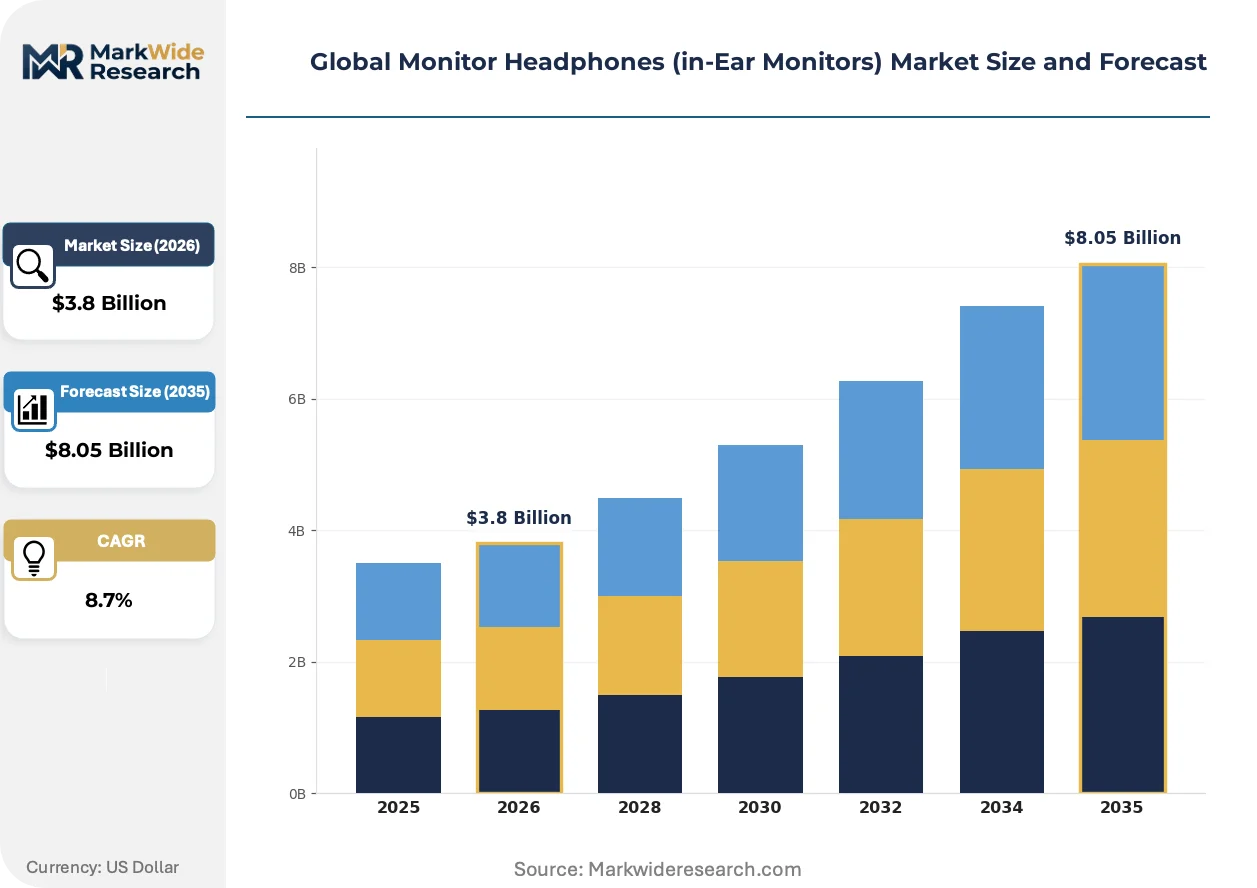
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Noise Cancelling, Open-Back End User: Musicians, Audiophiles, General Consumers, Sound Engineers Technology: Bluetooth, Active Noise Cancellation, Driver Type, Connectivity Distribution Channel: Online Retail, Brick-and-Mortar, Direct Sales, Specialty Stores |
| Companies Covered | Shure, Sennheiser, Sony, Audio-Technica, AKG, Beyerdynamic, Yamaha, Ultimate Ears, Westone Audio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monitor Headphones (in-Ear Monitors) Market Strategic Shifts
Acoustic engineering and RF connectivity are converging in ways that dissolve traditional boundaries between stage monitor, hearing assistance, and consumer audio categories, with protocol standardization and miniaturization as the twin enablers.
Multi-BA driver arrays with 3D-printed acoustic chambers are unifying frequency response precision across universal and custom-fit form factors. Shure and Sennheiser engineering teams are deploying these architectures in mid-tier musician products previously limited to boutique atelier manufacturers. The technology is compressing the performance gap between thousand-dollar custom molds and three-hundred-dollar universal monitors.
FCC Part 74 spectrum reallocation continues reshaping wireless IEM transmission hardware requirements, with manufacturers redesigning RF front-ends to operate in newly available 941-960 MHz guard bands. This regulatory pressure is accelerating digital modulation adoption over analog UHF architectures. North American touring rental companies are absorbing the steepest equipment refresh costs as legacy 500-600 MHz systems face operational sunset.
Direct-to-artist online configuration tools are displacing traditional audiologist-mediated custom fitting workflows. Ultimate Ears and similar atelier brands now ship impression kits with smartphone-guided capture applications, reducing geographic dependency on certified fitters. Japan and South Korea exhibit the highest self-service adoption rates, where mobile-first consumer behavior and dense urban logistics infrastructure support rapid turnaround mold production.
Global Monitor Headphones (in-Ear Monitors) Market Segmentation
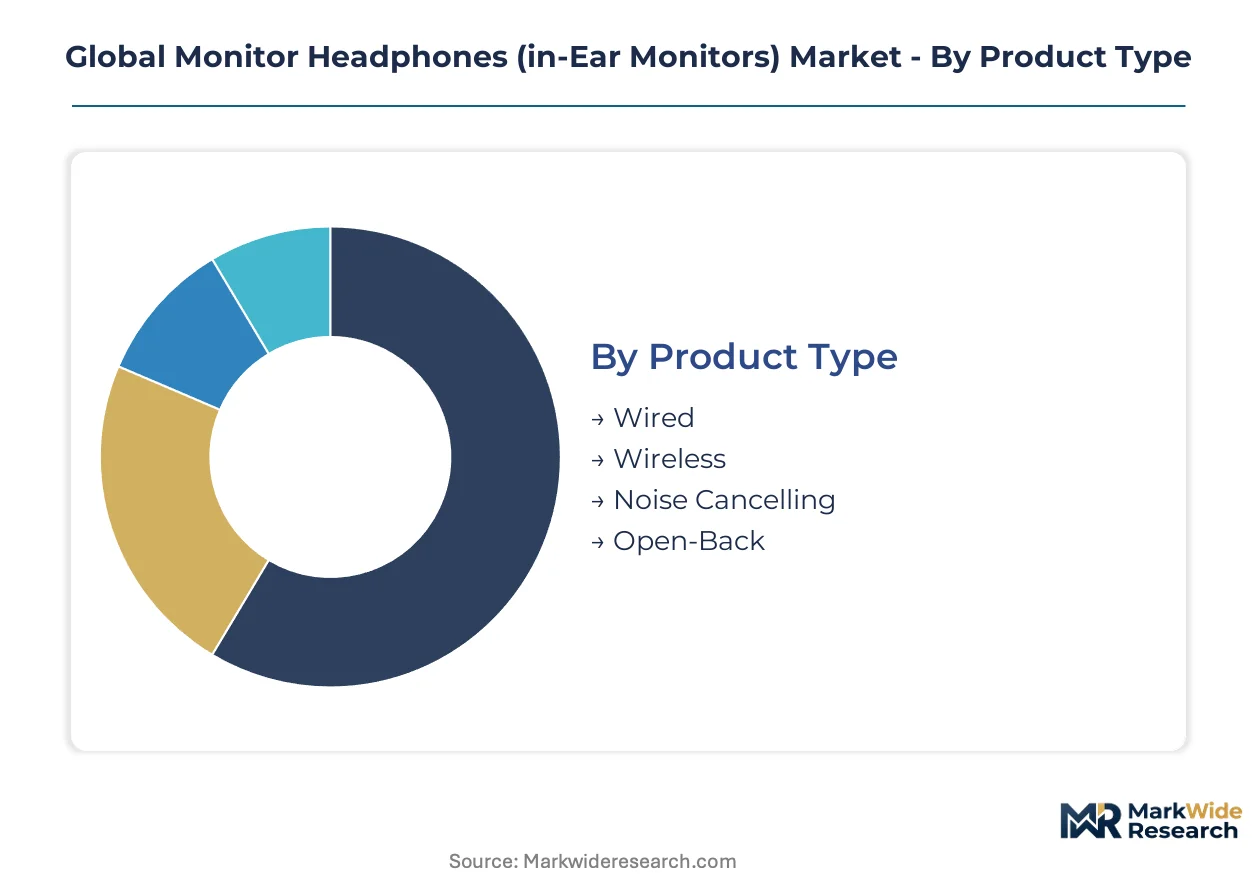
Segmentation in the monitor headphones market reflects divergent performance requirements across professional stage monitoring and consumer audio consumption. Driver architecture, connectivity protocol, and procurement channel each create distinct margin structures and competitive dynamics for manufacturers.
Product Type:
Wired configurations retain dominance where latency tolerance approaches zero, while wireless architectures gain ground among mobile-first users accepting fidelity trade-offs.
- Wired:Balanced-armature and dynamic driver assemblies with zero-latency analog or digital connectivity anchor professional stage monitoring. Demand concentrates with touring musicians and broadcast engineers in the United States and Germany where RF spectrum congestion makes wireless reliability unpredictable.
- Wireless:Bluetooth LE Audio and proprietary RF transmission systems enable cable-free mobility for performers and commuters. Adoption is climbing fastest in South Korea and Japan where smartphone-guided self-fitting workflows reduce dependency on audiologist networks.
- Noise Cancelling:Hybrid feedforward-feedback architectures with multiple microphones per earpiece target audiophile and frequent-flyer segments.
- Open-Back:Ventilated acoustic designs prioritize soundstage width over isolation, serving critical listening applications in controlled studio environments.
Mature deployment sits with wired systems. Newer deployment is concentrated in wireless configurations.
End User:
Buyer sophistication spans from technically demanding professionals to convenience-oriented general consumers, with margin depth inversely correlated with price sensitivity.
- Musicians:Custom-molded and universal-fit IEMs with multi-BA driver arrays demand precise frequency response matching for stage monitoring. Fleet-scale procurement by touring companies in Brazil and the United States drives volume concentration.
- Sound Engineers:Reference-grade monitors with flat frequency response and extended dynamic range support critical mixing decisions. European broadcast networks and classical recording studios in Germany represent the deepest specification requirements.
- Audiophiles:Enthusiast buyers prioritize driver-matching precision and premium materials over mass-market feature sets.
- General Consumers:Bluetooth convenience and active noise cancellation outweigh acoustic fidelity for commuter and casual listening applications.
Established demand centers on musicians and sound engineers. Expanding most quickly among general consumers adopting wireless convenience features.
Technology:
Connectivity protocol and acoustic engineering architectures are converging as Bluetooth LE Audio and Auracast reshape hardware design requirements.
- Bluetooth:LE Audio with Auracast broadcast capability enables direct-to-listener multicast in theaters and houses of worship. Regulatory pressure from FCC spectrum reallocation accelerates adoption in North American touring circuits.
- Active Noise Cancellation:Hybrid ANC with adaptive algorithms targets environmental noise across variable acoustic conditions. Integration is deepening fastest in premium commuter and aviation-adjacent segments.
- Driver Type:Balanced-armature miniaturization from Knowles and Sonion enables multi-way crossovers in compact shells.
- Connectivity:Analog UHF, digital RF, and native Bluetooth architectures compete across latency-sensitive and convenience-oriented use cases.
Legacy dominance rests with analog connectivity. Steepest expansion trajectory belongs to Bluetooth LE Audio implementations.
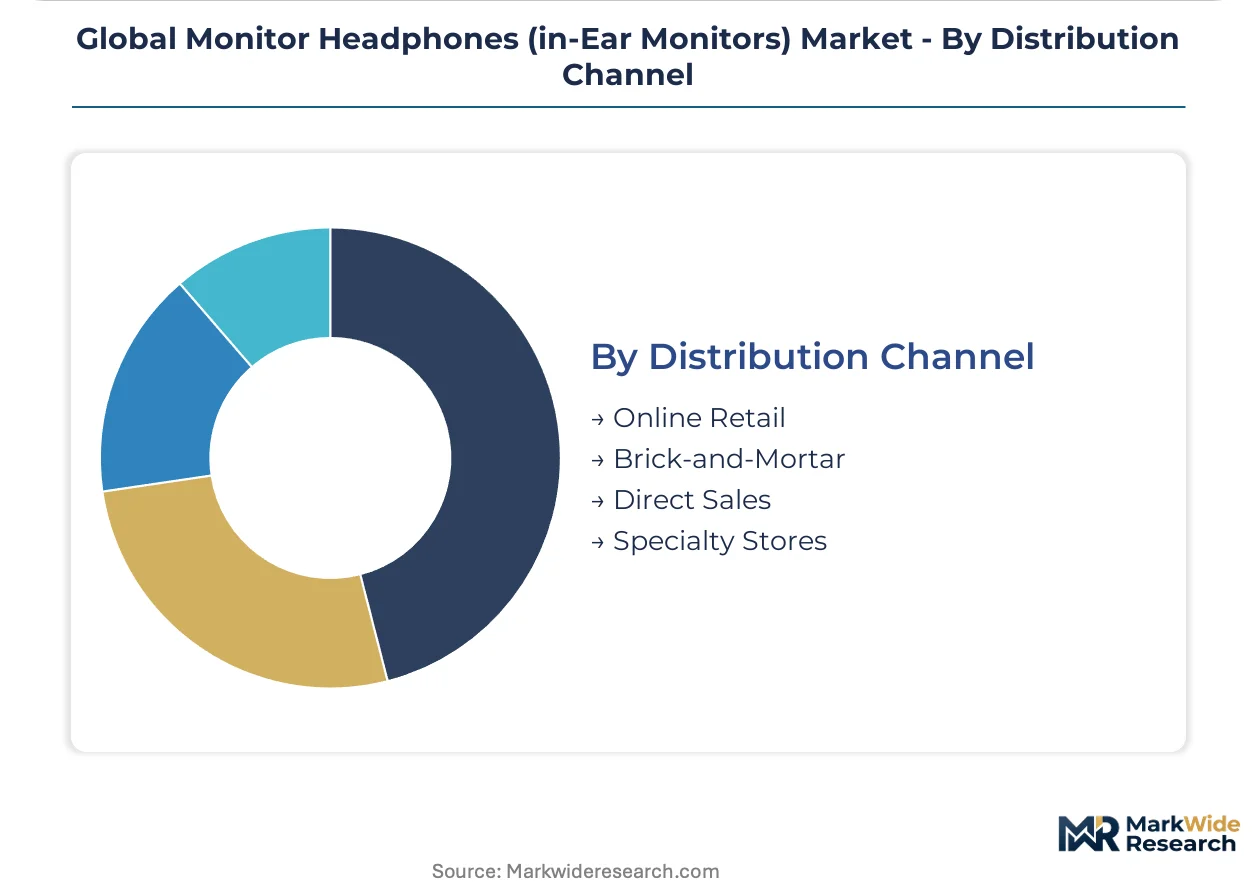
Distribution Channel:
Channel strategy must accommodate both high-touch professional procurement and automated consumer fulfillment.
- Online Retail:Direct-to-artist configuration tools with smartphone-guided impression capture displace traditional audiologist workflows. Japan and South Korea exhibit highest self-service adoption rates where dense urban logistics support rapid mold turnaround.
- Direct Sales:Manufacturer-direct relationships with touring companies and broadcast networks enable fleet-scale negotiation and custom specification.
- Specialty Stores:Professional audio retailers with demonstration facilities and fitting expertise serve musician and audiophile segments requiring tactile evaluation.
- Brick-and-Mortar:General electronics retail captures impulse-driven consumer purchases with lower specification requirements.
Volume concentrates in online and direct channels. Physical specialty retail retains importance for professional verification and custom fitting services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neodymium magnet supply chains anchored in Chinese processing facilities shape driver manufacturing economics across major IEM production centers. Spectrum regulatory fragmentation and touring infrastructure density create divergent growth trajectories across national markets.
United States
Live touring recovery in Nashville, Los Angeles, and Austin rebuilds artist monitor inventory cycles. FCC Part 74 spectrum reallocation forces RF hardware redesigns for 941-960 MHz guard band operation. Fleet-scale procurement by touring rental houses concentrates demand in these metropolitan production hubs.
Germany
European broadcast networks and classical recording studios in Berlin and Hamburg sustain reference-grade monitor specifications. The Federal Network Agency imposes equipment authorization frameworks that shape regional certification roadmaps. Precision-engineered driver architectures from Bavarian manufacturing clusters serve continental studio infrastructure.
Japan
METI equipment standards and dense urban logistics support rapid-turnaround custom mold production. Smartphone-guided self-fitting workflows achieve highest adoption rates in Tokyo and Osaka. KBS and MBC network specifications for immersive audio production mandate multi-channel monitor compatibility in domestic procurement.
South Korea
Seoul Capital Area concentration of K-pop production facilities drives wireless IEM adoption for performance choreography. The Radio Research Agency adds compliance layers for brands distributing across Asia-Pacific touring circuits. Bluetooth LE Audio implementation accelerates fastest among domestic smartphone-integrated workflows.
Brazil
São Paulo and Rio de Janeiro arena construction creates first-time installed base demand for venue-owned monitor systems. Anatel telecommunications certification extends regional launch timelines for imported RF equipment. Touring activity recovery across major music economies rebuilds replacement cadences for artist inventory.
Global Monitor Headphones (in-Ear Monitors) Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent consumer audio and hearing assistance applications. The vendor base concentrates around legacy professional audio manufacturers with decades-long touring relationships and specialized atelier brands controlling custom-molded segments. Three archetypes dominate: RF transmission specialists, multi-driver acoustic engineering houses, and direct-to-artist digital configurators. Competitive moves center on dual-protocol hardware development and audiologist network capacity expansion.
Among heritage professional audio manufacturers, Shure, Sennheiser, and Ultimate Ears occupy positions spanning wireless transmission, precision driver architecture, and custom-molded manufacturing respectively. These entities exemplify distinct strategic vectors within the market structure. Shure represents channel dominance through artist relationship networks. Sennheiser anchors European broadcast and classical recording specifications. Ultimate Ears exemplifies premium-tier custom manufacturing with direct-to-consumer digital fitting workflows.
| Leading Market Players |
|---|
| Shure |
| Sennheiser |
| Sony |
| Audio-Technica |
| AKG |
| Beyerdynamic |
| Yamaha |
| Ultimate Ears |
| Westone Audio |
| Others |
Value Chain & Pricing Dynamics
Fleet-scale touring rental houses and broadcast network procurement teams command the dominant pricing leverage in professional IEM tiers, compressing margin structures for manufacturers dependent on volume offtake agreements. This buyer concentration enforces contract-based long-term procurement frameworks that tether unit economics to multi-year replacement cycles and RF hardware refresh mandates.
Pricing Analysis
Volume-mass market wireless configurations trade at thinner margins than precision-engineered custom-molded tiers. Three-tier pricing structure across premium, standard, and economy levels separates audiologist-fitted multi-BA arrays from universal-fit commuter products and entry-level musician monitors. Pricing pressure stems from neodymium magnet volatility and FCC-mandated RF front-end redesigns. General consumers exhibit highest price sensitivity, while sound engineers and touring musicians prioritize driver-matching precision over unit economics.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Seoul, and Penang anchor hub-and-spoke fulfillment patterns for driver components and finished assemblies. Manufacturing draws from Chinese rare-earth processing facilities, Malaysian electronics packaging clusters, and Bavarian precision acoustic engineering centers. Single-source vulnerability concentrates in neodymium magnet supply chains tethered to Chinese export quota regimes. Distribution runs through manufacturer-direct channels for professional tiers and online retail platforms for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market has become a vertical-integration race as manufacturers pursue captive control over balanced-armature driver production to escape Knowles and Sonion pricing power and secure acoustic engineering talent pools.
For Market Incumbents: Lock in audiologist network capacity across secondary touring markets to defend custom-mold fulfillment timelines against digital self-fitting disruptors. Secure long-term neodymium supply agreements or invest in ferrite magnet R&D to insulate margin structures from Chinese export quota volatility. Backward integration into multi-BA driver manufacturing reduces dependency on Sonion and Knowles component pricing. For New Entrants and Emerging Players: Direct-to-artist online configuration platforms represent the most penetrable channel wedge, particularly in Japan and South Korea where smartphone-guided impression capture achieves highest adoption. Target hearing-assistance accessibility compliance as a regulatory tailwind for Auracast-enabled multicast products in theater and house-of-worship verticals. Pursue white-label manufacturing partnerships with established RF transmission specialists to bypass FCC and Anatel certification timeline barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated acoustic engineering houses with captive multi-BA driver production and established touring artist relationships. Acquisition targets should demonstrate sustained procurement relationships with major broadcast networks or fleet-scale touring rental companies. Monitor FCC spectrum reallocation implementation velocity as an inflection indicator for wireless-native product displacement of analog UHF architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Audiologist Network Expansion | Direct-to-artist digital fitting workflows in Japan and South Korea compress fulfillment timelines for custom molds. |
| Multi-BA Driver Manufacturing Scale-Up | In-house production of balanced-armature arrays reduces dependency on Knowles and Sonion component supply. |
| Bluetooth LE Audio Platform Integration | Auracast multicast capability enables hearing-accessibility compliance in theater and worship venue installations. |
| RF Front-End Redesign for 941-960 MHz | FCC Part 74 guard band operation preserves wireless channel density for large-venue touring deployments. |
| Strategic Partnership with Touring Rental Houses | Fleet-scale procurement agreements with Nashville and Los Angeles production hubs anchor volume offtake. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with live sound engineers, touring production managers, audiologist network operators, RF hardware procurement leads, and broadcast audio directors. FCC equipment authorization databases, METI technical standards documentation, Anatel certification registries, and ECHA REACH compliance filings provided regulatory trajectory inputs. Bottom-up driver shipment estimates and top-down touring revenue triangulation validated market sizing across the projection horizon.
Data-stream reconciliation combined unit economics modeling with procurement cycle analysis across wired, wireless, and noise-cancelling product architectures. Segmentation dimensions included connectivity protocol, driver configuration tier, end-user sophistication level, and regional regulatory cluster. CAGRs derived from replacement cadence modeling and installed base penetration curves, with specific inputs from concert production volume recovery trajectories and spectrum reallocation implementation schedules.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in RF spectrum allocation, disruptive driver technologies beyond balanced-armature and dynamic architectures, and macroeconomic shocks to live entertainment expenditure. Forecasts reflect documented assumptions regarding touring recovery velocity and Bluetooth LE Audio adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Wireless Earphone Market
Consumer Electronics
Waterproof Bathroom TV Market
Consumer Electronics
Silicone Sex Doll Market
Consumer Electronics
Advanced Baby Monitors Market
Consumer Electronics
Vape Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Headphones Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Notebook Market
Consumer Electronics
Android TV Box Market
Consumer Electronics
Middle East and Africa Smartphones Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
In-Ear-Monitors (Iems) Market