
 Keycap Market | 2026-2036
Keycap Market Size, Share, and Industry Trends Forecast 2026-2036
Keycap Market Insights
Premium double-shot and dye-sublimated PBT specifications is rotating the market upward as enthusiasts trade up from stock ABS sets. GMK Electronic Design leverages its German manufacturing heritage to sustain pricing power in the custom group-buy channel. Signature Plastics anchors North American supply with in-house injection molding for OEM and replacement segments. Tai-Hao Keycap Enterprise competes on volume through standardized colorways for mainstream mechanical keyboards.
A keycap is a removable plastic cover that mounts atop a mechanical keyboard switch stem, typically injection-molded from ABS or PBT thermoplastic with wall thicknesses of 1.0–1.5 mm and sculpted profiles such as Cherry, SA, or DSA to govern typing ergonomics and acoustics. Its commercial purpose centers on enabling user customization, extending switch longevity, and transmitting backlight through legends or transparent substrates. Artisan keycaps command the highest margin pools due to limited production runs and collector-driven resale markets, while OEM replacement sets retain volume leadership across enterprise and consumer refresh cycles. PBT material formulations are displacing ABS in premium tiers as thermal stability and resistance to shine attract durability-focused buyers.
China's SAMR enforces GB standards for plastic electronic accessories including phthalate content and flame-retardant thresholds, while the EU REACH regulation restricts SVHC substances in imported polymer goods sold to European consumers. The US Consumer Product Safety Commission monitors lead and cadmium levels in children's electronics peripherals, though most keycaps fall outside direct toy-safety mandates. Stakeholders must monitor how proliferating regional chemical-compliance frameworks reshape material sourcing and mold-injection partnerships across the supplier base.
Market Dynamics
Mechanical keyboard customization culture is compressing product lifecycles and fragmenting demand across artisan, premium, and volume tiers simultaneously. This enthusiast-driven velocity is forcing mold-injection suppliers to retool for shorter runs and higher SKU proliferation.
Growth Catalysts
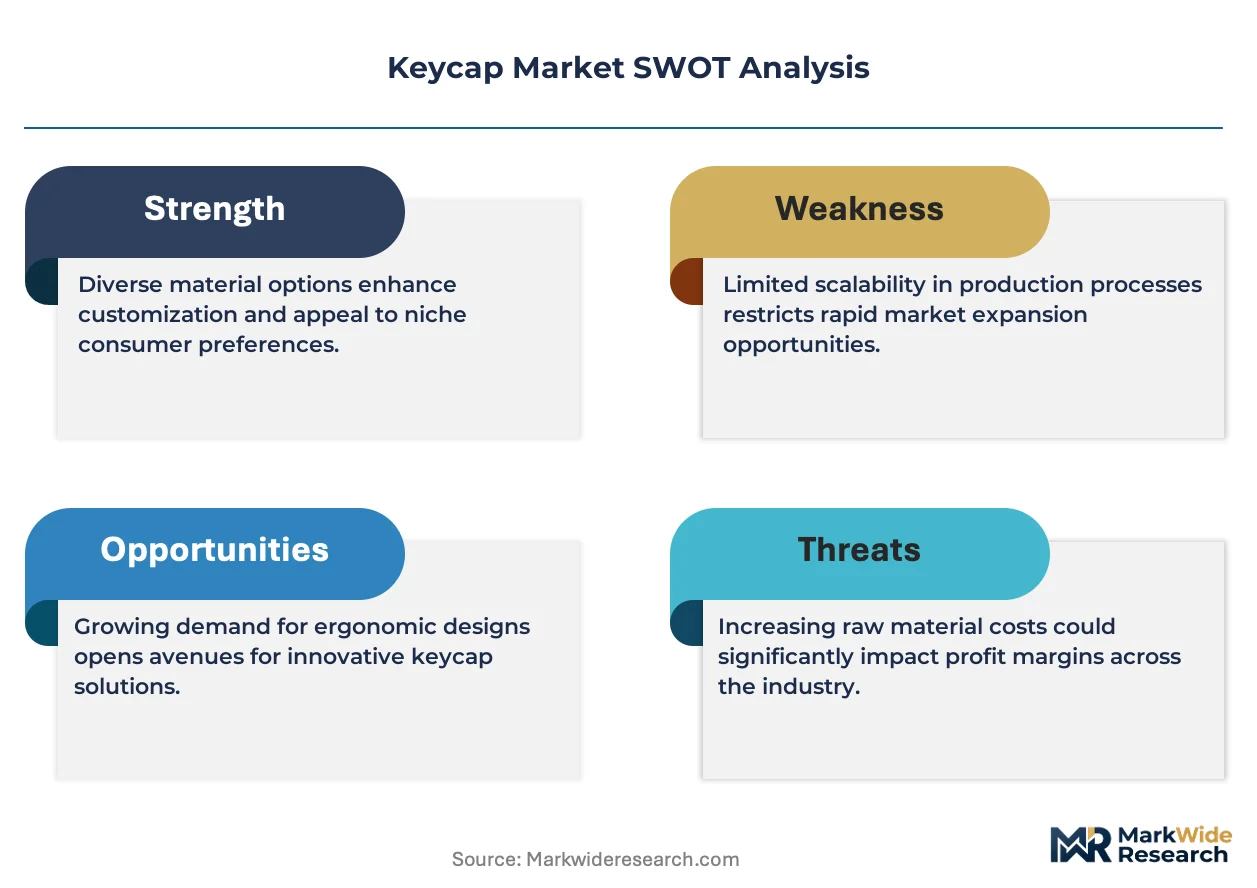
- REACH SVHC restrictions:European chemical compliance is accelerating PBT formulation investments as ABS alternatives face substance scrutiny at import.
- Content creator economy:Streaming professionals and esports athletes are normalizing visible peripheral customization, driving replacement-set velocity beyond enterprise refresh cycles.
- Injection molding precision gains:Multi-shot tooling advances are enabling complex legend geometries previously requiring secondary printing processes.
Market Restraints
- Acrylonitrile butadiene styrene (ABS) feedstock volatility:Petrochemical price swings compress margin predictability for volume-oriented manufacturers locked into ABS-dominant product lines.
- Guangdong mold-cluster concentration:Keycap tooling capacity concentrates in a single Chinese province, exposing supply continuity to regional logistics disruptions or power rationing.
- Dimensional tolerance stacking:Cross-manufacturer stem-fit variance creates compatibility friction that limits aftermarket mixing and increases return rates.
Strategic Opportunities
- India's nascent mechanical keyboard assembly:Local electronics manufacturing incentives under PLI schemes are creating captive demand for OEM-grade keycap supply without established domestic molding capacity.
- Biopolymer substrate development:Castor-oil-derived PBT alternatives align with EU Green Deal procurement preferences and open premium positioning for sustainability-certified product lines.
- Direct-to-consumer group-buy platforms:Crowdfunded production runs eliminate distributor margin extraction and enable pre-paid tooling amortization for artisan-grade designs.
Industry Challenges
- Master mold craftsmanship scarcity:Precision steel-cut mold fabrication requires skills concentrated among aging toolmakers in Taiwan and Japan, constraining capacity expansion for complex profile geometries.
- Dual-carbon compliance documentation:China's MEE enforcement of embodied carbon tracking for polymer electronics accessories is forcing supply-chain data infrastructure investments without standardized reporting protocols.
- Color-matching consistency across batches:Pigment dispersion variance between injection runs creates quality-control friction for group-buy organizers managing collector expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Keycap Market |
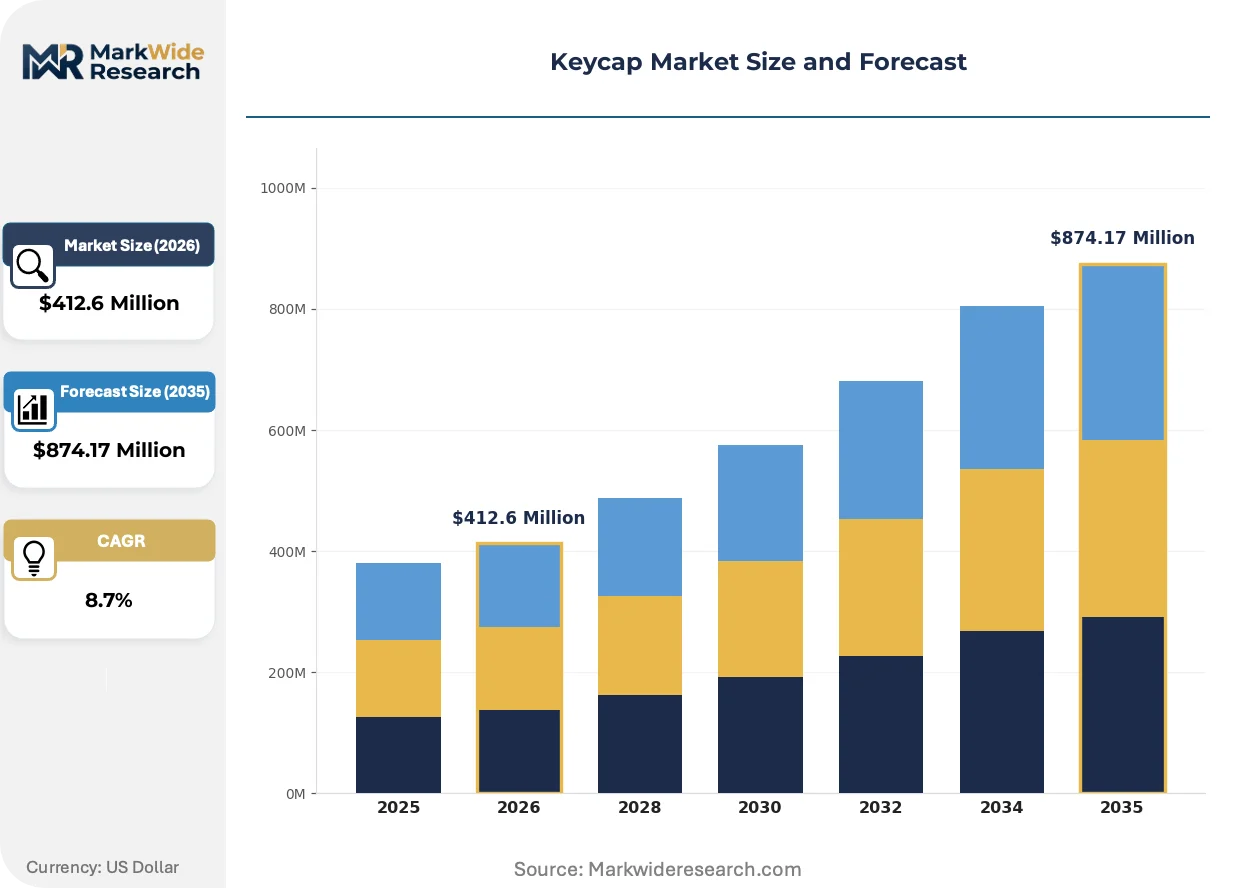
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Custom, OEM, Replacement, Artisan Material: ABS, PBT, PVC, Nylon Key Layout: ANSI, ISO, HHKB, QMK Backlight Compatibility: RGB, Single Color, Non-Transparent, Others |
| Companies Covered | Infinikey, Razer, GMK Electronic Design, Keychron, HyperX, Signature Plastics, Corsair Gaming, SteelSeries, Tai-Hao Keycap Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Keycap Market Trends and Innovations
Material science breakthroughs and regulatory chemistry constraints are converging to redefine manufacturing specifications across all price tiers. This technological pivot is compressing legacy ABS-dominant supply chains while elevating thermal-stability engineering.
Thick-walled PBT formulations with glass-fiber reinforcement are supplanting conventional ABS in enthusiast-grade keycap sets. Esports organizations and mechanical keyboard reviewers are prioritizing shine resistance and acoustic dampening in procurement specifications. This material transition is compressing pricing power for suppliers without PBT compounding capabilities or backward integration into polymer sourcing.
China's SAMR enforcement of GB standards for phthalate content and flame-retardant thresholds is restructuring supplier qualification requirements. Mold-injection partners must now document material composition through accredited testing laboratories before commercial shipment authorization. European importers are responding by consolidating procurement relationships with Chinese manufacturers holding pre-certified GB compliance dossiers.
Collector-driven resale markets for limited-run artisan keycaps are compressing primary-sale-to-secondary-flip intervals to under 48 hours. Discord-based community channels and dedicated aftermarket auction platforms are displacing traditional e-commerce discovery for rare designs. This velocity concentrates in the United States and Japan, where enthusiast density supports liquid secondary pricing.
Keycap Market Segmentation
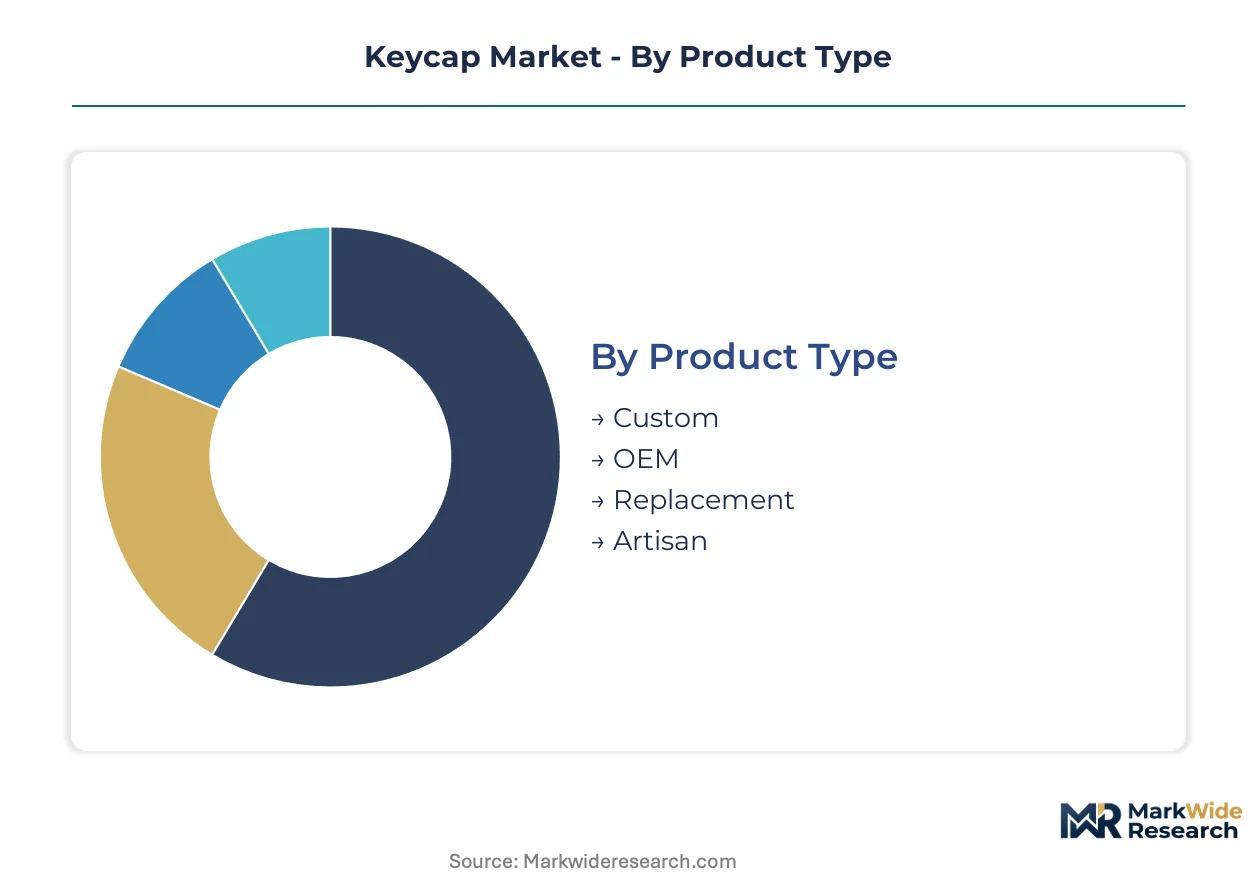
Keycap market segmentation reveals how enthusiast customization fragments demand across material science, regional layout standards, and collector-driven scarcity economics. Each category carries distinct margin profiles that reshape supplier capability investments and channel strategy.
Product Type:
Artisan and custom tiers command the widest margin spreads, while OEM and replacement segments anchor volume throughput for injection-molding operations.
- Custom:Crowdfunded group-buy production runs with pre-paid tooling amortization enable complex double-shot geometries and colorway experimentation. Demand concentrates in Germany and Japan where enthusiast density supports liquid secondary resale markets for limited designs.
- Artisan:Hand-sculpted or small-batch resin-cast designs trade at collector premiums with 48-hour primary-to-secondary flip intervals. United States buyers drive the steepest price escalation through Discord-based auction channels and dedicated aftermarket platforms.
- OEM:Factory-installed sets for pre-built mechanical keyboards compete on standardized colorways and compatibility certification.
- Replacement:Post-purchase refresh sets for worn stock keycaps target enterprise refresh cycles and durability-focused consumers.
The dominant share belongs to OEM, while Artisan is closing the gap fastest on margin contribution per unit.
Material:
Polymer selection determines thermal stability, acoustic properties, and regulatory compliance exposure across import jurisdictions.
- PBT:Glass-fiber-reinforced formulations with superior shine resistance and dye-sublimation compatibility are displacing ABS in premium tiers. Esports organizations in the United States now specify PBT in procurement contracts for extended tournament durability.
- ABS:Conventional acrylonitrile butadiene styrene dominates volume manufacturing but faces REACH SVHC scrutiny at European import. Petrochemical feedstock volatility compresses margin predictability for suppliers without backward integration into polymer sourcing.
- PVC:Lower-cost thermoplastic with limited thermal stability restricts application to entry-level replacement sets.
- Nylon:Emerging alternative for high-wear applications requiring enhanced mechanical strength and chemical resistance.
PBT holds the pricing power advantage, while Nylon is expanding most quickly in industrial peripheral applications.
Key Layout:
Regional typing standards and programmable firmware ecosystems fragment compatibility requirements across geographic markets.
- ANSI:United States standard layout with single-row Enter key dominates North American aftermarket demand and content creator customization.
- ISO:European configuration with split left Shift and vertical Enter key requires dedicated mold tooling for regional compliance.
- HHKB:Compact Happy Hacking Keyboard layout with Control key repositioning serves programmer and developer subsegments in Japan.
- QMK:Open-source firmware-compatible layouts enable programmable layer customization for power-user enthusiasts.
ANSI maintains volume leadership, while QMK is gaining share fastest among firmware-customization enthusiasts.
Backlight Compatibility:
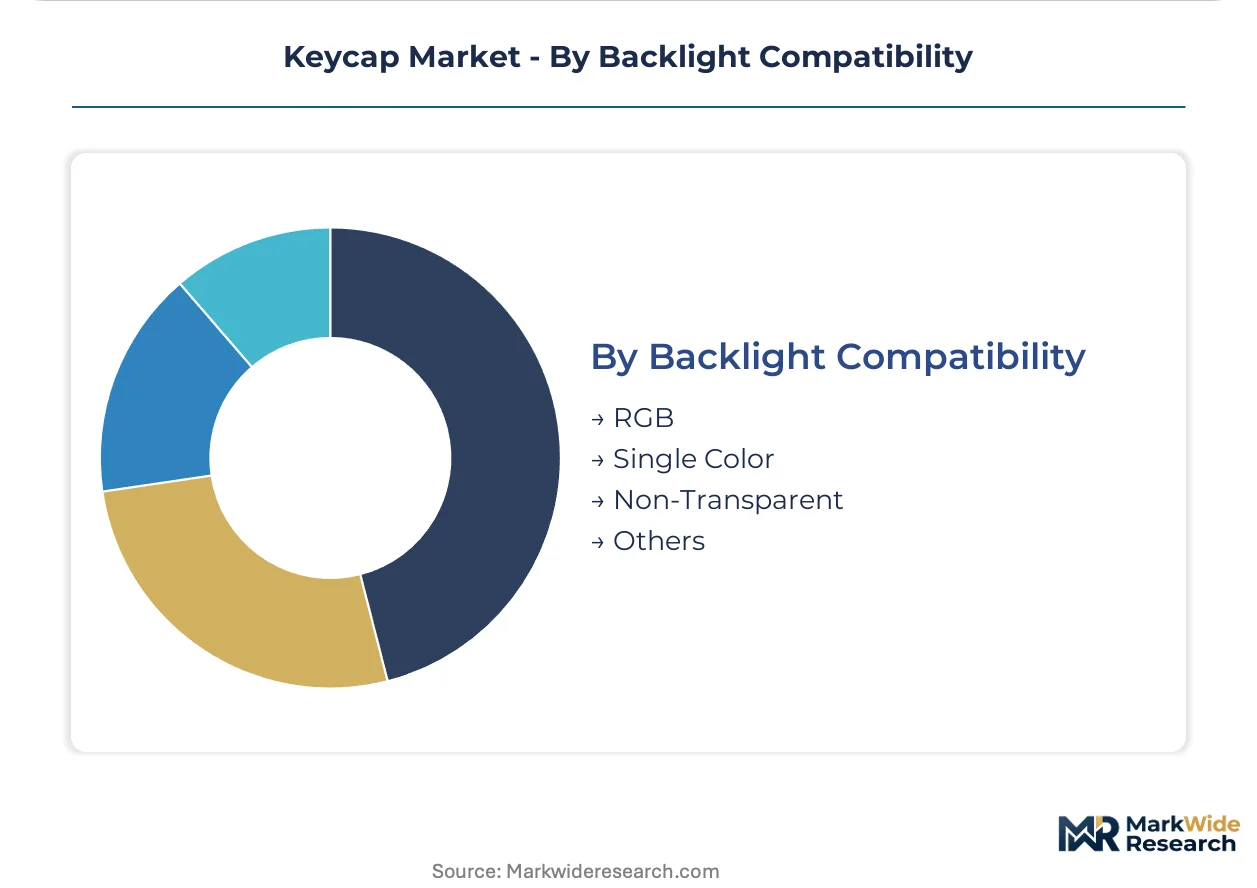
Illumination transmission properties determine legend manufacturing complexity and gaming peripheral positioning.
- RGB:Full-spectrum addressable backlighting demands translucent or doubleshot legend construction with precise light-pipe geometry. Gaming peripheral manufacturers in Taiwan specify RGB-compatible PBT for esports product lines.
- Single Color:Monochrome LED backlighting simplifies legend requirements while maintaining visibility enhancement for office environments.
- Non-Transparent:Opaque legends without illumination support prioritize dye-sublimation durability and acoustic dampening for typing-focused users.
- Others:Emerging electroluminescent and side-printed configurations for specialized industrial and medical input devices.
Non-Transparent commands the enthusiast purist segment, while RGB is climbing the fastest in gaming peripheral integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province hosts the densest concentration of mold-injection tooling capacity for keycap manufacturing, with Dongguan and Shenzhen clusters supplying OEM and aftermarket demand worldwide. This geographic concentration shapes regional procurement strategies and exposes supply continuity to localized disruptions.
United States
Content creator and esports professional adoption of visible peripheral customization drives replacement-set velocity beyond enterprise refresh cycles. The US Consumer Product Safety Commission monitors lead and cadmium thresholds in electronics peripherals, though most keycaps fall outside direct toy-safety mandates. California and Washington State host the densest enthusiast communities, with Discord-based auction channels concentrating aftermarket liquidity for artisan designs.
Germany
Enthusiast density in Berlin and Munich sustains liquid secondary resale markets for limited-run custom group-buy designs. ECHA REACH SVHC restrictions on acrylonitrile butadiene styrene formulations accelerate PBT procurement specifications among European distributors. GMK Electronic Design leverages its German manufacturing heritage to sustain pricing power in the premium custom channel.
China
SAMR enforcement of GB standards for phthalate content and flame-retardant thresholds restructures supplier qualification requirements for export-oriented molders. The dual-carbon policy under MEE mandates embodied carbon tracking for polymer electronics accessories, forcing supply-chain data infrastructure investments. Dongguan's mold cluster concentrates tooling expertise, though power rationing and logistics disruptions periodically constrain output.
Japan
Programmer and developer subsegments in Tokyo and Osaka sustain demand for compact HHKB-layout configurations with repositioned Control keys. METI oversight of JIS standards for electronic product safety shapes material composition requirements for domestic distribution. Collector-driven resale velocity for artisan keycaps matches United States intensity, with dedicated aftermarket platforms serving enthusiast density in metropolitan corridors.
India
PLI scheme incentives for local electronics manufacturing create captive demand for OEM-grade keycap supply without established domestic molding capacity. BIS certification requirements for imported polymer accessories reshape procurement relationships with Chinese suppliers holding pre-certified compliance dossiers. Karnataka and Tamil Nadu emerging as assembly hubs for mechanical keyboards drive component import dependency.
Keycap Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the keycap market. The vendor base stratifies into three tiers: German and American specialists commanding premium positioning through manufacturing heritage, Taiwanese and Chinese volume producers competing on standardized colorways, and gaming peripheral integrators bundling keycaps with complete keyboard systems. Strategic differentiation concentrates on mold-injection precision capabilities, material formulation backward integration, and direct-to-consumer group-buy platform control.
Within the heritage-specialist tier, GMK Electronic Design and Signature Plastics exemplify manufacturing-origin positioning, with the former representing German custom-channel heritage and the latter anchoring North American in-house injection molding. Tai-Hao Keycap Enterprise occupies the volume-competitive position, competing through standardized colorways for mainstream mechanical keyboard adoption. Razer and Corsair Gaming sit within the integrated-peripheral archetype, bundling keycap sets with complete gaming keyboard systems rather than pursuing standalone aftermarket positioning.
| Leading Market Players |
|---|
| Infinikey |
| Razer |
| GMK Electronic Design |
| Keychron |
| HyperX |
| Signature Plastics |
| Corsair Gaming |
| SteelSeries |
| Tai-Hao Keycap Enterprise |
| Others |
Pricing and Supply Chain Analysis
China's SAMR enforcement of GB standards for phthalate content and flame-retardant thresholds simultaneously gates supplier qualification and stratifies price tiers across import markets. Compliance documentation costs compress margins for uncertified molders while elevating pricing power for pre-certified Guangdong clusters serving European and North American distributors.
Pricing Analysis
REACH SVHC restrictions dictate the pricing tier structure across European import channels, separating GB-certified PBT formulations from ABS alternatives facing substance scrutiny. Three-tier pricing structure across premium, standard, and economy levels reflects material grade, backlight compatibility complexity, and legend manufacturing precision. Cost compression in volume ABS segments is intensifying because petrochemical feedstock volatility erodes margin predictability for suppliers without backward integration into polymer sourcing. Enterprise procurement teams exhibit highest price sensitivity, while artisan collectors demonstrate lowest sensitivity due to scarcity-driven resale velocity.
Supply Chain Analysis
Dongguan mold-cluster concentration anchors global tooling capacity, with Shenzhen logistics corridors feeding downstream distribution networks. Raw material flows draw from Saudi Arabian petrochemical feedstocks for ABS formulations, German polymer compounding for PBT substrates, and Japanese master mold steel for precision tooling. Single-source vulnerability concentrates in Guangdong Province, where power rationing or regional logistics disruptions constrain output continuity. Distribution runs through direct-to-consumer group-buy platforms for artisan tiers, OEM keyboard integrators for factory-installed sets, and specialized peripheral retailers for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The keycap market functions as a service-attach opportunity where aftermarket customization velocity and collector-driven resale platform fees expand faster than hardware unit economics. Group-buy organizer services, authentication/grading for secondary markets, and bespoke colorway consulting represent recurring-revenue layers outpacing injection-molding margins.
For Market Incumbents: Consolidate mold-injection precision capabilities through acquisition of Taiwanese master toolcraft specialists facing generational succession pressure. Lock in GB-compliant polymer sourcing partnerships before REACH SVHC list expansion accelerates material substitution costs. Channel control through proprietary group-buy platforms defends margin position against crowdfunding intermediaries extracting platform fees.
For New Entrants and Emerging Players: Differentiate on biopolymer substrate development, positioning castor-oil-derived PBT alternatives for EU Green Deal procurement preferences. India's PLI scheme incentives for mechanical keyboard assembly represent the most penetrable geography, with captive OEM-grade demand and absent domestic molding capacity. Direct-to-consumer group-buy platforms enable pre-paid tooling amortization without distributor margin extraction.
For Investors and Strategic Acquirers: China's dual-carbon policy enforcement under MEE reshapes the acquisition landscape, favoring targets with supply-chain data infrastructure for embodied carbon tracking. Five-to-ten-year viability hinges on material formulation backward integration and mold-injection precision capabilities rather than brand equity alone. Signal to monitor: GB standards expansion beyond phthalates into broader polymer additive restrictions, which would accelerate consolidation among pre-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Substrate Development | Castor-oil-derived PBT alternatives align with EU Green Deal procurement preferences for sustainability-certified product lines. |
| Direct-to-Consumer Group-Build Platform | Crowdfunded production runs eliminate distributor margin extraction and enable pre-paid tooling amortization for artisan designs. |
| Master Mold Craftsmanship Acquisition | Precision steel-cut mold fabrication skills concentrated among aging Taiwanese toolmakers constrain capacity expansion for complex geometries. |
| GB Compliance Dossier Investment | Pre-certified material composition documentation accelerates European importer procurement consolidation toward qualified Chinese manufacturers. |
| India PLI Scheme Localization | Karnataka and Tamil Nadu assembly hubs for mechanical keyboards drive component import dependency without domestic molding capacity. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from peripheral manufacturers, and enthusiast community transaction records across Discord-based auction channels. Primary interviews engaged mold-injection plant managers in Guangdong, procurement leads at gaming peripheral OEMs, group-buy organizers managing collector expectations, and aftermarket platform operators in the United States and Japan. Bottom-up unit economics from injection-molding operations triangulate against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include material formulation tier, product type across artisan through OEM, backlight compatibility configuration, and regional layout standard across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating esports professional adoption rates and content creator replacement velocity. Industry-specific forecast inputs capture REACH SVHC restriction timelines and China's dual-carbon policy enforcement intensity.
Material uncertainties — regulatory list expansion for restricted substances, petrochemical price volatility, and master mold craftsman retirement waves — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained enthusiast customization culture and stable cross-manufacturer stem-fit tolerances. Revision becomes warranted when GB standards enforcement intensity or REACH SVHC list expansion crosses thresholds triggering accelerated material substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Apple Accessories Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
In-Ear-Monitors (Iems) Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Phone Tripod Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Ereader Market
Consumer Electronics
Bluetooth Speakers Market