
 Gaming PC Market | 2026-2036
Gaming PC Market Size, Share, and Industry Trends Forecast 2026-2036
Gaming PC Market Analytics
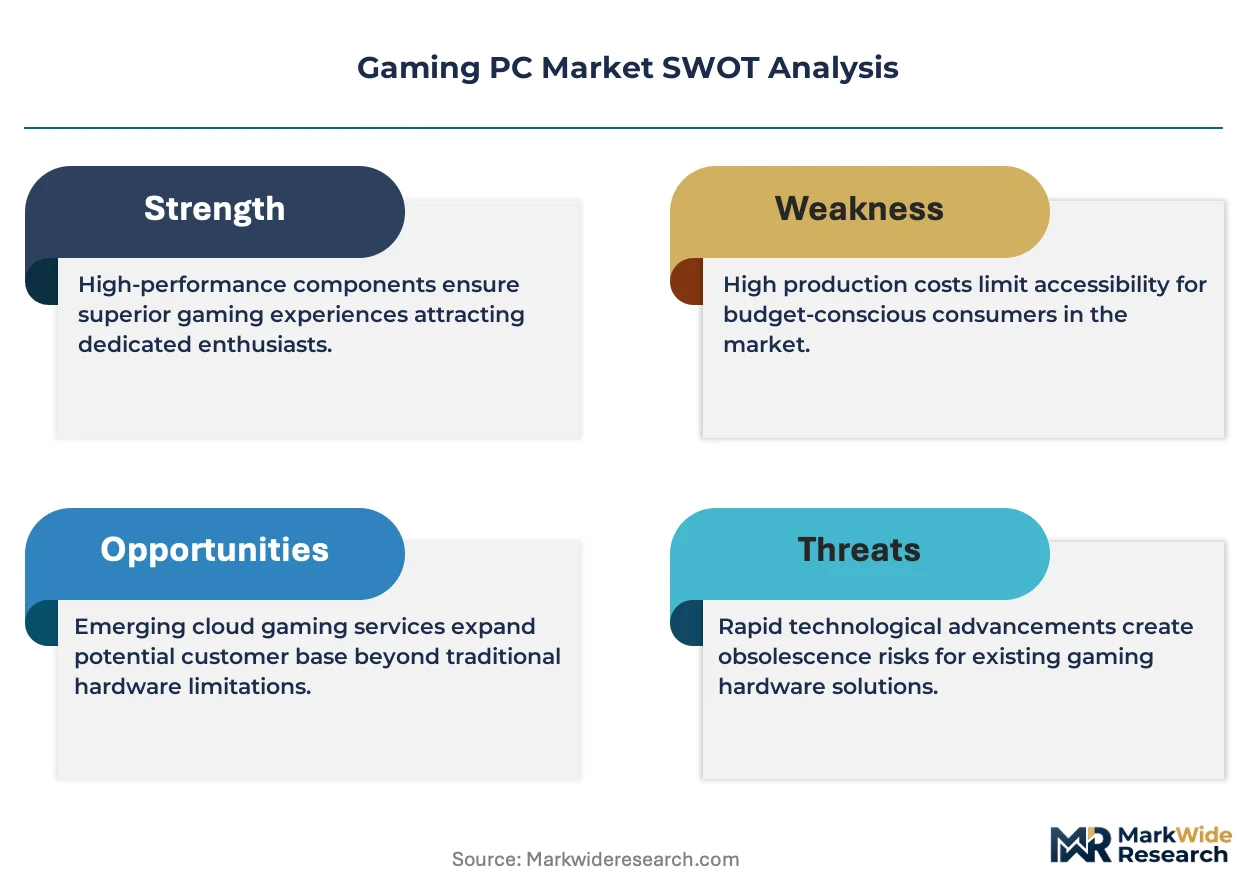
Aluminum chassis construction is restructuring thermal management economics across premium Gaming PC lines. ASUS leverages in-house motherboard foundries to sustain component cost advantages in high-performance segments. MSI anchors its position through graphics card specialization and deep OEM partnerships in East Asian assembly networks. Corsair Gaming differentiates via vertical control over memory and cooling subsystems, reducing reliance on third-party suppliers.
A Gaming PC comprises a microcomputer system engineered for real-time rendering workloads, typically integrating discrete GPUs with thermal design power exceeding 150W and DDR5 memory architectures exceeding 4800 MT/s. Gaming laptops capture the fastest expansion as mobile RTX-class GPUs narrow the performance gap with desktop equivalents, while entry-level desktops face margin compression from console substitution. High-end custom builds concentrate profit pools where extreme performance tiers command premium pricing from streamers and content creators. Ray tracing and DLSS graphics technologies are displacing rasterization-only configurations as baseline expectations across mid-range and above segments.
The EPA Energy Star program and EU Ecodesign regulations enforce standby power limits and efficiency labeling that constrain PSU design choices for systems sold in North America and Europe. China's GB standards for electronic product safety and NMPA-related electromagnetic compatibility certification govern market access for domestic and imported Gaming PC assemblies. Stakeholders must monitor how semiconductor licensing regimes and carbon border adjustments reshape component sourcing strategies and final assembly location decisions.
Market Dynamics
Ray tracing and DLSS graphics technologies are compressing upgrade cycles across mid-range Gaming PC segments as rasterization-only configurations lose buyer relevance.
Growth Catalysts
- Esports institutionalization:Professional leagues and university programs in South Korea and the United States are mandating high-refresh-rate systems for competitive play.
- China's internet café infrastructure:Domestic operators are refreshing hardware fleets to meet GB standards for electronic product safety and electromagnetic compatibility certification.
- Content creator workflows:Streamers on Twitch and YouTube are driving demand for extreme performance tiers capable of simultaneous gameplay capture and real-time encoding.
Market Restraints
- Semiconductor export controls:Bureau of Industry and Security licensing regimes are constraining GPU and advanced logic chip availability for manufacturers serving Chinese assembly networks.
- DDR5 memory cost volatility:Premium pricing for high-speed modules above 4800 MT/s is compressing margins on entry-level builds.
- Console substitution threat:PlayStation and Xbox platforms at sub-$500 price points are capturing casual gamers who previously represented desktop volume.
Strategic Opportunities
- India's underpenetrated enthusiast base:BIS certification pathways and PLI scheme incentives for electronics manufacturing are lowering barriers for localized assembly operations.
- Cloud gaming convergence:Hybrid architectures combining local rendering with edge compute streaming are opening mid-tier hardware configurations previously considered obsolete.
- EU Ecodesign regulatory tailwind:Efficiency labeling mandates for standby power are creating differentiation opportunities for PSU manufacturers with 80 Plus Titanium certification.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design and vapor chamber optimization require specialized expertise concentrated among East Asian OEM engineering teams.
- Carbon border adjustment complexity:Assembly location decisions are being forced by emerging EU carbon border mechanisms affecting aluminum chassis sourcing from Chinese foundries.
- IP licensing fragmentation:Patent thickets around PCIe 5.0 signal integrity and DDR5 controller implementations are extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaming PC Market |
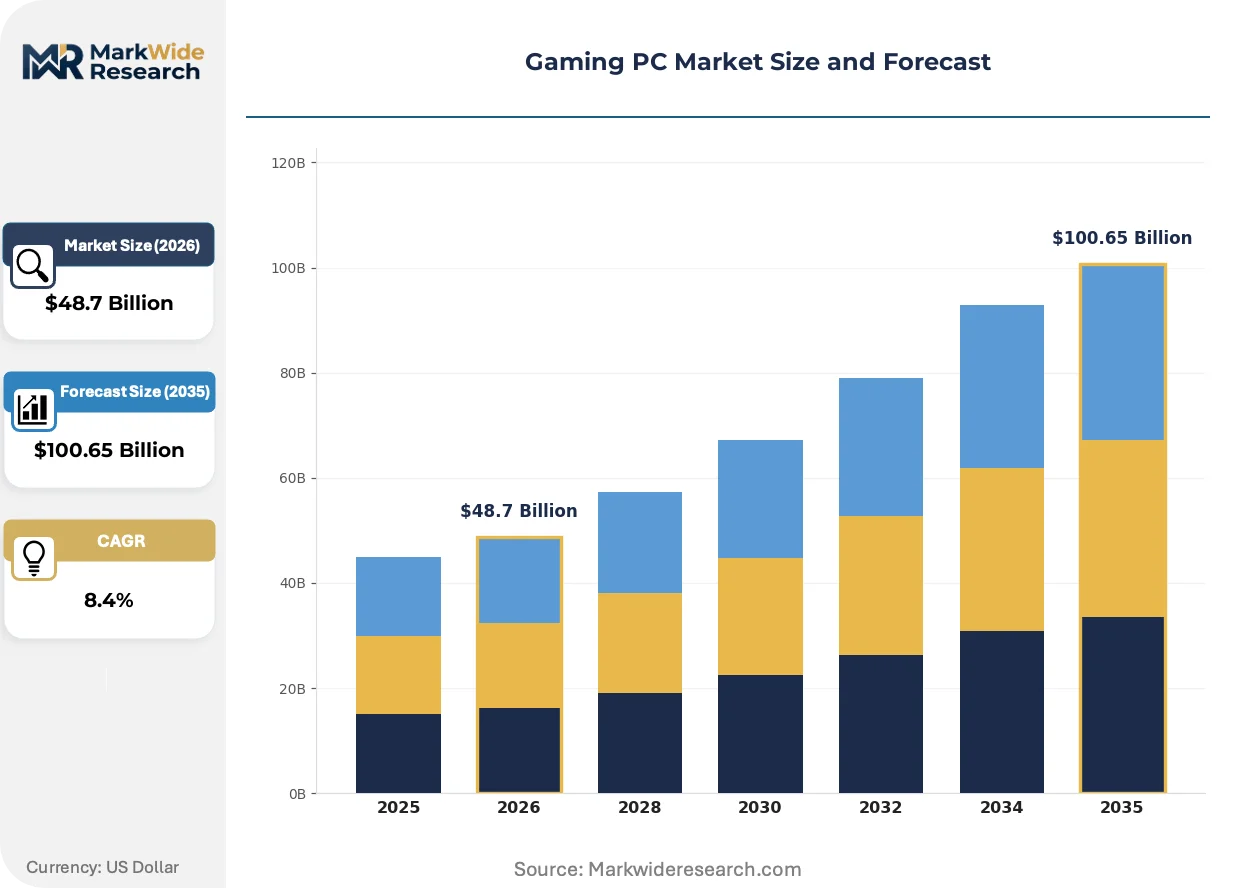
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gaming Desktops, Gaming Laptops, Custom Builds, All-in-One PCs Performance Level: Entry-Level, Mid-Range, High-End, Extreme End User: Casual Gamers, Professional Gamers, Esports Teams, Streamers Graphics Technology: Integrated Graphics, Dedicated Graphics, Ray Tracing, DLSS |
| Companies Covered | Dell Technologies (Alienware), ASUS, MSI, HP (OMEN), Lenovo (Legion), Acer (Predator), Corsair Gaming, Razer, CyberPowerPC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaming PC Market Evolving Landscape
Graphics rendering architectures and thermal management systems are undergoing simultaneous reinvention as power densities exceed 300W on flagship GPUs.
AI-driven frame generation is rewriting performance expectations for real-time rendering workloads. Competitive players and streamers are adopting DLSS 3 and FSR 3 configurations within eighteen months of release. The technology is compressing the performance gap between mid-range and flagship GPU tiers.
EPA Energy Star standby power limits are forcing PSU redesigns across North American product lines. Efficiency thresholds now exclude older topologies from certified configurations. System integrators are responding by consolidating supplier relationships with 80 Plus Platinum and Titanium vendors.
Direct-to-consumer configuration tools are displacing traditional retail channel dominance for enthusiast builds. Boutique assemblers in the United States and Germany are capturing margin through bespoke thermal and aesthetic customization. This pattern is most visible among content creators prioritizing component transparency and upgrade path guarantees.
Gaming PC Market Segmentation
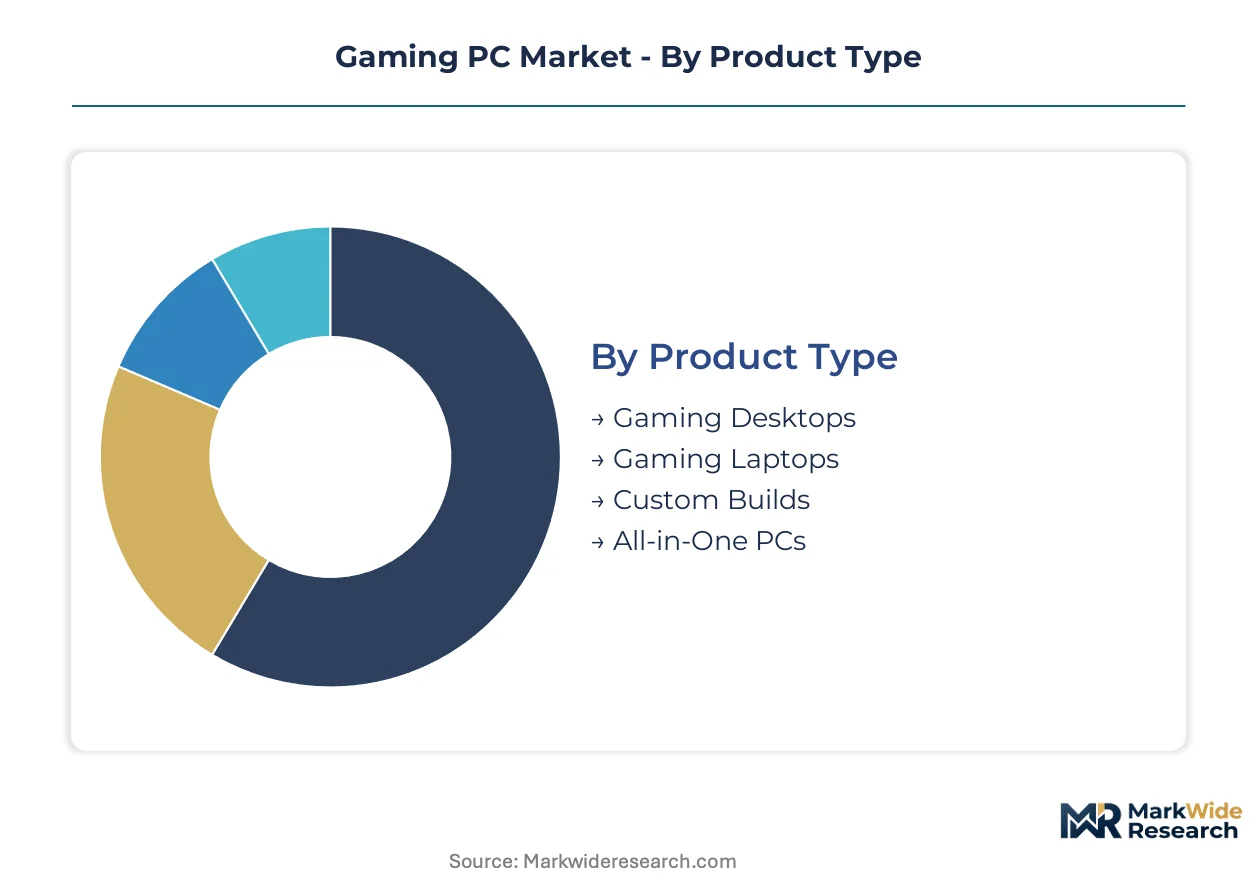
Gaming PC segmentation reveals divergent buyer priorities across hardware form factors, performance tiers, and rendering technologies. Component sourcing constraints and thermal design requirements reshape how manufacturers align product portfolios with distinct user workflows and regional certification standards.
Product Type:
Form factor selection separates buyers prioritizing thermal headroom from those demanding mobility and space efficiency.
- Gaming Desktops:Tower configurations accommodate discrete GPUs exceeding 300W thermal design power and liquid cooling loops. Demand concentrates among esports training facilities in South Korea and content creator studios in Germany, where upgrade path flexibility outweighs portability requirements.
- Gaming Laptops:Mobile RTX-class architectures now deliver frame rates within 15-20% of desktop equivalents at 1080p and 1440p resolutions. China's university esports programs and India's underpenetrated enthusiast base are driving procurement volumes as these systems bypass desktop space constraints.
- Custom Builds:Boutique assemblers in the United States and Germany capture margin through component transparency and aesthetic personalization. Bespoke thermal configurations appeal to streamers requiring simultaneous gameplay capture and encoding workloads.
- All-in-One PCs:Integrated display and system designs sacrifice GPU thermal limits for space efficiency in residential and hospitality deployments.
Gaming desktops lead volumes today; gaming laptops are gaining share fastest.
Performance Level:
Price-to-performance thresholds segment buyers by rendering workload intensity and upgrade cycle tolerance.
- Entry-Level:Systems targeting 1080p60 gameplay with previous-generation discrete GPUs or advanced integrated graphics. Console substitution pressure from sub-$500 PlayStation and Xbox platforms compresses margins and volumes in North American and European casual gaming segments.
- Mid-Range:Configurations balancing 1440p high-refresh-rate capability with DLSS and FSR frame generation technologies. China's internet café refresh cycles and India's PLI-incentivized local assembly operations concentrate demand as operators seek GB standards compliance without flagship pricing.
- High-End:4K-capable systems with current-generation GPUs and DDR5-5600+ memory architectures. Streamers on Twitch and YouTube prioritize these tiers for simultaneous gameplay and real-time encoding workflows.
- Extreme:Custom liquid-cooled builds with flagship GPUs exceeding 450W thermal design power. Professional esports teams and content creators command premium pricing for marginal frame rate advantages.
Mid-range configurations anchor volume today; extreme tiers command the steepest expansion trajectory in revenue terms.
End User:
Usage intensity and institutional purchasing power separate individual buyers from organization-backed procurement.
- Casual Gamers:Price-sensitive individuals prioritizing 1080p gameplay without ray tracing or frame generation features. Mobile and console substitution erodes this segment's desktop relevance in Western markets.
- Professional Gamers:Individuals deriving primary income from tournament winnings and sponsorship contracts. South Korean and United States-based competitors mandate high-refresh-rate displays and sub-10ms system latency.
- Esports Teams:Organization-backed purchases for training facilities and competition venues. Institutional procurement in China, South Korea, and Germany emphasizes standardized hardware configurations and vendor support contracts.
- Streamers:Content creators requiring simultaneous gameplay, face capture, and real-time encoding without frame drops. Dual-PC setups or extreme-tier single systems dominate this workflow-driven segment.
Casual gamers still represent the broadest installed base; streamers and esports teams are expanding most quickly as institutional legitimacy deepens.
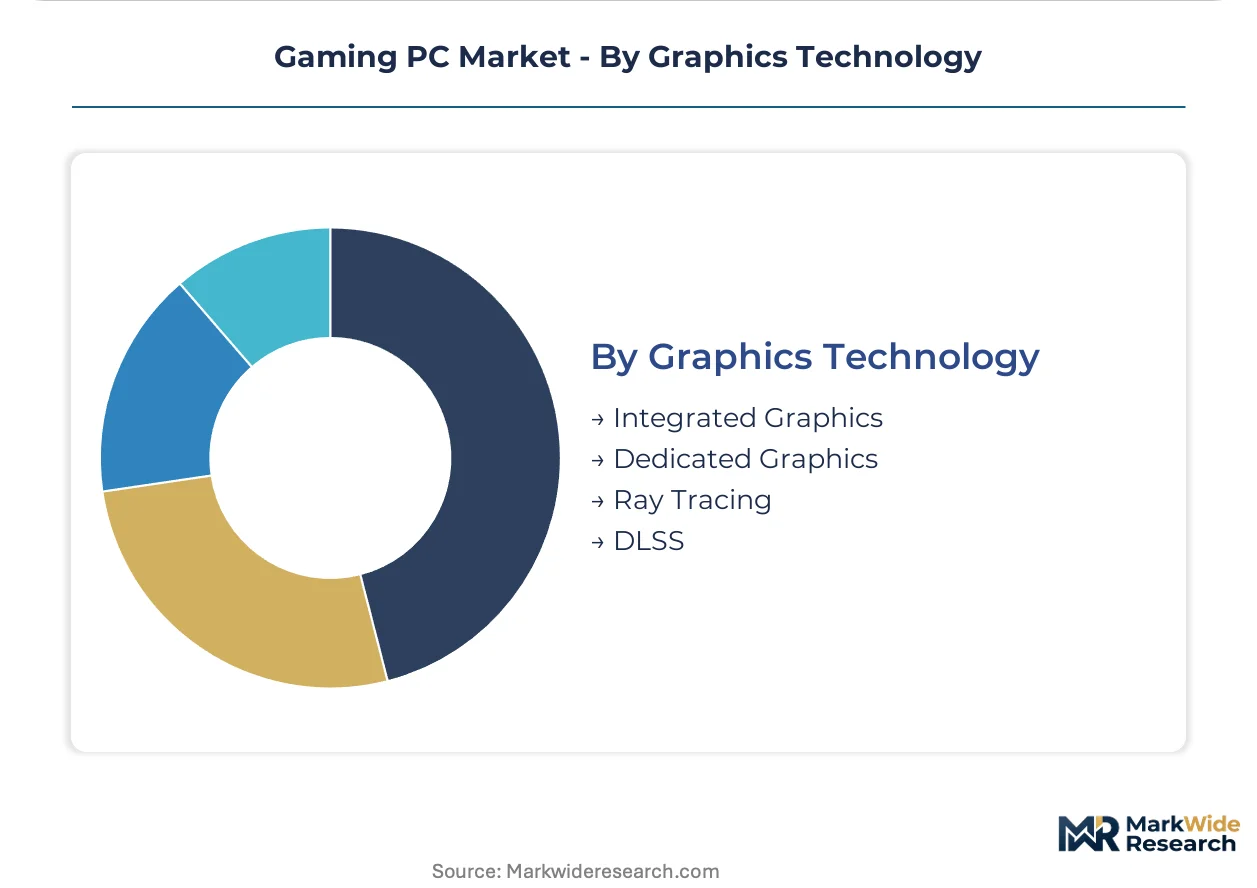
Graphics Technology:
Rendering pipeline capabilities now function as baseline purchase criteria rather than premium differentiators.
- Integrated Graphics:AMD RDNA and Intel Arc architectures now enable 1080p60 gameplay in thin-and-light form factors previously requiring discrete GPUs. Entry-level laptop volumes in India and Southeast Asia leverage these advances.
- Dedicated Graphics:Discrete GPU configurations remain mandatory for ray tracing and high-refresh-rate 1440p+ gameplay. NVIDIA and AMD supply constraints from Bureau of Industry and Security licensing regimes affect availability in Chinese assembly networks.
- Ray Tracing:Real-time lighting simulation has displaced rasterization-only configurations as baseline expectations above entry tier. DLSS 3 and FSR 3 adoption within eighteen months of release compresses upgrade cycles.
- DLSS:AI-driven frame generation rewrites performance expectations for real-time rendering workloads. Competitive players prioritize these configurations for marginal latency and visual clarity advantages.
Dedicated graphics configurations lead volumes today; DLSS-enabled systems are climbing the fastest as frame generation becomes standard above mid-range tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan-Shenzhen electronics corridor anchors global Gaming PC assembly capacity, with component sourcing networks extending through Kaohsiung and Penang. National regulations and industrial policy frameworks reshape how manufacturers configure regional supply chains and certification pathways.
United States
Esports institutionalization at universities and professional training facilities drives procurement of high-refresh-rate systems. EPA Energy Star standby power limits constrain PSU design choices for systems sold domestically. Austin and Seattle tech corridors host boutique assemblers capturing margin through direct-to-consumer configuration tools.
Germany
Content creator studios and streaming operations concentrate demand for extreme performance tiers capable of simultaneous encoding. EU Ecodesign regulations enforce efficiency labeling mandates that differentiate 80 Plus Titanium certified configurations. Berlin and Munich clusters sustain specialized thermal engineering expertise for liquid-cooled custom builds.
China
Internet café infrastructure refresh cycles and domestic brand expansion sustain volume leadership despite semiconductor export constraints. GB standards for electronic product safety and NMPA-related electromagnetic compatibility certification govern market access. Guangdong and Jiangsu provinces concentrate motherboard and graphics card foundry operations.
South Korea
Professional esports leagues mandate standardized hardware configurations for competitive play. MFDS-equivalent product safety frameworks align with international electromagnetic compatibility standards. Seoul Capital Area training facilities anchor institutional procurement volumes for extreme-tier systems.
India
Underpenetrated enthusiast bases and university esports program expansion drive mid-range laptop volumes. BIS certification pathways and PLI scheme incentives for electronics manufacturing lower barriers for localized assembly. Karnataka and Maharashtra industrial corridors attract component distributors serving domestic integrators.
Gaming PC Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from core component specializations into full system integration. The vendor base organizes around three tiers: diversified technology conglomerates with captive gaming divisions, component specialists leveraging vertical control over memory or cooling subsystems, and boutique assemblers commanding premium through aesthetic customization. Strategic archetypes include foundry-integrated manufacturers sustaining cost advantages, thermal engineering specialists monetizing vapor chamber expertise, and direct-to-consumer configurators capturing margin transparency. M&A activity and strategic partnerships reshape competitive positioning as firms secure DDR5 controller implementations and PCIe 5.0 signal integrity capabilities.
Within the diversified technology tier, Dell Technologies and HP occupy positions spanning enterprise infrastructure through enthusiast gaming sub-brands. ASUS and MSI exemplify foundry-integrated specialists with in-house motherboard production capabilities. Corsair Gaming anchors the component-specialist vector through captive supply of memory and cooling subsystems. These archetypes illustrate how competitive advantage derives from supply chain configuration rather than assembly scale alone.
| Leading Market Players |
|---|
| Dell Technologies (Alienware) |
| ASUS |
| MSI |
| HP (OMEN) |
| Lenovo (Legion) |
| Acer (Predator) |
| Corsair Gaming |
| Razer |
| CyberPowerPC |
| Others |
Value Network & Pricing Analysis
Esports team procurement concentration anchors premium-tier pricing power, while internet café operators in China drive volume-based standardization across mid-range configurations. This buyer duality creates divergent margin structures where institutional contracts sustain flagship premiums and fleet refresh cycles compress entry-level yields.
Pricing Analysis
DDR5 memory module costs pass through directly to system integrators, forcing margin compression on builds below mid-range tiers. Pricing stratifies across extreme, high-end, mid-range, and entry levels based on GPU thermal design power thresholds and memory speed certification. Cost pressure intensifies from console substitution at the low end, where PlayStation and Xbox platforms capture price-sensitive casual gamers. Internet café operators exhibit highest price sensitivity due to fleet-scale procurement, while content creators show lowest sensitivity when encoding performance guarantees are bundled.
Supply Chain Analysis
GPU foundry output rests on Taiwan Semiconductor Manufacturing capacity and Samsung Electronics wafer starts in South Korea. Graphics card assembly draws from Chinese surface-mount operations, Malaysian back-end facilities, and Vietnamese chassis fabrication. Bureau of Industry and Security licensing restrictions create single-source vulnerability for advanced logic chips bound for Chinese integrators. Distribution runs through Dongguan-Shenzhen electronics corridor consolidation hubs before regional fragmentation to North American and European system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gaming PC market functions as a stable compounder, with esports institutionalization providing recurring replacement demand from training facilities and league-standardized hardware mandates.
For Market Incumbents: Deploy thermal engineering specialization as a defensive moat. Capture vapor chamber and liquid cooling talent concentrated in East Asian OEM teams before competitors consolidate this scarce capability. Deepen backward integration into DDR5 controller implementations and PCIe 5.0 signal integrity IP to extend product development timelines that deter mid-tier challengers. Counter the console substitution threat by bundling upgrade path guarantees and component transparency for streamer segments. For New Entrants and Emerging Players: Begin with India's underpenetrated enthusiast base, where BIS certification pathways and PLI scheme incentives lower barriers for localized assembly operations. Target university esports programs in Karnataka and Maharashtra industrial corridors seeking mid-range laptop volumes with domestic support contracts. Establish direct-to-consumer configuration tools that bypass traditional retail channel dominance, mirroring boutique assemblers in Austin and Seattle. For Investors and Strategic Acquirers: Component specialists with captive cooling and memory subsystem control are the most active acquirer targets in this space, as diversified technology conglomerates seek vertical fill-ins. Frame long-term viability around 5-10 year replacement cycles driven by ray tracing and AI frame generation adoption curves. Monitor Bureau of Industry and Security licensing regime adjustments as the critical inflection signal for Chinese assembly network viability and component availability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Foundry Partnership | Secures wafer allocation from TSMC or Samsung for flagship RTX-class architectures. |
| Thermal Engineering Acquisition | Captures vapor chamber design talent concentrated among East Asian OEM teams. |
| Direct-to-Consumer Platform Launch | Bypasses retail channel margin extraction through bespoke configuration tools. |
| India PLI Scheme Localization | Leverages BIS certification and Maharashtra industrial corridor incentives for assembly. |
| 80 Plus Titanium PSU Certification | Differentiates configurations under EPA Energy Star and EU Ecodesign efficiency mandates. |
Research Methodology
Direct dialogue with system integrator procurement directors, esports team facility managers, semiconductor distributor sales leads, and thermal engineering OEM specialists grounded the qualitative foundation. Secondary validation drew from Bureau of Industry and Security export control filings, EPA Energy Star certified product databases, EU Ecodesign regulatory notices, and customs records through Dongguan-Shenzhen corridor trade flows. Bottom-up build from component bill-of-materials and top-down triangulation from end-user procurement surveys converged on segment-level estimates.
Unit shipment and revenue outputs reflect cross-validation between supply-side capacity modeling and demand-side replacement cycle analysis across the projection horizon. Segmentation dimensions span form factor, performance tier, graphics technology adoption, and end-user archetype. CAGRs derived from logistic diffusion curves fitted to ray tracing and DLSS penetration patterns, with GPU thermal design power trajectories and DDR5 speed bin transitions as key forecast inputs.
Several conditions sit outside the modeled scope, including Bureau of Industry and Security licensing regime expansion, carbon border adjustment implementation timelines, and emergent cloud gaming substitution thresholds. Forecasts assume continued esports institutionalization and internet café refresh compliance with GB standards. Material deviation in semiconductor export control enforcement or EU carbon border mechanism activation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Smartphone Screen Protector Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Wrist Watch Market
Consumer Electronics
Japan Gaming Peripherals Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
Phone Headsets Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Smartphone Console Market
Consumer Electronics
Global Smart Outdoor TV Market
Consumer Electronics
Stress Ball Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Vape Market