
 US Solar E-Bike Market | 2026-2036
US Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar E-Bike Market Insights
The Inflation Reduction Act's clean vehicle tax credits is shifting procurement economics toward solar-assisted electric mobility in the United States. Rad Power Bikes leverages direct-to-consumer channels to sustain price accessibility for urban commuters. Trek Bicycle Corporation anchors premium positioning through dealer network density and component quality. Lectric eBikes specializes in value-engineered folding platforms that occupy the entry-level fleet segment.
A solar e-bike integrates photovoltaic cells into frame surfaces or detachable panels to supplement lithium-ion battery charge cycles, typically adding 15-25 miles of auxiliary range per day of sun exposure. Its primary commercial purpose lies in reducing grid dependency for last-mile delivery and commuter fleets operating in high-insolation zones. Commuter e-bikes lead volume distribution where daily mileage predictability justifies solar panel cost recovery. Folding e-bikes represent the fastest-growing structural category as apartment-dwelling urbanites prioritize storage efficiency. Smart connectivity technology concentrates margin pools through subscription-enabled fleet management and theft recovery services.
The Consumer Product Safety Commission governs electrical system safety standards while the Federal Highway Administration shapes bike lane infrastructure eligibility that affects commercial fleet routing. California Air Resources Board zero-emission vehicle incentives stack with federal IRA credits to compress payback periods for solar e-bike adopters. State-level building codes and utility interconnection rules in sunbelt jurisdictions will determine whether workplace solar charging becomes a standard employee benefit or remains a niche amenity.
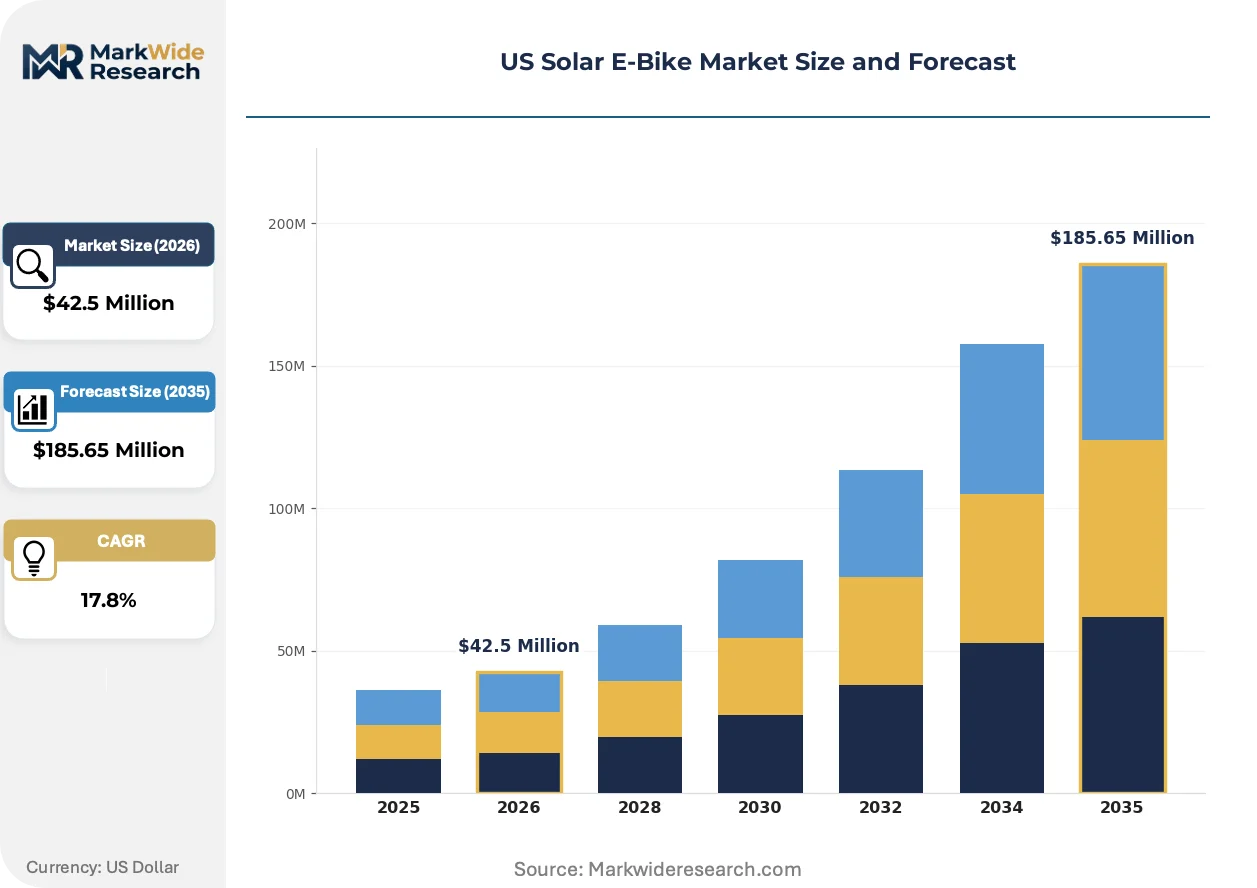
Market Dynamics
The US solar e-bike market is experiencing a structural acceleration driven by the Inflation Reduction Act's clean vehicle tax credits, which are compressing payback periods and redirecting fleet procurement budgets toward photovoltaic-assisted mobility platforms.
Growth Catalysts
- IRA Clean Vehicle Credits:The Inflation Reduction Act's federal tax incentives stack with California Air Resources Board zero-emission vehicle programs to reduce acquisition costs for commercial fleet operators.
- Last-Mile Delivery Electrification:Urban logistics networks in high-insolation metropolitan corridors are replacing combustion van fleets with solar-assisted cargo bikes to circumvent congestion pricing and access restrictions.
- Perovskite Cell Efficiency Gains:Emerging photovoltaic materials are increasing daily auxiliary range contributions from frame-integrated panels, extending operational radius for commuter and courier applications.
Market Restraints
- Lithium Price Volatility:Battery pack input costs remain exposed to upstream mining concentration and processing bottlenecks, compressing margin structures for value-engineered product tiers.
- Photovoltaic Manufacturing Concentration:Domestic cell and panel production capacity lags demand, creating dependency on imported components subject to tariff and trade policy uncertainty.
- Weather-Dependent Range Variability:Solar auxiliary contribution fluctuates with seasonal irradiance patterns and cloud cover, limiting deployment viability in northern tier states during winter months.
Strategic Opportunities
- Sunbelt Workplace Charging Infrastructure:California, Arizona, and Texas employers are piloting solar canopy bike parking as a differentiated benefits amenity to attract urban talent pools.
- Fleet-as-a-Service Subscription Models:Commercial operators in dense metropolitan districts are adopting usage-based procurement to eliminate upfront capital requirements and technology obsolescence risk.
- Smart Connectivity Convergence:Integration of GPS tracking, theft recovery, and predictive maintenance telemetry is creating recurring revenue streams through software-enabled fleet management platforms.
Industry Challenges
- Electrical System Certification Complexity:The Consumer Product Safety Commission's evolving safety standards for photovoltaic-integrated battery systems are extending product development timelines and testing expenditures.
- Intermittent Power Management Engineering:Optimizing charge controllers to blend grid, regenerative braking, and solar inputs requires specialized firmware expertise that remains scarce in the domestic supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar E-Bike Market |
| Market Size in 2026 | $42.5 Million |
| Market Size in 2035 | $185.65 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding E-Bikes, Mountain E-Bikes, Commuter E-Bikes, Cruiser E-Bikes Technology: Solar Battery Integration, Smart Connectivity, Regenerative Braking, GPS Navigation End User: Recreational Users, Commuters, Delivery Services, Tourists Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Rental Services |
| Companies Covered | Vintage Electric Bikes, Rad Power Bikes, Trek Bicycle Corporation, Aventon Bikes, Lectric eBikes, Juiced Bikes, Ride1UP, Blix Electric Bikes, Pedego Electric Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar E-Bike Market Trends and Innovations
Photovoltaic integration, regulatory incentive stacking, and procurement model innovation are converging to transform how commercial and consumer buyers acquire and operate solar-assisted electric mobility platforms.
Frame-embedded perovskite and crystalline silicon cells are integrating into down tube and rack-mounted configurations to harvest ambient light during parking and transit. Food delivery cooperatives and municipal postal services in California and Florida are deploying these systems at scale to reduce mid-shift charging dependency. The technology is integrating operational flexibility into route planning that previously required battery swap infrastructure or extended dwell time at charging stations.
The Inflation Reduction Act's commercial clean vehicle credit structure is altering total cost of ownership calculations for fleet procurement departments. The Federal Highway Administration's evolving bike lane infrastructure eligibility criteria are simultaneously expanding permitted routing networks for commercial cargo variants. California's incentive stacking with CARB programs is producing the most compressed payback periods, concentrating early adoption in Los Angeles, San Diego, and San Francisco metropolitan statistical areas.
Commercial buyers are consolidating procurement authority into centralized fleet management departments that negotiate enterprise service agreements rather than transactional equipment purchases. Direct-to-consumer channels are losing share in the commercial segment to vertically integrated lessors offering maintenance-inclusive subscriptions. This behavioral shift is most pronounced among last-mile logistics providers operating in urban cores with established bike lane networks and congestion pricing regimes.
US Solar E-Bike Market Segmentation
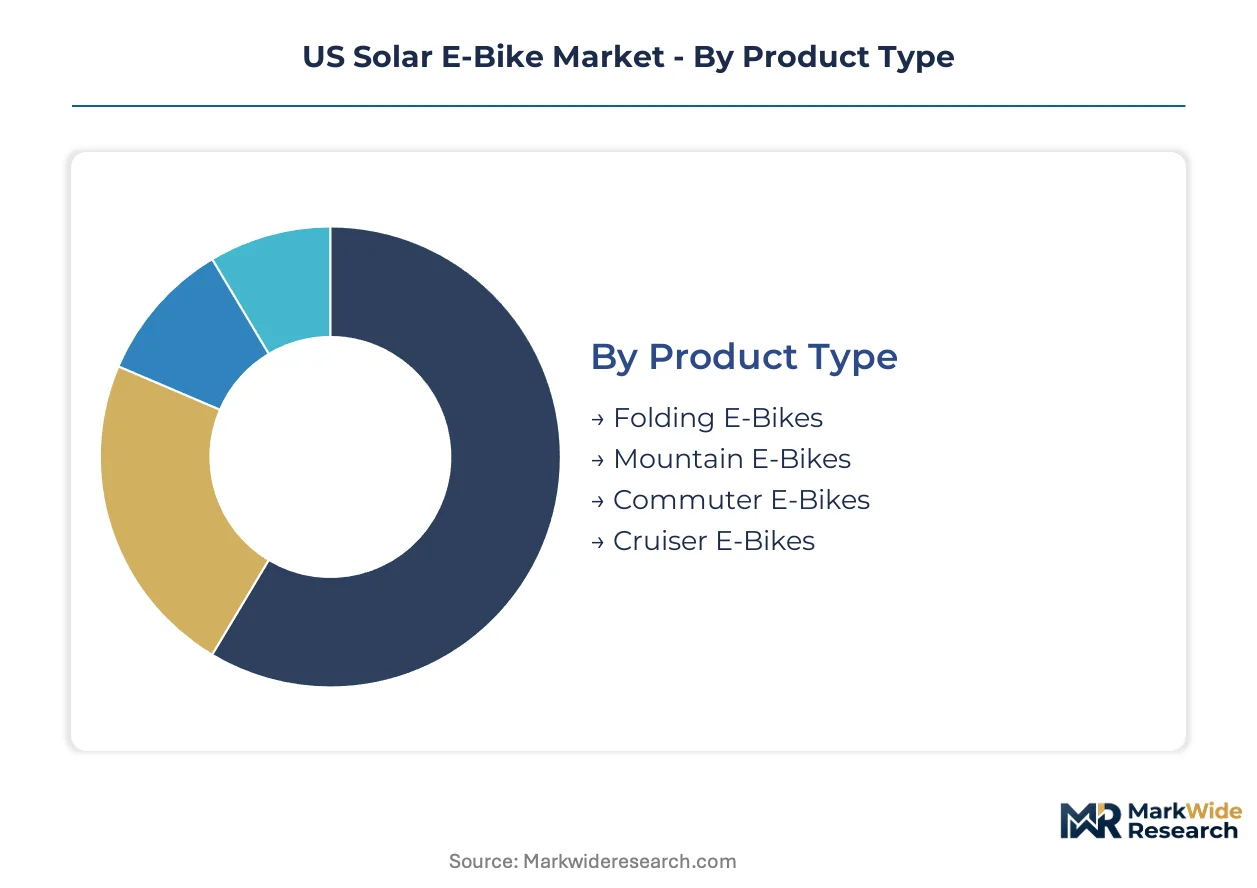
Segmentation in the US solar e-bike market reveals how photovoltaic integration creates divergent value propositions across mobility use cases. Buyer priorities shift from storage efficiency in dense urban housing to range reliability in commercial fleet deployment.
Product Type:
Price sensitivity and infrastructure access determine which frame configurations dominate procurement decisions.
- Commuter E-Bikes:Frame-integrated solar panels on step-through and diamond-frame geometries deliver 15-25 miles of auxiliary range per day. California metropolitan corridors concentrate procurement where bike lane density and workplace charging infrastructure overlap with high solar irradiance.
- Folding E-Bikes:Collapsible frame designs prioritize apartment storage constraints over aerodynamic efficiency. Demand clusters among urban renters in San Francisco, New York, and Boston who lack secure garage access.
- Mountain E-Bikes:Reinforced suspension systems accommodate off-trail photovoltaic mounting racks for backcountry recreational use.
- Cruiser E-Bikes:Upright seating geometries with integrated rear-rack solar panels target beachside retirement communities in Florida and Arizona.
Volume sits with commuter configurations; growth tilts toward folding platforms as urban density intensifies.
Technology:
Feature bundling strategies separate fleet-grade reliability from consumer convenience tiers.
- Solar Battery Integration:Perovskite and crystalline silicon cell arrays embedded in frame tubes or detachable panel systems supplement lithium-ion charge cycles. Food delivery cooperatives in Los Angeles and San Diego deploy these systems to reduce mid-shift charging dependency.
- Smart Connectivity:GPS tracking, theft recovery, and predictive maintenance telemetry generate recurring subscription revenue. Commercial fleet operators prioritize these platforms for route optimization and asset monitoring.
- Regenerative Braking:Kinetic energy recovery systems extend range in stop-and-go urban traffic patterns.
- GPS Navigation:Integrated routing software with bike lane prioritization aids courier efficiency in congested metropolitan districts.
Revenue concentrates in solar-battery systems; margin expansion tracks smart connectivity adoption.
End User:
Duty cycle intensity and route predictability shape technology specifications and financing structures.
- Delivery Services:High-mileage commercial operators in urban logistics networks require maximum solar auxiliary contribution to minimize grid charging frequency. The Inflation Reduction Act's commercial clean vehicle credits compress payback periods for fleet procurement in California, Arizona, and Texas.
- Commuters:Daily predictability justifies solar panel cost recovery through reduced electricity expenditure. Federal Highway Administration bike lane eligibility criteria influence route viability assessments.
- Recreational Users:Weekend riders prioritize purchase price over photovoltaic efficiency metrics.
- Tourists:Rental-based consumption in resort municipalities favors simple operation over advanced feature sets.
Fleet deployment drives unit economics; recreational adoption scales price accessibility.
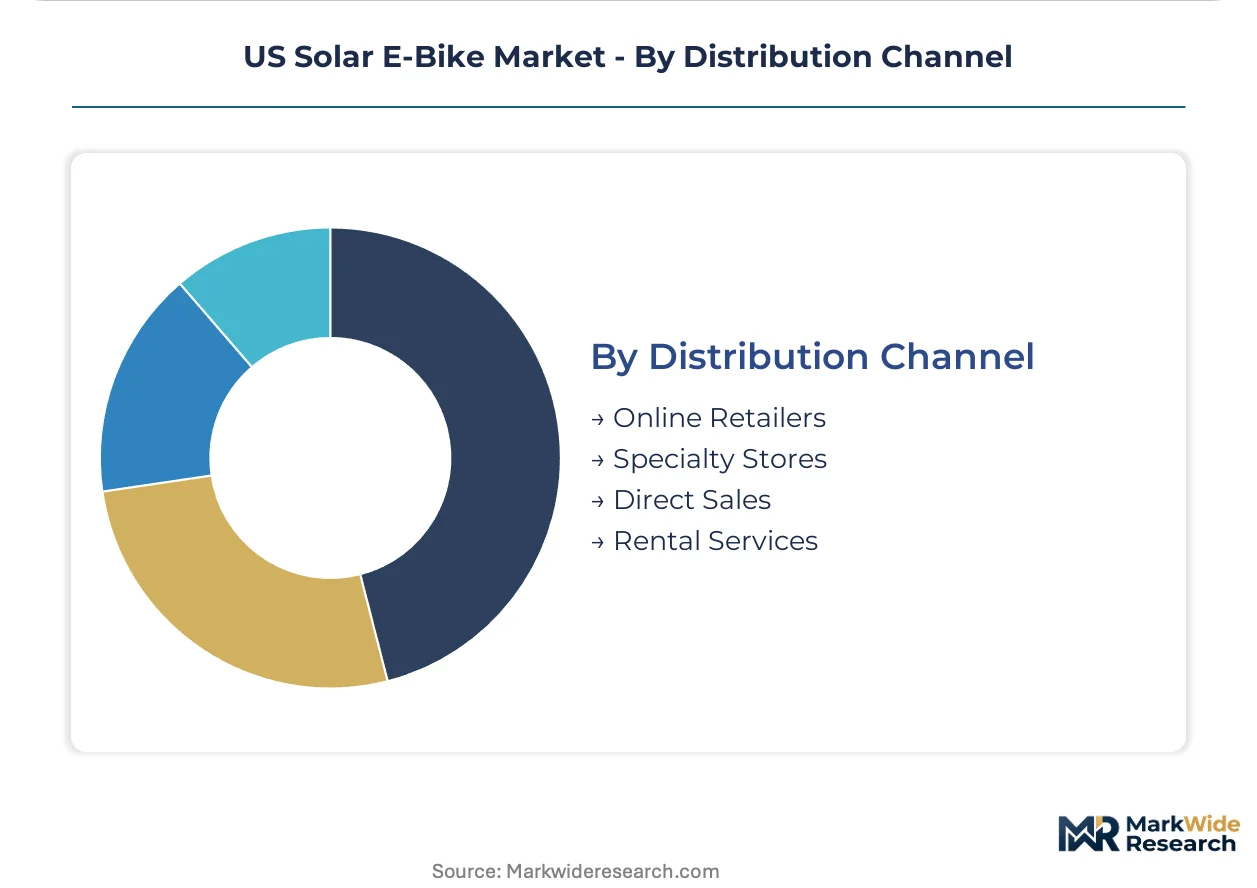
Distribution Channel:
Channel selection reflects buyer sophistication and service requirements across consumer and commercial segments.
- Direct Sales:Manufacturer-owned channels capture margin and control customer data for subscription service conversion. Rad Power Bikes leverages this model to sustain price accessibility for urban commuters.
- Specialty Stores:Dealer networks provide maintenance infrastructure and test-ride access that anchors premium positioning. Trek Bicycle Corporation concentrates here for component quality assurance.
- Online Retailers:E-commerce platforms reduce customer acquisition costs for value-engineered product tiers.
- Rental Services:Usage-based procurement eliminates upfront capital requirements and technology obsolescence risk for commercial operators.
Commercial volume flows through direct and rental channels; consumer purchases fragment across specialty and online routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic consumption concentrates in sunbelt metropolitan corridors while photovoltaic cell manufacturing remains import-dependent. California, Arizona, and Texas generate disproportionate fleet procurement volume due to overlapping solar irradiance and urban logistics density. The Inflation Reduction Act's domestic content requirements are gradually shifting component sourcing geography.
California
Los Angeles and San Diego logistics networks drive commercial fleet electrification for last-mile delivery services. California Air Resources Board zero-emission vehicle incentives stack with federal IRA credits to produce the nation's shortest payback periods. The San Francisco Bay Area anchors commuter adoption where bike lane infrastructure density intersects with technology sector employee benefit programs.
Arizona
Phoenix and Tucson metropolitan areas exploit year-round solar irradiance for maximum photovoltaic auxiliary range contribution. Workplace solar canopy bike parking pilots are spreading among employers competing for urban talent pools. State-level building codes in Maricopa County are determining whether commercial property developers standardize solar charging amenities.
Texas
Houston and Dallas-Fort Worth delivery cooperatives are replacing combustion van fleets with solar-assisted cargo bikes to circumvent downtown congestion pricing zones. The state's independent grid structure creates variable electricity pricing that enhances solar self-consumption economics. Austin's municipal postal service has emerged as an early pilot site for frame-integrated perovskite deployments.
Florida
Miami and Tampa beachside retirement communities generate cruiser e-bike demand for recreational solar-assisted mobility. Florida Power & Light utility interconnection rules shape whether workplace solar charging expands beyond municipal pilot programs. Orlando's tourism rental operators are testing subscription-based fleet models to eliminate upfront capital barriers.
New York
New York City apartment density drives folding e-bike demand despite lower solar irradiance limiting photovoltaic efficiency. The Metropolitan Transportation Authority's bike lane expansion programs are expanding permitted commercial routing networks. State-level clean transportation incentives remain less generous than California equivalents, compressing adoption to high-mileage courier applications.
US Solar E-Bike Market Competitive Landscape
The competitive structure tilts toward direct-to-consumer specialists with vertically integrated supply chains. Market concentration remains moderate with no single player commanding dominant share. Two strategic archetypes predominate: price-accessible volume manufacturers and premium-tier dealer-network incumbents. Capacity expansion and subscription service development represent the dominant competitive moves as firms seek recurring revenue insulation from hardware margin compression.
Within the direct-to-consumer tier, Rad Power Bikes and Lectric eBikes exemplify price-accessible market penetration strategies. Trek Bicycle Corporation anchors premium positioning through established dealer infrastructure. These three manufacturers collectively represent the spectrum from value-engineered fleet procurement to component-quality-assured consumer segments, with each archetype occupying defensible positioning against cross-tier encroachment.
| Leading Market Players |
|---|
| Vintage Electric Bikes |
| Rad Power Bikes |
| Trek Bicycle Corporation |
| Aventon Bikes |
| Lectric eBikes |
| Juiced Bikes |
| Ride1UP |
| Blix Electric Bikes |
| Pedego Electric Bikes |
| Others |
Pricing and Supply Chain Analysis
Photovoltaic cell manufacturing costs cascade through three distinct pricing tiers as crystalline silicon and emerging perovskite inputs move from imported wafer suppliers to domestic frame integrators and finally to fleet procurement departments. Lithium-ion battery pack pricing exerts parallel pressure, with cathode material volatility transmitted downstream through value-engineered commuter models and premium dealer-network offerings alike.
Pricing Analysis
Range-per-dollar throughput anchors value-based pricing for commercial fleet operators calculating total cost of ownership against diesel van alternatives. Three-tier pricing structure across premium, standard, and economy levels separates Trek Bicycle Corporation's component-quality-assured dealer offerings from Rad Power Bikes' direct-to-consumer accessibility and Lectric eBikes' entry-level fleet positioning. Cost compression in the economy tier is intensifying because IRA credit eligibility requirements are forcing specification upgrades. Delivery services exhibit highest price sensitivity due to thin per-mile margins, while municipal postal services demonstrate lowest sensitivity given budgetary insulation from taxpayer funding.
Supply Chain Analysis
Single-source vulnerability sits with Chinese photovoltaic cell and lithium processing capacity that feeds domestic pack assembly operations. Taiwan and South Korea provide alternative wafer sourcing, though at volume premiums that erode margin structures for value-engineered tiers. Crystalline silicon wafers, lithium carbonate, and rare-earth permanent magnets constitute the critical input trinity. Tariff exposure on Chinese-origin cells creates procurement timing risk for manufacturers without qualified alternative supplier relationships. Distribution runs through direct-to-consumer fulfillment centers and specialty dealer networks, with rental fleet lessors emerging as a consolidated commercial channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over photovoltaic cell sourcing and smart connectivity software stacks determines margin retention against hardware commoditization.
For Market Incumbents: Hedge against lithium price volatility through long-term offtake agreements with Australian and Chilean mining operations rather than spot-market exposure. Secure CARB certification pathways early to maintain eligibility for California incentive stacking as standards tighten. Channel control through captive dealer networks protects premium positioning against direct-to-consumer erosion.
For New Entrants and Emerging Players: Capture the folding e-bike white space in New York and Boston apartment-dense corridors where incumbents underindex on storage-optimized designs. Penetrate the Arizona workplace charging pilot market before infrastructure standards crystallize around established suppliers. A subscription-first go-to-market angle bypasses upfront capital barriers that constrain fleet procurement experimentation.
For Investors and Strategic Acquirers: Perovskite cell efficiency announcements from domestic pilot facilities are the leading indicator that photovoltaic auxiliary range economics are approaching fleet-scale viability. Long-term viability hinges on software-enabled recurring revenue attachment rates rather than hardware shipment volumes. Acquisition targets should display smart connectivity platform maturity with existing GPS tracking and predictive maintenance telemetry deployments. Watch for IRA domestic content requirement phase-in schedules as the critical policy inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Perovskite Cell Integration | Frame-embedded perovskite arrays extend daily auxiliary range contribution beyond crystalline silicon limitations for courier applications. |
| Fleet-as-a-Service Platform Launch | Subscription models eliminate upfront capital barriers that constrain last-mile logistics electrification in congestion-priced urban cores. |
| Smart Connectivity Stack Development | GPS tracking and predictive maintenance telemetry generate recurring revenue streams insulated from hardware margin compression. |
| Workplace Charging Infrastructure Partnership | Solar canopy bike parking pilots in Arizona and Texas attract urban talent pools while creating captive fleet demand. |
| Domestic Cell Sourcing Transition | IRA domestic content requirements are shifting procurement toward qualified alternative suppliers outside tariff-exposed jurisdictions. |
Research Methodology
Document review covered SEC 10-K filings from publicly traded bicycle and battery manufacturers, Consumer Product Safety Commission safety standard dockets, and Federal Highway Administration infrastructure eligibility guidance, complemented by interviews with fleet procurement managers at last-mile logistics operators, dealer network principals, and photovoltaic cell procurement leads. Primary fieldwork engaged e-bike platform engineers, CARB regulatory affairs specialists, and commercial real estate developers piloting workplace charging amenities. Secondary validation drew from EIA electricity pricing data, customs import records for lithium and solar cell trade flows, and municipal procurement database extracts. Bottom-up unit economics modeling triangulated against top-down market sizing from incentive program enrollment figures.
Cross-referencing historical adoption curves in adjacent electric mobility categories against panel input from fleet operator investment committees shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology bundling, end-user duty cycle intensity, and distribution channel structure. CAGRs were derived from trajectory fitting to observed incentive-driven procurement acceleration patterns. Forecast inputs incorporated solar irradiance variability by metropolitan statistical area and evolving Federal Highway Administration bike lane eligibility criteria.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to perovskite commercialization timelines, lithium supply contract renegotiations, and potential IRA credit modification legislation. Forecasts reflect documented assumptions regarding incentive program continuity and infrastructure deployment schedules. Specific risk factors that could revise projections include photovoltaic tariff escalation, battery safety standard revisions extending certification timelines, and northern tier state winter range shortfalls limiting fleet viability assessments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Traction Motor Core Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Global Electric Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Intelligent Motor Control Center Market
Electric Motor
Electric Drives Market
Electric Motor
Motorcycle Battery Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Automotive Wiper Motor Market