
 Europe Automotive Torque Actuator Motor Market | 2026-2036
Europe Automotive Torque Actuator Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Torque Actuator Motor Market Insights
ISO 26262 functional safety certification is collapsing the supplier landscape for torque actuator motors in Europe. Robert Bosch GmbH leverages its in-house semiconductor and motor manufacturing to sustain full-stack control over safety-critical actuator modules. Continental AG anchors its competitive position through deep integration with chassis and powertrain platforms across German and Czech vehicle plants. Nidec Corporation competes by specializing in compact brushless motor architectures optimized for steer-by-wire and brake-by-wire applications.
Automotive torque actuator motors are electromechanical devices that convert electrical energy into precise rotational force for vehicle subsystem control, typically operating at voltages between 12V and 48V with position feedback resolution below 0.1 degrees for safety-critical functions. These motors enable active torque distribution, variable gear selection, and automated clutch engagement in modern powertrain and chassis systems. Brushless motors dominate European OEM specifications due to their superior thermal endurance and electromagnetic compatibility profiles under continuous duty cycles. Electronic control systems represent the fastest-growing technology dimension as vehicle networks shift from hydraulic and pneumatic actuation to software-defined torque management with real-time diagnostic capability.
The EU AI Act and ECE R79 steering regulations are reshaping product validation requirements for torque actuator motors deployed in automated driving corridors. REACH compliance on rare-earth magnet content and the F-Gas Regulation on thermal management fluids are adding material traceability costs that filter through Tier-1 procurement contracts. The European Medicines Agency does not regulate this sector; ECHA chemical restrictions and CE marking under the EU Machinery Directive govern market access instead. Stakeholders must monitor how Euro 7 powertrain standards and the CSRD supply-chain disclosure rules will alter qualification timelines for new actuator platforms before committing capital to capacity expansion.
Market Dynamics
Electric powertrain architectures are compressing torque actuator motor specifications across European assembly lines, forcing suppliers to consolidate 12V and 48V control electronics into unified safety-critical modules. This voltage convergence is collapsing legacy component boundaries and redrawing procurement relationships between Tier-1 integrators and semiconductor foundries.
Growth Catalysts
- Euro 7 emission benchmarks:Mechanical precision mandates for powertrain actuation are tightening tolerances on brushless motor feedback systems, pulling advanced torque modules into every new vehicle platform certified after 2026.
- Stuttgart-Munich engineering corridor:OEM prototyping facilities and Tier-1 development centers cluster in southern Germany, concentrating demand pull for steer-by-wire and brake-by-wire actuator validation.
- Steer-by-wire architectures:Elimination of mechanical steering columns is expanding addressable motor volume per vehicle from single-unit to redundant dual-motor configurations.
Market Restraints
- Rare-earth magnet supply concentration:REACH compliance on neodymium and dysprosium traceability is adding qualification costs that filter through Tier-1 procurement contracts, compressing margin structures for non-integrated suppliers.
- ISO 26262 certification timelines:Functional safety validation for ASIL-D rated actuator modules extends development cycles by 18-24 months, freezing out capital-constrained entrants.
- Hydraulic actuation legacy:Mature chassis systems in commercial vehicle segments retain installed base advantages, slowing electrification conversion in heavy-duty torque applications.
Strategic Opportunities
- Czech vehicle plant integration:Continental AG and Bosch have anchored manufacturing in Moravia-Silesia, creating regional supply chain density that lower-cost competitors can exploit for contract manufacturing partnerships.
- EU AI Act validation corridors:Automated driving test zones in Germany and France are creating preemptive certification pathways for torque actuators with real-time diagnostic telemetry.
- CSRD supply-chain disclosure:Mandatory carbon accounting is advantaging motor suppliers with captive rare-earth recycling and European-sourced magnet content.
Industry Challenges
- Embedded software competency gaps:Motor suppliers without in-house functional safety engineering teams face ASIL-D certification failures that block platform approvals from KBA and other national type-approval authorities.
- Legacy powertrain integration friction:Dual-voltage architectures (12V auxiliary, 48V propulsion) require torque actuators with protocol-switching capability, complicating validation matrices for Tier-1 integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Torque Actuator Motor Market |
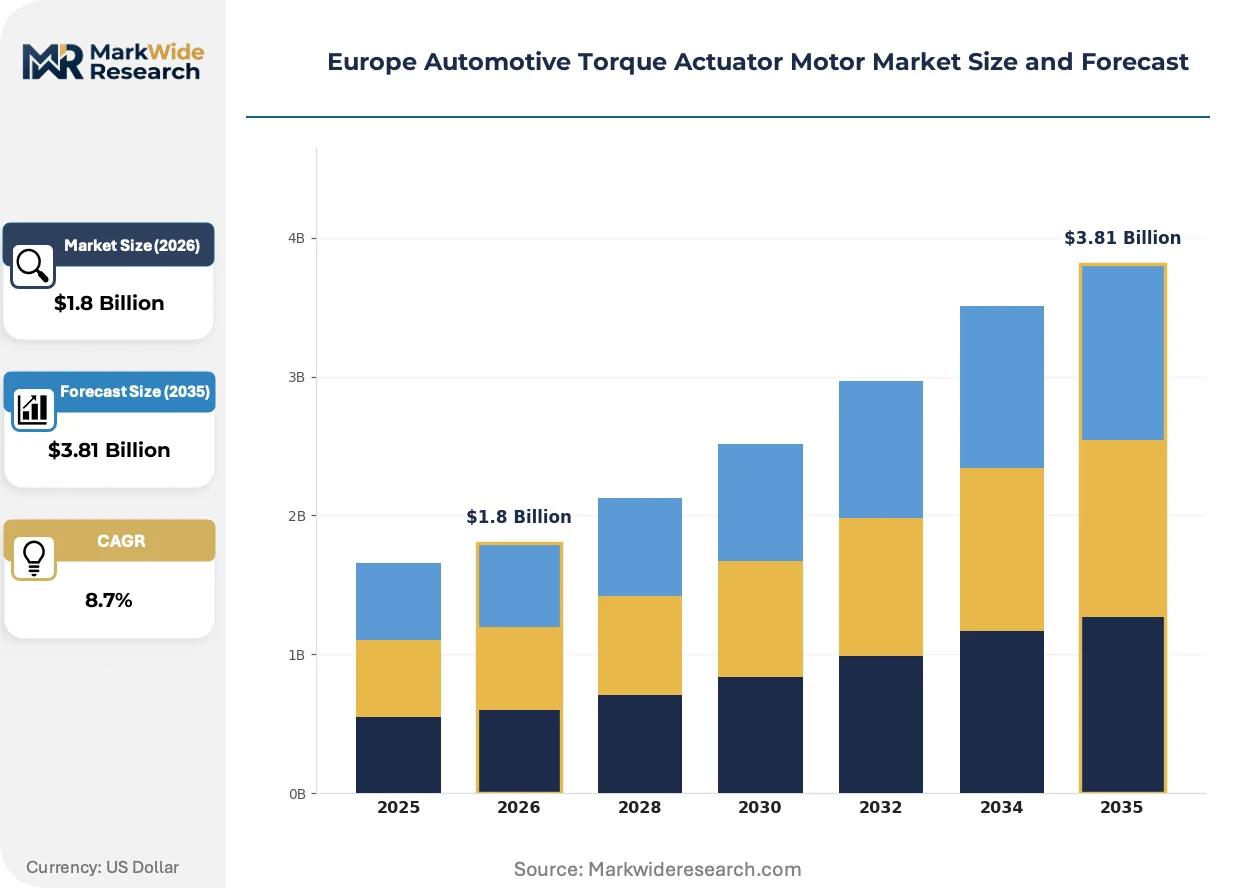
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless Motors, Stepper Motors, AC Motors, DC Motors End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electronic Control Systems, Mechanical Linkages, Hydraulics, Pneumatics Application: Powertrain Systems, Steering Mechanisms, Brake Systems, Chassis Control |
| Companies Covered | Robert Bosch GmbH, Nidec Corporation, Continental AG, Denso Corporation, Johnson Electric Holdings Ltd, Mitsubishi Electric Corp, CTS Corp, Mabuchi Motor Co., Ltd., NSK Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Torque Actuator Motor Market Trends and Innovations
Software-defined torque management is displacing hydraulic and pneumatic actuation across European chassis platforms, compressing hardware differentiation into semiconductor and firmware layers. This shift is collapsing traditional component boundaries and elevating real-time diagnostic capability to a primary purchasing criterion.
Integrated motor-inverter modules are miniaturizing power electronics into the actuator housing itself, eliminating discrete ECU packaging. Tier-1 suppliers in Germany and the Czech Republic are adopting these compact brushless architectures for steer-by-wire prototypes. The technology is miniaturizing thermal management requirements and enabling dual-redundant motor configurations within legacy steering column envelopes.
ECE R79 steering regulations are mandating fail-operational performance for automated driving systems, forcing torque actuator suppliers to implement dual-channel position sensing and independent power paths. The regulation is extending validation timelines and concentrating development resources on safety-critical firmware verification. German OEMs are responding by pre-qualifying suppliers with in-house semiconductor fabrication.
Buyer concentration among German premium OEMs is compressing supplier negotiation leverage and extending payment terms. Tier-2 motor specialists are responding by forming cooperative purchasing consortia for rare-earth magnets and silicon carbide substrates. This consolidation is most visible in Baden-Württemberg and Bavaria, where engineering co-location enables shared validation infrastructure.
Europe Automotive Torque Actuator Motor Market Segmentation
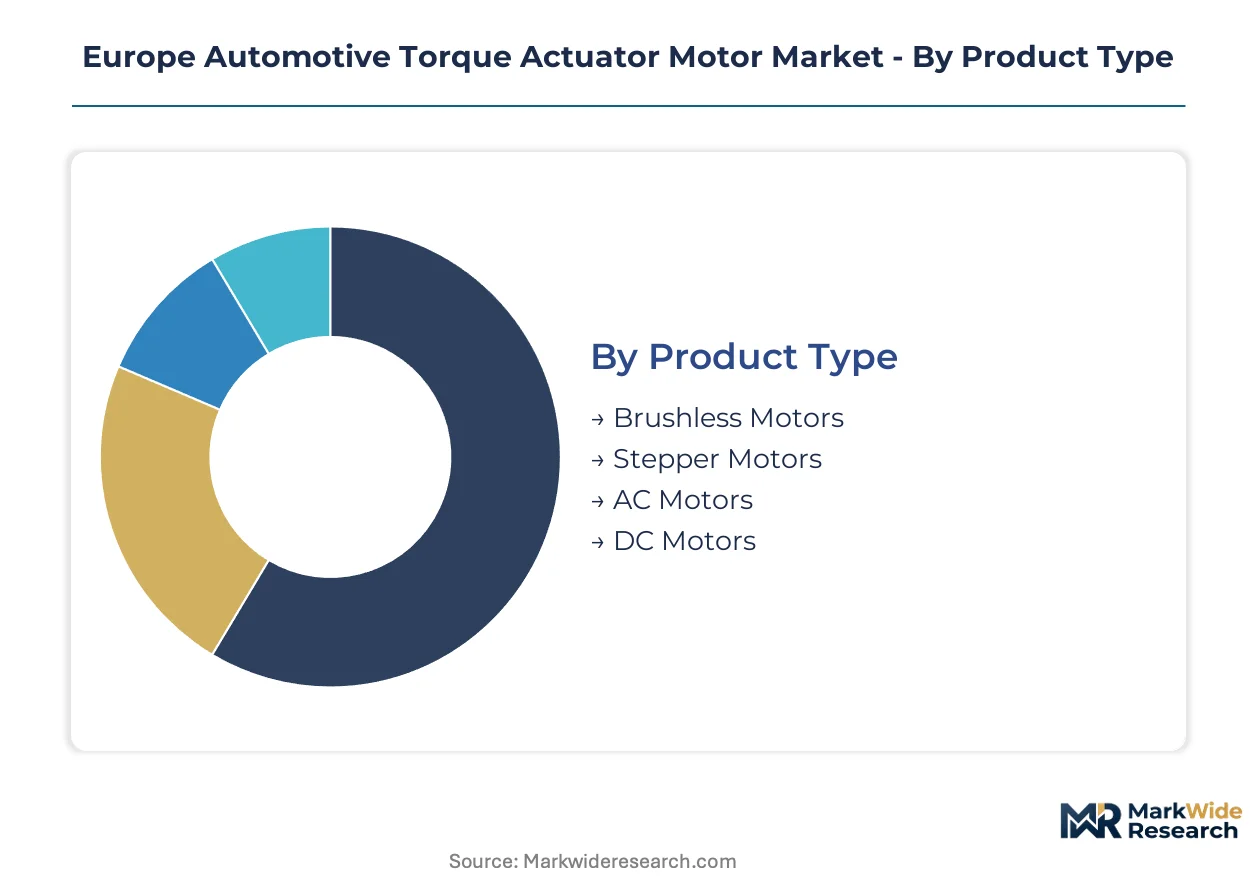
Torque actuator motor procurement in Europe fragments across voltage architectures, safety certification tiers, and integration depth. Segment boundaries are collapsing as 48V powertrains force suppliers to consolidate discrete motor categories into unified electromechanical modules.
Product Type:
REACH compliance on rare-earth traceability and ISO 26262 ASIL ratings are segmenting motor procurement by magnet composition and thermal endurance certification.
- Brushless Motors:Permanent magnet synchronous architectures dominate steer-by-wire and brake-by-wire platforms due to superior electromagnetic compatibility under continuous duty cycles. German premium OEMs in the Stuttgart-Munich corridor specify these exclusively for automated driving corridors requiring fail-operational redundancy.
- Stepper Motors:Open-loop positioning systems with discrete step resolution serve variable valve timing and automated clutch engagement in cost-optimized powertrain modules. Czech vehicle plants favor these for hybrid transmission actuation where absolute position feedback is secondary to cost containment.
- AC Motors:Induction architectures with simplified rotor construction address heavy-duty commercial vehicle torque demands where rare-earth supply concentration poses procurement risk.
- DC Motors:Brushed commutator designs persist in legacy 12V auxiliary systems and aftermarket replacement channels with minimal functional safety requirements.
Established volume favors brushless architectures; emerging adoption favors stepper configurations in hybrid powertrain cost engineering.
End User:
Procurement authority is concentrating at the platform integration tier, collapsing traditional boundaries between component supply and vehicle assembly.
- OEMs:Engineering centers in Baden-Württemberg and Bavaria retain direct sourcing authority for safety-critical steer-by-wire motors, mandating in-house semiconductor validation and dual-source magnet procurement to satisfy CSRD disclosure requirements.
- Tier-1 Suppliers:Chassis and powertrain integrators in Moravia-Silesia consolidate 12V and 48V motor-inverter modules into unified subsystems, compressing Tier-2 component boundaries and extending payment terms to 90-120 days.
- Aftermarket Providers:Independent distributors serve legacy hydraulic-to-electric conversion demand in commercial vehicle segments with extended service intervals.
- Vehicle Assemblers:Contract manufacturers in Eastern European border regions execute final torque actuator calibration per OEM specification without design authority.
Platform control concentrates with OEMs and Tier-1 integrators; aftermarket channels capture residual legacy replacement volume.
Technology:
Software-defined torque management is elevating electronic control systems above mechanical actuation heritage in procurement priority.
- Electronic Control Systems:Real-time diagnostic firmware with ASIL-D functional safety certification enables automated driving torque redundancy. ECE R79 steering regulations mandate dual-channel position sensing and independent power paths, extending validation timelines for suppliers without embedded software competency.
- Mechanical Linkages:Direct shaft couplings and reduction gearsets provide deterministic torque transmission for brake-by-wire backup modes where electrical failure must default to mechanical continuity.
- Hydraulics:Pressurized fluid actuation retains installed base advantages in heavy-duty chassis systems, slowing electrification conversion in commercial vehicle torque applications.
- Pneumatics:Compressed air systems persist in auxiliary braking and suspension adjustment with minimal integration complexity.
Electronic architectures are climbing the fastest; hydraulic legacy retains defensive positions in commercial vehicle duty cycles.
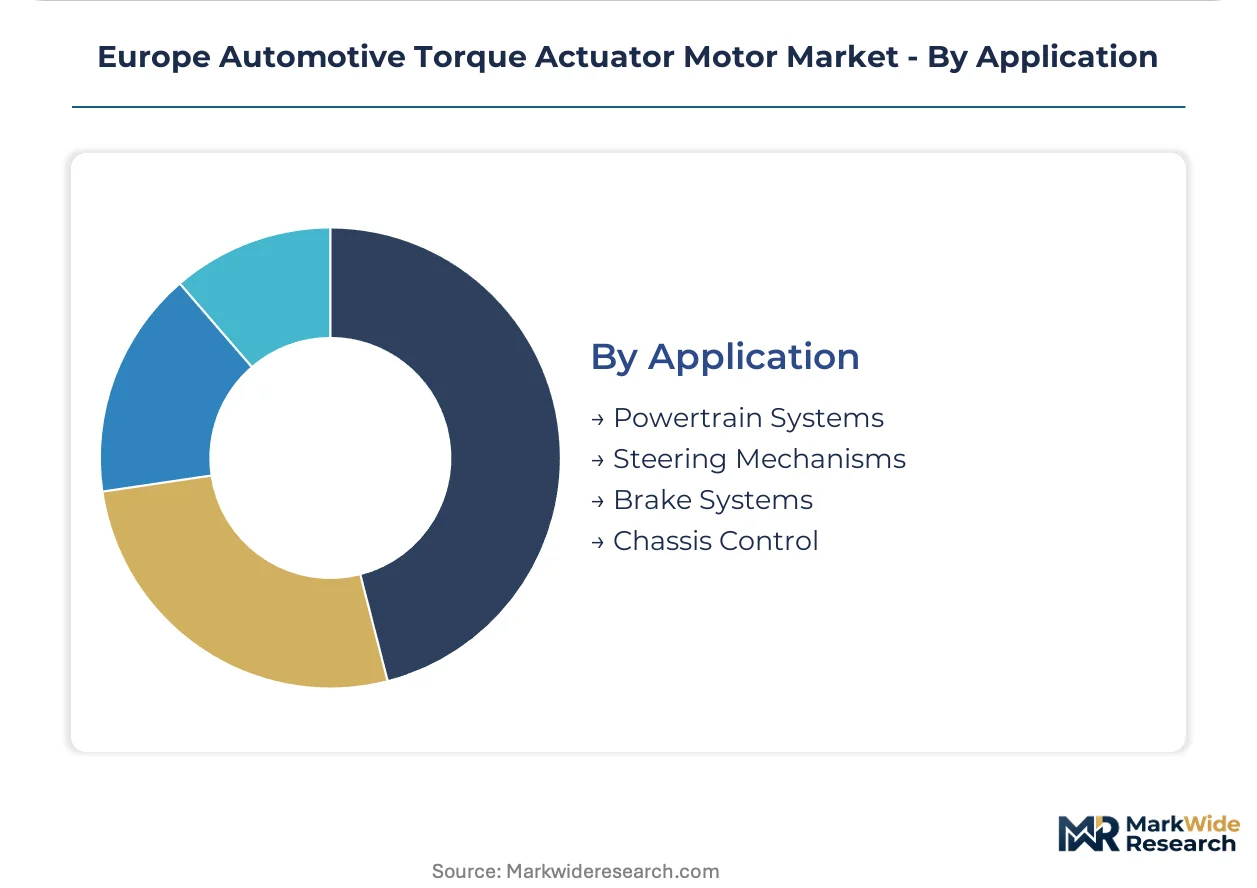
Application:
Euro 7 emission benchmarks are pulling advanced torque modules into every powertrain and chassis subsystem certified for production after 2026.
- Powertrain Systems:Automated clutch engagement and variable gear selection motors operate at 48V with position feedback resolution below 0.1 degrees. Dual-voltage architectures require protocol-switching capability, complicating validation matrices for Tier-1 integrators serving German OEM platforms.
- Steering Mechanisms:Steer-by-wire elimination of mechanical columns expands addressable motor volume per vehicle from single-unit to redundant dual-motor configurations. KBA type-approval mandates fail-operational performance for automated driving systems.
- Brake Systems:Electro-hydraulic brake actuation combines motor-driven piston control with hydraulic backup modes, bridging electrification and legacy safety requirements.
- Chassis Control:Active torque distribution motors enable vectoring and stability management across multi-motor electric axle configurations.
Steering and powertrain applications command development resources; chassis control motors gain share fastest in multi-axle electric platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium OEM engineering centers in southern Germany concentrate procurement authority for safety-critical torque actuator modules. Tier-1 integrators cluster in Moravia-Silesia and the Stuttgart-Munich corridor to minimize validation cycle times. National type-approval authorities in Germany, France, and the UK are extending qualification timelines for steer-by-wire platforms.
Germany
KBA mandates fail-operational performance for automated driving torque actuators under ECE R79. Stuttgart and Munich host OEM prototyping facilities that pre-qualify suppliers with in-house semiconductor validation. The Baden-Württemberg and Bavaria engineering corridor concentrates dual-motor steer-by-wire development for premium vehicle platforms.
Czech Republic
Continental AG and Bosch anchor manufacturing in Moravia-Silesia for chassis and powertrain module integration. Czech vehicle plants favor stepper motor configurations for hybrid transmission actuation where cost containment outweighs absolute position feedback precision. The region's supply chain density attracts contract manufacturing partnerships from lower-cost competitors.
France
ANSM and CNIL oversight intersects with EU AI Act validation corridors for automated driving test zones. French OEMs are pre-qualifying torque actuators with real-time diagnostic telemetry for fail-operational steering systems. Industrial clusters around Paris and Lyon concentrate brake-by-wire actuator prototyping for multi-motor electric axle configurations.
United Kingdom
Post-Brexit regulatory divergence from EU type-approval frameworks is creating parallel validation requirements for torque actuator suppliers. UK-based Tier-1 integrators are consolidating 12V and 48V motor-inverter modules to serve both domestic and continental European OEM contracts. The Midlands automotive corridor retains development capacity for powertrain actuation systems.
Italy
Lombardy and Piedmont engineering centers specialize in compact brushless architectures for chassis control applications. Italian Tier-1 suppliers are exploiting CSRD supply-chain disclosure rules by developing captive rare-earth recycling partnerships. The region's motor specialists focus on active torque distribution for multi-axle electric platforms.
Europe Automotive Torque Actuator Motor Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive semiconductor and motor manufacturing capabilities. The supplier landscape is consolidating around integrated electromechanical module providers that control firmware, power electronics, and magnetic material sourcing. Two strategic archetypes dominate: full-stack safety-critical system integrators and compact motor specialists optimized for steer-by-wire redundancy. Competitive moves center on backward integration into rare-earth magnet supply chains and strategic partnerships with semiconductor foundries for ASIL-D certified control electronics.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify full-stack control over safety-critical actuator modules through in-house manufacturing depth. Nidec Corporation occupies a specialist position focused on compact brushless motor architectures. These three companies represent the competitive anchors that Tier-2 motor specialists must position against when seeking platform approvals from German and Czech vehicle plants.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Nidec Corporation |
| Continental AG |
| Denso Corporation |
| Johnson Electric Holdings Ltd |
| Mitsubishi Electric Corp |
| CTS Corp |
| Mabuchi Motor Co., Ltd. |
| NSK Ltd. |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification timelines for ASIL-D certified torque actuator modules concentrate supply-side pricing power with integrated Tier-1 suppliers possessing captive semiconductor foundry relationships. This extended validation cycle compresses buyer negotiation leverage and extends payment terms to 90-120 days across German and Czech procurement contracts.
Pricing Analysis
Cost-plus contracts indexed to rare-earth magnet spot prices dominate Tier-1 procurement agreements for brushless motor architectures. Three-tier pricing structure across ASIL-D certified, ASIL-B intermediate, and non-safety-critical economy levels reflects ISO 26262 certification investment recovery. Pricing pressure stems from REACH compliance traceability costs filtering through neodymium supply chains. Aftermarket distributors exhibit highest price sensitivity due to legacy hydraulic conversion demand, while OEM direct sourcing tolerates premium positioning for fail-operational redundancy.
Supply Chain Analysis
Strategic stockpiling of dysprosium and terbium inventories characterizes motor suppliers seeking insulation from Chinese export quota volatility, contrasting with just-in-time silicon carbide substrate procurement from German and Austrian semiconductor foundries. Magnet sourcing concentrates in China, Myanmar, and Australia; winding copper and lamination steel draw from European mills. Single-source vulnerability permeates rare-earth separation capacity. Distribution runs through Tier-1 integrator consolidation hubs in Moravia-Silesia before final vehicle plant sequencing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German premium OEMs and Tier-1 chassis integrators, collapsing negotiation leverage for component specialists and extending qualification timelines that freeze out capital-constrained entrants.
For Market Incumbents: Secure backward integration into rare-earth magnet recycling and European-sourced magnetic material supply to satisfy CSRD disclosure requirements and insulate margin structures from REACH traceability cost inflation. Defend platform approvals by pre-qualifying dual-source semiconductor validation capabilities with KBA and other national type-approval authorities before competitors complete ASIL-D certification cycles. For New Entrants and Emerging Players: Differentiate on compact brushless architectures optimized for steer-by-wire redundancy in Czech vehicle plant contract manufacturing partnerships. Czech hybrid transmission actuation presents the most penetrable white-space, where stepper motor cost engineering outweighs absolute position feedback precision. Pursue cooperative purchasing consortia for silicon carbide substrates to bypass individual volume minimums imposed by German foundries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core motor divisions lacking embedded software competency for ASIL-D functional safety certification. Five-to-ten year viability hinges on firmware development depth rather than mechanical manufacturing scale. Watch for Euro 7 powertrain standard finalization as the inflection signal triggering accelerated torque actuator platform refresh cycles and captive capacity investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Recycling Integration | Captive dysprosium recovery satisfies CSRD carbon accounting and REACH traceability mandates for European OEM contracts. |
| ASIL-D Firmware Development Partnership | Semiconductor foundry alliances compress 18-24 month functional safety validation timelines for steer-by-wire platforms. |
| Czech Manufacturing Footprint Expansion | Moravia-Silesia regional density enables shared validation infrastructure and contract manufacturing partnerships. |
| Dual-Voltage Protocol Switching Investment | 12V-48V unified module capability addresses legacy powertrain integration friction in hybrid architectures. |
| Real-Time Diagnostic Telemetry Certification | EU AI Act validation corridor pre-qualification secures automated driving torque actuator procurement authority. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement documentation anchors the qualitative findings on torque actuator motor specification convergence. Primary interviews with chassis integration directors, powertrain platform engineers, aftermarket distribution managers, and semiconductor foundry account executives combined with secondary validation from vehicle production databases, IHS Markit registration data, ECHA chemical restriction filings, and KBA type-approval records. Bottom-up segment sizing triangulates against top-down OEM procurement budget analysis.
Sensitivity analysis on rare-earth price volatility and Euro 7 implementation timing frames the forecast envelope across the projection horizon. Segmentation dimensions modeled include voltage architecture, ASIL certification tier, motor topology, integration depth, end-user procurement authority, and regional production cluster. CAGRs derive from vehicle platform production schedules weighted by content-per-vehicle assumptions for steer-by-wire, brake-by-wire, and powertrain actuation applications. Forecast inputs incorporate EU Green Deal powertrain electrification mandates and ECE R79 steering regulation compliance timelines.
Material uncertainties — rare-earth export quota disruption, Euro 7 standard finalization delays, and semiconductor foundry capacity allocation shifts — sit outside the modeled envelope. Forecasts reflect assumptions on OEM platform electrification roadmaps and Tier-1 supplier consolidation trajectories. Revision becomes warranted when KBA or other national type-approval authorities modify fail-operational performance thresholds for automated driving torque actuators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
United States AC Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Europe Alternating Current (AC) Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Car Charger Market
Electric Motor
Electronically Commutated Motors Market
Electric Motor
Implant Motors Market
Electric Motor
Starter Motor Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Europe Electric Motor Market
Electric Motor
Global Automotive Onboard Charger Market