
 Global Motor Management Market | 2026-2036
Global Motor Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motor Management Market Foresight
IEC 61800-9 efficiency class upgrades is reorganizing procurement priorities across industrial motor fleets. ABB Ltd leverages its digital platform architecture to anchor premium retrofit contracts in European process industries. Siemens AG sustains technology leadership through integrated drive-train diagnostics that span low-voltage to medium-voltage motor systems. Schneider Electric SE differentiates via edge-computing motor protection relays that reduce unplanned downtime in critical infrastructure.
Motor management encompasses hardware and software systems that monitor, protect, and optimize electric motor performance through parameters including thermal overload curves, vibration spectra, and power factor correction, primarily serving industrial facilities seeking to extend asset life and reduce energy consumption. Controllers and sensors capture the dominant share of product-type revenue as retrofit installations outpace greenfield deployments in mature industrial bases. Manufacturing automation and renewable energy applications exhibit the strongest structural momentum, with wind turbine generator monitoring and conveyor system predictive maintenance driving replacement cycles faster than building systems or material handling segments.
IEC 61800 efficiency standards, NEMA MG-1 Premium efficiency mandates, and EU Ecodesign regulations collectively tighten minimum performance requirements and reshape supplier qualification criteria across all major sales channels. China's GB 18613 motor efficiency standards and India's BIS certification requirements add parallel compliance layers for equipment manufacturers serving Asian supply chains. Stakeholders must evaluate whether their product portfolios align with emerging cyber-security requirements for connected motor management systems before regulatory deadlines harden market access rules.
Market Dynamics
The transition from reactive maintenance to predictive motor management is compressing replacement cycles and forcing hardware-software integration across industrial facilities. IEC 61800-9 efficiency mandates and NEMA MG-1 Premium standards are simultaneously raising performance floors and disqualifying legacy equipment from new procurement tenders.
Growth Catalysts
- Industrial Electrification:Manufacturing automation in Germany, China, and the United States is accelerating motor fleet digitization as plants pursue energy optimization and thermal overload protection.
- IEC 61800-9 Efficiency Classes:Mandatory efficiency upgrades across European process industries are triggering wholesale retrofit demand for integrated drive-train diagnostics.
- Wind Turbine Generator Monitoring:Renewable energy expansion is creating specialized demand for vibration spectra analysis and power factor correction in offshore and onshore installations.
Market Restraints
- Semiconductor Component Volatility:Power electronics and sensor chip supply concentration in East Asian foundries creates input cost instability for motor controller manufacturers.
- Cyber-Security Compliance Burden:Emerging connected-system requirements for critical infrastructure are extending product development timelines and raising qualification costs.
- Legacy Equipment Longevity:Durable installed bases in mature industrial markets delay replacement cycles despite efficiency mandate pressures.
Strategic Opportunities
- Edge-Computing Protection Relays:Unplanned downtime reduction in water treatment and energy infrastructure is opening premium pricing for localized motor protection intelligence.
- India's BIS Certification Requirements:Parallel compliance layers for Asian supply chains create first-mover advantages for certified equipment portfolios.
- Digital Platform Convergence:Integration of thermal monitoring, vibration analysis, and energy metering into unified dashboards is displacing point-solution vendors.
Industry Challenges
- Embedded Systems Engineering Talent:Scarcity of firmware developers with motor control algorithm expertise is constraining product roadmap execution.
- Multi-Standard Certification Complexity:Simultaneous IEC, NEMA, GB 18613, and BIS testing requirements fragment R&D resources and delay market entry.
- Legacy SCADA Integration:Retrofit installations require protocol translation layers that increase commissioning costs and technical support burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motor Management Market |
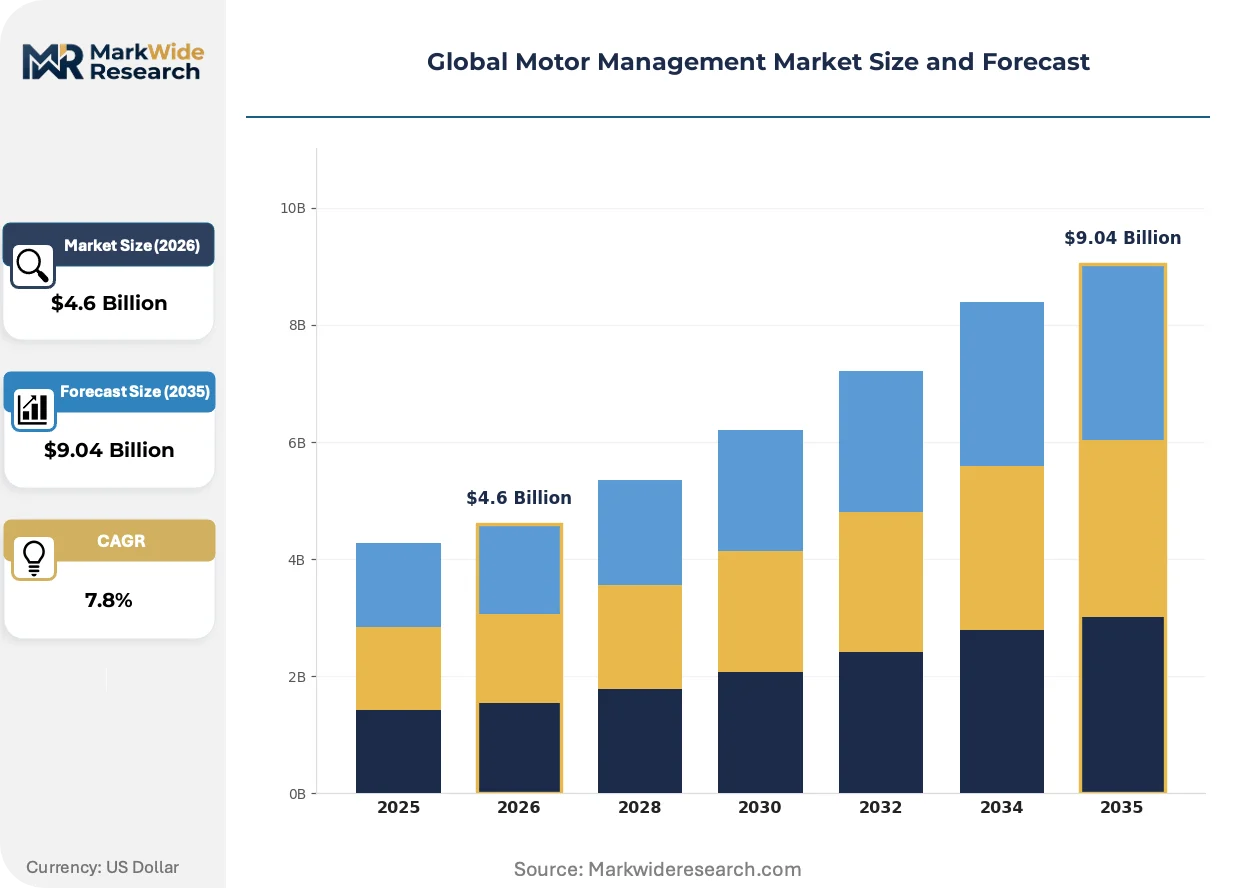
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Controllers, Sensors, Actuators, Converters, Relays Technology: Brushless DC, Induction, Synchronous, Stepper, Universal Application: Manufacturing Automation, Building Systems, Renewable Energy, Robotics, Material Handling End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Equipment Manufacturers |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Eaton Corporation, Mitsubishi Electric Corporation, General Electric, Rockwell Automation, Fuji Electric Co., Ltd., AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motor Management Market Shifts & Advancements
Sensor fusion architectures and edge-AI inference are redefining what motor management systems detect and automate without cloud dependency. The competitive frontier has shifted from hardware reliability to predictive accuracy and interoperability with plant-wide digital twins.
Digital twin integration for electric motor fleets is bifurcating the vendor landscape between platform-native suppliers and hardware-only component makers. Process industries in Germany and the Netherlands are deploying these systems at scale for conveyor and pump monitoring. The technology is compressing margins for standalone sensor vendors while anchoring long-term service contracts for integrated solution providers.
The EU Ecodesign regulations and F-Gas Regulation are tightening minimum efficiency thresholds and refrigerant system monitoring requirements for motor-driven compressors. Industrial OEMs must now document lifecycle energy consumption to maintain CE marking eligibility. Medium-voltage motor systems in chemical and paper processing face the steepest compliance redesign costs.
Asset-as-a-service contracting is displacing capital purchase models for large motor fleets in water utilities and mining operations. Performance guarantees covering energy consumption and uptime are transferring operational risk from plant operators to equipment vendors. This shift is most visible in Australia's desalination infrastructure and Brazil's iron ore processing corridors.
Global Motor Management Market Segmentation
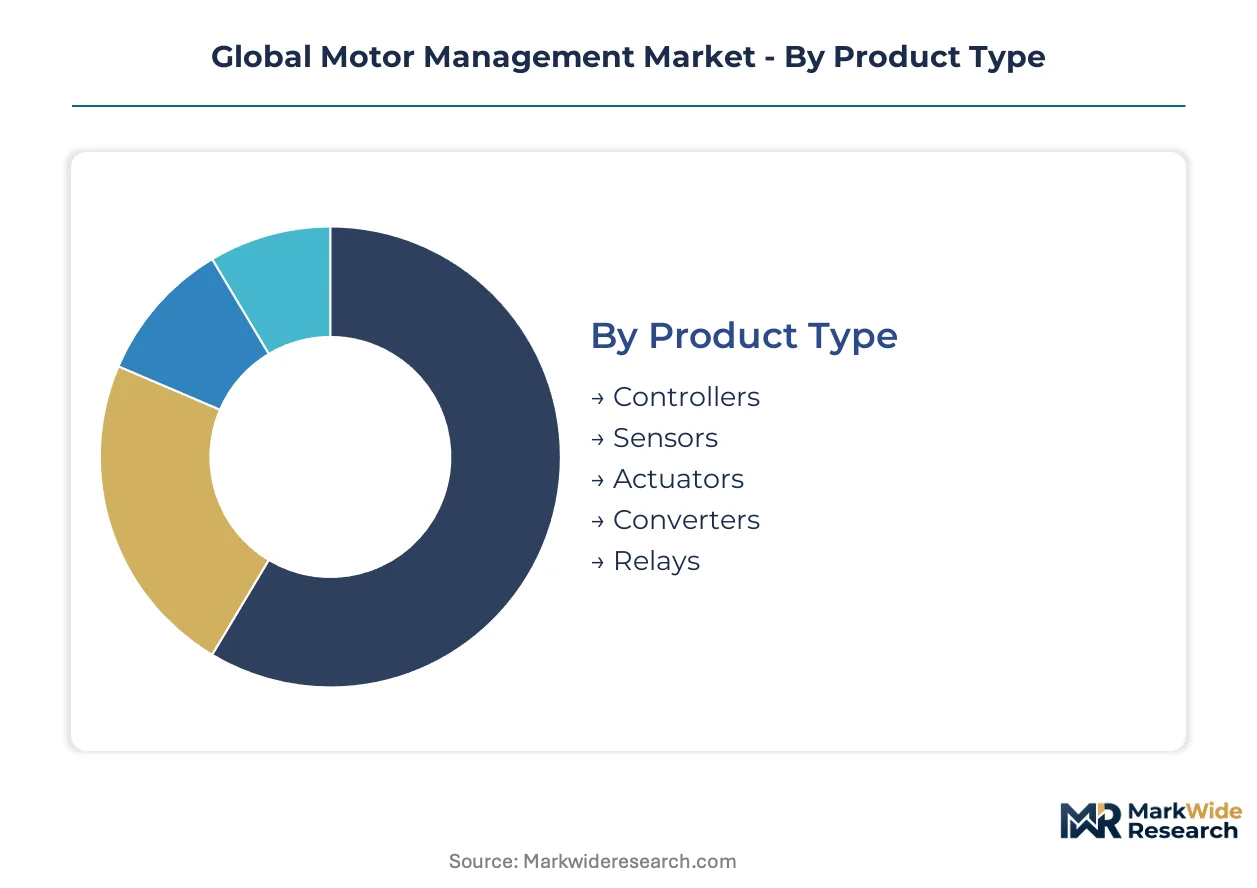
Motor management segmentation reveals how hardware-software integration intensity varies across industrial electrification applications. Procurement patterns diverge sharply between retrofit-heavy mature markets and greenfield automation corridors.
Product Type:
IEC 61800-9 efficiency mandates and NEMA MG-1 Premium standards are driving differential specification requirements across hardware categories, with connected-system compliance costs fragmenting supplier qualification tiers.
- Controllers:Embedded drive-train diagnostics platforms process thermal overload curves and power factor data in real-time. German process industries and Chinese EV battery plants are consolidating procurement around integrated motor control units that satisfy both IEC and GB 18613 efficiency certifications.
- Sensors:Vibration spectra and thermal monitoring arrays capture the dominant retrofit revenue share in mature industrial bases. United States manufacturing facilities are accelerating replacement cycles as predictive maintenance contracts displace reactive service models.
- Actuators:Precision positioning modules serve robotics and material handling segments with motion control algorithms.
- Converters:Power electronics interfaces bridge legacy motor fleets with modern digital control architectures.
- Relays:Edge-computing protection devices reduce unplanned downtime in water treatment and energy infrastructure.
Controllers handle the majority of throughput; sensors are expanding most quickly on share.
Technology:
Cost tier differentiation separates premium efficiency platforms from commodity motor architectures, with efficiency class premiums widening as IEC 61800-9 IE4/IE5 mandates harden.
- Brushless DC:Permanent magnet synchronous designs deliver highest efficiency ratings for precision motion applications. Robotics OEMs in Japan and wind turbine manufacturers in Denmark are specifying these systems for variable-speed duty cycles where energy recovery justifies capital premiums.
- Induction:Squirrel-cage architectures dominate installed base volumes across conveyor and pump systems. Indian cement plants and Brazilian mining operations are prioritizing these units for ruggedized duty where maintenance simplicity outweighs peak efficiency targets.
- Synchronous:Field-excited designs serve high-torque applications in chemical processing and paper manufacturing.
- Stepper:Open-loop positioning systems retain niche demand in laboratory automation and small-scale manufacturing.
- Universal:Series-wound configurations persist in handheld power tools and appliance motors where cost minimization dominates.
Induction technology anchors volume shipments; brushless DC is climbing the fastest on efficiency-driven replacement demand.
Application:
Customer type concentration varies by application maturity, with asset-as-a-service contracting penetrating water utilities and mining faster than discrete manufacturing.
- Manufacturing Automation:Conveyor system predictive maintenance and thermal overload protection dominate retrofit demand. German automotive plants and United States food processing facilities are deploying integrated drive-train diagnostics to compress unplanned downtime.
- Renewable Energy:Wind turbine generator monitoring requires specialized vibration analysis and power factor correction. Offshore installations in the North Sea and onshore corridors in Texas are driving replacement cycles faster than conventional utility applications.
- Building Systems:HVAC and elevator motor management faces longer replacement horizons due to installed base durability.
- Robotics:Precision motion control and force feedback systems serve collaborative automation deployments.
- Material Handling:Crane and forklift motor protection emphasizes ruggedized thermal monitoring for intermittent duty cycles.
Manufacturing automation captures the largest application revenue pool; renewable energy is gaining share fastest on capacity expansion timelines.
End User:
Supply concentration among semiconductor foundries is reshaping procurement risk profiles across end-user tiers, with Tier-1 suppliers and OEMs diverging on inventory strategies.
- OEMs:Original equipment manufacturers specify integrated motor-drive systems for new machine platforms. Industrial pump and compressor builders in Italy and machine tool producers in Switzerland are consolidating supplier relationships around platforms that satisfy EU Ecodesign lifecycle documentation requirements.
- Tier-1 Suppliers:Subsystem integrators face margin compression from multi-standard certification complexity across IEC, NEMA, and BIS testing regimes. Indian and Chinese automotive component suppliers are prioritizing certified portfolios to capture first-mover advantages in regional supply chains.
- Aftermarket Providers:Service contractors retrofit legacy fleets with predictive monitoring upgrades.
- Vehicle Assemblers:Electric powertrain integration demands specialized motor management for traction and auxiliary systems.
- Equipment Manufacturers:General industrial machinery builders balance standardization against customization pressures.
OEMs direct the highest procurement volumes; Tier-1 suppliers are expanding most quickly on supply chain regionalization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German motor management exports flow predominantly into Dutch and Belgian process industries, establishing a north-south corridor that shapes procurement specifications across the Rhine-Ruhr industrial belt.
United States
Food processing facilities in Wisconsin and automotive plants in Michigan are retrofitting conveyor systems with predictive maintenance modules. EPA industrial efficiency guidelines and FERC grid-interconnection standards tighten compliance timelines for motor-drive integration. The Ohio River Valley chemical corridor is consolidating supplier relationships around platforms satisfying NEMA MG-1 Premium mandates.
Germany
Ruhr-based steel operations and Bavarian automotive assembly lines are deploying integrated drive-train diagnostics for thermal overload protection. EU Ecodesign regulations and the F-Gas Regulation impose lifecycle documentation requirements on motor-driven compressor systems. The Stuttgart industrial cluster is pioneering edge-computing protection relay deployments for unplanned downtime reduction.
China
EV battery plants in Jiangsu and wind turbine assembly in Shandong are accelerating brushless DC motor adoption for variable-speed duty cycles. GB 18613 motor efficiency standards and MIIT industrial digitization directives create parallel certification layers for equipment manufacturers. The Yangtze River Delta electronics corridor is consolidating procurement around IEC and GB dual-certified control units.
India
Cement plants in Rajasthan and automotive component suppliers in Tamil Nadu are prioritizing induction motor architectures for ruggedized maintenance simplicity. BIS certification requirements and CEA power quality regulations are reshaping supplier qualification criteria for regional supply chains. The Gujarat industrial belt is capturing first-mover advantages through certified portfolio investments ahead of compliance deadlines.
Japan
Robotics OEMs in Kanagawa and precision machinery builders in Aichi are specifying permanent magnet synchronous systems for energy recovery applications. METI carbon neutrality roadmaps and JIS efficiency standards are accelerating replacement cycles in mature industrial bases. The Nagoya manufacturing cluster is integrating sensor fusion architectures for localized motor protection intelligence.
Global Motor Management Market Competitive Landscape
Listed leaders compete with private specialists across platform integration depth, with publicly traded conglomerates anchoring premium retrofit contracts while private component vendors capture sensor retrofit volumes. The vendor base stratifies into three tiers: integrated solution providers with digital twin capabilities, hardware-focused protection relay specialists, and regional system integrators serving legacy SCADA translation requirements. Strategic archetypes include platform-native suppliers consolidating around unified dashboards, edge-computing specialists localizing inference capabilities, and certification-first vendors navigating multi-standard complexity. Dominant competitive moves encompass backward integration into power electronics manufacturing and geographic expansion through certified portfolio replication in Asian supply chains.
Within the platform-native tier, ABB Ltd and Siemens AG exemplify integrated architecture providers, while Schneider Electric SE occupies a position bridging hardware reliability with edge-computing intelligence. These three entities represent contrasting approaches to the predictive maintenance transition: ABB anchors premium retrofit contracts through digital platform convergence, Siemens sustains technology leadership across voltage categories, and Schneider differentiates via localized protection intelligence for critical infrastructure. Each exemplifies how European industrial conglomerates are repositioning around software-integrated motor management rather than standalone component sales.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Eaton Corporation |
| Mitsubishi Electric Corporation |
| General Electric |
| Rockwell Automation |
| Fuji Electric Co., Ltd. |
| AMETEK Inc. |
| Others |
Supply & Pricing Matrix
Sixteen-week power electronics lead times in motor controller manufacturing concentrate pricing power among East Asian foundry operators and force European OEMs into strategic inventory pre-positioning. This supply-concentration dynamic compresses margins for mid-tier motor management vendors while amplifying volume-discount leverage for consolidated automotive and wind turbine procurement desks.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on IEC 61800-9 efficiency certification tier and embedded software capability depth. Pricing pressure stems from semiconductor input cost volatility transmitted through controller bill-of-materials. Tier-1 automotive suppliers exhibit highest price sensitivity due to annual cost-down mandates, while water utility asset-as-a-service contracts show lowest sensitivity given uptime guarantee premiums.
Supply Chain Analysis
Strategic stockpile preferences dominate motor management procurement as just-in-time exposure to Taiwan and South Korea foundry volatility proved catastrophic during recent semiconductor shortages. Power MOSFETs, current sensors, and industrial-grade microcontrollers draw from concentrated East Asian fabrication. Single-source vulnerability in 200mm wafer capacity for automotive-qualified chips remains the structural risk. Distribution runs through authorized industrial distributors with technical application support rather than commodity electronics brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among German automotive OEMs and Chinese wind turbine integrators, compressing supplier margins and forcing qualification consolidation around dual-certified platform providers.
For Market Incumbents: Shield premium retrofit contract positions by deepening backward integration into power electronics manufacturing and accelerating IEC 61800-9 IE5 certification pipelines ahead of regulatory deadlines. Edge-computing protection relay portfolios face substitution threat from software-defined motor management platforms; defend through captive silicon sourcing partnerships that secure 200mm wafer allocation. For New Entrants and Emerging Players: Legacy SCADA protocol translation services represent an underserved layer where incumbent platform vendors under-serve mid-sized process industries. India's BIS certification gap offers the most penetrable regulatory entry point for certified motor controller portfolios. Lead with retrofit-focused aftermarket service contracts rather than greenfield platform sales to bypass entrenched OEM supply relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with neglected motor management divisions lacking digital twin integration capabilities. Five-to-ten-year viability hinges on software-recurring revenue attachment rates exceeding hardware replacement cycles. Watch for MIIT industrial digitization directive enforcement intensity as the inflection signal for Chinese market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive wafer supply secures controller production against Taiwan foundry allocation volatility. |
| Dual-Certification Portfolio Expansion | Simultaneous IEC 61800-9 and GB 18613 compliance unlocks German and Chinese procurement tenders. |
| Edge-AI Inference Localization | On-device motor fault prediction reduces cloud dependency for critical infrastructure operators. |
| Asset-as-a-Service Contracting | Performance guarantees transfer operational risk from Brazil mining operators to equipment vendors. |
| Digital Twin Platform Convergence | Unified thermal-vibration-energy dashboards displace standalone sensor vendors in Dutch process industries. |
Research Methodology
Desk research of IEC and NEMA regulatory filings, customs trade databases, and SEC industrial equipment disclosures preceded structured interviews with plant maintenance directors, OEM procurement teams, aftermarket service heads, and power electronics distribution channel partners. Primary fieldwork captured specification requirements across German automotive, Chinese EV battery, and United States food processing facilities. Bottom-up unit economics triangulated against top-down market sizing from industrial automation capex flows.
Variance decomposition across product type, technology tier, application intensity, and end-user procurement concentration shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle compression rates and efficiency mandate compliance timelines. Modeled inputs incorporated wind turbine generator monitoring adoption curves and semiconductor supply elasticity assumptions.
Forecasts assume regulatory continuity in EU Ecodesign, GB 18613, and BIS regimes; material policy shifts would require re-modeling compliance cost trajectories and certification timeline impacts. Semiconductor supply normalization and industrial electrification subsidy durability represent specific risk factors. Revision becomes warranted when power electronics lead time volatility crosses eighteen-week thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Voice Coil Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Automotive Sunroof Motor Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Separately Excited Motor Market
Electric Motor
Smart E-Drive Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Global Electric Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Torque Motor Market
Electric Motor
Traction Motors Market