
 Motorcycle Battery Market | 2026-2036
Motorcycle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Motorcycle Battery Market Intelligence
The bundling of smart chargers with advanced lithium-ion batteries is consolidating buyer preference towards complete power-management systems. GS Yuasa leverages its extensive OEM relationships to maintain a strong market position. Clarios competes on the basis of its global manufacturing footprint and distribution network. Shorai specializes in lightweight lithium-iron phosphate (LiFePO4) batteries for the performance and racing segments.
A motorcycle battery is a rechargeable energy storage device designed to provide the initial power for starting, lighting, and ignition (SLI) systems. These units typically operate at a nominal 12 volts and are engineered to withstand high vibration and varying temperatures. While lead-acid batteries maintain a large share in the replacement market for conventional two-wheelers, the lithium-ion battery type is the fastest-growing segment. This growth is directly tied to its adoption in new electric motorcycles and premium performance bikes.
The European Union's Battery Regulation, under the EU Green Deal, imposes strict recycling and carbon footprint reporting requirements. In the United States, the EPA enforces regulations governing the handling and disposal of lead-acid batteries. These frameworks influence material selection and end-of-life management for manufacturers. Decisions on investments in lithium-ion recycling infrastructure versus optimizing lead-acid supply chains will define competitive advantage.
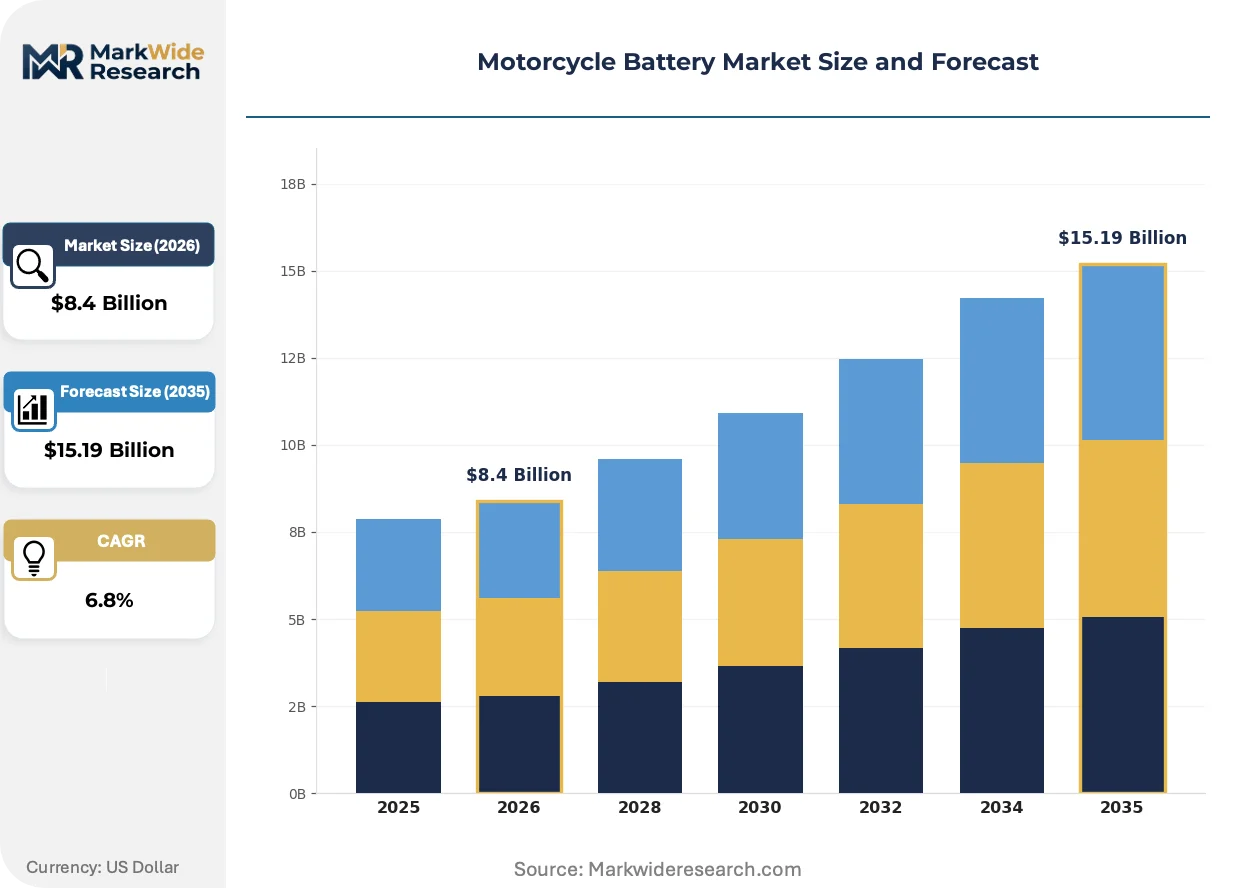
Market Dynamics
The fundamental dynamic shaping the motorcycle battery market is the technological and regulatory-driven transition from incumbent lead-acid batteries to advanced lithium-ion chemistries. This shift is most pronounced in the rapidly expanding electric motorcycle segment, creating distinct value chains and competitive pressures.
Growth Catalysts
- Lithium-Iron Phosphate (LiFePO4) Chemistry:The adoption of LiFePO4 batteries in performance and racing segments provides a significant catalyst due to their lighter weight, longer cycle life, and superior thermal stability compared to conventional options.
- Demand in Southeast Asia:High-volume two-wheeler markets, particularly in Vietnam and Indonesia, create sustained demand for cost-effective and durable batteries for both original equipment and replacement applications.
- EU Green Deal:The European Union's regulatory framework, specifically the Battery Regulation, pushes manufacturers toward designing batteries with lower carbon footprints and higher recyclability, favoring advanced and sustainable chemistries.
Market Restraints
- Input Cost Volatility:The price of lithium-ion batteries is highly sensitive to fluctuations in the global prices of raw materials like lithium and cobalt, creating margin pressure and pricing uncertainty for manufacturers.
- Supply Chain Concentration:A heavy concentration of lithium-ion cell manufacturing and raw material processing within China exposes the global supply chain to geopolitical risks and potential trade-related disruptions.
- Recycling Infrastructure Gap:The well-established and efficient recycling network for lead-acid batteries contrasts sharply with the nascent and more complex infrastructure required for recycling end-of-life lithium-ion units.
Strategic Opportunities
- Battery Swapping Services:Developing and deploying battery swapping stations for electric scooters and motorcycles presents an opportunity to create recurring revenue streams and address consumer concerns about charging times.
- Emerging Markets in India:India's strong government push for vehicle electrification, including the PLI scheme, opens significant opportunities for battery manufacturers targeting the country's massive two-wheeler market.
- Integrated Power Systems:The development of smart batteries with integrated Battery Management Systems (BMS) and IoT connectivity for diagnostics and predictive maintenance offers a path for product differentiation and higher value capture.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers face the challenge of navigating a fragmented landscape of environmental and safety regulations, such as the EU's Battery Regulation and the EPA's rules in the United States.
- Lack of Standardization:The absence of universal standards for battery form factors, voltages, and charging connectors in the electric motorcycle segment complicates product development and limits interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motorcycle Battery Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lead Acid, Lithium-Ion, Nickel-Metal Hydride, Gel, AGM Application: Two-Wheelers, Scooters, Dirt Bikes, Electric Motorcycles, Enduro Bikes Charging Technology: Standard Charger, Smart Charger, Fast Charger, Solar Charger, USB Charger End User: Dealerships, Service Centers, Rental Operators, Courier Services, Individual Owners |
| Companies Covered | GS Yuasa, Clarios, Yuasa Battery, Mighty Max Battery, East Penn Manufacturing, Odyssey Battery, Exide Technologies, Shorai, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motorcycle Battery Market Strategic Shifts & Innovations
Technological convergence is redefining the motorcycle battery from a simple component into the core of an integrated power management system. This evolution is accelerated by regulatory mandates focused on sustainability and the circular economy, influencing material selection and product lifecycles.
Advanced cell chemistries are being developed to improve energy density and safety. The adoption of lithium-iron phosphate is growing rapidly in the aftermarket and performance segments due to its inherent stability. This technological shift is consolidating R&D investment away from mature lead-acid technologies and toward next-generation lithium-ion variants with enhanced performance characteristics.
The US EPA's enforcement of the Resource Conservation and Recovery Act (RCRA) continues to govern the handling of lead-acid batteries. This regulation imposes strict cradle-to-grave responsibilities on manufacturers and distributors, shaping reverse logistics and core charge programs. The aftermarket for conventional motorcycles is most affected, reinforcing the established infrastructure for collecting and recycling lead-acid units.
Riders are increasingly purchasing batteries as part of a complete power management kit that includes a compatible smart charger. This behavioral shift disrupts the traditional component-based aftermarket channel, favoring brands that offer a fully integrated and warrantied system. This trend is most visible in the North American and European touring and performance segments, where reliability is paramount.
Motorcycle Battery Market Segmentation
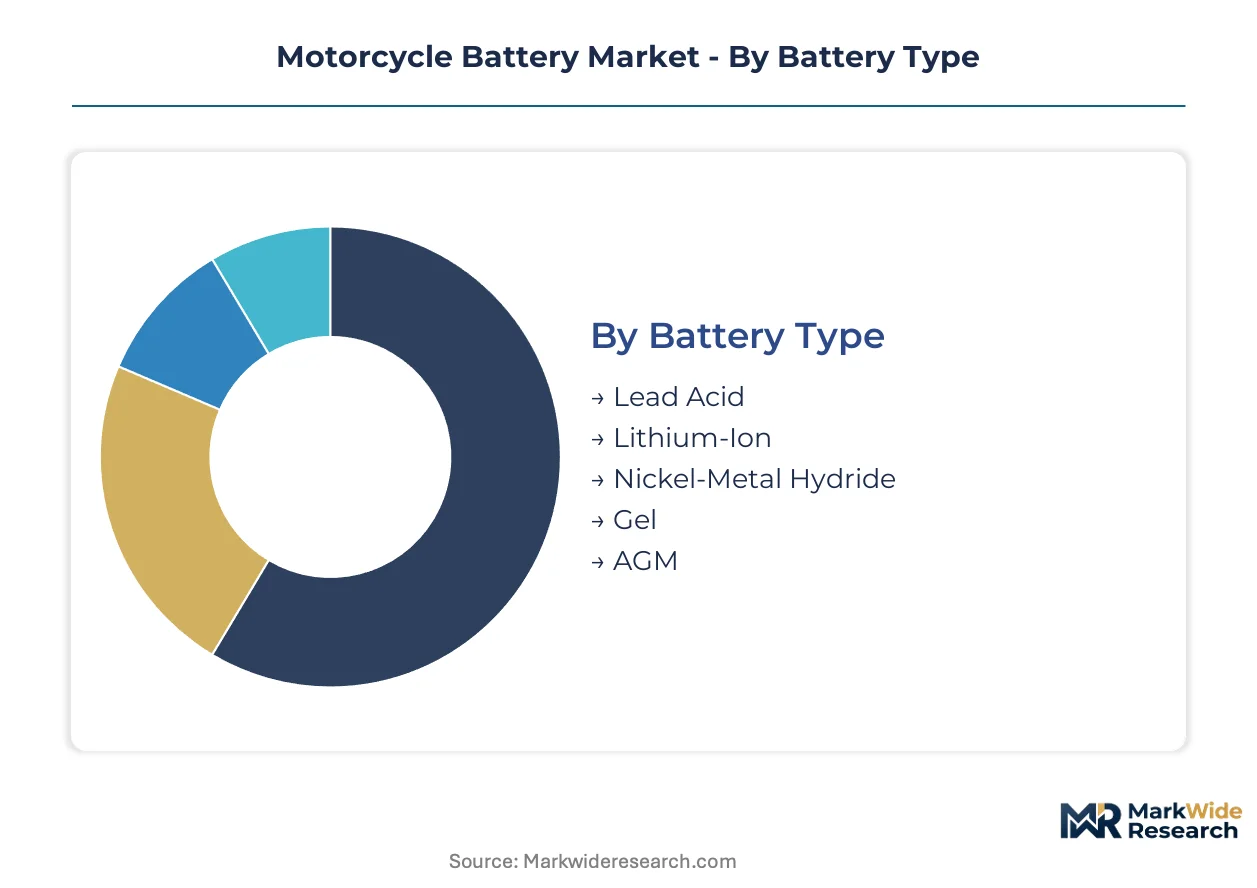
The motorcycle battery market exhibits diverse segmentation, reflecting varied technological requirements, application demands, and end-user preferences. Understanding these distinct segments is crucial for manufacturers to tailor product development, optimize distribution strategies, and capture specific value pools. This granular analysis provides a clear picture of where growth is concentrated and where competitive pressures are most acute.
Battery Type:
Manufacturing different battery chemistries demands varying capital investments, influencing market entry and production scale.
- Lead Acid:These batteries rely on lead plates and sulfuric acid electrolyte, offering a cost-effective solution for conventional internal combustion engine motorcycles. Demand concentrates in the replacement market for high-volume two-wheelers across Southeast Asia due to their established infrastructure and lower initial cost.
- Lithium-Ion:Utilizing lithium compounds, these batteries provide superior energy density, lighter weight, and longer cycle life compared to traditional chemistries. Adoption is accelerating in new electric motorcycles and premium performance bikes, driven by performance demands and environmental regulations.
- Nickel-Metal Hydride:These batteries offer a balance of energy density and cost, finding niche applications in some hybrid or specialized electric vehicles.
- Gel:Gel batteries use a silica-gel electrolyte, providing improved vibration resistance and spill-proof characteristics, suitable for certain off-road or touring applications.
- AGM:Absorbed Glass Mat batteries feature electrolyte absorbed in fiberglass mats, offering good cold-cranking performance and deep-cycle capabilities for diverse motorcycle models.
Lead Acid absorbs the bulk of installed capacity; Lithium-Ion is expanding most quickly.
Application:
Each application segment presents distinct performance requirements and operational environments for motorcycle batteries.
- Electric Motorcycles:These vehicles demand high-energy-density, fast-charging lithium-ion batteries to maximize range and performance. The segment's expansion is tied directly to government electrification initiatives and consumer environmental consciousness in markets like India.
- Two-Wheelers:This broad category includes standard commuter motorcycles and mopeds, primarily using lead-acid batteries for starting, lighting, and ignition functions. High-volume markets in Vietnam and Indonesia drive consistent demand for durable and affordable units.
- Scooters:Scooters require compact and reliable batteries, often prioritizing size and weight for urban mobility.
- Dirt Bikes:Batteries for dirt bikes must withstand extreme vibrations and harsh off-road conditions, favoring robust and lightweight designs.
- Enduro Bikes:Enduro bikes, used for long-distance off-road riding, need batteries that balance starting power with consistent energy delivery under varied terrains.
Two-wheelers continue to drive significant volume, while Electric Motorcycles exhibit the steepest expansion trajectory.
Charging Technology:
Charging technology differentiation increasingly influences consumer purchasing decisions, extending beyond mere battery capacity.
- Smart Charger:These chargers feature microprocessors that monitor battery conditions, optimizing the charging cycle to extend battery life and prevent overcharging. They are frequently bundled with advanced lithium-ion systems, particularly in North American and European performance segments.
- Fast Charger:Designed to significantly reduce charging times, fast chargers deliver higher current and voltage to compatible battery systems. The demand for faster charging is a key driver for electric motorcycle adoption, addressing range anxiety for riders.
- Standard Charger:Basic chargers provide a consistent current without advanced monitoring, commonly used for lead-acid batteries in the aftermarket.
- Solar Charger:Utilizing photovoltaic panels, solar chargers offer off-grid charging solutions, appealing to adventure riders and remote applications.
- USB Charger:These compact chargers provide low-power charging for smaller motorcycle batteries or auxiliary devices, offering convenience for riders.
Standard chargers remain foundational, but smart chargers are rapidly integrating into complete power management systems.
End User:
The end-user landscape dictates specific distribution channels and service support models for motorcycle battery suppliers.
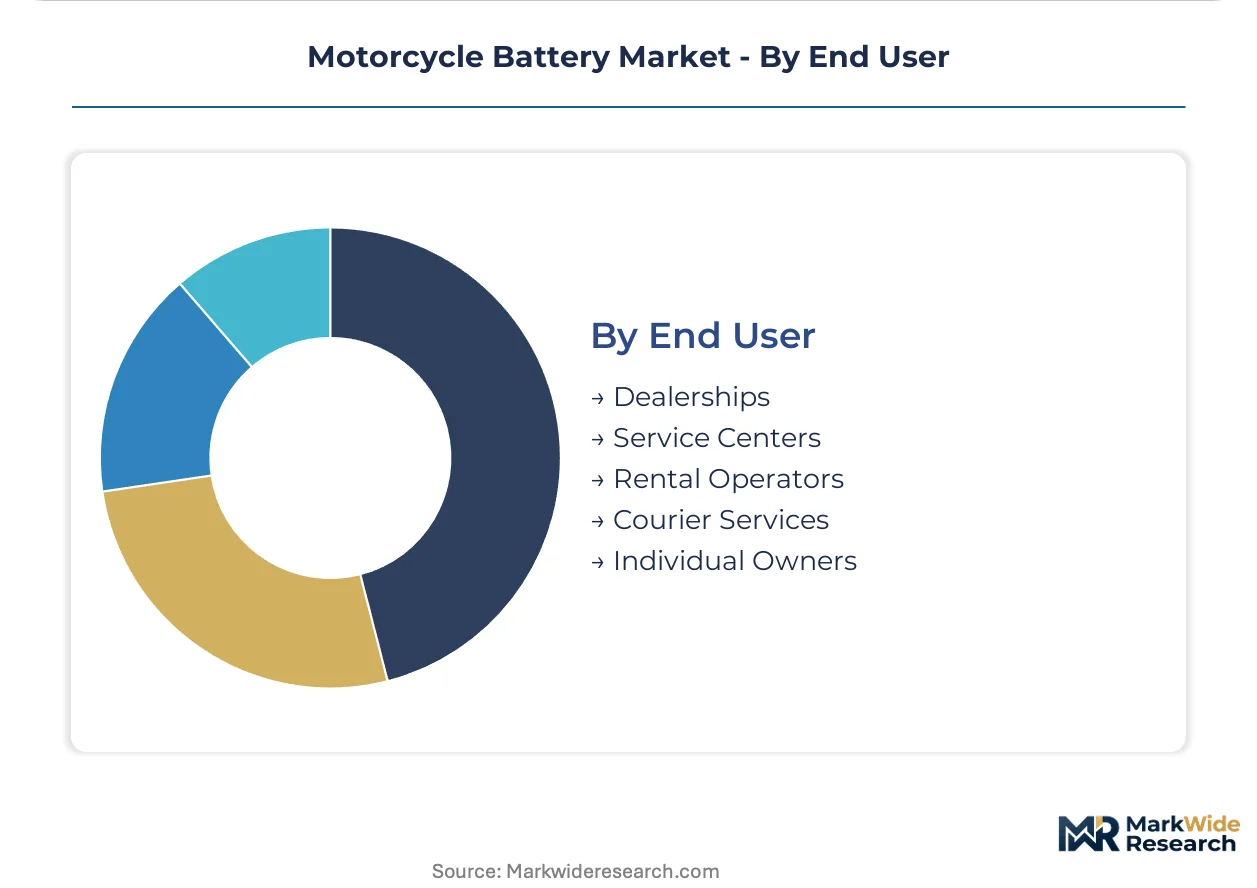
- Individual Owners:This segment represents the largest direct consumer base, purchasing batteries for replacement, upgrade, or maintenance of their personal motorcycles. Online retail platforms and aftermarket stores serve this broad demographic.
- Dealerships:Motorcycle dealerships serve as primary points of sale for original equipment batteries in new vehicles and offer brand-specific replacement units. GS Yuasa leverages extensive OEM relationships within this channel.
- Service Centers:Independent and authorized service centers provide battery diagnosis, replacement, and installation services, catering to a wide range of motorcycle makes and models.
- Rental Operators:Companies managing fleets of rental motorcycles or scooters require durable, long-lasting batteries with predictable performance and efficient swapping capabilities.
- Courier Services:Fleet operators for delivery and courier services demand highly reliable, high-cycle-life batteries to minimize downtime for their intensive daily operations.
Individual Owners represent the broadest market reach, with Dealerships maintaining influence over new vehicle sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive (PLI) scheme for vehicle electrification drives significant investment in battery manufacturing, establishing the country as a key hub. This government initiative stimulates domestic production and fosters a competitive environment for battery suppliers. Global manufacturers are targeting this region to establish localized supply chains.
India
Demand for electric two-wheelers in India is surging due to urban congestion, rising fuel costs, and environmental awareness. The Indian government's PLI scheme offers substantial financial incentives for advanced battery production. Manufacturing hubs in Maharashtra and Gujarat are rapidly expanding their capacities for lithium-ion cell assembly and battery pack integration.
Vietnam
Vietnam's rapidly expanding two-wheeler market creates sustained demand for cost-effective and durable batteries for new vehicles and replacements. The national government actively promotes electric vehicle adoption through targeted tax breaks and charging infrastructure development. Ho Chi Minh City's industrial zones are witnessing increased investment in battery assembly plants for local consumption.
Indonesia
Indonesia's vast two-wheeler fleet fuels a consistent replacement market for lead-acid batteries, alongside a rapidly growing electric demand. The Indonesian government actively supports local battery production, aiming to leverage its abundant nickel reserves for EV battery components. Jakarta and surrounding areas are quickly becoming pivotal centers for battery distribution and comprehensive service networks.
Germany
German consumers prioritize high-performance and sustainable battery solutions for premium motorcycles, particularly in touring and e-bike segments. The EU Battery Regulation, a core component of the EU Green Deal, mandates strict environmental and recycling standards. Stuttgart and Munich-based automotive suppliers are investing heavily in advanced lithium-ion research and development facilities.
United States
Demand for lightweight lithium-ion batteries in the performance and racing segments is particularly strong across the United States. The US EPA enforces comprehensive regulations governing the handling and disposal of lead-acid batteries. California's stringent emissions standards consistently drive innovation in electric motorcycle battery technology and charging infrastructure.
Motorcycle Battery Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the motorcycle battery market. The market exhibits a tiered structure, with established players dominating the conventional lead-acid segment. Niche innovators are rapidly gaining traction in advanced lithium-ion chemistries for performance applications. Strategic archetypes include global OEM suppliers, aftermarket specialists, and technology-driven disruptors. Companies are pursuing portfolio diversification and strategic partnerships to expand their market reach.
Among global OEM suppliers, GS Yuasa Corporation anchors a significant portion of the market through its extensive relationships with motorcycle manufacturers worldwide. Clarios International, a global manufacturer, represents another key player, leveraging its broad manufacturing footprint and robust distribution network to serve diverse segments. Conversely, Shorai Inc., a US-based specialist, exemplifies the technology-driven segment by focusing on lightweight lithium-iron phosphate (LiFePO4) batteries for performance and racing applications. These companies collectively illustrate the varied approaches to market penetration, from broad-scale supply to highly specialized product offerings and advanced chemistry focus.
| Leading Market Players |
|---|
| GS Yuasa |
| Clarios |
| Yuasa Battery |
| Mighty Max Battery |
| East Penn Manufacturing |
| Odyssey Battery |
| Exide Technologies |
| Shorai |
| Bosch |
| Others |
Cost & Logistics Intelligence
Skilled labor concentration in Southeast Asian battery manufacturing influences cost structures. This influences the price differentiation between commodity lead-acid units and advanced lithium-ion systems across various applications.
Pricing Analysis
Premium pricing for short lead-time lithium-ion batteries reflects their higher performance and quicker market delivery. The market primarily operates on a per-unit transactional model, with some contract-based long-term off-take agreements for original equipment manufacturers. Price differentiation stems from performance characteristics like energy density and cycle life, alongside brand premium in specialized segments. Pricing softness for lead-acid batteries originates from intense competition in the replacement market. Individual owners purchasing for conventional two-wheelers are most price-sensitive, while performance segment buyers prioritize technology over cost.
Supply Chain Analysis
Availability of specialized labor in China and Southeast Asia supports extensive battery production and assembly. The global supply chain concentrates heavily on China for lithium-ion cell manufacturing, with Vietnam and Indonesia serving as key hubs for both assembly and lead-acid battery production. Raw material dependencies include lithium, cobalt, and nickel for advanced chemistries, alongside lead and sulfuric acid for traditional units. Geopolitical risks and potential trade disruptions represent a structural supply chain risk due to this concentration. Distribution operates through a hybrid model, combining direct OEM supply with extensive aftermarket networks for replacement units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motorcycle battery market is currently undergoing a consolidation phase. Regulatory pressures, specifically the EU Green Deal's stringent environmental standards, force out manufacturers unable to invest in sustainable chemistries and recycling infrastructure.
For Market Incumbents: To counter the displacement by advanced lithium-ion technologies, incumbents must deepen OEM relationships for new electric motorcycle platforms. Investing in lithium-ion manufacturing capacity, particularly LiFePO4, enables competition in performance segments. R&D in next-generation cell chemistries and integrated power systems provides a critical lever for long-term relevance. Expanding recycling capabilities for lithium-ion units also ensures compliance with evolving regulations.
For New Entrants and Emerging Players: Launch via direct-to-consumer online channels and specialist dealerships to target niche segments. Specialized, lightweight LiFePO4 batteries for performance and racing segments represent a significant white-space opportunity. Integrated power management systems with smart chargers for premium touring bikes also offer differentiation. The aftermarket in North America and Europe, focusing on enthusiast riders, remains the most penetrable segment for innovative products.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers with deep pockets and a long-term vision. The market offers sustained growth over the next decade due to the accelerating electrification trend. Acquisition targets should include innovators in battery management systems (BMS) or specialized lithium-ion cell manufacturers. Accelerated government incentives for electric two-wheelers in emerging markets like India serve as a critical signal to watch for inflection points.
| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Lithium Processing | Secures critical raw material supply against geopolitical risks and price volatility. |
| Battery Swapping Network Deployment | Addresses consumer range anxiety for electric scooter fleets and reduces charging times. |
| R&D in Solid-State Battery Chemistry | Positions for long-term technological leadership and superior safety characteristics. |
| Partnerships with Electric Motorcycle OEMs | Captures share in the rapidly expanding new vehicle segment and ensures design-in. |
| Investment in Li-ion Recycling Infrastructure | Ensures compliance with EU Battery Regulation and reduces material costs over time. |
Research Approach
Industry reports, company financial statements, and government policy documents formed the secondary backbone of this analysis. Primary interviews were conducted with battery manufacturers' R&D leads, electric vehicle OEM procurement managers, aftermarket distributors, and recycling facility operators. This approach combines qualitative insights with quantitative data, ensuring robust bottom-up and top-down triangulation.
Historical trendline analysis informed the initial market size estimations and growth projections across the modeling period. The analytical framework modeled segmentation dimensions including battery type, application, charging technology, end user, and regional market maturity. Compound annual growth rates were derived from historical trends and projected future adoption curves. Key industry-specific forecast inputs included electric vehicle penetration rates, raw material price forecasts, and regulatory compliance costs.
The model assumes a particular technology adoption path; alternative pathways for solid-state batteries would alter the outlook. Forecasts reflect assumptions regarding raw material availability and regulatory stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Outboard Electric Motors Market
Electric Motor
Global Automotive Onboard Charger Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Electric Drives Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Global Hub Motors Market
Electric Motor
Vibrator Motor Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Automotive ABS Motor Market