
 Garden Tool Lithium Battery Market | 2026-2036
Garden Tool Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Tool Lithium Battery Market Insights
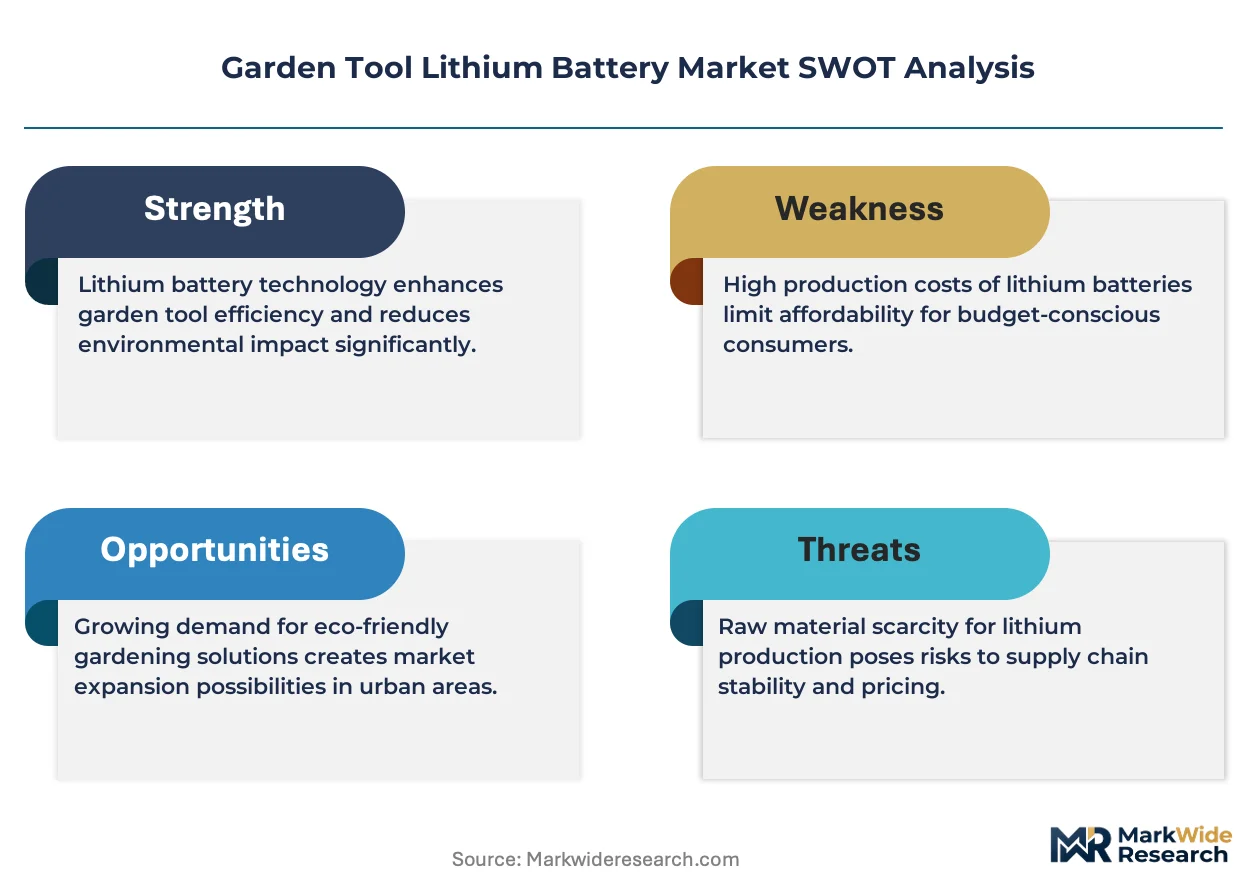
EPA small-engine emission standards is hardening the cost-of-entry calculus for new battery suppliers seeking commercial traction. STIHL leverages its captive dealer network to sustain replacement battery attach rates across professional-grade chainsaw lines. LG Chem anchors global cell supply through backward integration into cathode precursor production. Samsung SDI competes on high-discharge cell architectures purpose-built for brushless motor loads.
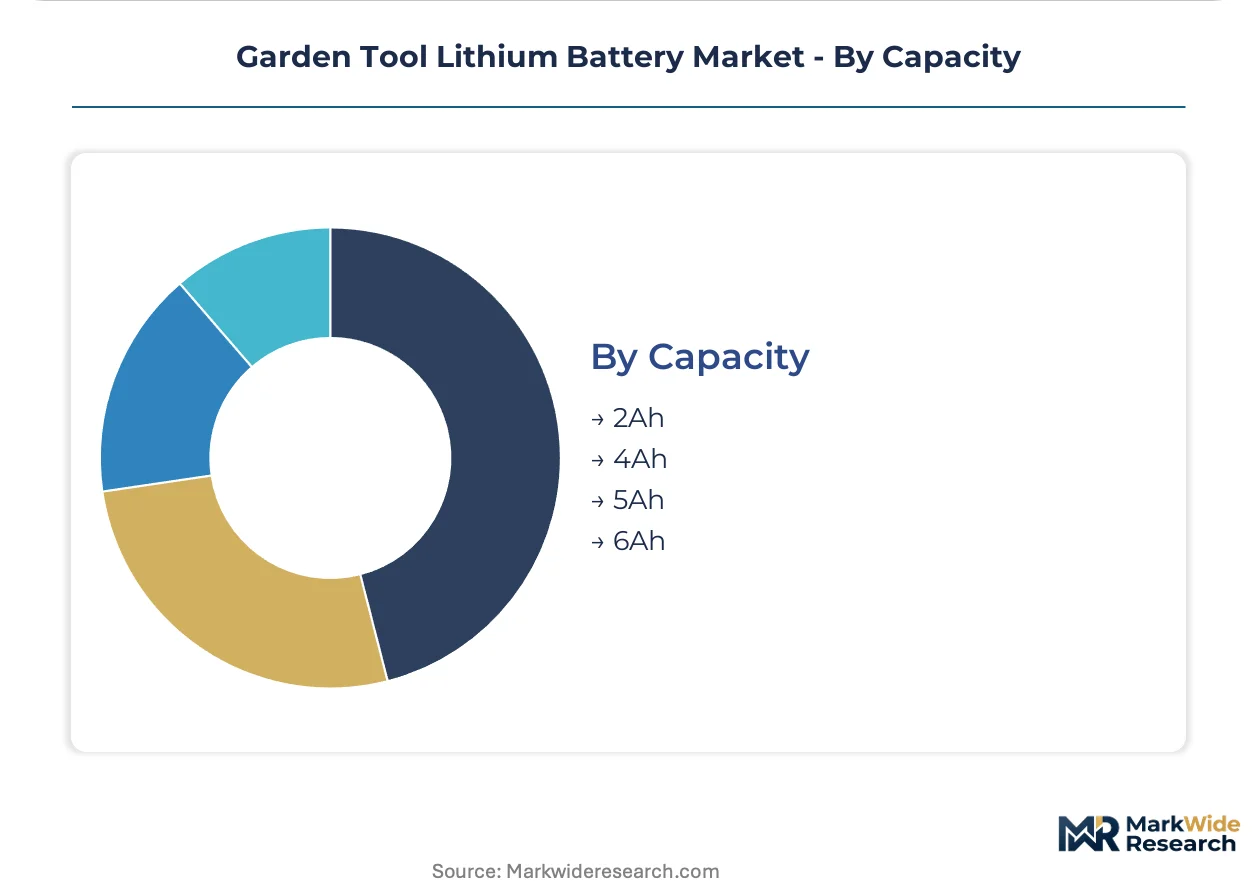
Garden tool lithium batteries are rechargeable electrochemical energy storage systems, typically employing nickel-manganese-cobalt or lithium iron phosphate cathode chemistries in cylindrical 18650 or 21700 form factors, engineered to deliver sustained 20-40 amp discharge rates for intermittent high-torque garden equipment operation. The product type dimension shows cordless tools and lawnmowers commanding the dominant installed base, while hedge trimmers and leaf blowers represent faster conversion pockets as homeowners complete partial fleet electrification. Capacity stratification reveals 4Ah and 5Ah packs capturing the bulk of mid-tier homeowner demand, with 6Ah configurations penetrating commercial landscaper segments where runtime per charge directly determines crew productivity economics.
OSHA workplace noise exposure limits and EPA Phase 3 small-engine emission rules collectively constrain gas-powered equipment viability in commercial settings, expanding addressable demand for compliant electric alternatives. The EU F-Gas Regulation and REACH chemical compliance frameworks impose parallel substance restrictions on battery supply chains serving European OEMs. Stakeholders must monitor evolving state-level equipment mandates and chemistry disclosure requirements to anticipate which cell formulations will retain market access.
Market Dynamics
EPA Phase 3 small-engine emission rules and parallel state-level equipment bans are structurally eliminating gas-powered alternatives from commercial landscaping, forcing fleet operators to absorb electrification costs and reconfigure crew deployment around battery runtime economics.
Growth Catalysts
- OSHA workplace noise exposure limits:Commercial crews in the United States face 85 decibel thresholds that gas equipment routinely breaches, mandating hearing protection or equipment substitution.
- Suburban municipality electrification mandates:Park districts and groundskeeping departments across the United States are specifying battery-only procurement for new equipment acquisitions.
- Lithium iron phosphate cathode chemistry:Improved thermal stability and cycle life are extending pack durability for intermittent high-torque applications like chainsaws and brush cutters.
Market Restraints
- Cobalt and lithium carbonate price volatility:Cathode precursor costs swing with mining output and refining capacity, compressing pack margins for mid-tier suppliers.
- Cell supply concentration in East Asian manufacturing:Cylindrical 21700 and 18650 production clusters heavily in South Korea and China, exposing OEMs to logistics disruption and tariff exposure.
- Gas equipment residual value collapse:Accelerated regulatory obsolescence is stranding commercial fleet investments before depreciation schedules complete.
Strategic Opportunities
- Commercial landscaper battery-as-a-service models:Fleet operators in the United States are testing subscription runtime packages that unbundle capital expenditure from operational deployment.
- EU F-Gas Regulation compliance positioning:REACH chemical disclosure and substance restriction frameworks favor cell suppliers with transparent precursor sourcing and recycling certification.
- Smart battery management system integration:IoT-enabled charge state monitoring and predictive maintenance alerts are converging with fleet telematics platforms.
Industry Challenges
- Brushless motor controller firmware integration:Pack electronics must communicate fault tolerance protocols across proprietary OEM motor architectures, extending qualification timelines.
- UL 2580 and IEC 62660 certification backlog:Third-party safety testing capacity constraints are delaying new pack introductions by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Tool Lithium Battery Market |
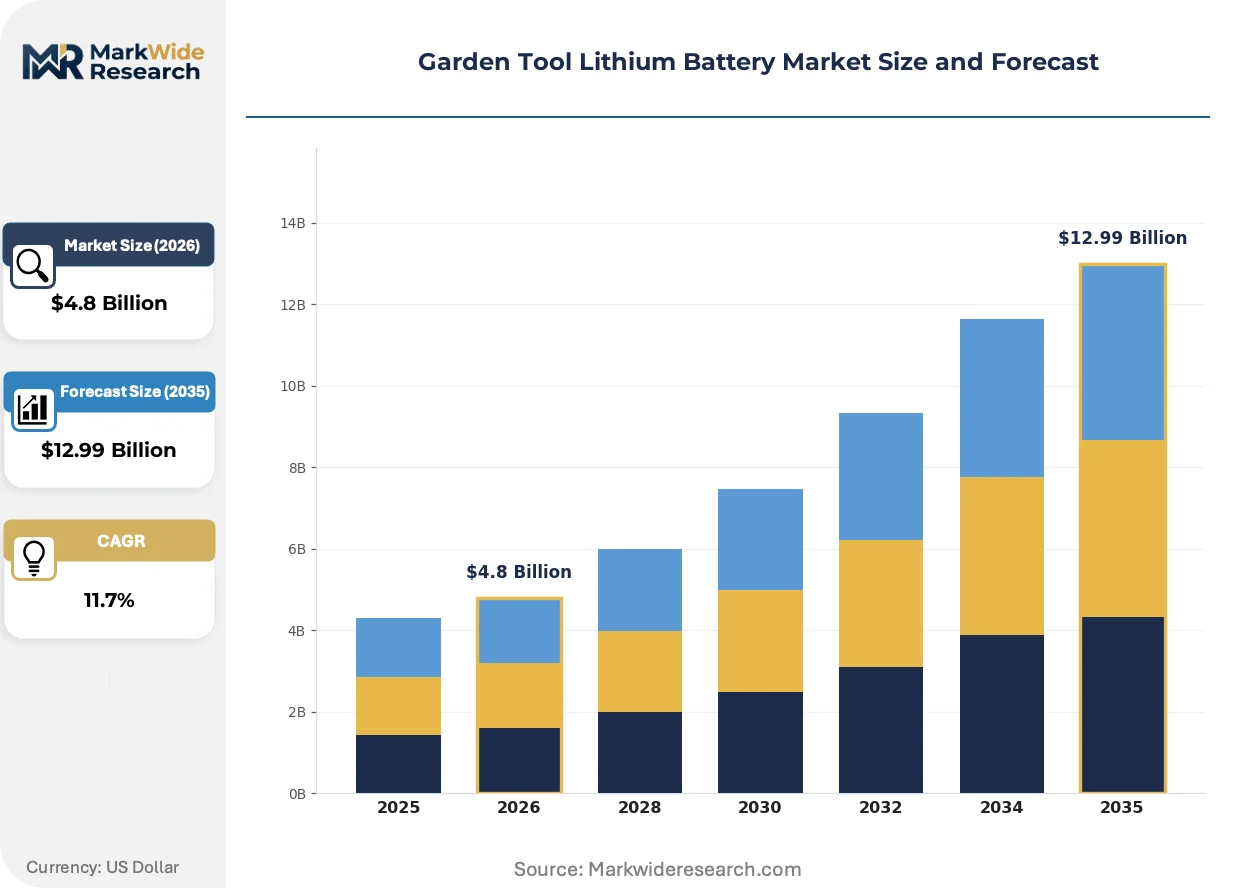
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Tools, Hedge Trimmers, Lawnmowers, Leaf Blowers End User: Homeowners, Landscapers, Garden Centers, Commercial Users Technology: Li-ion Batteries, LiPo Batteries, Fast Charging Technology, Solar-assisted Capacity: 2Ah, 4Ah, 5Ah, 6Ah |
| Companies Covered | STIHL, LG Chem, Husqvarna, DeWalt, Panasonic, Bosch, Samsung SDI, Greenworks, Makita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Tool Lithium Battery Market Trends and Innovations
Silicon-anode formulations and solid-state electrolyte research are pushing energy density boundaries while regulatory pressure compresses development timelines for compliant next-generation packs.
Silicon-composite anode technology is expanding into high-discharge garden tool applications by replacing graphite with silicon oxide blends that boost capacity per cell. Professional-grade chainsaw and lawnmower OEMs in the United States are piloting these cells for extended runtime without pack weight penalties. The technology is expanding into premium product tiers where runtime per charge directly determines crew productivity metrics and contract bidding competitiveness.
EPA small-engine emission standards are hardening compliance thresholds for new gas equipment certification, effectively freezing development investment in two-stroke combustion platforms. Landscaping fleet operators face accelerated depreciation on existing gas assets and compressed replacement cycles. The United States commercial segment is responding by consolidating purchase orders around fewer electric OEMs with proven battery supply chains.
Direct-to-fleet procurement models are bypassing traditional dealer networks as large landscaping companies negotiate volume pricing and standardized pack architectures. Equipment lessors and national maintenance contractors are displacing independent retail channels for commercial-grade battery systems. This pattern is most visible in the United States where regional fleet operators command sufficient scale to justify custom pack specifications and dedicated field service agreements.
Garden Tool Lithium Battery Market Segmentation
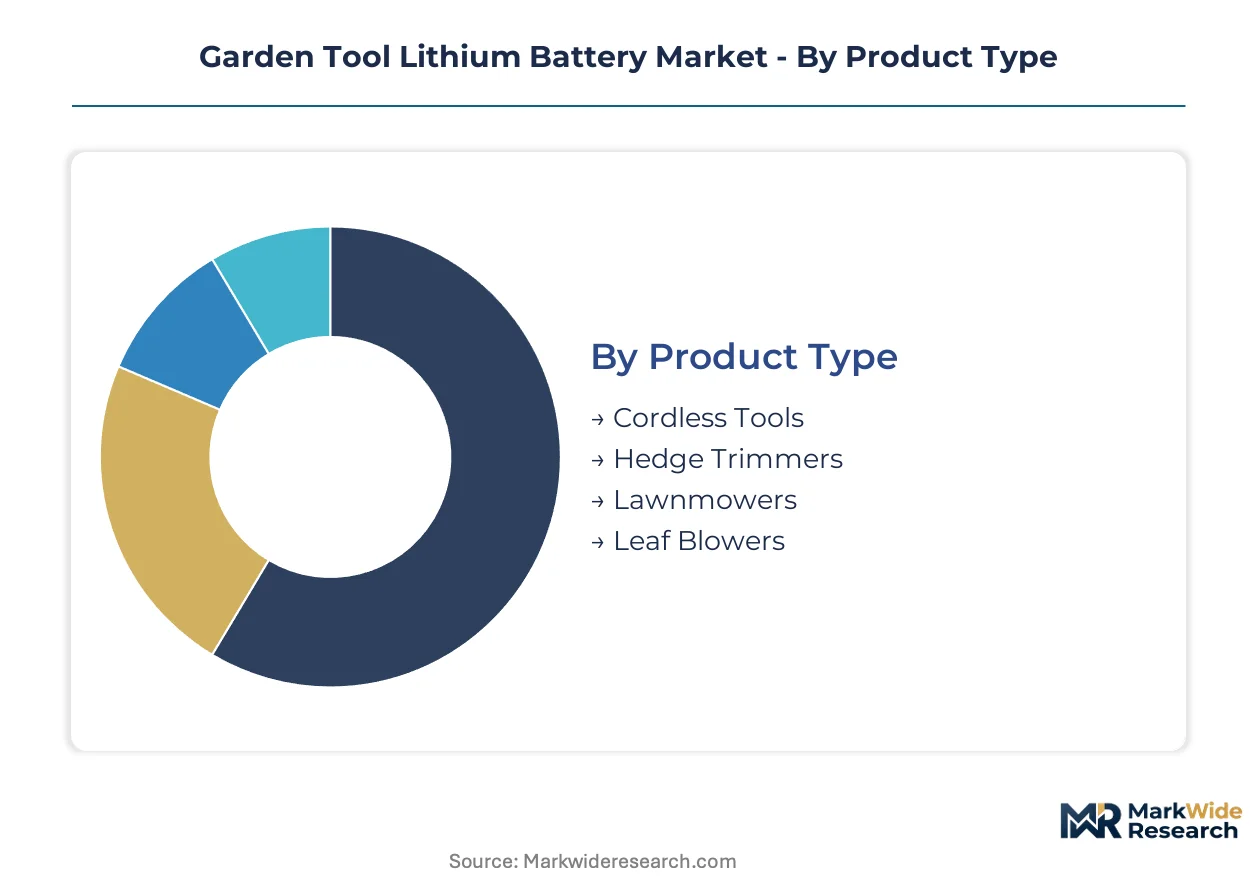
Segmentation in garden tool lithium batteries reveals how pack architectures align with distinct runtime requirements and duty cycles. Supply chain configuration varies sharply across these dimensions, with cylindrical cell sourcing and BMS firmware integration creating divergent cost structures for each segment cluster.
Product Type:
Cylindrical cell allocation concentrates in cordless tool and lawnmower platforms where 21700 form factor standardization drives procurement scale.
- Cordless Tools:These systems employ 18650 and 21700 cylindrical cells in 4Ah-5Ah configurations, with nickel-manganese-cobalt cathodes dominating mid-tier homeowner demand. Landscapers in suburban United States municipalities specify these packs for intermittent high-torque applications where OSHA noise compliance mandates electric alternatives.
- Lawnmowers:Riding and push mower platforms require 6Ah+ multi-cell arrays with sophisticated thermal management. Commercial fleet operators in the United States absorb higher pack costs to secure runtime economics that determine crew productivity and contract bidding viability.
- Hedge Trimmers:Compact 2Ah-4Ah packs serve residential trimming cycles with lighter weight profiles. EPA Phase 3 emission rules accelerate conversion from two-stroke gas units in noise-sensitive United States jurisdictions.
- Leaf Blowers:High-discharge 4Ah-5Ah configurations address sustained blower motor loads. United States park districts specify these for groundskeeping fleets under municipal electrification mandates.
Today's leader: Lawnmowers. Tomorrow's challenger: Leaf Blowers.
End User:
Customer type determines pricing architecture and field service requirements, with commercial segments demanding battery-as-a-service models that residential buyers reject.
- Homeowners:Price-sensitive buyers purchasing 4Ah packs through retail channels for intermittent weekend use. United States suburban households complete partial fleet electrification, prioritizing hedge trimmers and leaf blowers over capital-intensive lawnmower platforms.
- Landscapers:Professional crews in the United States negotiate volume pricing and standardized pack architectures through direct-to-fleet procurement. OSHA workplace noise exposure limits and EPA emission standards force complete gas fleet replacement, compressing depreciation schedules.
- Garden Centers:Institutional buyers specifying battery-only equipment for demonstration and rental fleets. These operators in the United States face compressed margins from stranded gas inventory.
- Commercial Users:National maintenance contractors and equipment lessors demanding IoT-enabled BMS integration with fleet telematics. United States regional operators justify custom pack specifications and dedicated service agreements at sufficient scale.
Commercial Users capture margin expansion. Homeowners face price compression.
Technology:
Cathode chemistry and cell format decisions cascade through thermal stability, cycle life, and qualification timeline trade-offs.
- Li-ion Batteries:Nickel-manganese-cobalt cylindrical cells anchor professional-grade applications with proven 500+ cycle durability. United States OEMs qualify these through UL 2580 certification for chainsaw and brush cutter platforms.
- LiPo Batteries:Pouch cell architectures enable form factor flexibility for compact handheld tools. Weight-sensitive applications in the United States residential segment adopt these despite higher fire suppression requirements.
- Fast Charging Technology:Silicon-anode formulations and advanced BMS algorithms reduce downtime for commercial crews. United States fleet operators pilot these systems where runtime per charge determines contract economics.
- Solar-assisted:Trickle-charge integration for remote maintenance applications and off-grid residential use. United States park districts in sunbelt states evaluate these for isolated groundskeeping stations.
Li-ion Batteries defend installed base. Fast Charging Technology gains qualification momentum.
Capacity:
Ah ratings segment procurement tiers, with 4Ah and 5Ah packs commanding mid-market volume while 6Ah configurations penetrate commercial productivity economics.
- 2Ah:Entry-level packs for lightweight hedge trimmers and occasional homeowner use. United States retail channels move these at price points that compress supplier margins.
- 4Ah:The workhorse configuration for residential cordless tool platforms. United States homeowners completing partial fleet electrification concentrate demand here for runtime-cost balance.
- 5Ah:Extended runtime for serious residential users and small commercial crews. United States landscapers with limited scale specify these to defer 6Ah capital outlay.
- 6Ah:Professional-grade arrays for lawnmowers and sustained-load applications. United States commercial fleet operators absorb premium pricing where runtime directly determines crew deployment efficiency and contract profitability.
4Ah commands volume leadership. 6Ah climbs the fastest on commercial conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial landscaping crews concentrate in suburban corridors across multiple continents, driving battery demand through municipal procurement mandates and OSHA-equivalent workplace standards. Regulatory pressure on small-engine emissions is reshaping fleet conversion timelines in every major market.
United States
Professional landscaping fleets in California, Florida, and Texas are absorbing electrification costs ahead of state-level equipment bans. EPA Phase 3 small-engine emission rules are structurally eliminating gas-powered alternatives from commercial groundskeeping contracts. The Dallas-Fort Worth metroplex anchors demand for 6Ah lawnmower arrays where runtime economics determine crew deployment efficiency.
Germany
Commercial garden maintenance contractors in Bavaria and North Rhine-Westphalia face REACH chemical compliance frameworks that favor transparent battery supply chains. The EU F-Gas Regulation imposes parallel substance restrictions on cell formulations serving European OEMs. Stuttgart's industrial corridor hosts precision motor-controller manufacturers integrating German-engineered brushless systems with high-discharge packs.
China
Cell production clusters in the Yangtze River Delta and Pearl River Delta dominate cylindrical 18650 and 21700 output for export markets. MIIT dual carbon goals are accelerating domestic electrification of municipal maintenance fleets in Beijing and Shanghai. Shenzhen anchors BMS firmware development for smart battery management systems converging with fleet telematics.
Japan
Precision tool manufacturers in the Kanto region demand high-cycle-life cells for professional-grade hedge trimmers and brush cutters. METI industrial standards are hardening qualification thresholds for battery safety certification. Nagoya's automotive supplier ecosystem is cross-applying thermal management expertise to garden tool pack architectures.
United Kingdom
Park districts across Greater London and the Southeast are specifying battery-only procurement under municipal decarbonization programs. The UK Environment Agency's non-road mobile machinery regulations are compressing replacement cycles for commercial landscaping fleets. Birmingham's manufacturing belt hosts pack assemblers serving mid-tier homeowner demand through retail distribution channels.
Garden Tool Lithium Battery Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Consolidation pressure is concentrating share among vertically integrated cell suppliers and captive OEM battery divisions. The structure rewards players with backward integration into cathode precursor production and those with established dealer network lock-in. Capacity expansion and strategic partnerships represent the dominant competitive moves, with M&A activity targeting BMS firmware capabilities and regional pack assembly assets.
Within the diversified industrial tier, STIHL and Husqvarna exemplify equipment OEMs leveraging captive dealer networks to sustain replacement battery attach rates. LG Chem and Samsung SDI anchor the pure-play cell supplier vector, with South Korea-based operations concentrating cylindrical high-discharge production. Bosch occupies a position bridging both archetypes through its power tool division and automotive cell expertise.
| Leading Market Players |
|---|
| STIHL |
| LG Chem |
| Husqvarna |
| DeWalt |
| Panasonic |
| Bosch |
| Samsung SDI |
| Greenworks |
| Makita |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate benchmark prices cascade through cathode precursor contracts into tiered pack economics, compressing margins for mid-tier suppliers while vertically integrated cell manufacturers capture pricing power through captive material sourcing.
Pricing Analysis
Battery-as-a-service subscriptions are unbundling capital expenditure from runtime procurement for United States commercial landscapers, while transactional pack sales dominate residential channels. Price differentiation stems from UL 2580 certification tier and volume procurement scale, with fleet operators securing standardized architectures at preferential rates. Pricing pressure intensifies as stranded gas equipment liquidations flood secondary markets with depreciated capital. Homeowners exhibit acute price sensitivity at 4Ah entry points, whereas commercial crews absorb 6Ah premiums where runtime determines contract profitability.
Supply Chain Analysis
Cathode active material supply rests on South Korean and Chinese precursor refiners, with cylindrical cell output concentrating in the Yangtze River Delta and Pearl River Delta manufacturing clusters. Nickel-manganese-cobalt formulations and lithium carbonate feedstock draw from Australian mining operations and Chilean brine extraction. Single-source vulnerability in 21700 form factor production exposes OEMs to logistics disruption and tariff exposure. Distribution runs through captive dealer networks for equipment OEMs and direct-to-fleet channels for national landscaping contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Phase 3 small-engine emission rules compound regulatory pressure into sustained demand displacement, eliminating gas-powered alternatives from commercial landscaping viability and compressing fleet replacement cycles.
For Market Incumbents: Deepen backward integration into cathode precursor production to insulate margin structures from lithium carbonate volatility. Secure UL 2580 and IEC 62660 certification capacity ahead of qualification backlogs. Lock in dealer network exclusivity agreements to defend replacement battery attach rates against direct-to-fleet procurement erosion. For New Entrants and Emerging Players: Silicon-anode fast-charging architectures offer technology-first wedge positioning for premium commercial tiers underserved by incumbent NMC formulations. Target United States regional fleet operators with 50-200 crew scale lacking negotiating leverage for custom specifications. Deploy battery-as-a-service pilot programs to bypass capital expenditure barriers among mid-tier landscapers. For Investors and Strategic Acquirers: Asymmetric upside sits with BMS firmware specialists possessing IoT-enabled charge state monitoring and predictive maintenance capabilities. Long-term viability hinges on qualification timelines and chemistry disclosure transparency under REACH frameworks. Watch EPA enforcement intensity and state-level equipment ban acceleration as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captive material sourcing insulates LG Chem and Samsung SDI from lithium carbonate volatility. |
| Smart Battery Management System Development | IoT-enabled BMS integration converges with fleet telematics platforms for commercial users. |
| Direct-to-Fleet Procurement Channel Establishment | Bypasses traditional dealer networks for national landscaping contractors and equipment lessors. |
| Silicon-Anode Fast-Charging Qualification | Extends runtime without pack weight penalties for professional-grade chainsaw and lawnmower OEMs. |
| REACH Chemical Compliance Certification | Transparent precursor sourcing and recycling certification unlocks EU F-Gas Regulation market access. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and the United Kingdom, with primary inputs from each market cluster. The research combines structured interviews with OEM procurement directors, commercial fleet operators, cell supplier technical leads, and dealer network managers with secondary validation from EPA regulatory filings, EU ECHA substance databases, MIIT dual carbon policy documents, and customs trade flow records. Bottom-up pack shipment analysis triangulates against top-down equipment production estimates.
Granularity-level modeling operates at cathode chemistry, cell format, capacity tier, end-user segment, and regional regulatory cluster dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by runtime economics and fleet conversion timelines. Forecast inputs incorporate OSHA noise exposure limit enforcement patterns, state-level equipment ban adoption curves, and silicon-anode qualification momentum for fast-charging applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price volatility, tariff regime shifts, and solid-state electrolyte commercialization timelines. Forecasts reflect documented assumptions on regulatory enforcement intensity and cell supply concentration persistence. A small set of named triggers—EPA Phase 3 implementation acceleration, REACH substance restriction expansion, and cylindrical cell manufacturing geographic diversification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
France Alternating Current (AC) Motor Market
Electric Motor
Traction Motor Core Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Global Motor Soft Starter Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Global Motor Management Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
Two Wheeler Electric Starter Magnet Market
Electric Motor
Fluid Conveyance Products Motors Market