
 Automotive Seat Motor Market | 2026-2036
Automotive Seat Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Motor Market Outlook
Aftermarket service revenue for seat motor replacement and calibration is fragmenting across independent repair networks and authorized service channels. Robert Bosch GmbH leverages its integrated electronics-software stack to capture higher-margin diagnostics-linked motor sales. Mabuchi Motor Co., Ltd. anchors the volume tier with standardized DC motor platforms for mass-market seat tracks. Nidec Corporation differentiates through brushless motor architectures that reduce electromagnetic interference in premium cabin environments.
An automotive seat motor is a compact electromechanical actuator, typically rated between 12V and 24V DC, that converts electrical energy into precise linear or rotary motion to adjust seat position, angle, and support features. These motors employ worm gear reduction systems to achieve high torque output at low speeds while maintaining positional holding capability without continuous power draw. Recline motors and lumbar support motors concentrate margin pools because they require higher-precision position feedback and greater torque density than basic height adjustment units. Electric motor technology leads the technology segmentation due to OEM electrification roadmaps that favor electronically controlled seating over pneumatic alternatives, while mechanical systems persist in cost-sensitive commercial vehicle applications.
The EPA enforces material restrictions on heavy metals in motor housings through TSCA Section 6 rules, while NHTSA's FMVSS 302 flammability standard governs wire insulation and motor encapsulant selection in US-bound vehicles. The EU's REACH regulation and RoHS directive limit hazardous substances in seat motor supply chains, effectively screening non-compliant Asian suppliers from European OEM qualification programs. Stakeholders must monitor how emerging autonomous vehicle interior reconfigurations reshape motor count per seat and torque specification requirements.
Market Dynamics
Luxury vehicle seating systems are deepening their integration of multi-axis motors, compressing development cycles and forcing tier-one suppliers to consolidate mechatronic module production within premium European automotive clusters.
Growth Catalysts
- EU F-Gas Regulation:Tightening specifications for motor housings and lubricants are accelerating R&D investment in fluorinated-gas-free sealing technologies and bio-based lubricant formulations across German and Italian supplier bases.
- Autonomous interior reconfiguration:Self-driving vehicle architectures demand motors with higher torque density and redundant position feedback, expanding motor count per seat from two to six units in robotaxi programs.
- Brushless DC architectures:Nidec Corporation and Japanese competitors are displacing brushed motors in premium cabins, reducing electromagnetic interference that disrupts advanced driver-assistance sensor arrays.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings compress margins on high-torque brushless designs, forcing OEMs to dual-source magnet supply from Chinese and Australian mining operations.
- REACH compliance screening:The EU's substance restrictions effectively disqualify non-compliant Asian suppliers from European OEM qualification programs, concentrating qualified vendor pools in Germany, Japan, and South Korea.
- Pneumatic seating persistence:Cost-sensitive commercial vehicle segments in India and Brazil continue specifying pneumatic lumbar systems, capping electromechanical penetration in heavy-duty truck cabins.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive electronics are attracting seat motor manufacturers to establish localized brushless motor assembly for domestic OEMs and export markets.
- Aftermarket diagnostics integration:Robert Bosch GmbH's electronics-software stack enables predictive motor failure detection, creating attach-rate opportunities for replacement units through authorized service channels.
- Silicon carbide MOSFET convergence:Pairing wide-bandgap power electronics with brushless motor controllers reduces thermal management mass and enables higher switching frequencies for precision seat positioning.
Industry Challenges
- Mechatronics systems integration:Calibrating multi-motor seating modules with seatbelt pretensioners and occupant classification sensors extends validation timelines by eight to fourteen months for new vehicle platforms.
- Functional safety certification:ISO 26262 ASIL-B compliance for seat motors with memory positioning functions demands specialized firmware development capabilities scarce outside German and Japanese engineering centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Motor Market |
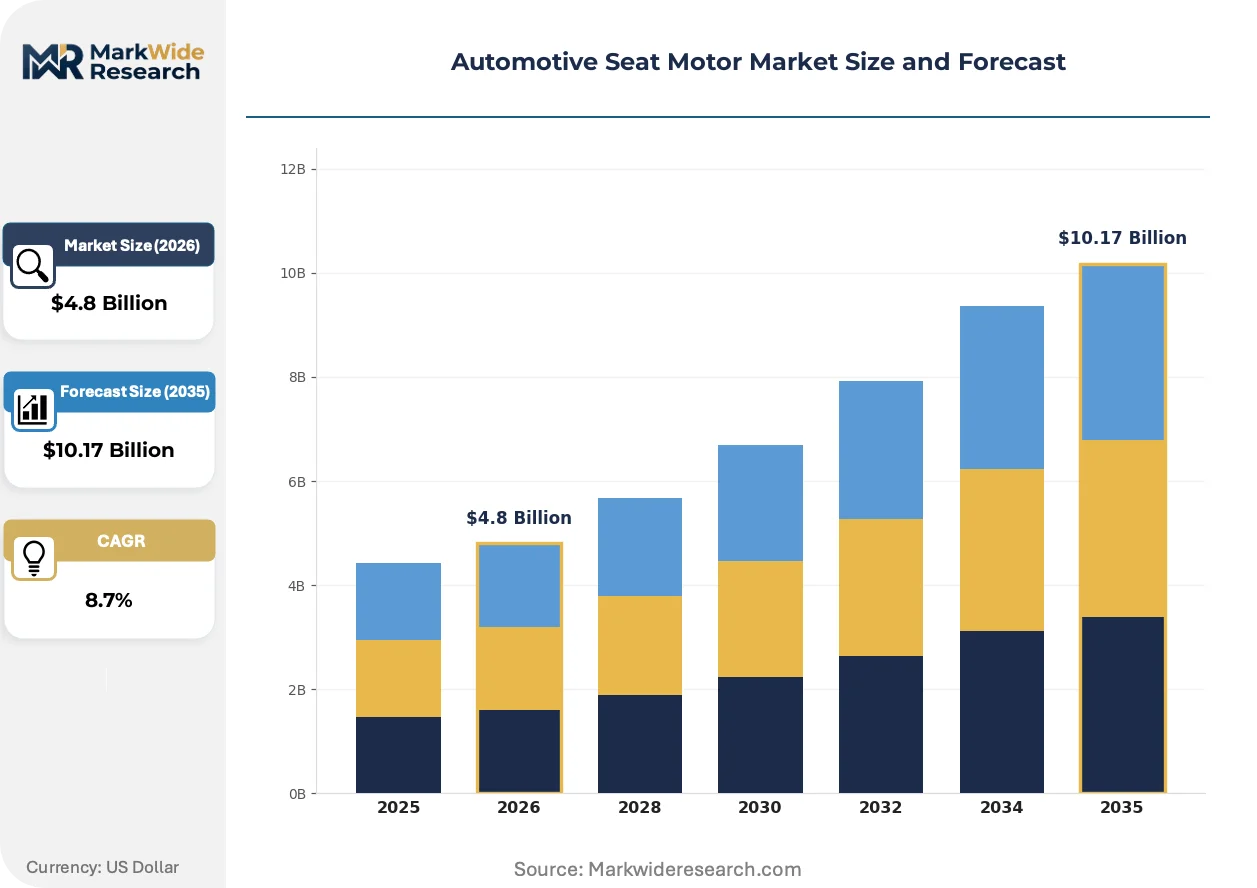
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forward Tilt Motor, Recline Motor, Lumbar Support Motor, Height Adjustment Motor End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Electric Motors, Pneumatic Systems, Hydraulic Systems, Mechanical Systems Application: Luxury Vehicles, Commercial Vehicles, Passenger Cars, Motorhomes |
| Companies Covered | Robert Bosch GmbH, Mabuchi Motor Co., Ltd., Nidec Corporation, ASMO, Brose Fahrzeugteile, Denso Corporation, Mitsuba Corporation, Shenghuabo Group, Johnson Electric Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Motor Market Strategic Shifts
Motor virtualization and predictive maintenance architectures are compressing hardware-software boundaries, while regulatory chemistry restrictions and shifting procurement accountability reshape supplier-OEM relationships.
Brushless DC motor technology is virtualizing traditional mechanical commutation through integrated gate drivers and field-oriented control algorithms. Premium German OEMs are adopting these architectures for massaging and active bolting seats, eliminating brush wear failures that drive warranty claims. This virtualization is compressing the serviceable motor aftermarket by embedding predictive health monitoring directly into motor control firmware.
The EU F-Gas Regulation and REACH directive are tightening material specifications for seat motor housings, wire insulation, and lubricants. Suppliers must reformulate encapsulant chemistries and validate alternative friction modifiers, extending qualification cycles by twelve to eighteen months. German premium OEMs are responding by consolidating sourcing with vertically integrated mechatronic module suppliers capable of in-house materials compliance testing.
Accountability for seat motor specification is migrating from tier-two component buyers to OEM seating system architects. Tier-one suppliers like Lear and Adient now contract directly with Mabuchi and Nidec for platform motors, disintermediating traditional automotive electrical distributors. This concentration is most visible in Stuttgart and Munich, where Mercedes-Benz and BMW seating engineering teams specify motor torque curves and CAN bus protocols at the component level.
Automotive Seat Motor Market Segmentation
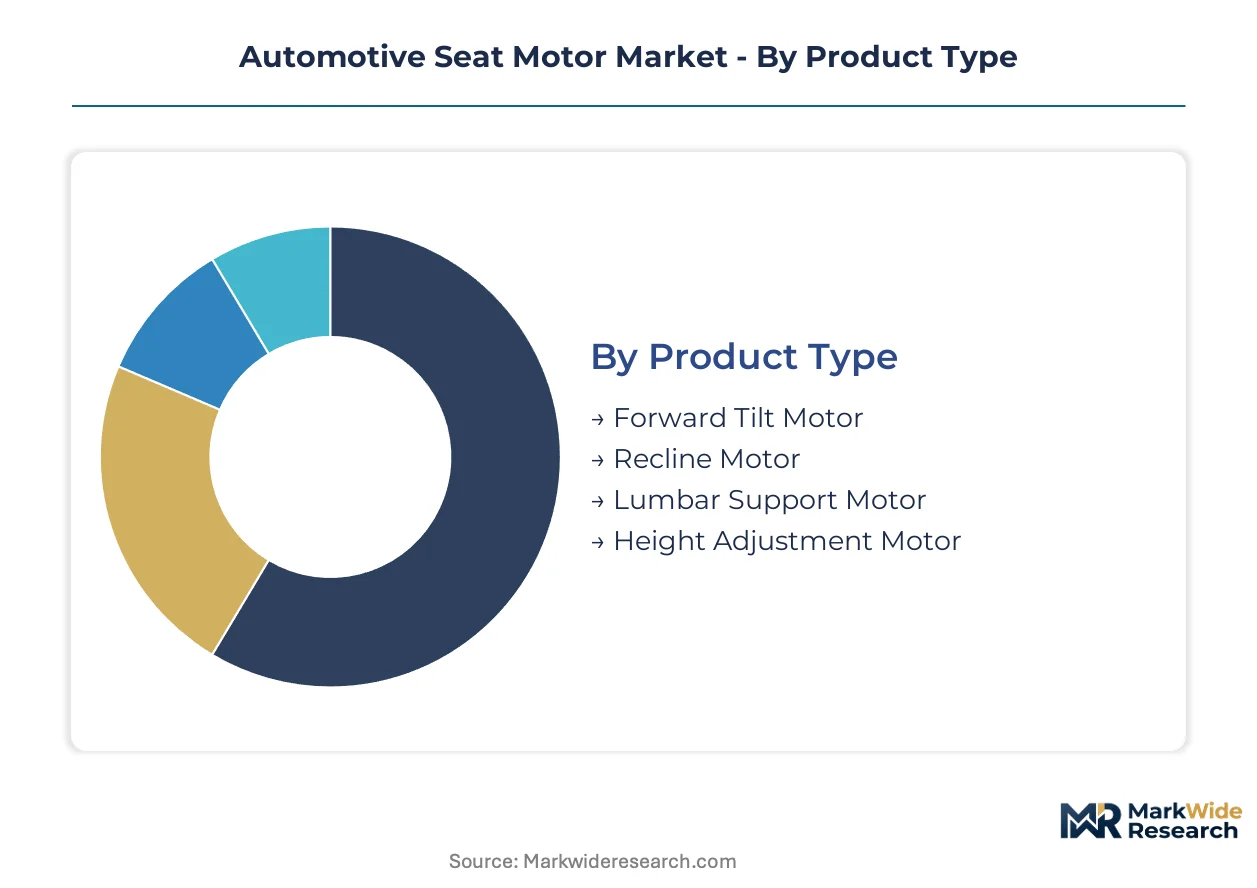
Segmentation in the automotive seat motor market reveals how torque density requirements, regulatory compliance burdens, and procurement accountability vary sharply across application tiers. Understanding these divides enables suppliers to align R&D spend with margin concentration zones.
Product Type:
Maturity spans from commodity track actuators to precision feedback-intensive modules commanding premium positioning.
- Forward Tilt Motor:Worm gear reduction systems deliver high torque at low speeds for seat base inclination. Demand clusters in German premium OEM programs where multi-axis seating architectures require synchronized tilt actuation.
- Recline Motor:Higher-precision position feedback mechanisms enable memory positioning and anti-pinch safety compliance. These units concentrate margin pools in Stuttgart and Munich engineering centers where ISO 26262 ASIL-B firmware development capabilities anchor qualification programs.
- Lumbar Support Motor:Compact bidirectional actuators with overload protection for ergonomic adjustment cycles.
- Height Adjustment Motor:Standardized DC platforms with basic positional holding capability dominate mass-market seat tracks.
Height Adjustment Motor retains volume leadership; Recline Motor holds the steepest expansion curve.
End User:
Procurement accountability is migrating downstream from traditional distribution channels toward direct OEM specification.
- OEMs:Seating system architects at Mercedes-Benz and BMW now specify motor torque curves and CAN bus protocols at the component level, disintermediating tier-two buyers. This concentration demands suppliers maintain in-house materials compliance testing for REACH and EU F-Gas Regulation adherence.
- Tier-1 Suppliers:Lear and Adient contract directly with motor specialists for platform motors, consolidating mechatronic module production within premium European automotive clusters. These relationships require eight to fourteen month validation timelines for multi-motor calibration with occupant classification sensors.
- Aftermarket Providers:Independent repair networks fragment service revenue across replacement and calibration offerings.
- Vehicle Assemblers:Contract manufacturers with limited seating engineering autonomy source pre-integrated modules.
OEMs command the specification hierarchy; Tier-1 Suppliers capture the deepest integration economics.
Technology:
Electrification roadmaps are compressing the addressable market for non-electric actuation technologies.
- Electric Motors:Brushless DC architectures with integrated gate drivers and field-oriented control algorithms are displacing brushed alternatives in premium cabins. Nidec Corporation and Japanese competitors reduce electromagnetic interference that disrupts advanced driver-assistance sensor arrays.
- Pneumatic Systems:Compressed air lumbar solutions persist in cost-sensitive commercial vehicle segments across India and Brazil, capping electromechanical penetration in heavy-duty truck cabins where CDSCO and BIS certification costs outweigh performance benefits.
- Hydraulic Systems:High-force actuation for specialized industrial vehicle seating applications with limited automotive adoption.
- Mechanical Systems:Manual adjustment mechanisms retain foothold in emerging market entry vehicle configurations.
Electric Motors anchor technology transition; Pneumatic Systems defend residual commercial vehicle niches.
Application:
Motor count per seat varies from two units in conventional architectures to six in autonomous interior reconfigurations.
- Luxury Vehicles:Multi-axis motors with massaging and active bolting functions demand redundant position feedback and higher torque density. German premium OEMs consolidate sourcing with vertically integrated mechatronic suppliers capable of predictive health monitoring firmware development.
- Passenger Cars:Volume production programs specify standardized DC motor platforms from Mabuchi Motor for cost-optimized seat tracks across mass-market nameplates.
- Commercial Vehicles:Pneumatic lumbar persistence and durability-focused specifications dominate heavy-duty cabin requirements.
- Motorhomes:Low-volume specialized seating configurations with customized actuation ranges.
Passenger Cars generate unit volume concentration; Luxury Vehicles drive specification escalation and margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese engineering clusters anchor the seat motor supply base, with premium OEM specification power concentrating in Stuttgart and Munich while volume manufacturing scales across Chinese coastal provinces.
Germany
Mercedes-Benz and BMW seating architects specify motor torque curves and CAN bus protocols directly at the component level, bypassing traditional tier-two distribution channels. The EU F-Gas Regulation and REACH directive enforce twelve-to-eighteen-month qualification cycles for housing materials and lubricant formulations. Stuttgart and Munich engineering centers host vertically integrated mechatronic suppliers capable of in-house compliance testing and ISO 26262 ASIL-B firmware development.
Japan
Nidec Corporation and Mabuchi Motor anchor brushless DC and standardized DC platforms respectively, serving both domestic OEMs and export markets across premium and mass-market tiers. METI industrial policy supports precision motor R&D through technology development grants. Nagoya and Osaka manufacturing corridors concentrate torque-dense actuator production for global seating module export.
China
Domestic OEM electrification roadmaps expand electronically controlled seating penetration beyond legacy pneumatic alternatives in commercial vehicle segments. MIIT GB standards and dual carbon goals accelerate local brushless motor assembly investment. Yangtze River Delta and Pearl River Delta clusters attract foreign joint ventures for mechatronic module localization serving regional automakers.
United States
NHTSA FMVSS 302 flammability standards govern wire insulation and motor encapsulant selection for US-bound vehicle programs. EPA TSCA Section 6 restrictions on heavy metals in motor housings shape supplier qualification requirements. Michigan and Ohio automotive corridors concentrate tier-one seating system integration facilities calibrating multi-motor modules with occupant classification sensors.
India
Production-linked incentive schemes for advanced automotive electronics attract seat motor manufacturers to establish localized brushless motor assembly for domestic OEMs and export markets. BIS certification requirements and CDSCO automotive component standards structure import substitution programs. Maharashtra and Gujarat industrial zones concentrate emerging tier-two supplier capacity for cost-optimized seat track actuators.
Automotive Seat Motor Market Competitive Environment
Vertically integrated mechatronic specialists and standardized motor fabricators split the market along specification complexity lines. Three archetypes dominate: German-Japanese engineering houses with in-house firmware capabilities, East Asian volume manufacturers with platform standardization expertise, and diversified automotive suppliers leveraging electronics-software integration. Competitive positioning sharpens through direct OEM contracting relationships and backward integration into magnet supply chains.
Among diversified automotive suppliers, Robert Bosch GmbH represents the electronics-software integration archetype, while Mabuchi Motor Co., Ltd. and Nidec Corporation exemplify the volume-platform and brushless-specialist positions respectively. These three anchors illustrate how procurement accountability migration toward direct OEM specification favors suppliers with either integrated diagnostics capabilities or torque-density leadership in electromagnetic interference-sensitive cabin environments.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Mabuchi Motor Co., Ltd. |
| Nidec Corporation |
| ASMO |
| Brose Fahrzeugteile |
| Denso Corporation |
| Mitsuba Corporation |
| Shenghuabo Group |
| Johnson Electric Holdings Limited |
| Others |
Value Chain & Pricing Dynamics
Stuttgart and Munich engineering clusters concentrate torque-dense brushless motor assembly capacity, concentrating pricing power with vertically integrated mechatronic suppliers capable of REACH-compliant materials testing and ISO 26262 firmware development. German premium OEMs now specify motor torque curves and CAN bus protocols directly, compressing tier-two margins while elevating component-level price realization for qualified vendors.
Pricing Analysis
EU F-Gas Regulation and REACH directive dictate the pricing tier structure across the European qualification landscape. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified brushless architectures with predictive health monitoring from basic DC track actuators and pneumatic alternatives. Price differentiation hinges on electromagnetic interference certification grade and volume scale commitments. Cost compression in mass-market DC platforms is intensifying because Mabuchi Motor anchors standardized supply with minimal customization. Fleet operators and commercial vehicle assemblers exhibit highest price sensitivity; German luxury OEM seating architects show lowest.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Robert Bosch GmbH and Nidec Corporation anchor working capital flows for tier-two winding and magnet suppliers. Manufacturing concentrates in Germany, Japan, and China, with Yangtze River Delta clusters scaling brushless assembly for domestic electrification roadmaps. Rare earth magnet supply draws from Chinese and Australian mining operations, tethering torque-dense motor costs to neodymium price volatility. Single-source vulnerability in magnet procurement represents structural risk. Distribution runs through direct OEM contracting and tier-one mechatronic module integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive seat motor market sits in early-cycle recovery as autonomous vehicle interior reconfigurations expand motor count per seat from two to six units, creating sustained demand elevation through the projection horizon.
For Market Incumbents: Harden firmware development capabilities around ISO 26262 ASIL-B compliance to defend against emerging brushless specialists from South Korea. Backward integration into rare earth magnet supply chains mitigates cost volatility compression. Channel control through authorized service diagnostics protects aftermarket replacement revenue from independent repair networks.
For New Entrants and Emerging Players: Build out localized brushless motor assembly capacity in Maharashtra and Gujarat industrial zones to capture India PLI scheme incentives for advanced automotive electronics. Cost-sensitive commercial vehicle segments in Brazil and India present the most penetrable white space, where pneumatic lumbar persistence caps electromechanical penetration. Target fleet operator direct procurement channels with predictive maintenance firmware bundles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated mechatronic specialists with in-house REACH compliance testing and gate driver integration capabilities. Long-term viability rests on suppliers capturing specification authority migration from tier-two buyers toward OEM seating architects. Monitor robotaxi program seat motor procurement announcements as inflection indicator for torque density demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Brushless DC Architecture Migration | Nidec Corporation reduces electromagnetic interference disrupting ADAS sensor arrays in premium cabins. |
| REACH Compliance Testing Integration | German suppliers extend qualification cycles twelve-to-eighteen months with in-house materials validation. |
| Predictive Maintenance Firmware Development | Robert Bosch GmbH embeds health monitoring to compress aftermarket service revenue fragmentation. |
| Rare Earth Magnet Dual-Sourcing | OEMs mitigate neodymium price volatility through Australian and Chinese supply chain diversification. |
| Direct OEM Contracting Concentration | Lear and Adient disintermediate electrical distributors by contracting Mabuchi for platform motors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across OEM seating system architects, tier-one mechatronic procurement leads, aftermarket distributor operations, and motor control firmware engineers. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA TSCA Section 6 filings, and EU ECHA substance restriction updates. Bottom-up unit volume modeling triangulated against top-down OEM platform content analysis.
Calibration across the analysis window employed vehicle class, propulsion architecture, content per vehicle, and regional production cluster segmentation. CAGRs derived from installed base growth, replacement cycle compression, and autonomous interior reconfiguration penetration curves. Rare earth magnet price volatility and REACH qualification timeline assumptions shaped margin trajectory inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese brushless specialists or accelerated robotaxi deployment would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
E-Bike Motor Market
Electric Motor
Trolling Motor Market
Electric Motor
Electric AC Motors Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
GCC Electric Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Hub Drive Motor Market
Electric Motor
EV Traction Motor Market
Electric Motor
Electric Vehicle Motor Shaft Market
Electric Motor
Electric Vehicle (EV) Traction Motor Market