
 United States AC Motor Market | 2026-2036
United States AC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
United States AC Motor Market Insights
Copper is rebalancing product economics as permanent magnet rare-earth dependencies face supply volatility and cost pressure. ABB leverages integrated drives-motor packages to sustain pricing power in high-horsepower industrial applications. Siemens anchors its position through digital twin diagnostics embedded in large synchronous motor lines. Regal Rexnord Corporation dominates fractional and medium horsepower distribution through extensive aftermarket channel control.
An AC motor converts alternating current into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at speeds governed by input frequency and pole count with efficiency ratings spanning IE1 through IE4 classes. Induction motors retain the largest installed base across manufacturing and HVAC end uses due to rugged construction and lower capital cost, while synchronous motors capture premium applications requiring precise speed control. Servomotors represent the fastest-expanding product category as automated packaging and robotics lines multiply in the Midwest and Southeast.
The Department of Energy enforces minimum efficiency standards under 10 CFR 431 that disqualify lower-tier motors from commercial sale, while NEMA MG 1 defines performance and testing protocols that manufacturers must satisfy for market access. OSHA electrical safety requirements and EPA industrial energy mandates compound compliance complexity for facility operators managing large motor fleets. Stakeholders must weigh total cost of ownership against first-cost tradeoffs as efficiency regulations tighten and utility rebate programs shift toward connected, condition-monitored motor systems.
Market Dynamics
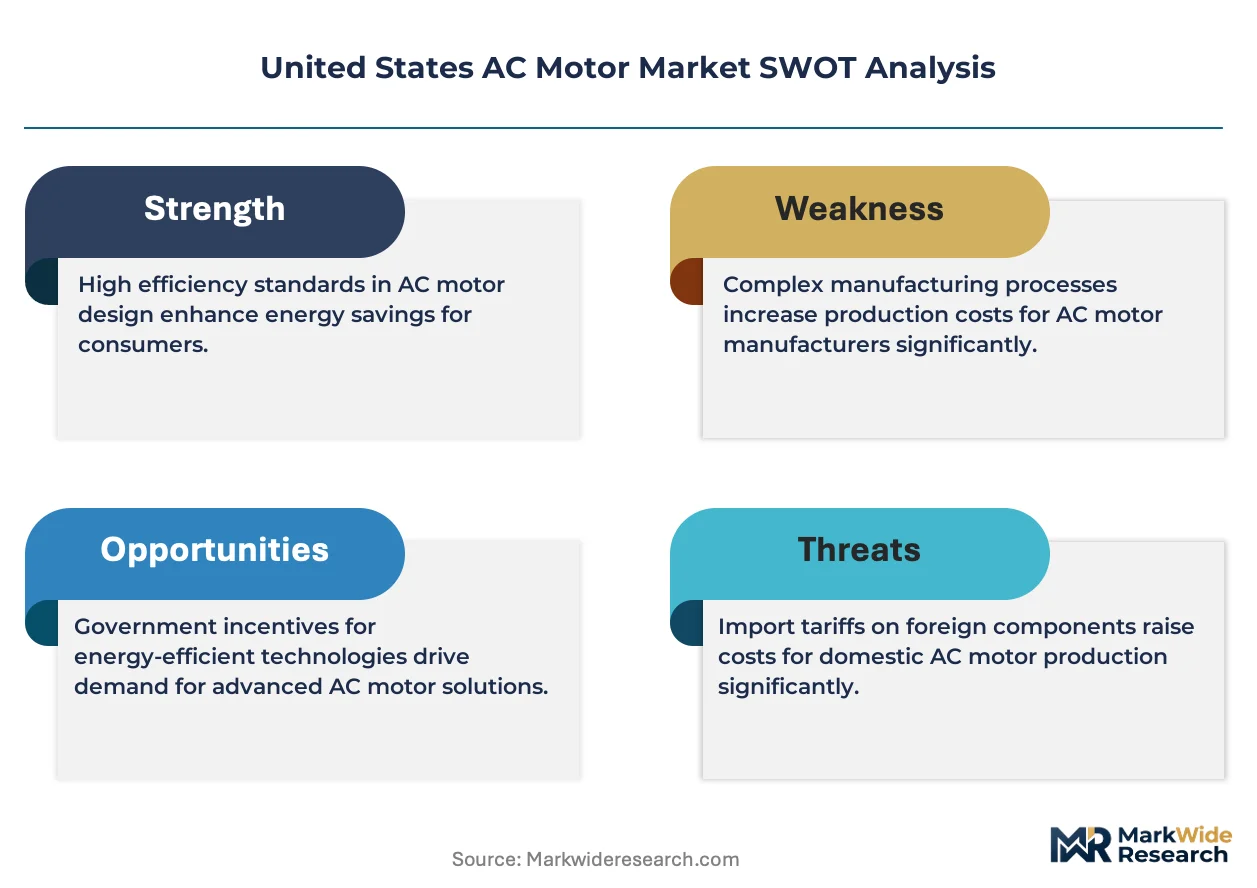
Department of Energy efficiency mandates under 10 CFR 431 are compressing replacement cycles across industrial motor fleets as facility operators face stranded asset risk from non-compliant equipment.
Growth Catalysts
- HVAC Upgrade Cycles:Commercial building operators in Texas and California are accelerating motor replacements ahead of tightened state energy codes, pulling forward demand for premium efficiency induction models.
- 10 CFR 431 Enforcement:The DOE's minimum efficiency standards are disqualifying IE1 and IE2 motors from commercial sale, forcing industrial buyers toward IE3 and IE4 certified equipment.
- Servo Adoption in Packaging:Automated food processing lines across the Midwest are deploying precision AC servomotors for robotic material handling, displacing pneumatic actuation in high-speed applications.
Market Restraints
- Copper Price Volatility:Stator winding costs fluctuate with London Metal Exchange copper futures, squeezing margin stability for manufacturers of high-horsepower industrial motors.
- Rare-Earth Concentration:Permanent magnet synchronous motors depend on neodymium supply chains concentrated in Chinese processing facilities, exposing buyers to export restriction risk.
- NEMA MG 1 Testing Burden:Compliance verification protocols add certification overhead that disadvantages smaller domestic manufacturers against integrated multinational suppliers.
Strategic Opportunities
- Great Lakes Retrofit Wave:Petrochemical and automotive plants in Michigan and Ohio operate aging motor bases exceeding twenty-year service life, creating replacement demand for condition-monitored premium units.
- Utility Rebate Digitization:State-level demand response programs are shifting incentives toward connected motor systems with embedded power metering, opening channel partnerships between OEMs and regional utilities.
- Synchronous-Induction Hybrid Designs:Convergence of permanent magnet and reluctance rotor technologies is enabling new product categories that bridge efficiency and capital cost tradeoffs for mid-horsepower applications.
Industry Challenges
- Electromechanical Technician Shortage:Motor rewind and field service capabilities are contracting as vocational training programs decline in the Southeast manufacturing corridor, lengthening repair lead times.
- Legacy VFD Integration:Facility operators face compatibility friction when upgrading to IE4 motors with existing variable frequency drive infrastructure not optimized for synchronous motor control algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States AC Motor Market |
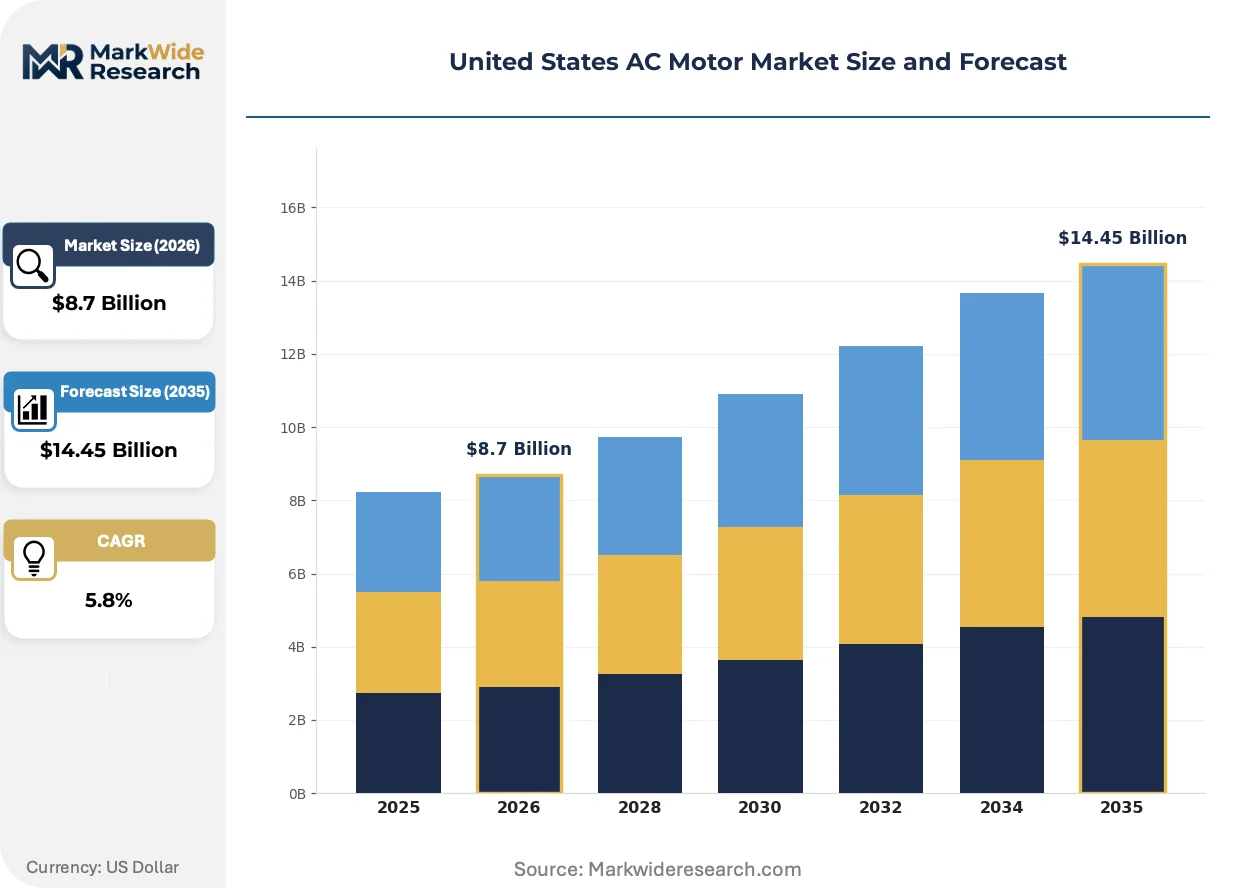
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Motor, Synchronous Motor, Servomotor, Torque Motor End User: Manufacturing, HVAC, Consumer Electronics, Marine Installation: Indoor, Outdoor, Integrated, Standalone Power Rating: Fractional Horsepower, Medium Horsepower, High Horsepower, Other |
| Companies Covered | ABB, Siemens, General Electric, Rockwell Automation, Nidec Motor Corporation, Johnson Electric, Regal Rexnord Corporation, AMETEK, Toshiba International Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States AC Motor Market Trends and Innovations
Digital twin diagnostics and copper-based winding innovations are restructuring how motor performance is validated and maintained across industrial asset bases.
Copper rotor die-casting technology is absorbing manufacturing investment as permanent magnet alternatives face supply volatility. Food processing and automotive stamping facilities in the Great Lakes corridor are adopting copper rotor induction motors for high-torque applications previously reserved for rare-earth synchronous designs. This material shift is absorbing price pressure from magnet supply constraints while maintaining IE4 efficiency thresholds.
OSHA electrical safety requirements are tightening lockout-tagout protocols for motor maintenance operations in heavy industrial settings. Facility safety managers must now document arc flash hazard analysis for motor control centers above specified voltage thresholds. Petrochemical complexes along the Gulf Coast are responding by consolidating motor fleets under single-source service contracts with integrated safety certification.
Condition-based maintenance contracts are displacing time-based overhaul schedules across large manufacturing motor fleets. Asset managers at Midwest automotive plants are unbundling motor supply from service agreements, selecting OEMs based on predictive analytics platform maturity rather than unit cost alone. This procurement evolution is most visible in Michigan and Ohio where integrated motor-drive-service packages are capturing multi-year facility agreements.
United States AC Motor Market Segmentation
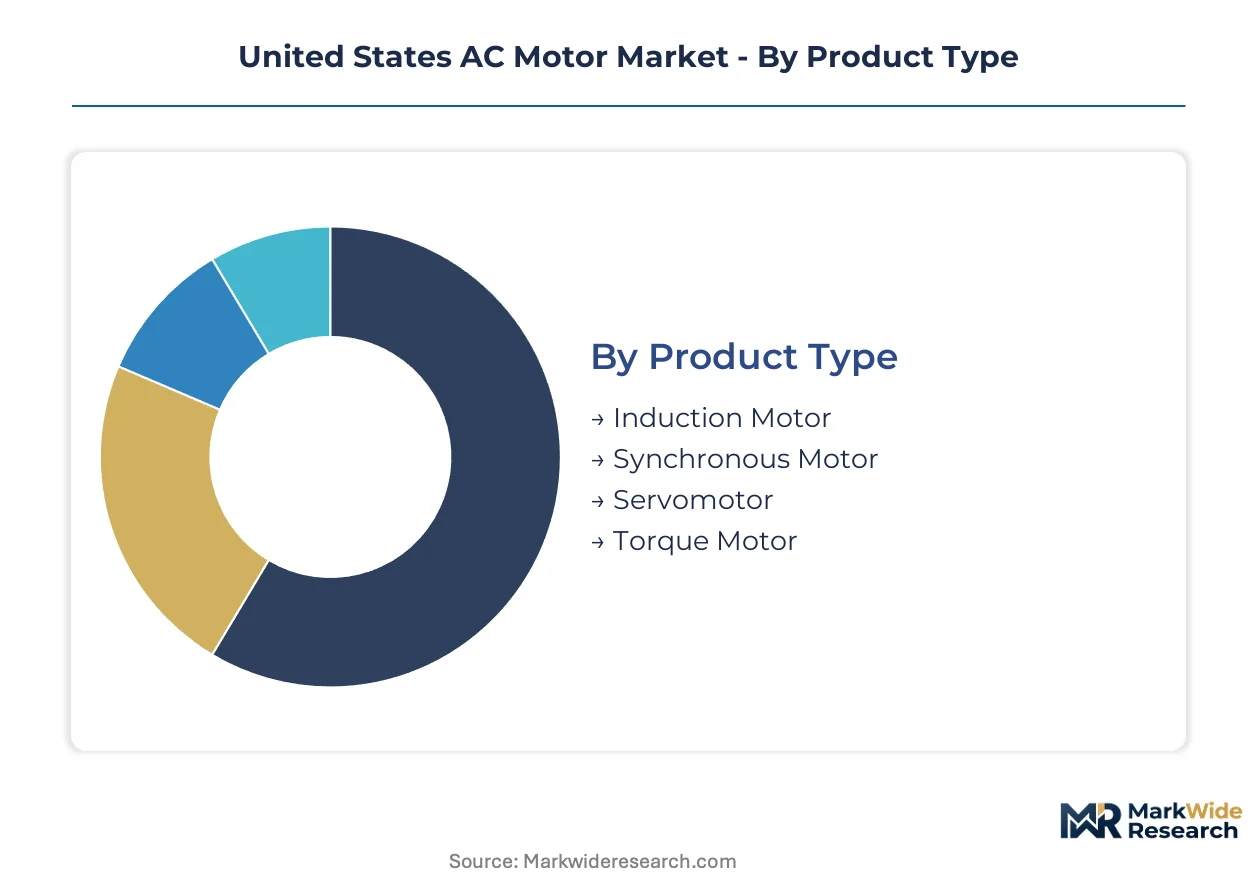
AC motor procurement in the United States splits across technical specifications, operating environments, and power requirements that determine lifecycle economics. Facility operators weight capital cost against efficiency mandates and maintenance accessibility when selecting across these dimensions.
Product Type:
Customization intensity varies sharply across this category, from standardized induction platforms to precision-engineered servo systems requiring application-specific tuning.
- Induction Motor:Electromagnetic torque generation through rotor slip relative to stator field frequency delivers rugged construction with minimal maintenance requirements. Manufacturing plants across the Great Lakes corridor deploy these for conveyor drives and pump applications where capital cost sensitivity outweighs precision needs.
- Synchronous Motor:Rotor locks to stator field frequency enabling exact speed holding for compressors and extruders in Texas petrochemical complexes. Permanent magnet variants achieve IE4 efficiency but face neodymium supply exposure through Chinese processing concentration.
- Servomotor:Closed-loop position control with encoder feedback supports robotic packaging lines in Midwest food processing facilities.
- Torque Motor:Direct-drive elimination of mechanical transmission suits indexing tables and winding equipment in automotive stamping plants.
Most installed capacity flows through Induction Motor. Expansion is steepest in Servomotor.
End User:
Application environments dictate cooling requirements, enclosure ratings, and duty cycle specifications across customer segments.
- Manufacturing:Continuous-duty industrial processes from metal forming to material handling demand motors rated for severe operating conditions. Automotive assembly plants in Ohio and Michigan specify premium efficiency units with predictive maintenance connectivity to minimize unplanned downtime costs.
- HVAC:Fan and compressor drives in commercial buildings face accelerating replacement cycles under California and Texas state energy codes. Rooftop unit manufacturers specify electronically commutated and premium induction models to meet ASHRAE efficiency thresholds.
- Consumer Electronics:Miniature AC motors power appliance compressors and fan systems with extreme cost compression requirements.
- Marine:Saltwater corrosion resistance and shock-rated construction distinguish propulsion and auxiliary systems for Gulf Coast vessel operators.
Manufacturing commands the largest motor fleet by unit count. HVAC replacement demand is climbing fastest as building codes tighten.
Installation:
Physical integration depth determines enclosure protection, thermal management, and service accessibility tradeoffs.
- Indoor:Climate-controlled environments permit open drip-proof and totally enclosed fan-cooled enclosures common in Midwest manufacturing facilities. Standardized mounting configurations reduce spare parts inventory complexity for maintenance departments.
- Outdoor:Weather-protected enclosures with enhanced sealing withstand temperature cycling and precipitation exposure for HVAC condenser fans and oilfield pumpjack drives across Texas Permian Basin operations.
- Integrated:Motor-drive combinations from single suppliers simplify commissioning and warranty coverage for automated production lines.
- Standalone:Separable motor and control components permit field replacement flexibility in legacy industrial infrastructure.
Indoor configurations dominate current installed base. Integrated packages are gaining share fastest in greenfield automation deployments.
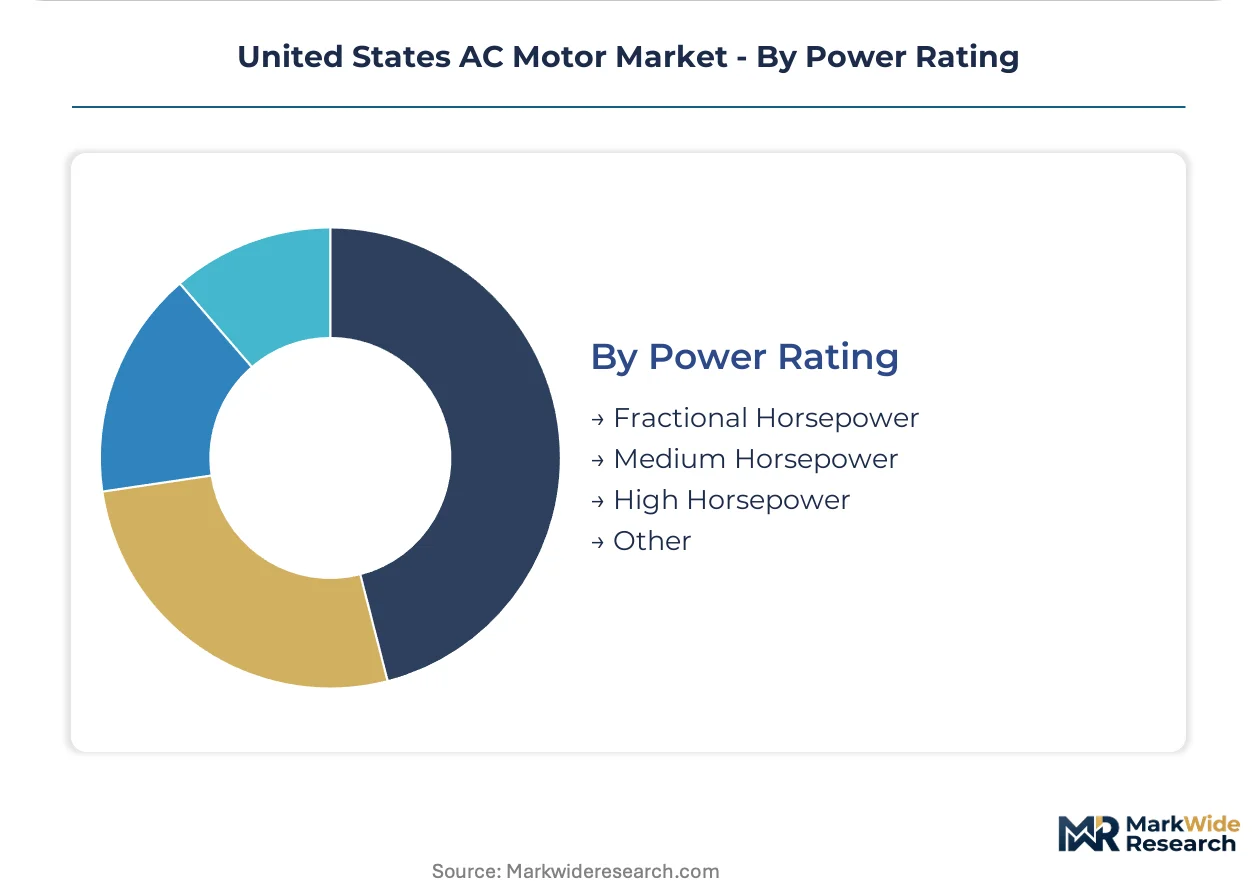
Power Rating:
Scale economies and regulatory thresholds create distinct competitive dynamics across horsepower categories.
- Fractional Horsepower:Sub-1 HP units power fans, blowers, and small appliances with extreme cost sensitivity and high production volumes. Regal Rexnord's distribution network controls aftermarket channels for replacement demand in residential and light commercial applications.
- Medium Horsepower:1-200 HP range captures the bulk of industrial process applications subject to DOE 10 CFR 431 efficiency mandates. Food processing and automotive plants in the Great Lakes states are retrofitting aging medium-horsepower fleets with IE3-certified units ahead of compliance deadlines.
- High Horsepower:Above 200 HP, custom-engineered synchronous and induction designs serve compressors, crushers, and refinery processes with extended lead times and project-based procurement.
- Other:Specialized ratings for military, aerospace, and medical applications fall outside standard industrial classification.
Medium Horsepower represents the largest revenue pool. High Horsepower expansion is accelerating most quickly in petrochemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors national AC motor demand through automotive stamping plants and food processing facilities in Michigan and Ohio. Texas petrochemical complexes and California commercial building stock generate concentrated replacement cycles. Midwest automation lines and Southeast HVAC markets complete the geographic demand map.
Texas
Permian Basin pumpjack operations and Gulf Coast refinery expansions drive high-horsepower synchronous motor procurement. The state's utility commission administers demand response rebate programs favoring connected motor systems with embedded metering. Houston-area petrochemical clusters are retrofitting aging compressor drives with IE4-certified units ahead of federal efficiency deadlines.
California
Commercial building electrification mandates accelerate HVAC motor replacement cycles across Los Angeles and San Francisco metro areas. The California Energy Commission enforces Title 24 efficiency standards that disqualify lower-tier equipment from new construction. Silicon Valley data center operators specify premium induction motors with predictive maintenance connectivity for cooling system redundancy.
Michigan
Automotive assembly plants in Detroit and Flint specify medium-horsepower premium efficiency motors for robotic welding and conveyor systems. OSHA electrical safety requirements tighten lockout-tagout protocols for motor maintenance in heavy industrial settings. Tier 1 stamping facilities in Grand Rapids are unbundling motor supply from service agreements to prioritize predictive analytics platform maturity.
Ohio
Food processing lines across Cincinnati and Cleveland deploy precision AC servomotors for automated packaging applications. The Department of Energy's 10 CFR 431 standards force industrial buyers toward IE3 and IE4 certified equipment. Akron-area polymer plants operate motor bases exceeding twenty-year service life, creating replacement demand for condition-monitored premium units.
Southeast
Georgia and Florida distribution centers multiply robotic material handling lines requiring closed-loop servomotor control. State energy codes in the region lag California and Texas but adoption is accelerating. Charlotte-area HVAC equipment manufacturers specify electronically commutated motors to meet ASHRAE efficiency thresholds for commercial rooftop units.
United States AC Motor Market Competitive Landscape
Global majors compete with regional champions across integrated drive-motor packages and aftermarket service networks. The vendor base organizes around three tiers: multinational industrial conglomerates with full-stack automation portfolios, mid-sized specialists in fractional and medium horsepower segments, and niche servomotor engineers serving robotics integrators. Dominant competitive moves include strategic partnerships between OEMs and regional utilities for rebate program digitization, plus portfolio diversification into condition-based maintenance contracts.
Among the multinational tier, ABB, Siemens, and Regal Rexnord Corporation occupy distinct positioning archetypes. ABB represents the integrated drives-motor systems approach with emphasis on high-horsepower industrial applications. Siemens exemplifies digital twin diagnostics embedded in large synchronous motor lines. Regal Rexnord anchors the fractional and medium horsepower distribution channel through extensive aftermarket control. These three collectively illustrate how scale, technology specialization, and channel depth segment competitive terrain.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| General Electric |
| Rockwell Automation |
| Nidec Motor Corporation |
| Johnson Electric |
| Regal Rexnord Corporation |
| AMETEK |
| Toshiba International Corporation |
| Others |
Pricing and Supply Chain Analysis
IE4 premium-tier certification against IE3 standard-grade equipment creates a bifurcated pricing architecture that simultaneously reflects copper-intensive manufacturing costs and rare-earth supply vulnerability. This divergence manifests in procurement patterns where Texas petrochemical operators absorb synchronous motor premiums while Great Lakes automotive plants optimize total cost of ownership through copper rotor induction alternatives.
Pricing Analysis
Copper futures pass-through from London Metal Exchange contracts directly compresses margin stability for manufacturers of high-horsepower industrial motors. Three-tier pricing structure across premium IE4 synchronous, standard IE3 induction, and economy IE2 closeout inventory reflects both DOE 10 CFR 431 compliance deadlines and neodymium supply concentration risk. Pricing pressure stems from stranded asset risk forcing accelerated replacement cycles among facility operators. HVAC contractors in California demonstrate highest price sensitivity due to thin installation margins, while Gulf Coast petrochemical buyers prioritize efficiency premiums over first cost.
Supply Chain Analysis
Regional distribution centers in Chicago, Dallas, and Atlanta operate hub-and-spoke patterns that consolidate fractional and medium horsepower inventory for aftermarket channel fulfillment. Manufacturing concentration rests on Mexico, China, and domestic Great Lakes facilities for stator lamination and rotor assembly. Raw material dependencies center on Chilean copper cathode, Chinese rare-earth processing, and domestic electrical steel from Ohio and Pennsylvania mills. Single-source vulnerability concentrates in neodymium magnet supply chains through Chinese export license protocols. Distribution runs through authorized distributor networks with integrated service capabilities rather than direct OEM fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States AC Motor Market functions as a stable compounder anchored by regulatory-mandated replacement cycles that guarantee baseline demand regardless of industrial capex volatility.
For Market Incumbents: Cement channel control through exclusive service contracts with Great Lakes automotive stamping facilities facing OSHA electrical safety compliance burdens. Deepen backward integration into copper rotor die-casting capabilities to offset rare-earth price volatility threatening synchronous motor margins. Prioritize predictive analytics platform certification to capture utility rebate digitization opportunities in Texas and California. For New Entrants and Emerging Players: Mid-market food processing facilities in Ohio and Michigan present underserved buyer archetypes with aging motor bases exceeding twenty-year service life and limited predictive maintenance vendor relationships. Precision servo integration for robotic packaging lines offers penetrable white space against entrenched multinational automation portfolios. Go-to-market execution should anchor on condition-based maintenance contracts unbundled from equipment supply, mirroring procurement evolution visible at Tier 1 automotive suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with copper rotor induction specialists positioned between rare-earth synchronous premium pricing and commodity IE3 saturation. Long-term viability over a multi-year horizon favors manufacturers with captive electrical steel sourcing and established utility rebate program partnerships. Monitor Department of Energy enforcement actions on 10 CFR 431 compliance deadlines as the critical inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rotor Manufacturing | Captive die-casting capacity insulates margin stability from LME futures volatility for high-horsepower producers. |
| Utility Rebate Program Partnership | Channel alignment with Texas and California demand response digitization secures specification lock-in for connected motor systems. |
| Predictive Maintenance Platform Development | Analytics maturity determines procurement decisions at Michigan and Ohio automotive plants unbundling supply from service. |
| Synchronous-Induction Hybrid Product Launch | Reluctance rotor convergence bridges efficiency and capital cost tradeoffs for mid-horsepower food processing applications. |
| Aftermarket Channel Consolidation | Regal Rexnord's fractional horsepower distribution control demonstrates value of spare parts inventory proximity to Southeast manufacturing. |
Research Methodology
Bottom-up end-use facility modeling reconciled against top-down motor shipment tracking forms the analytical core of this study. Primary interviews with maintenance directors at Great Lakes automotive plants, HVAC contractors in California, petrochemical facility engineers in Texas, and aftermarket distribution managers in the Southeast informed demand-side calibration. Secondary validation drew from Department of Energy 10 CFR 431 enforcement databases, NEMA MG 1 certification registries, OSHA electrical safety incident reports, and utility commission rebate program filings. Triangulation across these sources anchored volume estimates against actual procurement patterns.
Historical trendline analysis of motor replacement cycles, efficiency regulation phase-in dates, and copper price elasticity informed projection mechanics. Segmentation dimensions modeled include product type, power rating tier, installation configuration, and end-use industry vertical across the projection horizon. CAGR derivation incorporated facility age distribution analysis, state energy code adoption timelines, and servomotor penetration rates in automated packaging lines. Industry-specific forecast inputs centered on DOE compliance deadline clustering and utility incentive program budget allocations.
Underlying measurement precision varies by segment; fractional horsepower consumer electronics and standardized medium horsepower industrial units carry tighter precision than custom high-horsepower synchronous designs. Forecasts reflect documented assumptions on regulatory enforcement intensity, copper price band stability, and rare-earth export policy continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Electric Motorcycle Market
Electric Motor
Global Hub Motors Market
Electric Motor
Intelligent Motor Controller Market
Electric Motor
Global Electric Motor Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Global Automotive Micro Motor Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Brazil Electrically Powered Hydraulic Steering Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
Electric Traction Motor Market