
 Identity Resolution Software Market | 2026-2036
Identity Resolution Software Market Size, Share, and Industry Trends Forecast 2026-2036
Identity Resolution Software Market Intelligence
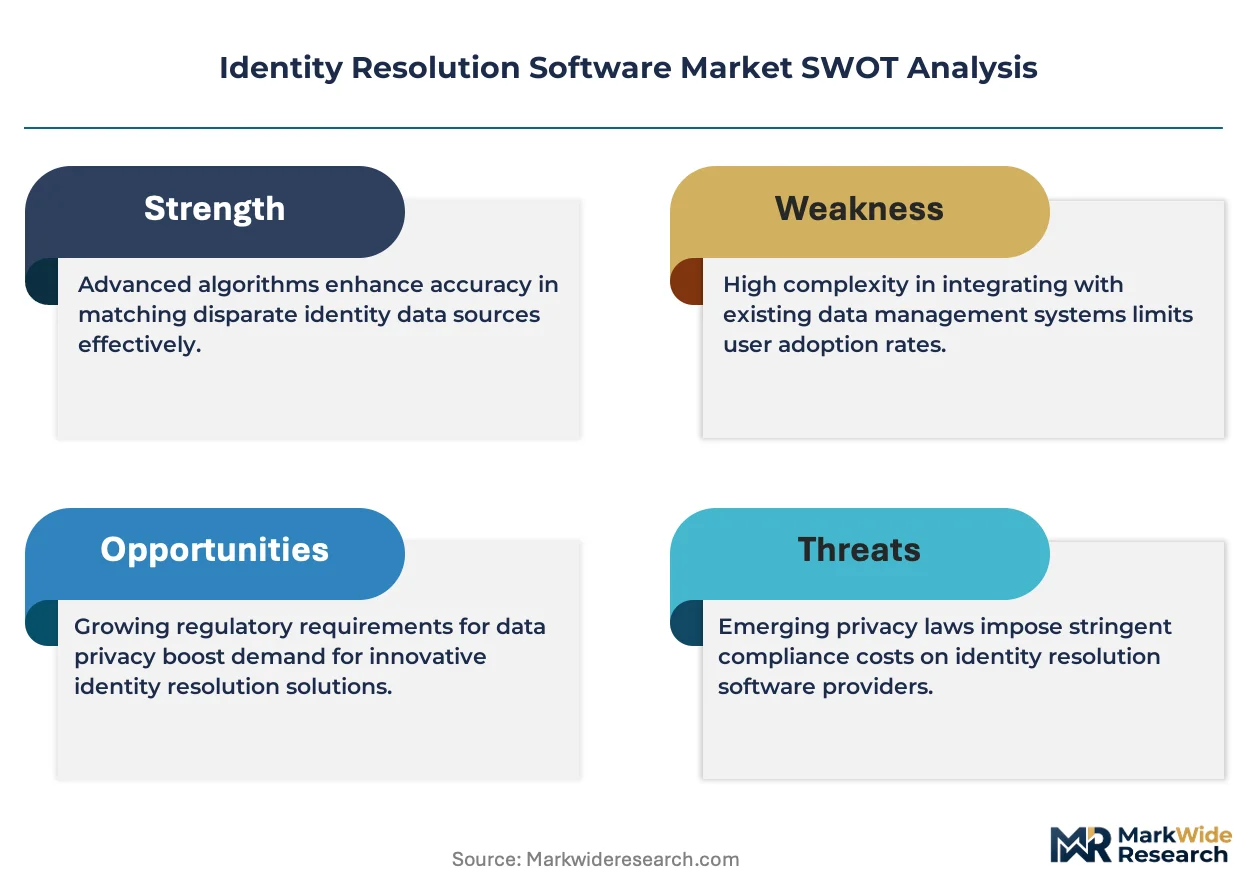
Cross-channel identity graph licensing is reconfiguring margin pools away from standalone data management platforms toward integrated real-time activation layers. LiveRamp leverages its deterministic matching network to sustain premium pricing in the programmatic advertising stack. Experian anchors its position through credit-data adjacency and proprietary device-linking methodologies. Amperity competes on customer data platform convergence, specializing in first-party identity stitching for retail enterprises.
Identity resolution software probabilistically and deterministically links fragmented consumer identifiers across devices, channels, and platforms into persistent unified profiles using cryptographic hashing, fuzzy matching algorithms, and graph database architectures; its primary commercial purpose is enabling compliant, accurate personalization while eliminating data silos and duplicate records. Cloud-based deployment now leads solution type demand as enterprises abandon on-premises infrastructure maintenance burdens, while machine learning-based matching represents the fastest-expanding technology segment as neural embedding models displace rules-based deterministic approaches. Data governance solutions command expanding margin pools as GDPR, state privacy laws, and sector-specific mandates elevate auditability requirements above throughput metrics.
The Federal Trade Commission and state attorneys general in California and Virginia enforce evolving privacy frameworks that mandate explicit consent chains and deletion rights, directly shaping product roadmaps toward consent-aware identity graphs with automated suppression workflows. The EU AI Act and ISO/IEC 27701 standards further constrain cross-border data linking by requiring algorithmic transparency documentation for automated profiling decisions. Stakeholders must monitor emerging state-level privacy patchworks and assess whether their identity infrastructure can adapt to jurisdiction-specific consent orchestration without fragmenting unified profile completeness.
Market Dynamics
Financial services institutions are consolidating fragmented customer data estates into unified identity graphs, pressured by GDPR and EU AI Act mandates for auditable matching algorithms. This structural force compresses deployment timelines and elevates explainability requirements above raw matching accuracy.
Growth Catalysts
- GDPR Article 17 erasure mandates:European enterprises are procuring identity resolution platforms with automated suppression workflows to satisfy deletion rights without fragmenting unified profiles.
- Healthcare interoperability:US hospital systems are deploying real-time patient matching to eliminate duplicate records across electronic health record silos, driven by HIPAA information-blocking penalties.
- Neural embedding architectures:Machine learning-based probabilistic matching is expanding addressable match rates beyond deterministic rules engines in retail personalization stacks.
Market Restraints
- Specialized graph database talent scarcity:Supply of engineers proficient in Neo4j and TigerGraph query optimization concentrates in San Francisco and London, inflating implementation costs.
- Cross-border data friction:China's Personal Information Protection Law and data localization requirements fragment identity graph completeness for multinational enterprises operating across mainland facilities.
- Cryptographic key management complexity:Deterministic matching using SHA-256 hashing demands hardware security module investments that mid-market buyers defer.
Strategic Opportunities
- Brazil's open banking expansion:Brazil's central bank consent framework creates greenfield demand for financial identity stitching across newly interoperable deposit and credit data.
- Cookie deprecation tailwinds:Google's Privacy Sandbox phase-out of third-party identifiers is forcing programmatic advertisers toward first-party identity graph licensing.
- Convergence of customer data platforms:CDP vendors are bundling identity resolution as a native module, compressing standalone software addressable market while expanding total wallet capture.
Industry Challenges
- ISO/IEC 27701 certification timelines:Privacy information management system audits require 12-18 month implementation cycles that delay enterprise procurement decisions.
- Legacy master data management integration:Fortune 500 enterprises maintain decades-old customer hierarchies in SAP and Oracle systems that resist real-time API synchronization with cloud-native identity graphs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Identity Resolution Software Market |
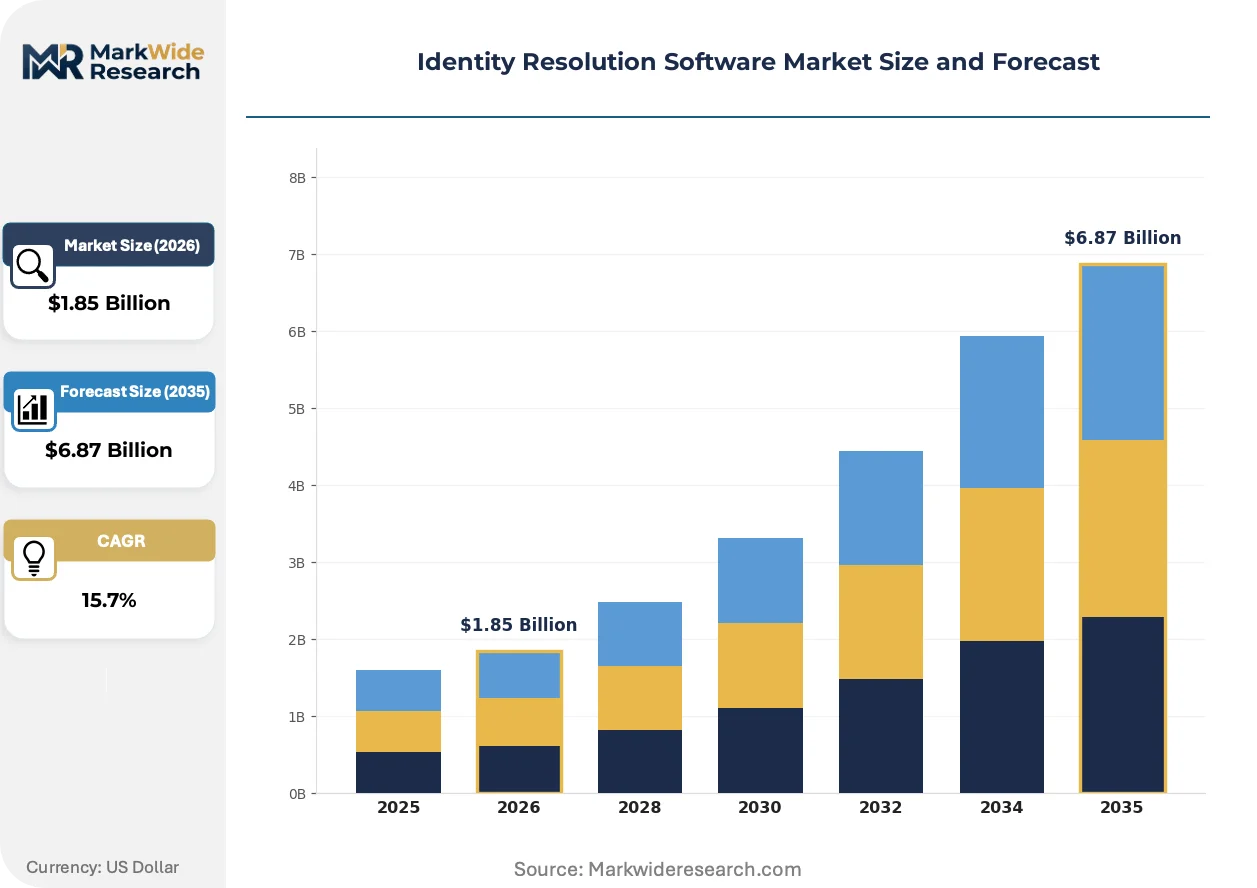
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Integration, Data Enrichment, Data Governance, Identity Matching Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Tenant End User: Retail, Healthcare, Financial Services, Government Technology: Machine Learning, Artificial Intelligence, Big Data Analytics, Distributed Ledger |
| Companies Covered | Signal, Amperity, Informatica, Experian, Criteo, LiveRamp, Neustar, Acxiom, Zeta Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Identity Resolution Software Market Strategic Shifts & Innovations
Neural embedding models and automated consent orchestration are compressing the gap between data collection and actionable identity graphs. These shifts are elevating explainability and real-time responsiveness as primary competitive differentiators.
Transformer-based embedding architectures are rendering obsolete rules-based deterministic matching in high-velocity personalization use cases. Retail enterprises in the United States are deploying these models to link probabilistic device signals within milliseconds of page load. The structural consequence is margin compression for vendors maintaining legacy fuzzy matching codebases that cannot scale to sub-100-millisecond latency requirements.
The EU AI Act's automated profiling documentation requirements are forcing algorithmic transparency into product roadmaps. Vendors must now generate audit trails for every match decision that affects credit, employment, or insurance outcomes. Financial services institutions in Germany and France are prioritizing vendors with built-in explainability dashboards over those with superior raw match rates.
First-party data co-ops are displacing third-party identity graph licensing in programmatic advertising. Retail media networks at Walmart and Target are inviting suppliers to match customer segments against pooled deterministic identifiers without external data brokers. This behavioral shift concentrates most visibly in the United States, where retail media spend now exceeds connected television investment and identity resolution contracts increasingly flow through commerce platforms rather than standalone software vendors.
Identity Resolution Software Market Segmentation
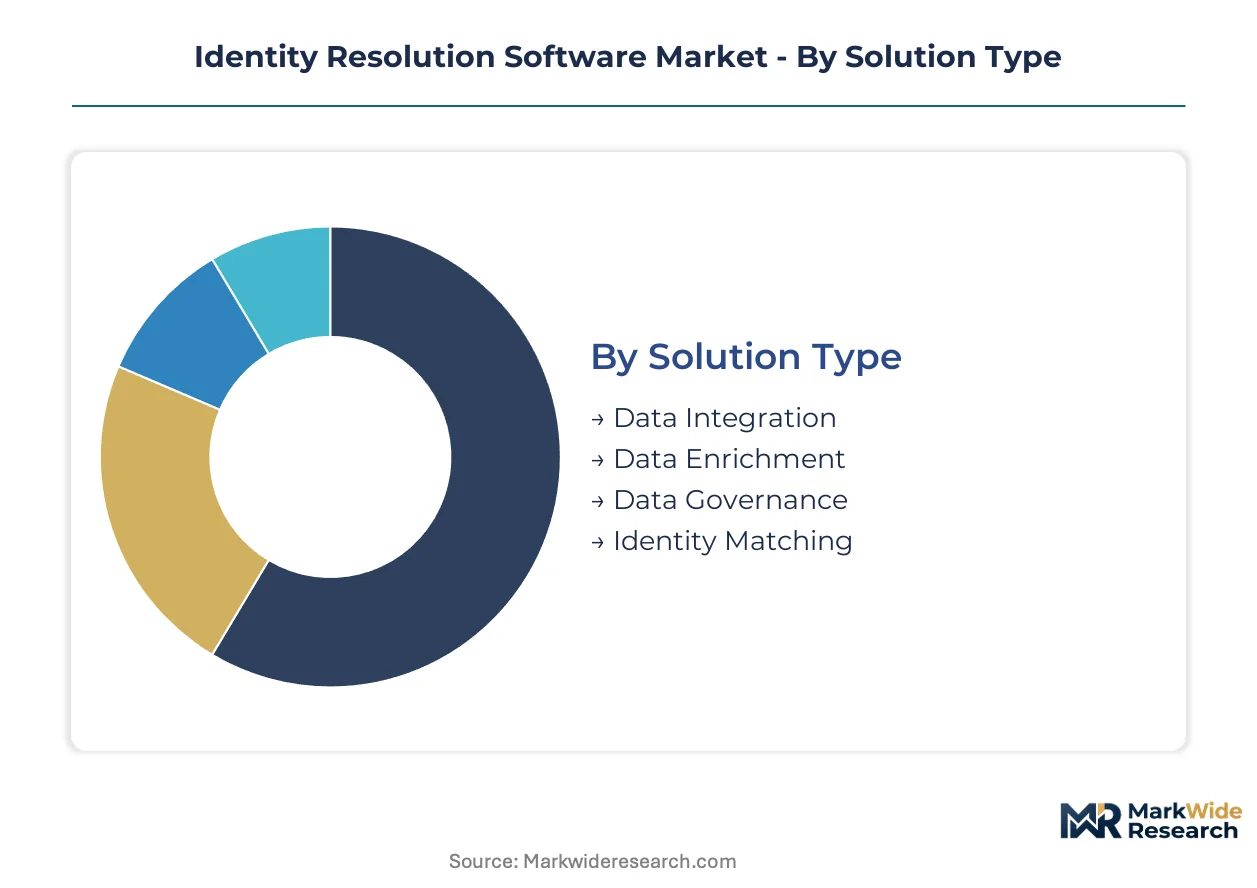
Identity resolution software segments by solution architecture, infrastructure model, buyer vertical, and underlying technology stack. Each dimension carries distinct margin profiles and procurement timelines that shape vendor positioning.
Solution Type:
Cost tier determines procurement authority and implementation complexity across functional modules.
- Data Integration:Pipeline orchestration engines extract, transform, and load fragmented identifiers from CRM, ERP, and streaming sources into unified schemas. Financial services procurement teams in Germany prioritize pre-built connectors for core banking systems.
- Identity Matching:Probabilistic and deterministic algorithms link disparate identifiers using graph traversal and cryptographic hashing. Real-time retail personalization in the United States demands sub-100-millisecond match latency that rules-based engines cannot satisfy.
- Data Enrichment:Third-party attribute appending from demographic, behavioral, and device graph sources.
- Data Governance:Consent orchestration, lineage tracking, and automated suppression workflows for GDPR Article 17 compliance.
Identity Matching holds installed capacity. Data Governance is rotating up the share rankings.
Deployment Model:
Application requirements for latency, data residency, and integration depth segment infrastructure choices.
- Cloud-Based:Managed SaaS architectures eliminate hardware procurement and scale compute elastically for seasonal retail traffic spikes. HIPAA-eligible AWS and Azure regions satisfy United States healthcare data residency requirements without on-premises capital expenditure.
- Hybrid:Sensitive identity graphs remain on-premises while activation layers deploy to cloud edge nodes. German automotive manufacturers favor this model to retain sovereign control over customer master data while enabling real-time marketing personalization.
- On-Premises:Air-gapped deployments for classified government environments and legacy mainframe integration.
- Multi-Tenant:Shared infrastructure with logical isolation serving mid-market buyers seeking enterprise-grade capabilities without dedicated resource costs.
Cloud-Based deployments command the largest revenue base. Hybrid architectures are climbing the fastest as sovereignty requirements harden.
End User:
Customer type dictates feature prioritization, compliance frameworks, and sales cycle duration.
- Financial Services:Anti-money laundering, know-your-customer, and fraud prevention use cases demand auditable match explanations under EU AI Act automated profiling rules. French and German banks now require algorithmic transparency dashboards as standard evaluation criteria.
- Retail:First-party identity graph construction for loyalty program personalization and retail media network monetization. Walmart and Target in the United States are displacing third-party data brokers with proprietary deterministic matching pools.
- Healthcare:Patient matching across electronic health record silos to eliminate duplicate records and HIPAA information-blocking penalties.
- Government:Citizen identity verification and benefits eligibility matching with heightened security classification requirements.
Financial Services maintains the deepest technology penetration. Retail is gaining share fastest as cookie deprecation accelerates first-party data investments.
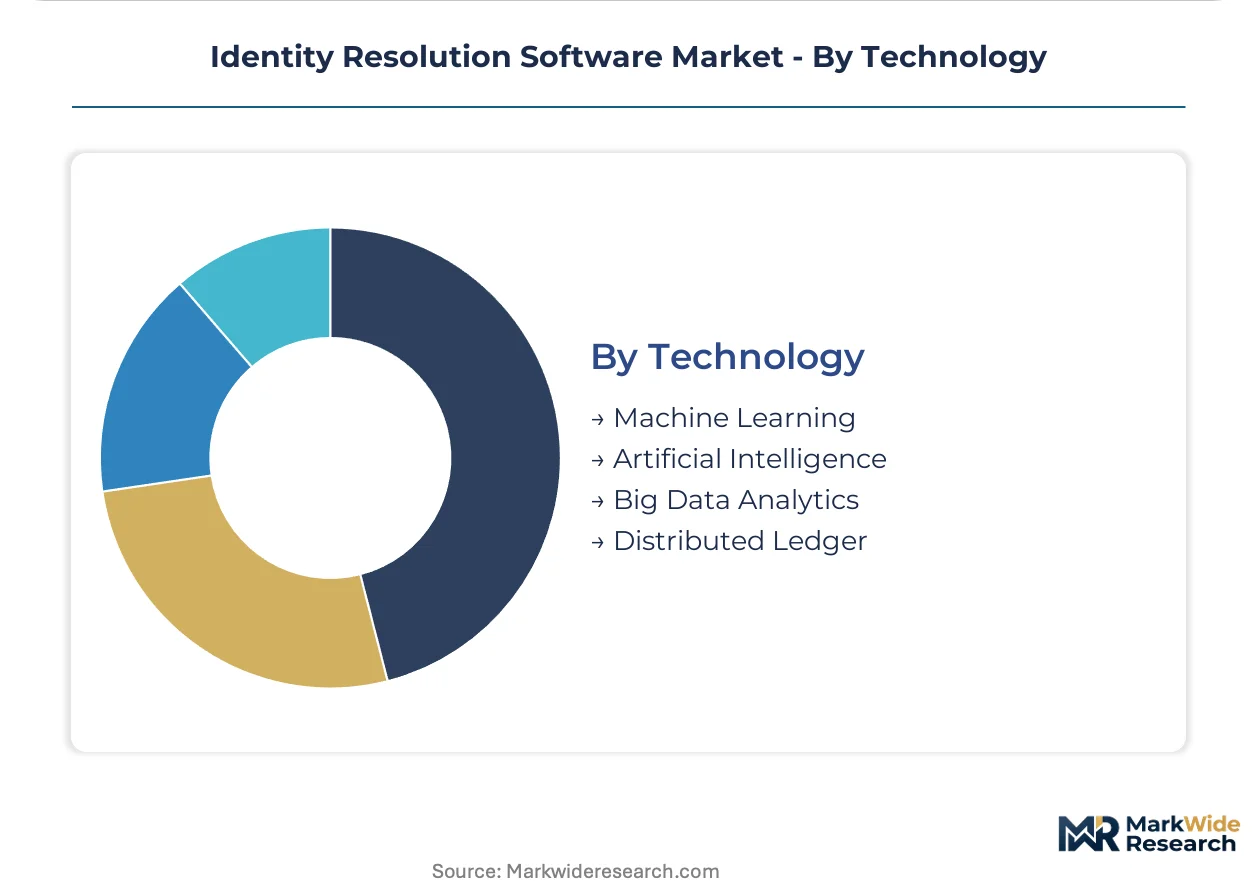
Technology:
Maturity curves and talent availability differentiate competitive positioning across underlying architectures.
- Machine Learning:Neural embedding models encode identity attributes as high-dimensional vectors enabling probabilistic similarity scoring. Transformer architectures from United States-based research labs are displacing legacy fuzzy matching in high-velocity personalization stacks.
- Big Data Analytics:Distributed query engines process petabyte-scale identity graphs across Apache Spark and Databricks clusters.
- Artificial Intelligence:Automated feature engineering and model retraining pipelines reduce manual tuning for match threshold optimization.
- Distributed Ledger:Blockchain-based consent registries providing immutable audit trails for cross-enterprise identity verification pilots.
Machine Learning anchors current R&D investment. Big Data Analytics retains the broadest production deployment base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent for graph database optimization concentrates in San Francisco and London, inflating implementation costs for enterprises outside these clusters. Cloud-native deployment dominates procurement in markets with mature digital infrastructure. Regulatory fragmentation across jurisdictions forces vendors to architect jurisdiction-specific consent orchestration layers.
United States
Real-time personalization requirements from retail and healthcare sectors drive cloud-native identity resolution procurement. The FTC enforces evolving privacy frameworks mandating explicit consent chains and automated suppression workflows. Hospital systems in Texas and California deploy patient matching solutions to eliminate duplicate records across electronic health record silos.
Germany
Financial services institutions demand auditable match explanations for anti-money laundering and know-your-customer use cases. The EU AI Act mandates algorithmic transparency documentation for automated profiling decisions affecting credit and insurance outcomes. Automotive manufacturers in Bavaria favor hybrid deployment models to retain sovereign control over customer master data.
United Kingdom
GDPR Article 17 erasure mandates push enterprises toward identity resolution platforms with automated suppression workflows. The Information Commissioner's Office enforces deletion rights without permitting fragmentation of unified profiles. London-based fintech clusters prioritize vendors with built-in explainability dashboards over those with superior raw match rates.
Brazil
Open banking expansion creates greenfield demand for financial identity stitching across newly interoperable deposit and credit data. The central bank consent framework requires auditable matching algorithms for cross-institutional customer verification. São Paulo-based retail media networks invite suppliers to match customer segments against pooled deterministic identifiers.
China
Data localization requirements under the Personal Information Protection Law fragment identity graph completeness for multinational enterprises. The national regulator mandates hardware security module investments for cryptographic key management in deterministic matching. Manufacturing clusters in Guangdong and Jiangsu defer cloud migration due to sovereignty concerns and cross-border data friction.
Identity Resolution Software Market Key Industry Players
Deterministic matching specialists and probabilistic platform vendors split the market along latency and explainability vectors. The vendor base organizes into three strategic archetypes: credit-data incumbents with proprietary device-linking methodologies, customer data platform convergers specializing in first-party identity stitching, and programmatic advertising integrators leveraging cross-channel identity graph licensing. Dominant competitive moves include convergence bundling that compresses standalone software addressable market, and first-party data co-op formation that displaces third-party identity graph licensing.
Within the credit-data incumbent tier, Experian anchors positioning through adjacency to financial verification workflows. Amperity and LiveRamp occupy contrasting positions in the customer data platform and programmatic advertising integration tiers respectively, with the former exemplifying first-party specialization for retail enterprises and the latter representing deterministic network leverage in media activation stacks.
| Leading Market Players |
|---|
| Signal |
| Amperity |
| Informatica |
| Experian |
| Criteo |
| LiveRamp |
| Neustar |
| Acxiom |
| Zeta Global |
| Others |
Cost & Logistics Intelligence
San Francisco and London engineering clusters concentrate graph database optimization talent, inflating implementation costs for enterprises outside these hubs and compressing margin pools for mid-market buyers seeking real-time identity matching capabilities. This geographic concentration of technical expertise shapes vendor pricing power and procurement timelines across deployment tiers.
Pricing Analysis
GDPR Article 17 and the EU AI Act dictate the pricing tier structure for identity resolution platforms, with automated suppression workflows and algorithmic transparency dashboards commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade explainability features from mid-market deterministic matching and basic data integration modules. Cost compression in the standard tier is intensifying because cloud-native deployment commoditizes pipeline orchestration, while healthcare and financial services buyers show least price sensitivity due to HIPAA and EU AI Act compliance mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from hyperscale cloud providers anchor vendor working capital structures, with AWS and Azure consumption commitments stretching 12-24 months. Software development draws from United States, India, and Poland engineering centers, with cryptographic hashing modules and neural embedding architectures resting on specialized GPU clusters and hardware security module supply. Single-source vulnerability concentrates in NVIDIA tensor core availability for transformer-based matching models. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated retail media networks and financial services institutions, which are displacing fragmented third-party data broker relationships with proprietary first-party identity graph licensing. This consolidation compresses addressable market for standalone software vendors while expanding total wallet capture for integrated platform providers.
For Market Incumbents:Harden algorithmic transparency documentation and automated consent orchestration capabilities to defend against emerging entrants offering neural embedding architectures at lower latency thresholds. Prioritize ISO/IEC 27701 certification investment to maintain procurement eligibility among German and French financial institutions. Channel control through direct API integration with core banking and electronic health record systems preserves switching costs.
For New Entrants and Emerging Players:Pursue Brazil's open banking expansion and Southeast Asian retail media network formation as white-space targets, where greenfield demand for financial identity stitching lacks incumbent saturation. The most penetrable segment lies in mid-market healthcare systems seeking HIPAA-compliant patient matching without legacy master data management integration burdens. A vertical-specific go-to-market angle targeting hospital information-blocking penalty avoidance accelerates initial traction.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors customer data platform convergers with native identity resolution modules, as bundling compresses standalone software addressable market while expanding total wallet capture. Long-term viability hinges on first-party data co-op formation capabilities and real-time personalization latency performance. The signal to watch is cookie deprecation acceleration forcing programmatic advertisers toward deterministic identity graph licensing versus probabilistic matching investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CDP vendors bundling identity resolution displace standalone software procurement at Walmart and Target. |
| Acquisition of Specialist Firm | Neural embedding startups with sub-100-millisecond latency capabilities command premium positioning in retail personalization stacks. |
| Strategic Partnership | Cloud hyperscaler alliances provide HIPAA-eligible infrastructure without capital expenditure burden for hospital systems. |
| Product Launch | Explainability dashboards addressing EU AI Act automated profiling requirements unlock German and French banking procurement. |
| Geographic Expansion | Brazil central bank consent framework creates greenfield demand for cross-institutional customer verification platforms. |
Research Approach
Desk research of SEC filings, hyperscaler capex disclosures, and regulatory framework documentation preceded structured interviews with chief technology officers, IT procurement officers, platform engineers, and integration specialists across financial services, retail, and healthcare verticals. Primary fieldwork combined with secondary validation from GDPR enforcement actions, EU AI Act implementation guidance, and hospital procurement database analysis. Bottom-up deployment modeling and top-down market sizing triangulation anchored volume and value estimates.
Assumptions held fixed include sustained cloud-native deployment preference, continued third-party cookie deprecation timelines, and stable HIPAA information-blocking penalty enforcement intensity; variables included neural embedding adoption velocity and jurisdiction-specific consent orchestration fragmentation. Segmentation dimensions modeled encompass deployment model, organization size, vertical compliance framework, integration complexity, and regional regulatory cluster. CAGRs derived from technology substitution curves and enterprise procurement cycle analysis, with inputs from electronic health record silo consolidation rates and retail media network spend allocation shifts.
Macroeconomic conditions sit as an overlay; deviation in enterprise software capital expenditure cycles or cross-border data localization enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about technology adoption and regulatory enforcement; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Data Quality Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Binary Drivers Market
Software & Services
Global Web Scraper Software Market
Software & Services
Global HVAC Software Market
Software & Services
Quote Management Software Market
Software & Services
Global Smartphone Operating System (OS) Market
Software & Services
Architectural Rendering Software Market
Software & Services
Debt Collection Software Market
Software & Services
Global Cloud-Based Call Center Software Market
Software & Services
Global Application Platform Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Network Documentation Software Market
Software & Services
Workshop Management Software Market
Software & Services
North America Digital Marketing Software Market
Software & Services
User Interface Software Market