
 Global Application Platform Market | 2026-2036
Global Application Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Platform Market Foresight
The application platform market is pivoting on a widening split between premium unified suites and commodity point solutions. Microsoft Corporation leverages its Azure-native integration to sustain enterprise lock-in across hybrid deployment scenarios. Oracle Corporation anchors its position through database-tier control that extends into application infrastructure. Huawei Technologies Co. Ltd. competes on sovereign-cloud mandates in regulated Asian and Middle Eastern markets.
An application platform provides a unified runtime, development, and management environment for building, deploying, and operating software applications, typically exposing container orchestration, API gateways, and event brokers as core functional modules. Low-code platforms are capturing disproportionate margin pools by compressing time-to-deployment for line-of-business applications, while API management segments face commoditization from open-source alternatives. Integration platform solutions lead in average contract value among solution types, reflecting the complexity premium attached to heterogeneous system landscapes in BFSI and telecom end user industries.
FDA guidelines on software-as-medical-device, EU AI Act risk-classification requirements, and China's MIIT data-localization standards are collectively elevating compliance architecture to a primary procurement criterion. The EU Green Deal and CSRD reporting obligations are forcing platform vendors to embed carbon-accounting APIs and sustainable-compute dashboards into core offerings. Stakeholders must weigh sovereign-data requirements against interoperability costs when selecting deployment architectures.
Market Dynamics
Enterprise consolidation of application estates around governed low-code environments is compressing vendor selection cycles and elevating compliance architecture above functional feature parity in procurement scoring matrices.
Growth Catalysts
- EU AI Act risk-classification mandates:Financial services and healthcare enterprises in Germany and France are procuring platforms with built-in algorithmic audit trails and explainability modules to satisfy conformity obligations.
- Container orchestration standardization:Kubernetes-native runtime environments are displacing proprietary middleware stacks in telecom and BFSI modernization programs, reducing lock-in premiums.
- India's PLI scheme for IT hardware:Domestic data center expansion is creating captive demand for sovereign-cloud application platforms with localized control planes and API gateways.
Market Restraints
- Specialized talent scarcity:Platform engineering and site reliability engineering roles command 40-60% compensation premiums in the United States and Germany, inflating total cost of ownership for self-managed deployments.
- Input cost volatility in compute infrastructure:GPU and high-memory instance pricing fluctuations in cloud regions are compressing margins for platform vendors offering consumption-based pricing.
- Regulatory fragmentation:Divergent data-localization requirements between China's MIIT standards, EU GDPR adequacy rulings, and US CLOUD Act jurisdictions are forcing redundant architectural investments.
Strategic Opportunities
- Carbon-accounting API integration:The EU Green Deal and CSRD reporting obligations are creating first-mover advantages for vendors embedding Scope 3 emissions dashboards into core platform offerings.
- Edge-native runtime expansion:Manufacturing and logistics enterprises in Japan and South Korea are deploying lightweight application platforms to factory floors and warehouse nodes, bypassing centralized cloud latency.
- Healthcare software-as-medical-device convergence:FDA 21 CFR Part 820 quality system requirements are opening specialized platform tiers with validated deployment pipelines and audit-ready documentation packages.
Industry Challenges
- Multi-cloud interoperability engineering:Enterprise architecture teams struggle to maintain consistent policy enforcement and identity federation across AWS, Azure, and GCP-native platform instances without vendor-specific tooling lock-in.
- Legacy system API extraction:Mainframe and AS/400 estate modernization projects in US insurance and German automotive sectors require expensive custom adapter development, extending platform value realization timelines by 12-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Platform Market |
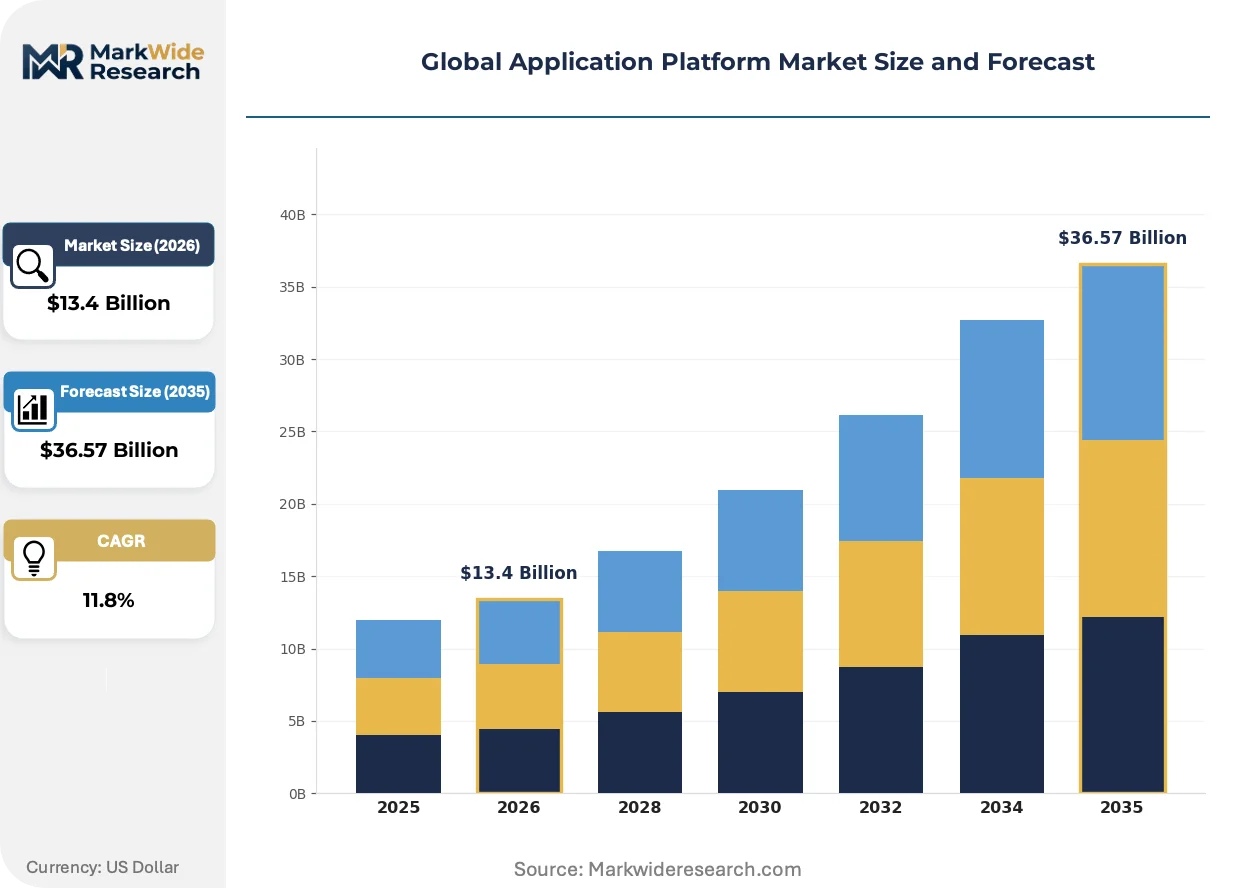
| Market Size in 2026 | $13.4 Billion |
| Market Size in 2035 | $36.57 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-Premises, Hybrid, Edge, Private Cloud Solution Type: Low-Code, Integration Platform, Mobile Backend, API Management, Event Streaming Use Case: Customer Engagement, Digital Transformation, Business Process Automation, IoT Integration, Data Analytics End User Industry: BFSI, Telecom, Manufacturing, Government, Transportation |
| Companies Covered | International Business Machines Corporation, Microsoft Corporation, Oracle Corporation, Salesforce.com Inc., SAP SE, Amazon Web Services Inc., Google LLC, Huawei Technologies Co. Ltd., ServiceNow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Platform Market Shifts & Advancements
Generative AI copilots are embedding into development workflows, compressing code generation cycles and forcing platform vendors to reposition around orchestration rather than raw runtime performance.
Retrieval-augmented generation frameworks are automating documentation synthesis and test case generation for enterprise Java and .NET codebases. Banking and insurance development teams in the United States and United Kingdom are deploying these capabilities at pilot scale, with production commitments accelerating through 2025. The technology is automating away tier-one support and maintenance tasks previously requiring dedicated offshore engineering benches.
The EU AI Act's foundation model transparency obligations are forcing platform vendors to expose training data provenance and inference logging APIs. German automotive and French healthcare enterprises are now scoring vendor proposals on algorithmic audit readiness, with non-compliant architectures disqualified at RFI stage. This regulatory pressure is fragmenting the unified platform market into compliance-grade and standard-tier product lines.
Consumption-based pricing with committed use discounts is displacing perpetual licensing in enterprise procurement negotiations. Large BFSI and telecom accounts in India and Brazil are demanding granular metering of API calls, container hours, and event stream volumes, unbundling previously fixed platform fees. This shift is most visible in multi-year contracts where variable cost exposure now exceeds 60% of total contract value.
Global Application Platform Market Segmentation
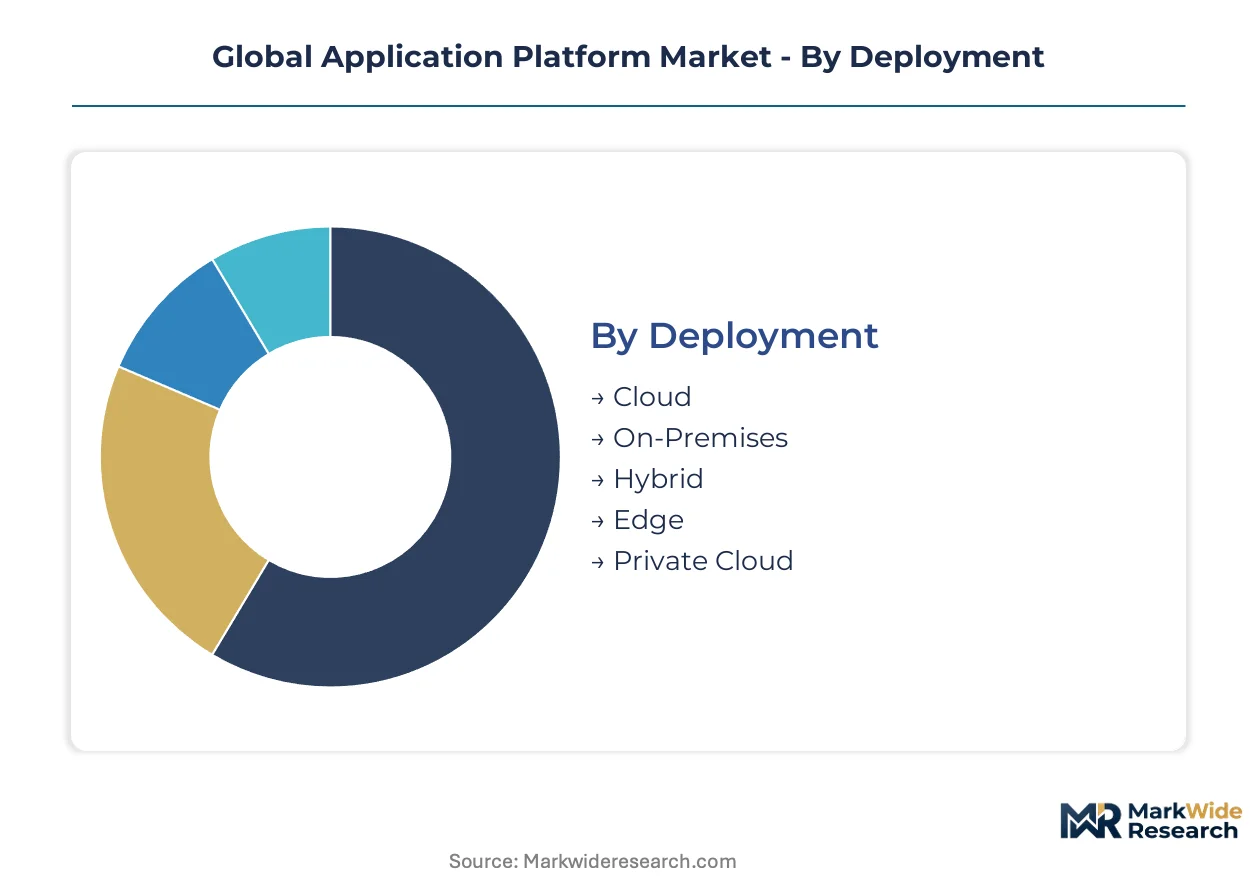
Application platform procurement decisions hinge on deployment topology, solution architecture, and vertical compliance requirements. Vendors compete across four intersecting dimensions that determine integration complexity, governance overhead, and total cost of ownership for enterprise buyers.
Deployment:
Cloud-native runtime environments dominate new procurement, though sovereign-data mandates and latency-sensitive workloads sustain hybrid and edge alternatives.
- Cloud:Public cloud deployments provide elastic compute scaling and managed control plane services. Financial services enterprises in the United States and Germany favor multi-tenant SaaS platforms with FedRAMP or BSI C5 certification to satisfy regulatory audit requirements.
- Hybrid:Split workload architectures allow sensitive transaction processing on-premises while bursting analytics to public infrastructure. German automotive manufacturers and Indian BFSI institutions deploy hybrid configurations to reconcile data-localization rules with cloud agility demands.
- On-Premises:Self-managed infrastructure persists in defense and classified government environments with air-gapped security requirements.
- Edge:Factory-floor and warehouse-node deployments in Japan and South Korea bypass centralized cloud latency for real-time manufacturing orchestration.
- Private Cloud:Dedicated single-tenant environments serve Middle Eastern sovereign-cloud mandates and Chinese MIIT data-localization standards.
Cloud leads on scale; edge gains share fastest in manufacturing modernization programs.
Solution Type:
Functional specialization determines margin capture, with integration complexity commanding premium pricing against commoditized API gateway segments.
- Integration Platform:Heterogeneous system orchestration commands the highest average contract values in enterprise procurement. BFSI and telecom accounts pay complexity premiums for pre-built connectors to SAP, Oracle, and mainframe estates.
- Low-Code:Visual development environments compress line-of-business application deployment cycles. Financial services teams in France and the United Kingdom accelerate customer-facing portal delivery without expanding specialized engineering headcount.
- API Management:Gateway and developer portal functions face margin pressure from open-source Kong and Envoy alternatives.
- Event Streaming:Real-time data pipeline infrastructure supports fraud detection and IoT telemetry use cases in telecom and transportation sectors.
- Mobile Backend:Device synchronization and push notification services address retail and logistics mobile workforce requirements.
Integration platform leads on contract value; low-code climbs fastest as business-unit self-service expands.
Use Case:
Enterprise priorities shift workload requirements toward real-time engagement and automated compliance documentation.
- Digital Transformation:Legacy estate modernization drives platform consolidation decisions across insurance and automotive sectors in Germany and the United States.
- Business Process Automation:Workflow orchestration with embedded EU AI Act audit trails satisfies conformity obligations in French healthcare and German financial services.
- Customer Engagement:Unified interaction platforms integrate conversational AI with transaction history for retail banking deployments.
- IoT Integration:Device fleet management and edge analytics support predictive maintenance in Japanese manufacturing and South Korean logistics networks.
- Data Analytics:Embedded business intelligence and carbon-accounting dashboards address EU CSRD reporting obligations.
Digital transformation leads on deployment scale; business process automation advances fastest under regulatory compliance pressure.
End User Industry:
Vertical compliance intensity and legacy system complexity determine platform selection criteria and contract duration.
- BFSI:Banking and insurance institutions demand algorithmic audit trails, explainability modules, and FedRAMP or BSI C5 certification. German and US institutions lead procurement volume for governed low-code environments.
- Telecom:Network function virtualization and customer identity management drive Kubernetes-native platform adoption across Indian and Brazilian operators.
- Manufacturing:Japanese and South Korean factories deploy edge-native runtimes for shop-floor quality control and supply chain traceability.
- Government:Sovereign-cloud mandates and classified workload requirements sustain on-premises and private cloud deployments.
- Transportation:Fleet telematics and logistics optimization platforms integrate with IoT sensor networks for real-time route adjustment.
BFSI leads on contract value and compliance sophistication; manufacturing expands fastest through edge deployment adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German enterprises outpace French institutions in governed low-code procurement, while Indian operators drive sovereign-cloud infrastructure expansion at faster clip than Brazilian counterparts.
United States
BFSI modernization and telecom network virtualization dominate enterprise procurement. FedRAMP certification requirements filter vendor selection for federal contracts. Financial services clusters in New York and Charlotte consolidate application estates around compliance-grade platforms with algorithmic audit capabilities.
Germany
Automotive manufacturers and insurance groups lead European platform investment. BSI C5 certification and EU AI Act risk-classification mandates shape RFP scoring matrices. Industrial software adoption concentrates in Stuttgart and Munich, where manufacturers deploy hybrid architectures for shop-floor quality systems.
India
Domestic data center expansion and PLI scheme incentives accelerate sovereign-cloud platform deployment. RBI data-localization guidelines and TRAI telecom regulations mandate localized control planes. Bengaluru and Mumbai host the primary engineering centers for platform customization and API gateway development.
Japan
Manufacturing modernization and edge-native runtime adoption characterize enterprise demand. METI industrial digitization programs subsidize factory-floor platform deployment. Nagoya and Osaka automotive clusters deploy lightweight application platforms for real-time supply chain orchestration.
South Korea
Electronics manufacturers and logistics operators drive edge-computing platform procurement. MFDS medical device software regulations and national AI strategy shape compliance architecture requirements. Busan port logistics and Gyeonggi-do semiconductor fabs represent concentrated deployment sites.
Global Application Platform Market Competitive Landscape
Top-tier vendors anchor unified-suite positioning, while mid-tier specialists compete on vertical compliance modules and sovereign-cloud localization. The market structure tilts toward consolidation as enterprise procurement teams compress vendor shortlists to three or fewer finalists. Strategic archetypes include database-centric incumbents extending infrastructure control, cloud-native challengers capturing consumption-based contracts, and regional specialists exploiting data-localization mandates. Dominant competitive moves involve M&A to fill API management gaps and strategic partnerships with systems integrators for legacy modernization delivery.
Within the database-control archetype, Oracle Corporation exemplifies infrastructure-tier lock-in strategies. Microsoft Corporation and Amazon Web Services Inc. occupy positions across the cloud-native consumption tier, with Azure-native integration and AWS service breadth representing alternative enterprise engagement models. Huawei Technologies Co. Ltd. anchors the sovereign-cloud specialist position, capturing regulated-market share through compliance with Chinese MIIT and Middle Eastern data-localization standards.
| Leading Market Players |
|---|
| International Business Machines Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Salesforce.com Inc. |
| SAP SE |
| Amazon Web Services Inc. |
| Google LLC |
| Huawei Technologies Co. Ltd. |
| ServiceNow Inc. |
| Others |
Supply & Pricing Matrix
Cloud hyperscaler-backed platform vendors anchor supply-side concentration, translating sovereign-cloud mandates into pricing discipline across regulated deployment tiers. Their captive infrastructure investments compress margin leakage while enabling consumption-based pricing models that shift cost volatility onto enterprise buyers.
Pricing Analysis
Bundled unified-suite offerings compete against unbundled point solutions across enterprise procurement cycles. Consumption-based SaaS tiers with committed use discounts dominate multi-year contracts, while FedRAMP and BSI C5 certification levels command 15-25% premiums over standard deployments. GPU instance cost volatility in cloud regions is intensifying pricing pressure on variable-rate tiers, with Indian BFSI and Brazilian telecom accounts proving most price-sensitive due to currency exposure. German automotive manufacturers show lowest sensitivity, prioritizing EU AI Act compliance architecture over unit cost.
Supply Chain Analysis
Cross-border data transit costs and regional cloud region latency shape platform delivery economics for distributed enterprise workloads. Control plane development concentrates in the United States, Germany, and India, with edge runtime modules sourcing from Japanese and South Korean manufacturing technology partners. The supply chain rests on specialized silicon for AI inference acceleration, Kubernetes distribution licensing, and API gateway open-source cores. Single-source vulnerability in GPU supply from Taiwan and South Korea threatens margin stability for vendors offering consumption-based AI services. Distribution runs through hyperscaler marketplaces, systems integrator channel partners, and direct enterprise field sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU compliance-premium jurisdictions and India PLI-subsidized sovereign-cloud buildouts, exploiting a structural cost differential in data-localization infrastructure.
For Market Incumbents: Deploy algorithmic audit trail modules as a defensive moat against cloud-native challengers lacking EU AI Act certification depth. Consolidate API management capabilities through targeted specialist acquisitions to fill connector gaps in mainframe modernization pipelines. Reinforce hybrid deployment tooling to counter pure-play SaaS entrants in German automotive and US insurance verticals. For New Entrants and Emerging Players: Mid-market French healthcare providers represent an underserved buyer archetype seeking governed low-code environments without hyperscaler lock-in. Edge-native runtime deployment for Japanese factory-floor quality control offers penetrable white space against centralized cloud incumbents. Lead with carbon-accounting API integration to capture EU CSRD-driven procurement cycles ahead of established vendor roadmap updates. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, consolidating vertical compliance modules to extend platform breadth. Long-term viability hinges on sovereign-cloud localization capabilities across Chinese MIIT and Middle Eastern data-residency frameworks. Target acquisition candidates with validated FDA 21 CFR Part 820 deployment pipelines for healthcare software-as-medical-device convergence. Monitor Indian PLI scheme disbursement velocity as an inflection signal for sovereign-cloud infrastructure buildout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified runtime consolidation captures BFSI modernization budgets in New York and Charlotte clusters. |
| Acquisition of Specialist Firm | API management gaps in mainframe connector portfolios drive Oracle and SAP tuck-in activity. |
| Geographic Expansion | Indian PLI-subsidized data centers create captive demand for localized control plane deployment. |
| Strategic Partnership | Systems integrator alliances accelerate legacy AS/400 extraction timelines for German insurance modernization. |
| Product Launch | Edge-native runtime releases target Nagoya automotive supply chain orchestration requirements. |
Research Methodology
Bottom-up enterprise workload modeling reconciled against top-down hyperscaler capex tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineering directors, IT procurement officers, and systems integrator partners informed deployment topology assumptions. Secondary validation drew from SEC filings, hyperscaler infrastructure expansion disclosures, EU AI Act implementation guidance, and RBI data-localization circulars. Triangulation between demand-side adoption signals and supply-side capacity investments anchored segmentation sizing.
Historical trendline analysis of container orchestration adoption curves and low-code platform procurement cycles established baseline growth parameters across the projection horizon. The forecast framework models deployment topology, solution architecture, vertical compliance intensity, and regional regulatory cluster as intersecting segmentation dimensions. CAGRs derive from fitted adoption curves adjusted for EU AI Act enforcement timelines and Indian PLI scheme infrastructure buildout pacing. GPU instance pricing volatility and specialized talent scarcity premiums fed sensitivity bands around self-managed deployment cost projections.
Inputs from hyperscaler earnings disclosures and national regulatory filings were available through the study window; gaps in private-cloud deployment telemetry at Middle Eastern sovereign-cloud facilities introduce uncertainty bands around edge-native runtime adoption forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
ID Photo Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Global Digital Adoption Platform Software Market
Software & Services
Global AB Testing Software Market
Software & Services
Enterprise Data Observability Software Market
Software & Services
Workshop Management Software Market
Software & Services
North America IT Services Market
Software & Services
Board Portal Market
Software & Services
Global Conversion Rate Optimization (CRO) Software Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Global Recruiting Software Market
Software & Services
Air Cargo Software Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Content Distribution Software Market
Software & Services
PLM and Engineering Software Market