
 North America Government and Security Biometrics Market | 2026-2036
North America Government and Security Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Government and Security Biometrics Market Insights
Multi-source procurement among federal agencies is hardening as departments diversify biometric vendors to reduce single-point-of-failure risks in national security infrastructure. IDEMIA leverages its NIST-certified fingerprint matching algorithms to sustain dominance in FBI criminal background check systems. Thales Group anchors its position through embedded biometric modules deployed across Canadian border management installations. NEC Corporation competes aggressively with iris recognition platforms optimized for high-throughput airport and seaport environments.
North America Government and Security Biometrics encompasses hardware and software systems that capture, process, and match physiological or behavioral characteristics against enrolled templates, typically operating at false acceptance rates below 0.01% for federal certification. These systems serve to verify or identify individuals in security-critical contexts where token-based credentials prove insufficient. Fingerprint recognition occupies the largest installed base across law enforcement applications, though facial recognition generates the fastest growth trajectory driven by contactless checkpoint mandates. Multi-factor biometric configurations command premium positioning in military and border security deployments where spoofing resistance determines procurement outcomes.
FBI certification under NIST standards shapes product development timelines and vendor qualification pathways across the United States. Canada aligns biometric accuracy requirements with Health Canada privacy frameworks and RCMP operational specifications for criminal identification networks. Stakeholders must monitor evolving NIST test protocols and provincial privacy rulings as determinants of which technology architectures achieve sustainable deployment eligibility.
Market Dynamics
Federal procurement diversification is compressing vendor concentration as DHS and DoD mandate multi-source biometric supply chains to eliminate single-point-of-failure vulnerabilities in critical infrastructure access systems.
Growth Catalysts
- NIST certification protocols:FBI accuracy thresholds for fingerprint and facial matching algorithms are tightening, forcing technology upgrades across federal criminal identification networks and sustaining replacement demand.
- Contactless checkpoint mandates:Border Security agencies across the United States, Canada, and Mexico are accelerating facial recognition and iris scanning deployments for port-of-entry modernization.
- Defense identity assurance budgets:DoD prioritization of biometric access control for critical infrastructure is expanding multi-factor authentication procurement in military installations.
Market Restraints
- Algorithm training data scarcity:Demographic bias in facial recognition training datasets limits deployment eligibility for federal certification under evolving NIST demographic parity requirements.
- Sensor hardware concentration:Specialized iris and facial capture module supply chains concentrate among limited semiconductor foundry capacity, creating procurement bottlenecks for high-throughput installations.
- Provincial privacy fragmentation:Canada's provincial privacy rulings create compliance complexity that delays RCMP and Health Canada biometric system rollouts.
Strategic Opportunities
- Behavioral biometric convergence:Keystroke dynamics and gait analysis integration with physiological systems creates differentiated offerings for continuous authentication in sensitive facilities.
- Mexico border infrastructure:Underpenetrated checkpoint modernization programs present expansion potential for iris recognition platforms in seaport and land crossing environments.
- IRA cybersecurity incentives:Federal infrastructure funding streams are subsidizing biometric access control upgrades in energy and water sector critical infrastructure.
Industry Challenges
- NIST test timeline compression:Extended algorithm evaluation cycles delay product qualification, forcing vendors to maintain parallel development tracks for evolving certification protocols.
- Legacy system interoperability:FBI criminal fingerprint databases and state-level AFIS architectures require costly middleware development for next-generation matching engine integration.
- Specialized biometric engineering talent:Shortage of algorithm scientists with NIST evaluation experience constrains vendor R&D scaling and federal contractor staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Government and Security Biometrics Market |
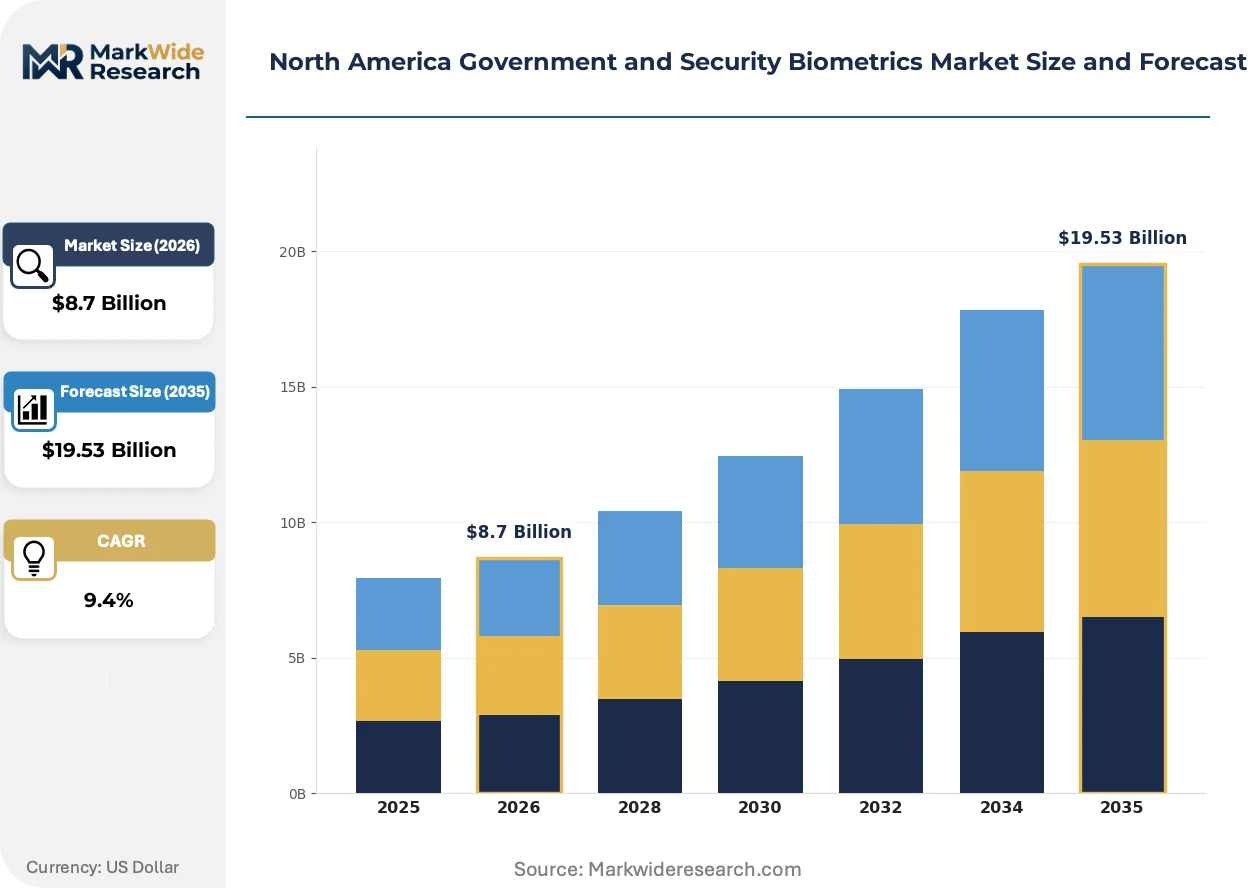
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint, Facial Recognition, Iris Recognition, Voice Recognition End User: Law Enforcement, Military, Border Security, Civil Identification Technology: Single-Factor, Multi-Factor, Biometric-as-a-Service, Embedded Systems Application: Access Control, Identity Verification, Criminal Identification, Time and Attendance |
| Companies Covered | IDEMIA, Thales Group, NEC Corporation, Aware Inc., M2SYS Technologies, HID Global Corporation, BIO-key International, Fujitsu, Innovatrics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Government and Security Biometrics Market Trends and Innovations
Edge-based biometric processing architectures are displacing centralized matching systems, enabling real-time authentication without network dependency while triggering vendor repositioning around on-device inference capabilities.
Multimodal biometric fusion is consolidating standalone fingerprint, facial, and iris systems into unified enrollment and verification platforms. DHS and CBP procurement specifications now prioritize these integrated configurations for border checkpoint deployments. The technology is consolidating vendor portfolios as single-modality specialists face technical disqualification from federal solicitations.
NIST FRVT and MINEX test protocols are tightening accuracy and demographic parity thresholds for federal certification eligibility. FBI qualification pathways now require algorithmic performance across age, gender, and skin tone distributions. United States federal civilian and defense procurement is responding with accelerated vendor requalification cycles and expanded testing budgets.
Agency buying patterns are compressing traditional multiyear deployment schedules into phased pilot-to-production accelerations. CBP and TSA are adopting rapid field-testing frameworks that compress vendor selection timelines. United States border and aviation security segments exhibit the most visible procurement cycle compression, with 18-month pilot-to-scale timelines replacing prior 36-month standards.
North America Government and Security Biometrics Market Segmentation
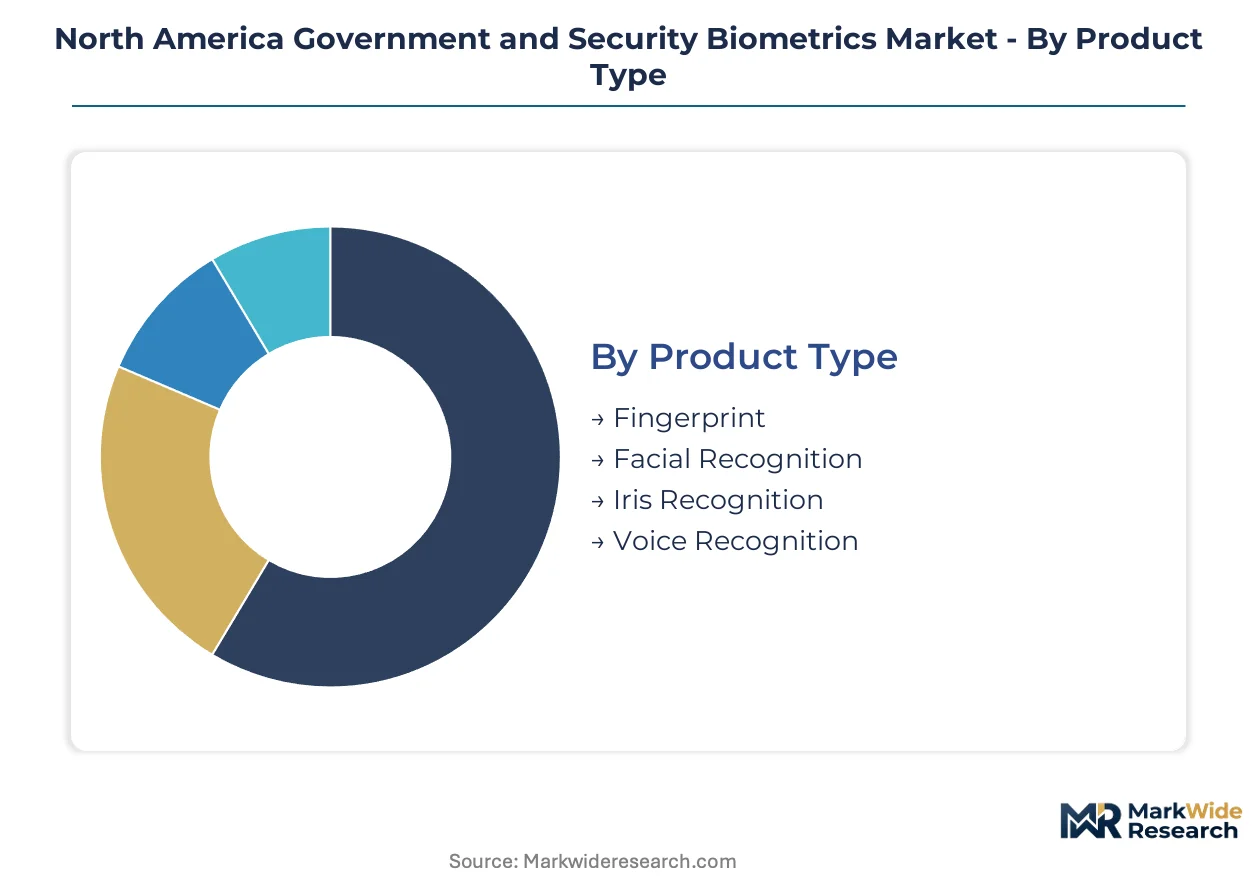
Biometric procurement across North American government agencies fragments across four intersecting dimensions. Each segmentation axis reveals distinct technology specifications, certification requirements, and budget allocation patterns that shape vendor positioning.
Product Type:
Hardware and software systems diverge sharply in sensor complexity, algorithm certification pathways, and deployment infrastructure requirements.
- Facial Recognition:Contactless capture systems process 2D and 3D facial geometry through NIST FRVT-certified algorithms. DHS and CBP checkpoint modernization programs across United States ports of entry are driving the steepest expansion trajectory as agencies mandate touchless passenger processing.
- Fingerprint:Livescan and slap readers employing FBI-certified MINEX algorithms maintain the largest installed base across criminal identification networks. State-level AFIS upgrades and FBI Next Generation Identification system integrations sustain replacement demand in United States law enforcement.
- Iris Recognition:Near-infrared imaging systems capture unique patterns in the stroma for high-accuracy identification at distance. Deployments concentrate in Canadian border management installations and restricted military facility access points.
- Voice Recognition:Speaker verification systems analyze vocal tract physiology and behavioral patterns for remote authentication. Limited federal certification pathways constrain deployment to pilot programs in call center and telephone banking security contexts.
Fingerprint leads on scale; facial recognition leads on momentum.
End User:
Budget authority and procurement timelines vary substantially across federal civilian, defense, and intelligence community stakeholders.
- Border Security:CBP, CBSA, and Mexican National Migration Institute operations require high-throughput, outdoor-capable systems for land, air, and seaport environments. Facial and iris platforms dominate procurement specifications for checkpoint modernization across United States, Canadian, and Mexican ports of entry.
- Law Enforcement:FBI, RCMP, and state-level agencies operate criminal identification networks demanding NIST-certified accuracy thresholds. Fingerprint matching engines constitute core infrastructure, with facial recognition expanding for investigative and real-time screening applications.
- Military:DoD installations and classified facilities prioritize multi-factor biometric configurations with anti-spoofing countermeasures. Embedded access control systems protect critical infrastructure across continental United States and overseas bases.
- Civil Identification:State DMV, federal civilian agency credentialing, and social services programs employ biometric enrollment for identity assurance. TSA PreCheck and NEXUS trusted traveler programs represent high-volume civilian applications.
Law enforcement leads on scale; border security leads on momentum.
Technology:
System architecture choices determine deployment flexibility, cybersecurity posture, and total cost of ownership across federal procurement cycles.
- Multi-Factor:Fused biometric configurations combining fingerprint, facial, and iris modalities deliver highest assurance levels for classified facility access. DoD and intelligence community specifications now mandate multimodal approaches for sensitive compartmented information facilities.
- Single-Factor:Standalone fingerprint or facial systems serve lower-assurance applications with reduced infrastructure requirements. State and local law enforcement AFIS terminals and commercial building access represent primary deployment contexts.
- Embedded Systems:Edge-based processing modules execute matching algorithms on-device without network dependency. Military and critical infrastructure applications prioritize these architectures for continuity during communication disruption.
- Biometric-as-a-Service:Cloud-hosted matching platforms reduce capital expenditure for state and local agencies with limited IT infrastructure. Privacy compliance complexity and FBI criminal data handling restrictions constrain federal adoption.
Single-factor leads on scale; multi-factor leads on momentum.
Application:
Use case specifications dictate sensor form factors, throughput requirements, and integration complexity with legacy identity management systems.
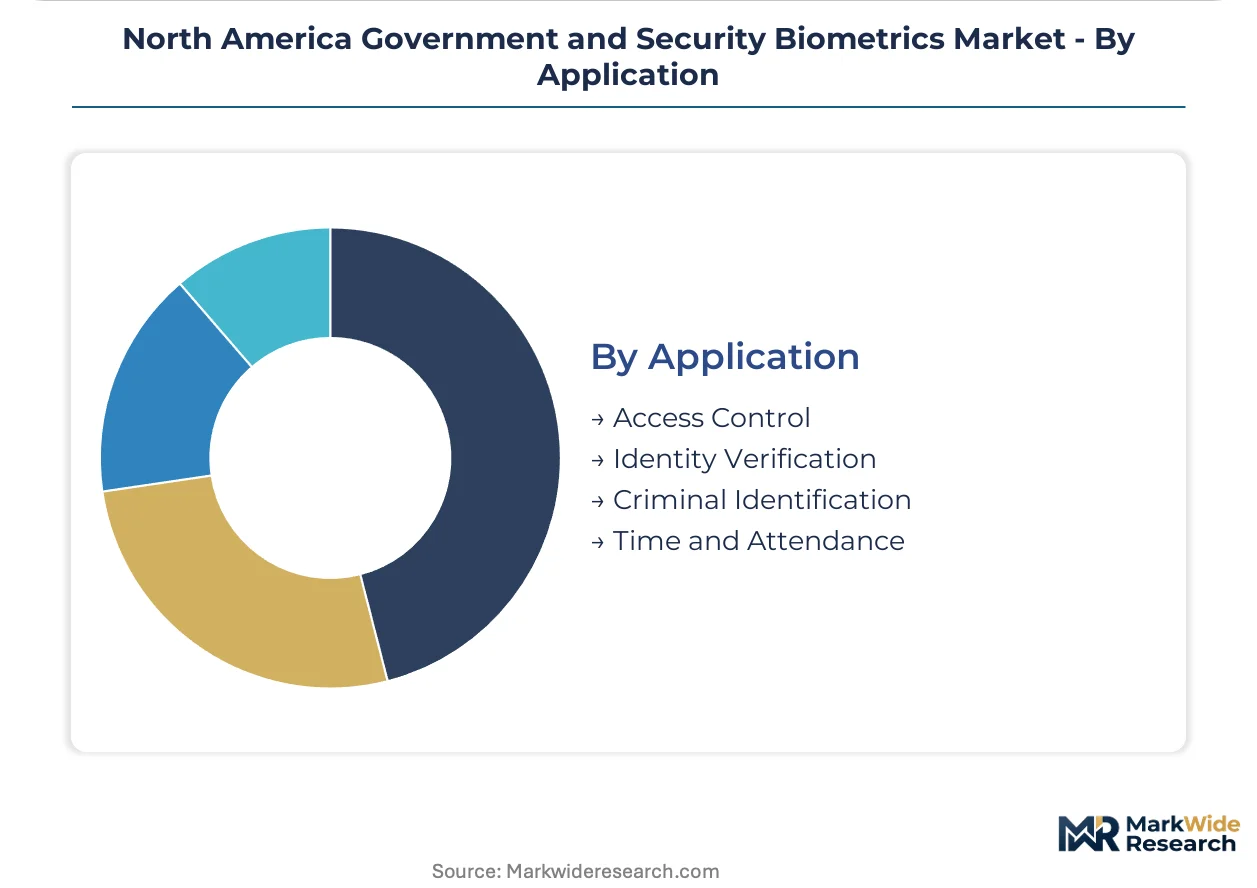
- Access Control:Physical and logical entry systems protect facilities, networks, and data repositories through continuous or point-of-entry authentication. DoD critical infrastructure and federal civilian agency campus security represent primary demand concentrations.
- Identity Verification:One-to-one matching confirms claimed identity against enrolled credentials for benefit disbursement and credential issuance. State DMV REAL ID compliance and federal employment verification sustain procurement volumes.
- Criminal Identification:One-to-many searching identifies unknown subjects against biometric databases for investigation and prosecution. FBI NGI and RCMP criminal repositories drive algorithm accuracy requirements and system upgrade cycles.
- Time and Attendance:Workforce management applications track employee presence through biometric clock-in systems. Federal contractor compliance and military personnel accountability represent specialized government segments.
Criminal identification leads on scale; access control leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biometric procurement across North America diverges sharply by national regulatory frameworks, with compliance cost differentials shaping vendor qualification strategies and deployment timelines across federal, provincial, and state jurisdictions.
United States
DHS and DoD budgets dominate procurement volumes, with CBP facial recognition deployments at southwestern land ports and TSA checkpoint modernization driving hardware demand. FBI NIST certification protocols govern algorithm eligibility for criminal identification networks, forcing vendors through extended MINEX and FRVT evaluation cycles. Washington D.C.-area federal contracting corridors concentrate system integrators serving intelligence community and defense biometric access control requirements.
Canada
CBSA iris scanning installations at Vancouver International Airport and Toronto Pearson anchor high-throughput border infrastructure investments. Health Canada privacy frameworks and RCMP operational specifications create dual compliance pathways that delay provincial biometric system rollouts relative to federal timelines. Montreal-Thales embedded biometric module production supports Canadian border management installations with domestically integrated hardware.
Mexico
Instituto Nacional de Migración checkpoint modernization programs at Tijuana and Ciudad Juárez land crossings present underpenetrated demand for iris recognition platforms. Mexican federal procurement aligns with US-Mexico-Canada Agreement cross-border security cooperation frameworks, though budget constraints compress deployment scales. Mexico City federal district concentrates civil identification biometric enrollment for social services and electoral credentialing programs.
North America Government and Security Biometrics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded edge-processing architectures and behavioral biometric convergence. The vendor structure concentrates around NIST-certified algorithm providers with FBI qualification pathways, while specialized sensor manufacturers occupy upstream hardware positions. Three archetypes dominate: integrated platform vendors with end-to-end enrollment-to-matching capabilities, algorithm specialists licensing certified matching engines, and embedded module suppliers delivering edge-based capture devices. Competitive dynamics center on technology licensing partnerships for algorithm distribution and strategic alliances between hardware fabricators and federal system integrators.
Among NIST-certified platform vendors, IDEMIA and NEC Corporation exemplify contrasting geographic anchoring strategies, with Paris-based IDEMIA sustaining FBI criminal background check dominance and Tokyo-based NEC Corporation competing through iris recognition specialization. Thales Group occupies a distinct position as a European defense-electronics conglomerate with embedded biometric module integration capabilities. These three entities represent the tier-one competitive set whose certification portfolios and federal contracting relationships shape qualification barriers for mid-tier aspirants.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| NEC Corporation |
| Aware Inc. |
| M2SYS Technologies |
| HID Global Corporation |
| BIO-key International |
| Fujitsu |
| Innovatrics |
| Others |
Pricing and Supply Chain Analysis
Specialized near-infrared sensor modules for iris capture systems flow from semiconductor foundries through three certification-grade pricing tiers, with NIST MINEX and FRVT validation thresholds separating premium algorithm licenses from standard embedded hardware bundles.
Pricing Analysis
Input-cost pass-through from constrained semiconductor foundry capacity is compressing margins on embedded biometric modules while sustaining premium pricing for NIST-certified algorithm licenses. Three-tier pricing structure across premium, standard, and economy levels reflects certification investment recovery, with FBI-qualified matching engines commanding substantial markups over uncertified alternatives. Pricing pressure stems from federal procurement diversification mandates requiring vendors to absorb qualification redundancy costs. State and local law enforcement agencies exhibit highest price sensitivity due to limited IT capital budgets, while DoD critical infrastructure programs demonstrate lowest sensitivity given mission-assurance requirements.
Supply Chain Analysis
Reverse-logistics flows for biometric hardware center on FBI and DHS depot refurbishment programs that extend sensor module lifecycles through factory recalibration and firmware requalification. Manufacturing concentration spans Taiwan for CMOS image sensors, South Korea for specialized memory components, and the United States for NIST-certified algorithm development and system integration. Raw material dependencies include gallium arsenide substrates for near-infrared emitters, precision optical glass for iris capture lenses, and rare-earth elements for sensor magnetics. Single-source vulnerability concentrates in advanced CMOS foundry capacity for high-resolution facial capture arrays. Distribution runs through federal contracting corridors in the Washington D.C. metropolitan area, with system integrators managing downstream deployment to agency sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's provincial privacy compliance costs run substantially below United States federal certification overhead, creating arbitrage potential for vendors structuring algorithm development through Montreal-Thales integration partnerships while serving both markets.
For Market Incumbents: Anticipate margin compression from emerging edge-processing entrants by accelerating multimodal fusion R&D and securing exclusive NIST evaluation partnerships that extend certification lead times for challengers. Vertical integration into specialized sensor foundry relationships reduces single-source exposure for iris and facial capture modules. Defensive patent positioning around anti-spoofing liveness detection creates licensing revenue streams from mid-tier algorithm specialists. For New Entrants and Emerging Players: The price-point gap between premium FBI-certified platforms and uncertified state-local alternatives enables mid-market positioning through SaaS-tiered biometric-as-a-service offerings with rapid provincial pilot-to-scale pathways. Mexico's underpenetrated land port checkpoint infrastructure presents the most penetrable geography, with Instituto Nacional de Migración procurement aligning with USMCA security cooperation frameworks. Go-to-market execution should leverage Canadian provincial privacy rulings as faster qualification pathways relative to United States federal timelines. For Investors and Strategic Acquirers: Roll-up economics work for embedded edge-processing specialists because DoD and critical infrastructure procurement is displacing centralized architectures toward on-device inference capabilities. Five-to-ten-year viability hinges on sustained NIST test protocol evolution that perpetuates vendor requalification cycles and consolidates algorithm licensing revenue around certified incumbents. Acquisition target archetype: mid-cap firms with Health Canada or RCMP operational specifications that unlock Canadian federal procurement access. The signal to watch is CBP and TSA pilot-to-production timeline compression, which accelerates vendor selection velocity and rewards pre-positioned platform capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| NIST Certification Investment | FBI MINEX and FRVT qualification pathways lock in federal procurement eligibility and sustain replacement demand cycles. |
| Multimodal Fusion Development | DHS and CBP specifications now mandate integrated fingerprint-facial-iris configurations, disqualifying single-modality vendors. |
| Edge Processing Architecture Shift | DoD critical infrastructure requirements for network-independent authentication are displacing centralized matching systems. |
| Mexico Border Infrastructure Expansion | Instituto Nacional de Migración checkpoint modernization at Tijuana and Ciudad Juárez opens iris recognition deployment opportunities. |
| Behavioral Biometric Convergence | Keystroke dynamics and gait analysis integration creates differentiated continuous authentication offerings for sensitive facilities. |
Research Methodology
Direct dialogue with biometric system procurement officers at DHS and DoD, algorithm scientists with NIST evaluation experience, federal contracting executives, and state-level AFIS administrators grounded qualitative findings in operational constraints and certification timelines. Secondary validation drew from FBI MINEX and FRVT test protocol documentation, CBP and TSA budget justification materials, Health Canada privacy framework rulings, and SEC filings from publicly traded biometric technology providers. Bottom-up segment sizing triangulated against top-down federal budget allocation analysis across the analysis window.
Model outputs projected value expansion across product type, end user, technology, and application dimensions, with cross-segment interaction effects captured through multiplicative decomposition. CAGRs derived from logistic adoption curves fitted to federal procurement cycle data, adjusted for NIST test timeline compression and provincial privacy fragmentation delays. Industry-specific forecast inputs included DHS biometric identity assurance budget trajectories and RCMP criminal identification network upgrade schedules.
Caveats apply where NIST demographic parity requirement evolution or Canada provincial privacy ruling divergence could materially shift the outlook for facial recognition deployment eligibility. Forecasts rest on assumptions regarding sustained federal multi-source procurement mandates and semiconductor foundry capacity allocation for specialized sensor production. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
Global Voice Biometrics Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Global Biometric Authentication Identification Market
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
Biometrics As a Service in Healthcare Market
Biometrics & Identity Management
Flash Calling Authentication Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Passive Authentication Market