
 Hypoallergenic Dog Food Market | 2026-2036
Hypoallergenic Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Hypoallergenic Dog Food Market Insights
Pet owner purchasing around hypoallergenic formulations is consolidating toward households with diagnosed atopic or food-intolerant dogs. Mars Petcare, Inc. leverages its veterinary clinic partnerships to channel prescription diets through licensed practitioners. Hill's Pet Nutrition anchors its position through science-backed clinical nutrition protocols developed in collaboration with veterinary dermatologists. Nestlé Purina Pet Care competes by sustaining broad retail distribution while maintaining specialized therapeutic sub-brands.
Hypoallergenic dog food denotes formulations engineered to exclude common allergens—typically beef, dairy, wheat, chicken egg, soy, or corn—through limited ingredient decks or novel protein sources such as kangaroo, venison, or hydrolyzed proteins, with manufacturing protocols enforcing strict line segregation to prevent cross-contact. The primary commercial purpose centers on mitigating cutaneous and gastrointestinal adverse food reactions in canines while supporting nutritional adequacy per AAFCO profiles. Dry food occupies the largest volume position due to shelf stability and cost efficiency, yet freeze-dried segments command premium margin pools through minimal processing claims and raw-adjacent positioning. Online retailers represent the fastest-growing distribution channel, displacing traditional pet specialty stores as subscription models and tele-veterinary referrals converge.
The FDA Center for Veterinary Medicine oversees ingredient safety and facility registration, while AAFCO establishes model nutritional adequacy standards that most U.S. states adopt into feed control laws. State-level feed officials conduct label audits and facility inspections that determine market access for new entrants. Stakeholders must monitor evolving enforcement priorities around "hypoallergenic" marketing claims, as regulatory scrutiny tightens on substantiation for absence-of-allergen assertions.
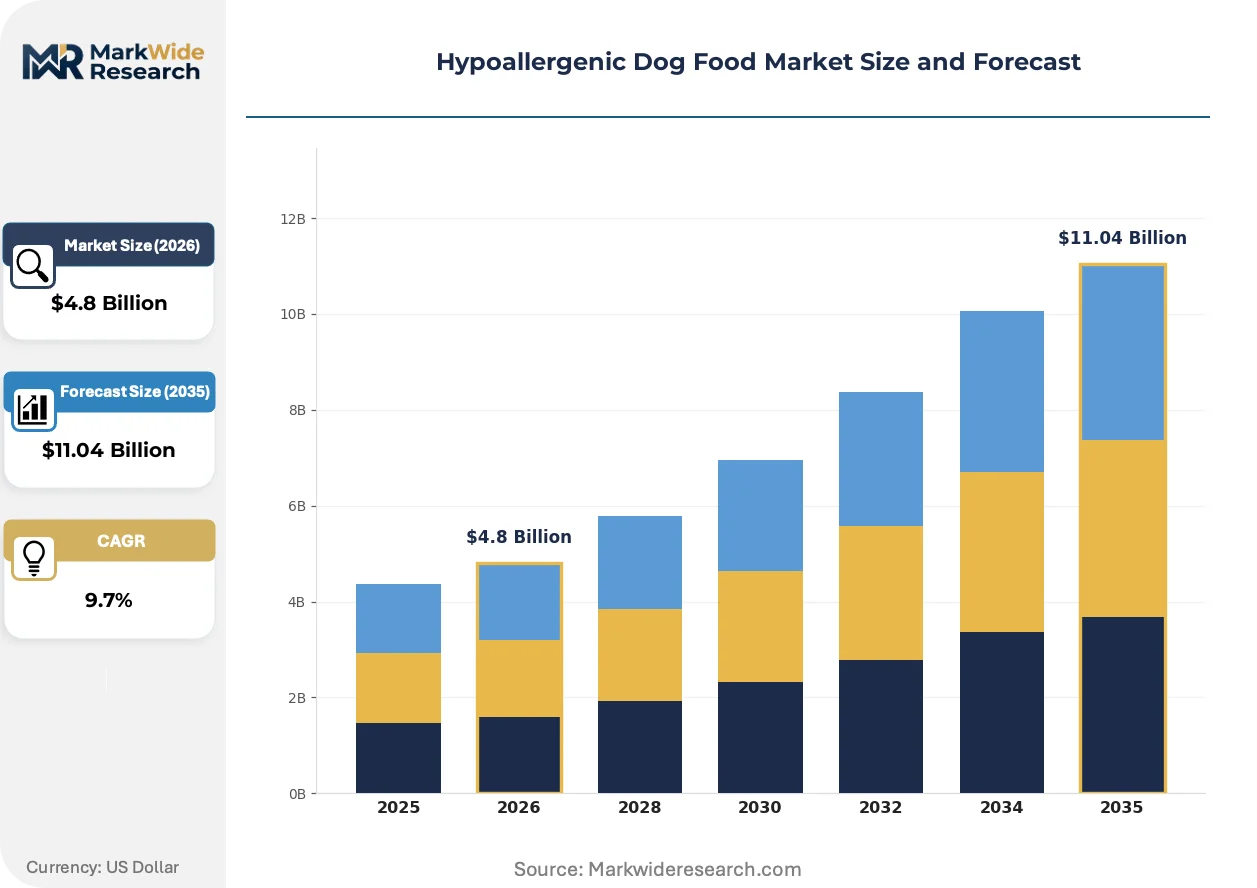
Market Dynamics
Veterinary channel consolidation is concentrating purchasing power among clinic networks that demand clinical trial substantiation for allergen exclusion claims, forcing manufacturers to invest in dermatological research partnerships or face delisting.
Growth Catalysts
- Novel Protein Sourcing:Kangaroo, venison, and insect-based formulations are expanding the addressable population of food-intolerant dogs beyond traditional limited-ingredient diets. Veterinary dermatologists increasingly prescribe these alternatives before immunotherapy.
- FDA Labeling Enforcement:The Center for Veterinary Medicine's tightened scrutiny on "hypoallergenic" marketing claims is advantaging manufacturers with validated manufacturing protocols and documented line segregation procedures.
- Subscription Commerce:Direct-to-consumer platforms with integrated tele-veterinary consultation are capturing households seeking convenience without sacrificing professional guidance on elimination diet protocols.
Market Restraints
- Hydrolyzed Protein Input Costs:Enzymatic processing of chicken and soy proteins requires specialized fermentation capacity concentrated among European and North American suppliers, creating margin compression during energy price volatility.
- Cross-Contact Prevention Infrastructure:Dedicated production lines and validated cleaning protocols impose capital requirements that exclude smaller co-manufacturers from therapeutic diet contracts.
- Diagnostic Access Limitations:Serum IgE testing and elimination diet trials remain cost-prohibitive for uninsured pet populations, constraining addressable demand to insured or affluent households.
Strategic Opportunities
- Freeze-Dried Raw Adjacent Positioning:Minimal processing claims are commanding premium shelf placement in independent pet specialty retailers seeking differentiation from mass-market therapeutic brands.
- AAFCO Nutritional Adequacy Expansion:State feed control officials are adopting updated model standards for growth and reproduction claims, enabling life-stage specific hypoallergenic formulations previously restricted to maintenance diets.
- Tele-Veterinary Referral Integration:Digital clinic platforms are creating closed-loop ecosystems where diagnostic consultation, prescription authorization, and auto-ship fulfillment consolidate within single-provider relationships.
Industry Challenges
- Veterinary Nutrition Specialist Scarcity:Board-certified veterinary dermatologists and nutritionists remain concentrated in academic medical centers and urban referral practices, limiting clinical trial capacity and prescriber education reach.
- Ingredient Traceability Documentation:Lot-level tracking from novel protein farms through hydrolysis facilities to finished goods requires ERP system investments that strain mid-tier manufacturer cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypoallergenic Dog Food Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Freeze-Dried Ingredient Source: Grain-Free, Novel Protein, Limited Ingredient, Organic Distribution Channel: Pet Specialty Stores, Online Retailers, Supermarkets, Vets Customer Segment: Pet Owners, Breeders, Pet Stores, Shelters |
| Companies Covered | Mars Petcare, Inc., Nestlé Purina Pet Care, Hill's Pet Nutrition, J.M. Smucker, Royal Canin Veterinary Diet, Canidae, Diamond Pet Foods, Merrick, Earthborn Holistic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypoallergenic Dog Food Market Trends and Innovations
Processing technology and distribution infrastructure are converging to collapse the traditional separation between prescription therapeutic diets and premium retail wellness formulations.
Hydrolyzed protein technology is absorbing the functional requirements previously reserved for pharmaceutical-grade allergen immunotherapy. Veterinary teaching hospitals are adopting these formulations as first-line intervention for canine atopic dermatitis, compressing the trial period before biologic therapy. This absorption is restructuring the competitive boundary between nutritional and pharmaceutical intervention categories.
The FDA Center for Veterinary Medicine is intensifying enforcement against unverified "grain-free" and "limited ingredient" positioning claims. Manufacturers now face warning letter risk for implied allergen absence without documented analytical testing. Therapeutic sub-brands with veterinary clinic distribution are responding by segregating prescription-only SKUs from retail-adjacent marketing entirely.
Subscription auto-replenishment with embedded veterinary consultation is displacing episodic retail purchasing for households managing chronic food intolerance. Independent tele-veterinary platforms are capturing these relationships through diagnostic-first onboarding that routes directly to partnered manufacturer fulfillment. This channel migration is most visible in coastal metropolitan markets with high pet insurance penetration and limited brick-and-mortar specialty retail density.
Hypoallergenic Dog Food Market Segmentation
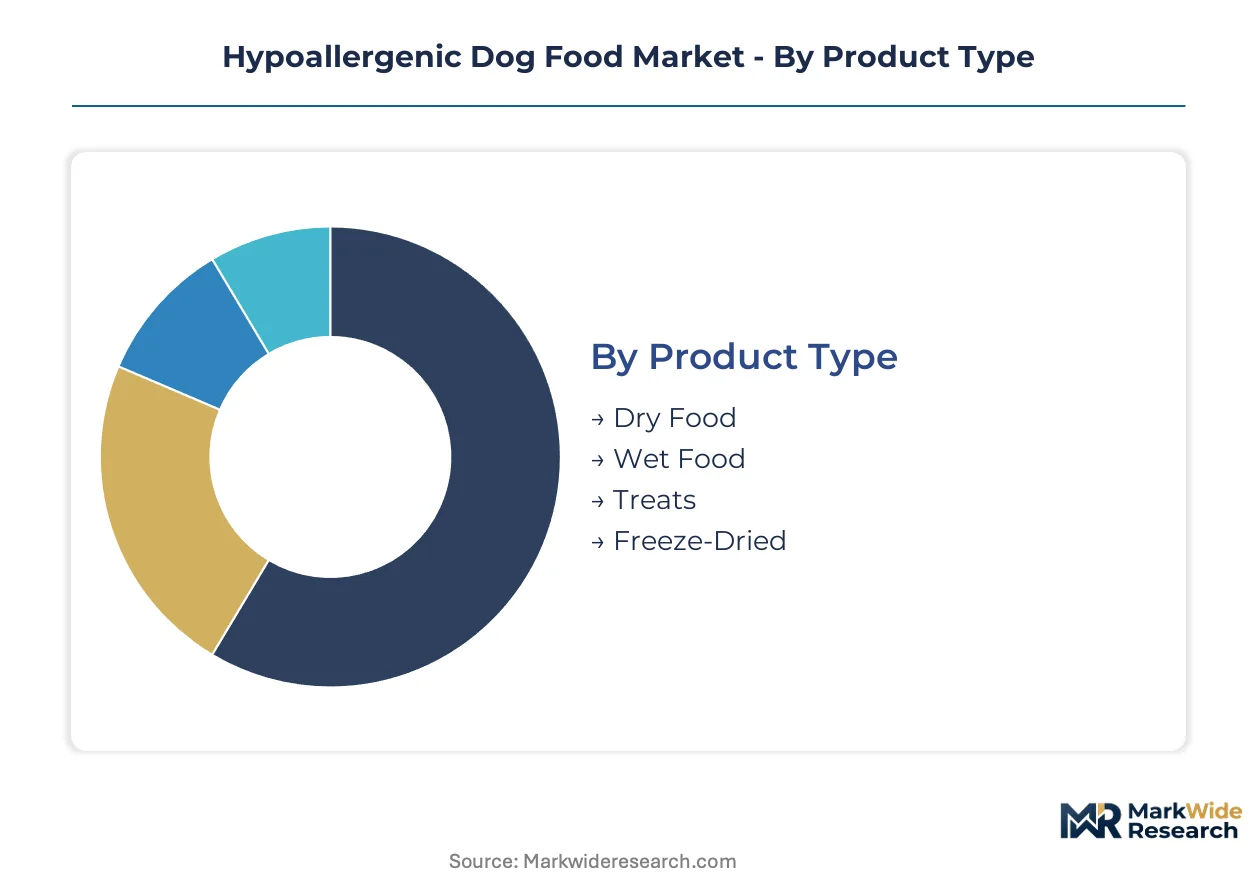
Hypoallergenic dog food segmentation reflects divergent certification burdens across therapeutic and wellness-positioned tiers. Veterinary prescription channels demand substantiated allergen exclusion protocols, while retail-facing segments compete on ingredient transparency claims.
Product Type:
Dry formulations carry the heaviest AAFCO nutritional adequacy documentation requirements, while freeze-dried segments face intensified FDA scrutiny on raw-adjacent pathogen control claims.
- Dry Food:Extruded kibble formulations dominate commercial volumes through shelf stability and cost efficiency. Demand concentrates in multi-dog households seeking long-term elimination diet maintenance, constrained by veterinary skepticism toward non-prescription dry alternatives for diagnosed atopic cases.
- Freeze-Dried:Minimal processing protocols retain native protein structures while achieving commercial sterility through sublimation. Coastal metropolitan markets with high pet insurance penetration drive adoption, attracted by raw-nutritional positioning without frozen supply chain requirements.
- Wet Food:Canned formulations serve transition phases in elimination diet protocols with higher palatability acceptance.
- Treats:Limited-ingredient chewables function as compliance tools within strict dietary regimens.
Leading the category by volume: Dry Food. Growing fastest: Freeze-Dried.
Ingredient Source:
Margin structures stratify sharply between commodity-exclusion positioning and novel protein sourcing, with hydrolyzed variants commanding the steepest premium tiers.
- Novel Protein:Kangaroo, venison, and insect-based formulations bypass established allergen recognition patterns in sensitized dogs. Veterinary dermatologists in academic medical centers increasingly prescribe these as first-line intervention before immunotherapy, though farm-to-facility traceability documentation strains mid-tier manufacturer ERP capabilities.
- Limited Ingredient:Single-source protein decks with simplified carbohydrate matrices reduce cross-reaction probability. Breeders and show kennels in suburban markets prioritize these for prophylactic feeding of allergy-prone lineages.
- Grain-Free:Excludes wheat, corn, and soy regardless of individual tolerance status.
- Organic:USDA-certified ingredient sourcing with prohibited synthetic additive lists.
Widest distribution penetration: Limited Ingredient. Steepest price premium: Novel Protein.
Distribution Channel:
Channel selection determines regulatory exposure, with veterinary clinics bearing FDA prescription diet oversight while online platforms navigate state feed control label audits.
- Vets:Clinic-network distribution requires clinical trial substantiation for allergen exclusion claims and documented line segregation protocols. Prescription authorization workflows capture insured households with diagnosed atopic dermatitis, creating sticky manufacturer relationships through tele-veterinary platform integration.
- Online Retailers:Direct-to-consumer platforms with subscription auto-replenishment displace episodic purchasing. Auto-ship fulfillment with embedded veterinary consultation captures convenience-seeking households in brick-and-mortar retail deserts.
- Pet Specialty Stores:Independent retailers seek freeze-dried differentiation from mass-market therapeutic brands.
- Supermarkets:Mass-market placement emphasizes price-accessible limited-ingredient positioning.
Highest customer lifetime value: Vets. Expanding most quickly: Online Retailers.
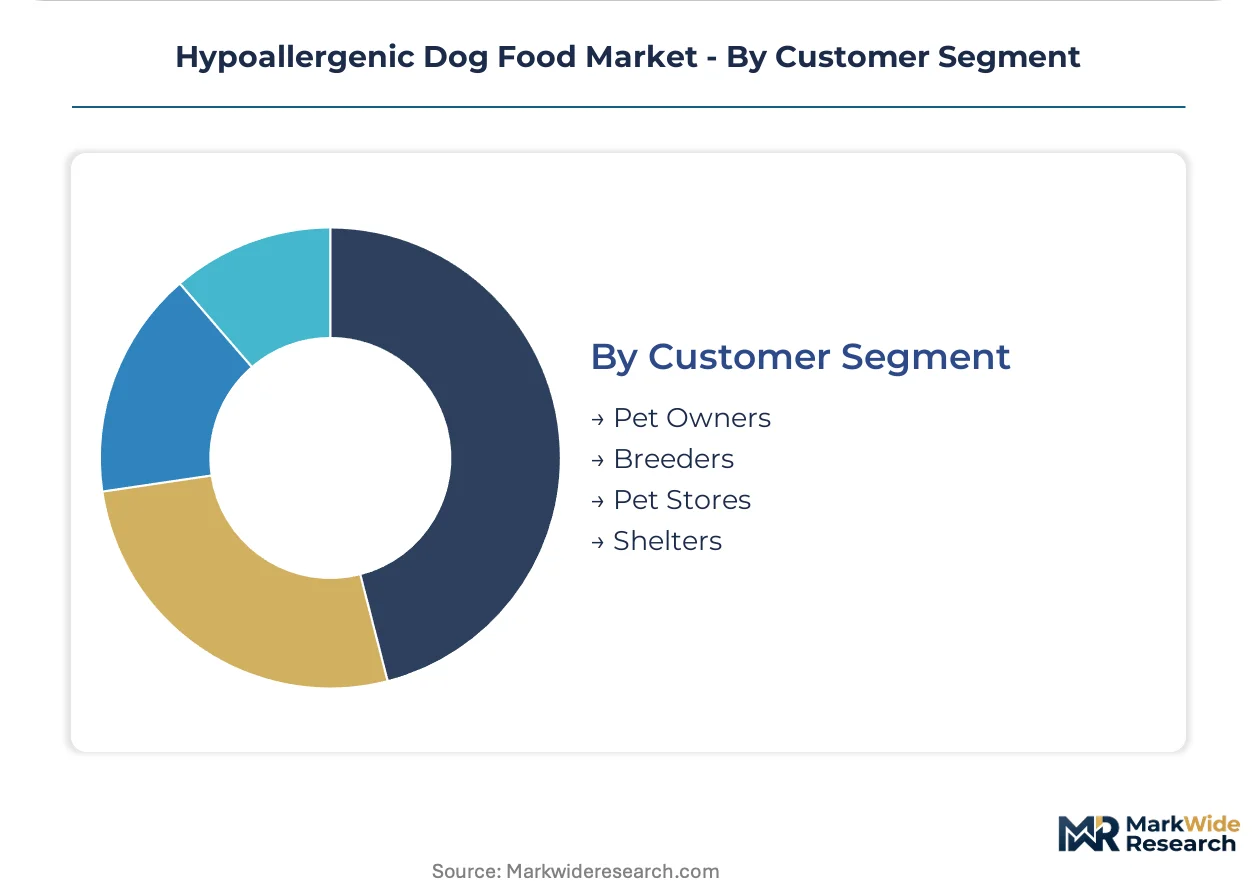
Customer Segment:
Diagnostic access and insurance penetration create stark purchasing power stratification across household types.
- Pet Owners:Insured households with diagnosed food-intolerant dogs drive prescription diet volumes and subscription loyalty. Affluent coastal markets sustain premium freeze-dried adoption despite per-pound cost multiples over dry alternatives.
- Breeders:Prophylactic feeding protocols for allergy-prone lineages sustain limited-ingredient demand with batch-consistency requirements.
- Pet Stores:Retail inventory decisions favor SKUs with broad allergen exclusion claims and visible ingredient transparency.
- Shelters:Budget-constrained procurement prioritizes cost-effective limited-ingredient options for intake populations with unknown dietary histories.
Dominant volume concentration: Pet Owners. Fastest-growing engagement: Breeders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for hypoallergenic dog food concentrates in affluent metropolitan areas with high pet insurance penetration and established veterinary specialty infrastructure. The United States anchors absolute consumption volumes through its dense network of veterinary dermatology referral practices. Western European markets follow with comparable diagnostic access but stricter regulatory frameworks governing allergen claims.
United States
Insured households in coastal metropolitan corridors drive prescription diet volumes through tele-veterinary platforms with integrated auto-ship fulfillment. The FDA Center for Veterinary Medicine enforces tightened substantiation standards for "hypoallergenic" marketing claims through warning letter programs. Greater Boston and the San Francisco Bay Area concentrate board-certified veterinary dermatologists who channel elimination diet protocols through academic medical center partnerships.
Germany
Prophylactic feeding protocols among show kennels and breeding associations sustain demand for limited-ingredient formulations with batch-traceability documentation. EFSA establishes novel protein safety assessments that manufacturers must complete before kangaroo or insect-based ingredient authorization. The Munich-Stuttgart corridor hosts specialized pet food research facilities developing hydrolyzed protein processing protocols for export markets.
United Kingdom
Subscription commerce penetration in London and Southeast England displaces traditional pet specialty retail through digital-first veterinary consultation models. The Food Standards Agency coordinates with veterinary regulators on allergen labeling enforcement for cross-border e-commerce shipments. The Cambridge-Oxford cluster attracts venture investment in tele-veterinary platforms targeting chronic condition management.
Japan
Urban pet owners in Tokyo and Osaka metropolitan areas sustain premium positioning for freeze-dried formulations with minimal processing claims. METI oversees pet food manufacturing standards that incorporate AAFCO nutritional adequacy references for export-oriented producers. The Nagoya industrial zone concentrates specialized extrusion equipment fabricators serving domestic hypoallergenic product lines.
Australia
Kangaroo protein sourcing advantages position domestic manufacturers to supply novel protein formulations across Asia-Pacific export channels. The Department of Agriculture enforces biosecurity protocols for wild-harvested game meats entering pet food processing facilities. Sydney and Melbourne veterinary teaching hospitals conduct clinical trials on Australian-sourced novel proteins for atopic dermatitis intervention protocols.
Hypoallergenic Dog Food Market Competitive Landscape
North American producers anchor the prescription therapeutic tier; European specialists hold premium positioning in novel protein sourcing and minimal processing claims. Market structure concentrates among vertically integrated conglomerates with captive veterinary distribution networks and mid-tier co-manufacturers serving private-label retail programs. Three archetypes dominate: clinic-network-integrated prescription diet providers, direct-to-consumer subscription platforms with tele-veterinary partnerships, and independent specialty brands competing on ingredient transparency. Capacity expansion into dedicated allergen-segregated production lines and strategic partnerships with diagnostic laboratory networks represent the dominant competitive moves.
Within the conglomerate tier, Mars Petcare, Inc. and Nestlé Purina Pet Care exemplify vertically integrated structures with global manufacturing footprints and established veterinary channel relationships. Hill's Pet Nutrition occupies a distinct position through its science-backed clinical nutrition protocols developed in collaboration with academic veterinary centers. These three entities represent the dominant competitive anchors against which mid-tier specialists and digital-native entrants position differentiation strategies.
| Leading Market Players |
|---|
| Mars Petcare, Inc. |
| Nestlé Purina Pet Care |
| Hill's Pet Nutrition |
| J.M. Smucker |
| Royal Canin Veterinary Diet |
| Canidae |
| Diamond Pet Foods |
| Merrick |
| Earthborn Holistic |
| Others |
Pricing and Supply Chain Analysis
AAFCO nutritional adequacy certification gates both qualified ingredient supply and premium-tier pricing access, as manufacturers lacking documented line segregation protocols face exclusion from veterinary prescription channels where margins concentrate. Price differentiation separates hydrolyzed protein formulations commanding veterinary-clinic premiums from retail-limited-ingredient alternatives competing on shelf accessibility.
Pricing Analysis
The volume-mass split positions dry extruded kibble as the cost-accessible workhorse for multi-dog households, while freeze-dried segments capture margin premiums through minimal processing claims and raw-adjacent positioning. Price differentiation hinges on certification grade—FDA-substantiated allergen exclusion protocols versus transparency-marketing claims—and volume scale, with subscription auto-replenishment softening per-unit sticker shock. Pricing pressure stems from hydrolyzed protein input costs, as enzymatic processing capacity concentrates among European and North American fermentation specialists. Uninsured pet owners exhibit acute price sensitivity, driving demand toward supermarket limited-ingredient options; insured households with diagnosed atopic dogs absorb premium pricing through veterinary channel lock-in.
Supply Chain Analysis
Domestic-content mandates in Australia and Germany reshape sourcing for novel protein formulations, requiring wild-harvested kangaroo traceability documentation and EFSA safety assessments before market authorization. Supply concentrates in the United States, Australia, and Germany, with kangaroo protein sourcing advantages positioning Australian manufacturers for Asia-Pacific export channels. Raw material dependencies include hydrolyzed chicken and soy proteins, insect meal for emerging alternative formulations, and wild-harvested game meats subject to biosecurity protocols. Single-source vulnerability runs through European fermentation capacity for enzymatic protein processing. Distribution runs through veterinary clinic networks for prescription tiers, direct-to-consumer platforms for subscription segments, and independent pet specialty for freeze-dried differentiation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dedicated allergen-segregated production line scarcity props pricing power for incumbent manufacturers, constraining mid-tier expansion and preserving margin pools in therapeutic tiers.
For Market Incumbents: Anchor market position through captive supply of hydrolyzed protein processing capacity in North America and Europe, insulating against energy-price volatility that compresses margins. Deepen veterinary clinic network integration through tele-platform partnerships that consolidate diagnostic consultation, prescription authorization, and auto-ship fulfillment within single-provider relationships. Defend against digital-native entrants by segregating prescription-only SKUs from retail-adjacent marketing to preempt FDA warning letter exposure. For New Entrants and Emerging Players: Insect-based protein technology offers a wedge into coastal metropolitan markets with high pet insurance penetration and limited brick-and-mortar specialty retail density. Target freeze-dried segments in independent pet specialty channels seeking differentiation from mass-market therapeutic brands. Pursue white-space in tele-veterinary platform partnerships that route diagnostic-first onboarding directly to partnered manufacturer fulfillment, bypassing traditional distribution. For Investors and Strategic Acquirers: FDA warning letter issuance against unverified "hypoallergenic" marketing claims is the leading indicator that regulatory scrutiny is tightening substantiation requirements, advantaging manufacturers with validated manufacturing protocols. Long-term viability centers on acquisition targets possessing documented line segregation procedures and clinical trial partnerships with academic veterinary centers. Watch for tele-veterinary platform consolidation signals as diagnostic laboratory networks seek captive supply agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dedicated allergen-segregated production lines unlock veterinary prescription channel access and margin premiums. |
| Backward Integration | In-house hydrolyzed protein fermentation capacity insulates against European supplier energy-price volatility. |
| Strategic Partnership | Tele-veterinary platform integration consolidates diagnostic-to-fulfillment workflows and subscription loyalty. |
| Regulatory Approval Pathway | AAFCO nutritional adequacy expansion for life-stage claims opens growth-stage and reproduction formulation markets. |
| Product Launch | Novel protein sourcing from kangaroo or insect meal bypasses established allergen recognition in sensitized dogs. |
Research Methodology
Multi-period observation of veterinary prescription volume trends, tele-veterinary platform penetration rates, and FDA warning letter patterns anchored the trend analysis, supplemented by interviews with veterinary dermatologists, pet food manufacturing executives, state feed control officials, and subscription commerce operators. Secondary validation drew from AAFCO model standard updates, FDA Center for Veterinary Medicine enforcement disclosures, EFSA novel protein safety assessments, and customs records of hydrolyzed protein ingredient trade flows. Bottom-up segmentation modeling triangulated against top-down category spend estimates from pet insurance claims databases.
The input-output matrix framed demand drivers across product type, ingredient source, distribution channel, and customer segment dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted projections of insured household expansion, veterinary specialist concentration growth, and subscription commerce adoption curves. Industry-specific forecast inputs included diagnostic access cost curves for serum IgE testing and elimination diet trials, plus ERP system penetration rates among mid-tier manufacturers for traceability documentation compliance.
Several conditions sit outside the modeled scope, including raw-pathogen outbreak events triggering FDA enforcement surges, trade disruption affecting Australian kangaroo protein export channels, and breakthrough biologic therapies displacing nutritional intervention for atopic dermatitis. Forecasts reflect documented assumptions around regulatory enforcement continuity and veterinary channel consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Noise Anxiety Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Dog Brush Market
Pet Care Products
Pet Care Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Cat Litter Boxes Market