
 Europe Pet Clothing Market | 2026-2036
Europe Pet Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pet Clothing Market Insights
Millennial urban pet owners is reorganizing demand away from purely functional winter gear toward fashion-driven seasonal collections. Hurtta leverages its Nordic heritage to sustain technical credibility in performance outerwear for active dogs. Mungo & Maud differentiates through British-crafted luxury positioning that commands boutique placement across London and Paris. Ruffwear anchors the adventure-travel segment with specialized harness-compatible designs that dominate specialty retail in Germany and Scandinavia.
Europe pet clothing encompasses functional and decorative garments engineered from woven, knitted, or bonded textiles with specifications including waterproof ratings, breathability indices, and reflective safety elements, manufactured through cut-and-sew, seamless knitting, or thermal bonding processes to protect animals from weather extremes or express owner aesthetics. Coats and sweaters capture the largest volume share due to climatic necessity across Northern Europe, while dresses and T-shirts represent the fastest-expanding category as fashion adoption accelerates in Mediterranean markets. The price tier structure concentrates margin pools at premium and luxury levels where material provenance and artisan construction justify elevated price points, whereas budget segments compete on volume through supermarket and mass online channels.
REACH regulations from ECHA restrict hazardous dyes and chemical finishes, compelling reformulation of textile treatments across the supply chain. CE marking requirements under EU product safety frameworks mandate flammability and mechanical safety testing for pet accessories sold within member states. The EU Green Deal carbon-border adjustments will incrementally raise input costs for polyester-dependent producers. Stakeholders must monitor pending textile waste directives that could mandate recycled content minimums and extended producer responsibility schemes before committing to multi-year material contracts.
Market Dynamics
REACH chemical standards from ECHA are forcing wholesale reformulation of textile treatments across European pet apparel supply chains, while the EU Green Deal's carbon-border adjustments compress margins for polyester-dependent producers. These regulatory pressures intersect with millennial demand for fashion-forward seasonal collections to reshape competitive positioning.
Growth Catalysts
- EU Green Deal carbon-border adjustments:The phased implementation of carbon pricing on imports is accelerating domestic sourcing of organic cotton and recycled polyester among brands seeking to preempt cost penalties.
- Pet humanization in urban Germany:Berlin and Munich households now allocate discretionary spending toward coordinated owner-pet apparel, expanding addressable market beyond functional necessity into aesthetic expression.
- Seamless knitting technology:Advanced circular knitting systems reduce material waste by eliminating cut-and-sew operations, aligning production economics with circular economy mandates.
Market Restraints
- REACH compliance costs:ECHA-mandated substitution of azo dyes and formaldehyde-based finishes raises raw material expenses for small-batch artisan producers.
- Recycled polyester supply concentration:European rPET flake production clusters in Germany and the Netherlands, creating geographic vulnerability for brands dependent on localized circular feedstock.
- Technical limitation in waterproof breathability:Existing solvent-free membrane technologies fail to match performance specifications of conventional PU coatings, constraining premium outerwear development.
Strategic Opportunities
- Underpenetrated Mediterranean markets:Spain and Portugal exhibit lower pet clothing penetration rates than Northern Europe, presenting first-mover advantage for seasonal lightweight collections.
- Extended producer responsibility schemes:Pending EU textile waste directives will mandate take-back programs, rewarding brands with established reverse logistics infrastructure.
- Digital-first DTC channel innovation:Social commerce integration via Instagram and TikTok shops is displacing traditional boutique wholesale in France and the United Kingdom.
Industry Challenges
- Technical talent scarcity in sustainable chemistry:Formulation chemists capable of developing REACH-compliant water-repellent finishes command premium compensation, constraining R&D expansion.
- Multi-jurisdictional certification timelines:CE marking requirements under EU product safety frameworks delay market entry by 4-8 months for harness-integrated apparel designs.
- Legacy ERP integration with traceability systems:Batch-level organic cotton tracking demands middleware investment that mid-tier producers struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pet Clothing Market |
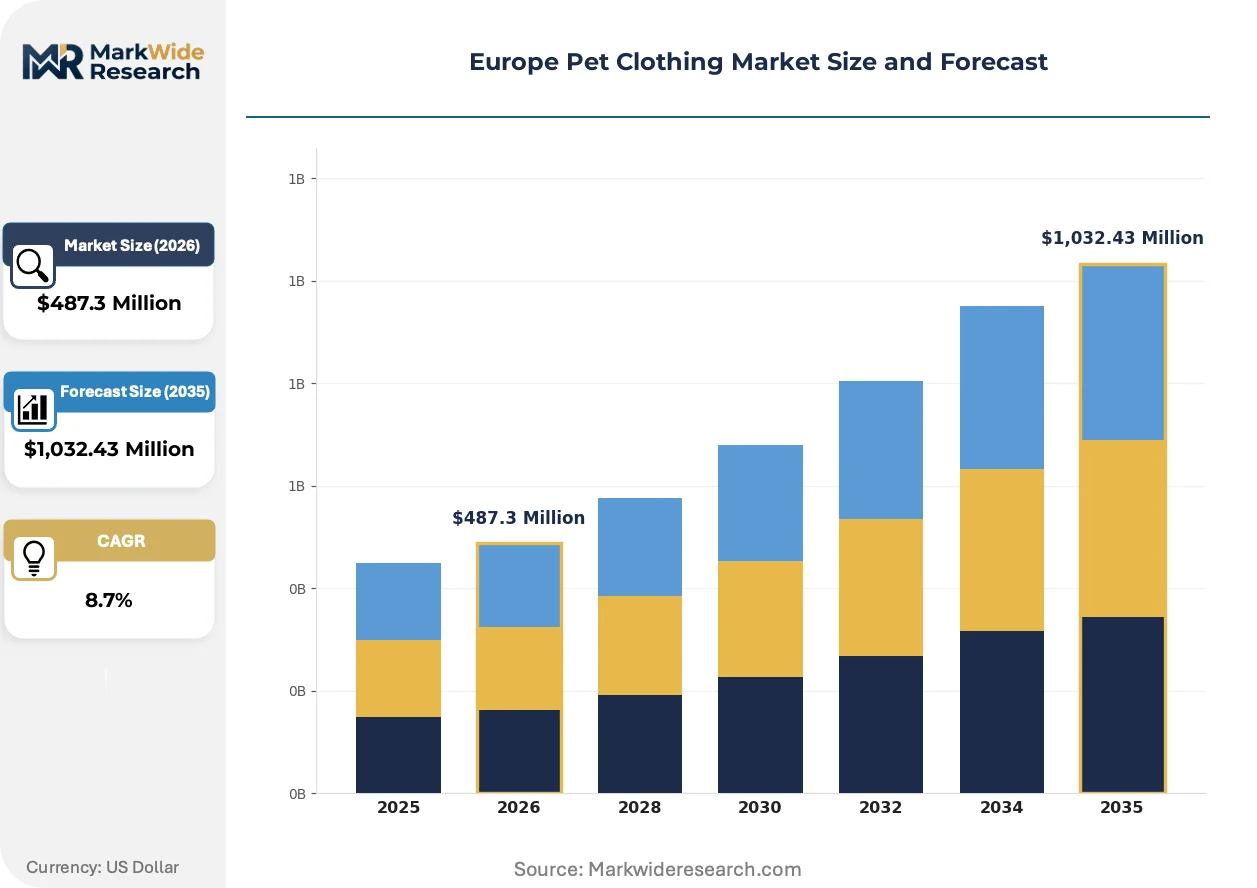
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shirts, Sweaters, Coats, Dresses Animal Type: Dogs, Cats, Rabbits, Ferrets Sales Channel: Online Retail, Specialty Stores, Supermarkets, Pet Boutiques Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Hurtta, Mungo & Maud, Ruffwear, Canada Pooch, Lucy & Co, Wagwear, H&M, Gucci Pet Collection, Ralph Lauren, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pet Clothing Market Trends and Innovations
Digital design-to-manufacture workflows and bio-based material science are compressing development cycles while regulatory chemistry constraints force innovation in functional finishes. These shifts are concentrating competitive advantage among vertically integrated producers with captive R&D capabilities.
Seamless 3D knitting technology is displacing conventional cut-and-sew construction in mid-premium sweater and coat production. German specialty mills in Saxony and Bavaria are deploying Shima Seiki WHOLEGARMENT systems to eliminate seam allowances and reduce labor content. This displacement is compressing lead times from six weeks to ten days while enabling mass-customization of fit parameters for brachycephalic breeds.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling reformulation of durable water-repellent treatments across the supply chain. ECHA's 2023 PFAS restriction proposal mandates substitution of C6 fluorocarbon chemistry by 2026, forcing brands to validate bio-based alternatives. Performance outerwear segments in Scandinavia and the Alpine region face the steepest compliance burden given functional requirements.
Subscription-based seasonal wardrobe services are displacing transactional e-commerce among urban millennial cohorts. Paris and London-based platforms now offer quarterly curated boxes with sizing algorithms and return-free exchanges. This model concentrates customer lifetime value while reducing return rates that previously eroded margin on fit-sensitive categories like dresses and harness-compatible coats.
Europe Pet Clothing Market Segmentation
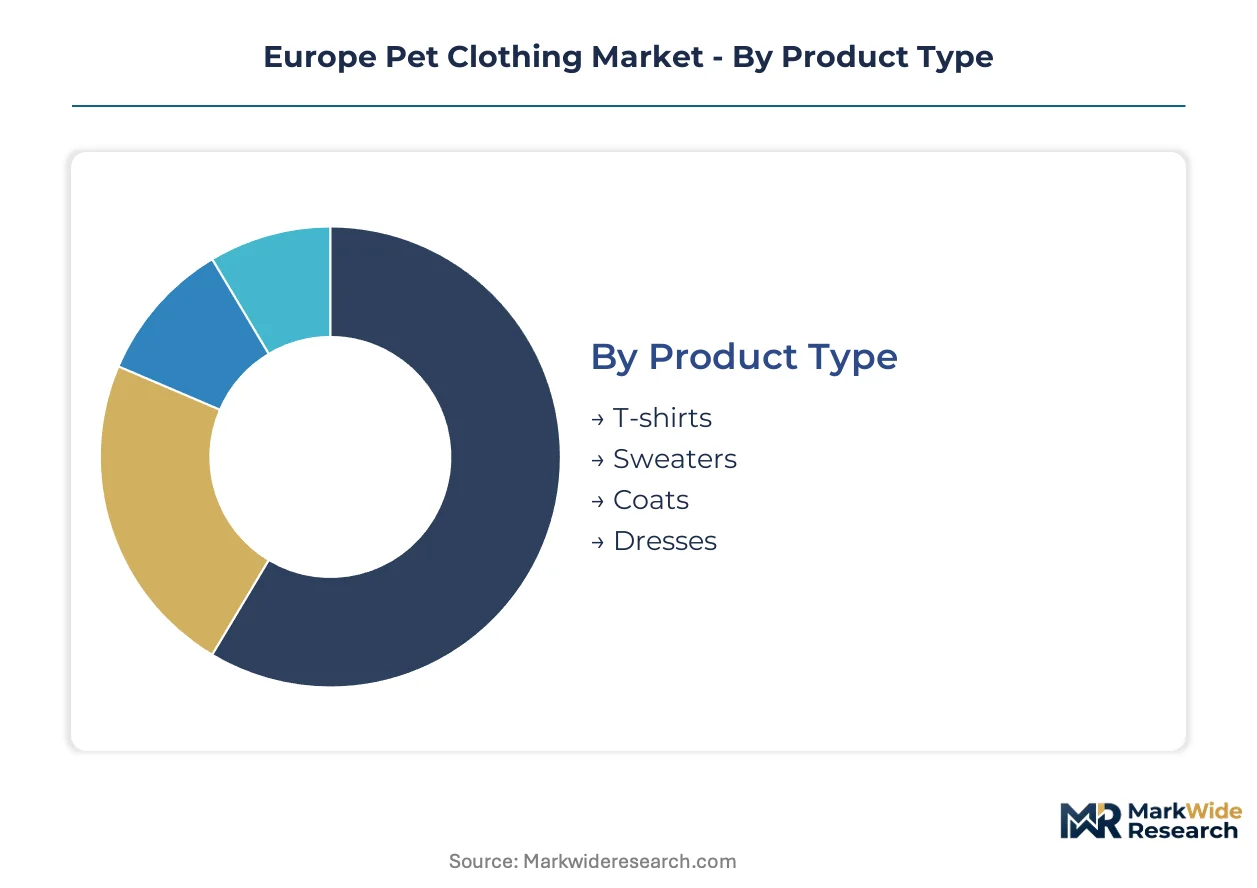
Segmentation in the Europe Pet Clothing Market reveals how regulatory chemistry constraints and millennial fashion preferences split demand across incompatible value chains. Distinct margin pools form around technical performance requirements versus aesthetic expression, with channel access determining which producers capture sustainable profitability.
Product Type:
Margin pools concentrate in weather-functional categories where Nordic and Alpine geographies sustain premium pricing, while Mediterranean expansion shifts growth toward lightweight fashion pieces.
- Coats:Technical outerwear engineered with waterproof-breathable membranes and reflective safety elements dominates Northern European demand. German and Scandinavian households prioritize harness-compatible designs for active dogs, sustaining price premiums despite REACH-mandated reformulation of fluorocarbon-free finishes.
- Sweaters:Knitted garments utilizing seamless 3D construction from Saxony and Bavarian mills eliminate cut-and-sew waste while enabling brachycephalic breed customization. Paris and London subscription services now rotate seasonal collections as core customer acquisition tools.
- T-shirts:Lightweight cotton and bamboo-blend basics serve Mediterranean climate needs with lower technical barriers to entry.
- Dresses:Fashion-forward silhouettes with coordinated owner-pet aesthetics command boutique placement in urban France and United Kingdom.
Coats hold installed capacity across Nordic supply chains. Dresses is rotating up the share rankings as social commerce penetration accelerates in Southern Europe.
Animal Type:
Volume concentration tracks pet humanization intensity, with canine apparel capturing infrastructure investment while feline categories exploit underpenetrated whitespace.
- Dogs:Harness integration requirements and breed-specific sizing standards create technical moats for producers with parametric design capabilities. German working dog culture and British show circuits sustain diversified demand across performance and luxury tiers.
- Cats:Smaller average garment sizes and escape-resistant fastening challenges have delayed category maturation, though Parisian and Milanese urban cohorts now drive acceptance of seasonal indoor-outdoor transition pieces.
- Rabbits:Thermal regulation needs in Continental European indoor housing sustain niche demand for insulated carriers and exercise pen accessories.
- Ferrets:Elongated body proportions require specialized pattern grading that limits mass-market participation to dedicated exotic pet channels.
Dogs holds installed capacity. Cats is rotating up the share rankings as apartment-dwelling millennials expand feline ownership.
Sales Channel:
Channel economics diverge sharply between inventory-light digital models and experience-dependent physical retail, with regulatory traceability requirements favoring scaled operators.
- Online Retail:Direct-to-consumer platforms with AI-driven sizing algorithms and return-free exchange policies now capture urban millennial spending previously directed through boutiques. Instagram and TikTok shop integration in France and United Kingdom compresses customer acquisition costs versus traditional search advertising.
- Pet Boutiques:Curated merchandising with artisan provenance storytelling commands sustained loyalty among high-discretionary households in Berlin, Munich, and London.
- Specialty Stores:Harness fitting expertise and seasonal collection previews sustain relevance for technical outerwear categories.
- Supermarkets:Volume-driven basic sweaters and rain covers compete on price through centralized procurement of undifferentiated Asian supply.
Online Retail holds installed capacity. Pet Boutiques is rotating up the share rankings as experiential retail differentiates against algorithmic recommendation engines.
Price Tier:
Pricing stratification reflects material provenance transparency and regulatory compliance depth, with luxury tiers capturing margin from REACH-averse artisan positioning.
- Luxury:British-crafted construction with batch-level organic cotton tracking and CE-marked safety certification dominates London and Paris placement. ECHA chemical restrictions actually reinforce competitive moats for producers with captive sustainable chemistry R&D.
- Premium:Recycled polyester formulations with GRS chain-of-custody documentation satisfy German and Dutch consumer expectations for circular economy alignment.
- Mid-Range:Blended materials with basic REACH compliance serve price-conscious urban households through multi-brand specialty retail.
- Budget:Undisclosed fiber content and untraceable dye houses concentrate in supermarket and mass marketplace channels with minimal regulatory exposure.
Luxury holds installed capacity. Premium is rotating up the share rankings as carbon-border adjustments compress polyester-dependent budget tier economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial households with elevated pet humanization rates concentrate demand across Northern and Western Europe, while Mediterranean markets present whitespace for seasonal lightweight collections.
Germany
Berlin and Munich households drive coordinated owner-pet apparel spending through discretionary budgets allocated to aesthetic expression. ECHA REACH compliance mandates reformulation of textile treatments, raising input costs for domestic producers. Saxony and Bavaria host seamless knitting mill clusters deploying advanced circular systems for waste reduction.
United Kingdom
London's boutique ecosystem sustains artisan-crafted luxury positioning with batch-level organic cotton tracking requirements. CE marking under EU product safety frameworks governs harness-integrated designs despite post-Brexit regulatory divergence. British show circuits and working dog culture diversify demand across performance and premium tiers.
France
Parisian urban cohorts anchor subscription-based seasonal wardrobe services with AI-driven sizing algorithms. The EU Green Deal carbon-border adjustments compress margins for polyester-dependent importers. Île-de-France and Provence-Alpes-Côte d'Azur concentrate social commerce integration via Instagram and TikTok shop channels.
Italy
Milanese apartment-dwelling millennials expand feline ownership, driving acceptance of indoor-outdoor transition pieces. Pending EU textile waste directives threaten extended producer responsibility schemes for brands lacking reverse logistics. Lombardy and Veneto maintain specialized pattern grading capabilities for exotic pet proportions.
Spain
Lower pet clothing penetration rates relative to Northern Europe create first-mover opportunities for lightweight fashion collections. ECHA PFAS restriction proposals mandate C6 fluorocarbon substitution by 2026, affecting technical outerwear development. Madrid and Catalonia emerge as testing grounds for Mediterranean climate-appropriate designs.
Europe Pet Clothing Market Competitive Landscape
Player mix skews toward Nordic technical specialists and British luxury artisans competing against mass-fashion brand extensions. Market structure concentrates margin pools at premium tiers where material provenance and regulatory compliance depth create defensive moats. Three archetypes dominate: heritage outdoor performance brands, artisan-crafted luxury houses, and fast-fashion private label extensions. Competitive moves center on seamless technology licensing partnerships and carbon-border-adjustment-driven domestic sourcing commitments.
Within the heritage performance tier, Hurtta leverages Nordic technical credibility for active dog outerwear, while Ruffwear anchors adventure-travel positioning through harness-compatible specialization. Mungo & Maud occupies British-crafted luxury positioning commanding boutique placement across London and Paris. These three exemplify how regulatory chemistry constraints and millennial fashion preferences split competitive advantage across incompatible value chains.
| Leading Market Players |
|---|
| Hurtta |
| Mungo & Maud |
| Ruffwear |
| Canada Pooch |
| Lucy & Co |
| Wagwear |
| H&M |
| Gucci Pet Collection |
| Ralph Lauren |
| Others |
Pricing and Supply Chain Analysis
Long-term organic cotton offtake agreements with Saxony and Bavarian mills lock in both supply access and price visibility for premium European producers navigating EU Green Deal carbon-border adjustments.
Pricing Analysis
Cost-plus contracts with rPET flake indexation anchor mid-tier pricing to German and Dutch recycled polymer markets. Three-tier pricing structure across luxury, premium, and budget levels separates batch-level organic cotton tracking from GRS-certified recycled formulations from undisclosed fiber content. Cost compression in budget tiers intensifies because carbon-border adjustments erode polyester-dependent import economics. Supermarket and mass marketplace channels exhibit highest price sensitivity, while London and Paris boutique placement sustains luxury tier insensitivity.
Supply Chain Analysis
Germany and the Netherlands anchor rPET flake production for circular feedstock, while Portugal and Spain host cut-and-sew assembly for lightweight Mediterranean collections. European pet apparel draws from organic cotton cultivation in Turkey and Egypt, recycled polyester from German chemical recycling facilities, and seamless knitting machinery from Japanese Shima Seiki deployments. Single-source vulnerability concentrates in Saxony and Bavaria for 3D WHOLEGARMENT production capacity. Distribution runs through direct-to-consumer platforms with AI sizing algorithms, specialty retail with harness fitting expertise, and supermarket centralized procurement of undifferentiated Asian supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as millennial demand splits between technical performance requirements and aesthetic expression, creating incompatible value chain niches for specialized positioning.
For Market Incumbents: Secure captive sustainable chemistry R&D capabilities to preempt REACH Annex XVII PFAS substitution deadlines. Backward integration into organic cotton cultivation in Turkey and Egypt defends margin position against carbon-border adjustment cost compression. Channel control through subscription-based seasonal wardrobe services locks in customer lifetime value against algorithmic recommendation engines. For New Entrants and Emerging Players: Subscription-layer gaps in feline apparel and Mediterranean lightweight collections offer white-space entry where incumbents under-serve. Spain and Portugal present most penetrable geography for first-mover seasonal collections. Go-to-market through Instagram and TikTok shop integration in Paris and London compresses customer acquisition costs versus traditional search advertising. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with captive seamless knitting capacity and REACH-compliant water-repellent formulation capabilities. Long-term viability over the next decade rests on regulatory chemistry depth and reverse logistics infrastructure for pending extended producer responsibility schemes. Watch ECHA textile waste directive implementation timelines as inflection indicator for circular economy compliance moats.| Strategic Initiative | Industry Significance |
|---|---|
| Seamless Knitting Technology Licensing | Shima Seiki WHOLEGARMENT deployment eliminates cut-and-sew waste while enabling brachycephalic breed customization. |
| REACH-Compliant Finish Development | Bio-based water-repellent chemistry substitution defends premium outerwear positioning against ECHA PFAS restrictions. |
| Subscription Service Launch | Paris and London platforms with AI sizing algorithms concentrate customer lifetime value and reduce fit-sensitive return rates. |
| Domestic Sourcing Commitment | German and Dutch rPET flake procurement preempts EU Green Deal carbon-border adjustment penalties on polyester imports. |
| Reverse Logistics Infrastructure Buildout | Take-back program establishment rewards brands ahead of pending EU textile waste directive mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across brand managers at heritage performance and luxury artisan houses, category buyers at Berlin and London pet boutiques, procurement leads at German specialty mills, and channel heads at direct-to-consumer platforms. Secondary validation drew from ECHA REACH regulatory filings, EU Green Deal policy documentation, customs records for organic cotton and recycled polyester trade flows, and SEC filings for mass-fashion brand extensions. Bottom-up volume modeling from breed-specific sizing standards and top-down value triangulation from price tier distribution were cross-referenced.
Across the analysis window, forecasts segment by product type, animal type, sales channel, and price tier with regional regulatory cluster overlays. CAGRs derive from installed capacity assessments in seamless knitting and projected adoption curves for subscription services. Industry-specific inputs include REACH compliance cost pass-through rates and carbon-border adjustment elasticity estimates for polyester-dependent producers.
Underlying assumptions cover sustained millennial pet humanization spending patterns and ECHA enforcement timelines, with deviation risk concentrated in PFAS substitution technology readiness and recycled polyester supply concentration. Recalibration cycles align with material shifts in EU textile waste directive finalization and social commerce platform algorithm changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Tofu Cat Litter Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Bird Cages and Accessories Market
Pet Care Products
Dog Pen Market
Pet Care Products
Pet Hair Brush Market
Pet Care Products
Dry Pet Food Market
Pet Care Products
Global Pet Carriers Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Pet Hair Care Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Cat Harness Market
Pet Care Products
Pet Tick and Flea Prevention Market