
 Thailand Pet Food Market | 2026-2036
Thailand Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Pet Food Market Outlook
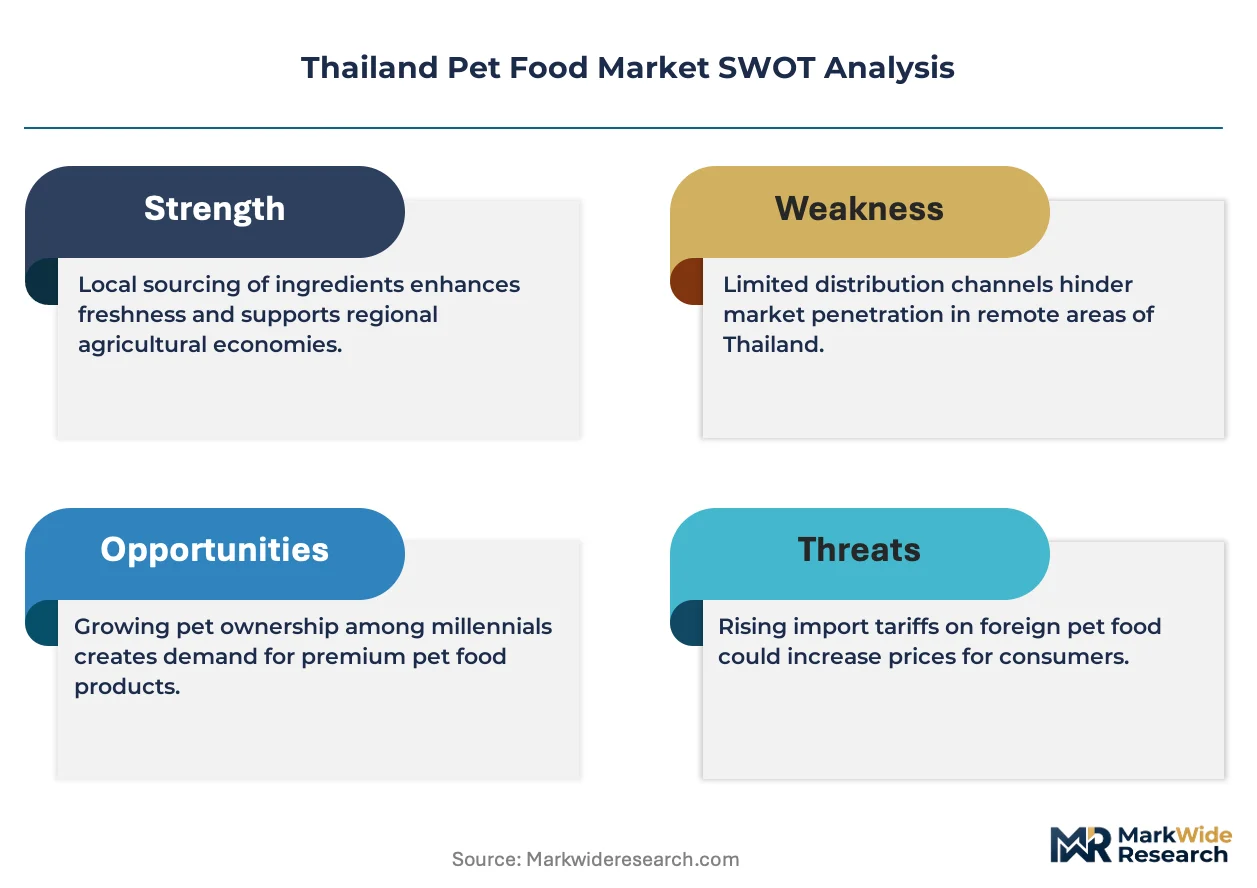
The gap between premium formulations and commodity kibble is shifting from a price divide to a supply-chain separation. Mars Incorporated leverages its global nutrition science infrastructure to sustain brand loyalty among Thai urban consumers. Charoen Pokphand Group anchors its position through captive poultry processing that feeds into economy-tier dry food lines. Thai Union Group PCL competes by extending its seafood processing expertise into high-protein wet food formulations for cats.
Thailand pet food encompasses nutritionally complete and complementary feeds manufactured for domesticated companion animals, typically formulated with protein meals, grains, vitamins, and preservatives to meet species-specific dietary requirements. Dry food dominates volume throughput due to shelf stability and lower logistics costs, while wet food concentrates margin pools through higher per-unit pricing and refrigerated supply chain requirements. Treats and snacks represent the fastest-growing product type as pet humanization trends accelerate spending on reward-based feeding occasions. Online retail channels are gaining structural importance, though veterinary clinics retain premium positioning for prescription and therapeutic diets.
Thailand's Department of Livestock Development enforces feed safety standards under the Animal Epidemic Act, while the Food and Drug Administration monitors imported pet food claims and additive approvals. The Thai Industrial Standards Institute maintains voluntary quality benchmarks that shape exporter eligibility for European and Japanese destinations. Stakeholders must monitor evolving ASEAN harmonization talks and domestic raw material cost pressures to calibrate portfolio allocation between mass-market and premium tiers.
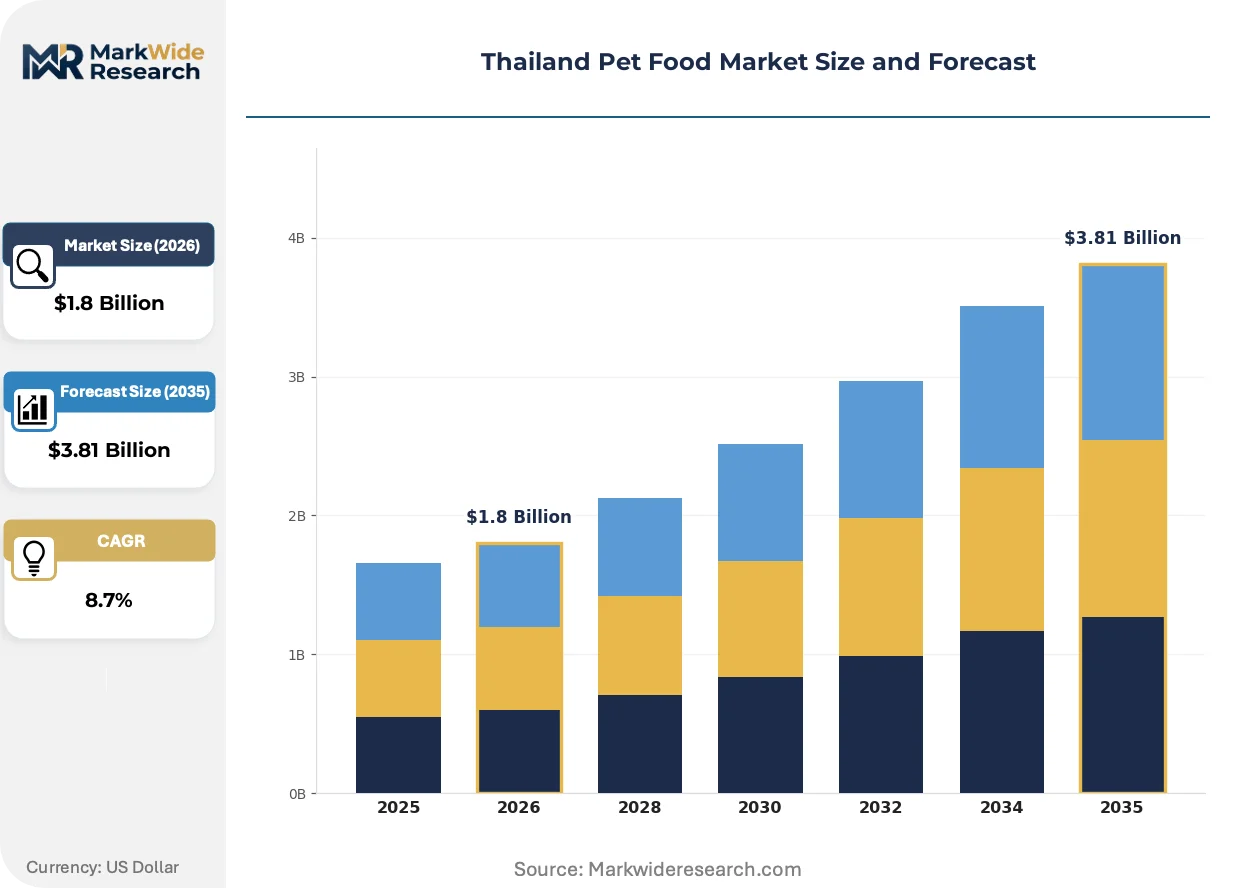
Market Dynamics
Urban condominium living in Bangkok and Chiang Mai is compressing feeding rituals into smaller, more frequent occasions, forcing manufacturers to recalibrate portion formats and shelf-stable packaging around space-constrained storage and single-serve convenience.
Growth Catalysts
- Animal Epidemic Act amendments:Thailand's Department of Livestock Development tightened pet food labeling rules, creating compliance-driven demand for reformulation services and certified packaging substrates among domestic manufacturers.
- Seafood processing residue valorization:Thai Union Group PCL and coastal processors are redirecting tuna and shrimp by-product streams into high-protein wet food inputs, lowering raw material costs for premium formulations.
- Condominium pet humanization:Bangkok's vertical residential density concentrates pet-owning households, amplifying per-capita spending on treats and refrigerated fresh formats through proximity to convenience retail.
Market Restraints
- Maize and soybean meal price volatility:Thailand's dry food sector depends on imported feed grains, exposing margin structures to currency fluctuations and Black Sea supply disruptions.
- Veterinary clinic channel concentration:Prescription diet distribution clusters in Bangkok and Chiang Mai clinic networks, limiting therapeutic brand reach into secondary provinces.
- Refrigerated last-mile gaps:Wet food and fresh format growth confronts cold chain infrastructure deficits in Thailand's northeastern and southern regions.
Strategic Opportunities
- Isaan province underpenetration:Thailand's northeastern region shows rising pet ownership rates with limited premium brand presence, creating first-mover potential for regional distribution partnerships.
- Thai Industrial Standards Institute certification:Voluntary TISI benchmarks unlock Japanese and European export eligibility, enabling margin expansion through cross-border premium positioning.
- Veterinary telehealth integration:Remote consultation platforms are converging with subscription pet food delivery, opening direct-to-consumer channels for therapeutic diet brands.
Industry Challenges
- Veterinary nutritionist talent scarcity:Thailand's universities produce insufficient companion animal nutrition specialists, constraining R&D pipeline velocity for prescription formulations.
- ASEAN harmonization timeline uncertainty:Divergent feed safety standards across member states complicate multi-country labeling and ingredient approval strategies for Thai exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Pet Food Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Animal Type: Dog, Cat, Fish, Bird Distribution Channel: Supermarkets, Pet Stores, Online Retail, Veterinary Clinics Price Tier: Premium, Mid-range, Economy, Discount |
| Companies Covered | Colgate-Palmolive Company, Thai Union Group PCL, Mars Incorporated, Inaba Pet Food Co Ltd, Betagro Agro Group PCL, Charoen Pokphand Group, Hunter Group Ltd, i-Tail Corporation, Nestlé, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Pet Food Market Strategic Shifts
Reformulation priorities are pivoting from shelf-life extension toward clean-label transparency and protein-source diversification, driven by Bangkok consumer scrutiny of ingredient provenance and processing methods.
High-pressure processing technology is expanding into premium wet food manufacturing, enabling pathogen reduction without thermal degradation of amino acid profiles. Chiang Mai and Bangkok contract manufacturers are adopting HPP lines to serve private-label brands demanding refrigerated fresh positioning. This technology is expanding into mid-tier price bands as equipment leasing models reduce capital barriers.
Thailand's Department of Livestock Development is enforcing stricter mycotoxin thresholds under the Animal Epidemic Act, compelling dry food producers to upgrade testing protocols and supplier qualification systems. Domestic mills are absorbing higher analytical costs or consolidating procurement around certified grain elevators. Economy-tier manufacturers face disproportionate compliance burden relative to their margin structures.
Subscription replenishment models are displacing traditional retail stocking cycles among Bangkok's time-constrained professionals, with auto-ship platforms capturing recurring revenue through portion-calibrated delivery frequencies. Veterinary clinics are responding with their own membership programs bundding preventive care with therapeutic diet supply. Channel conflict between digital natives and established clinic networks intensifies in metropolitan Thailand.
Thailand Pet Food Market Segmentation
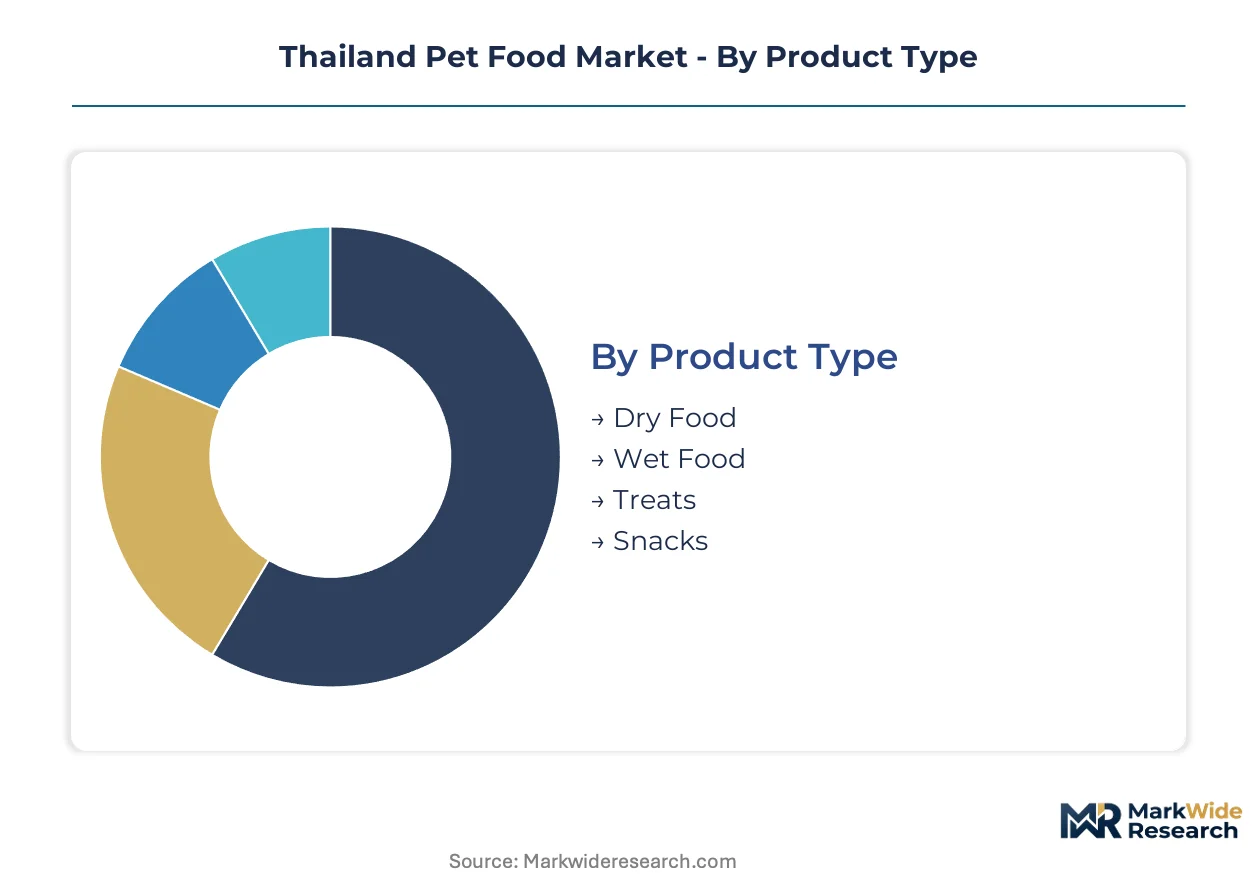
Thailand's pet food segmentation reflects divergent supply chain economics and urban consumption patterns. Manufacturers must align formulation, packaging, and channel strategy to the distinct margin structures and regulatory exposures of each category.
Product Type:
Pet owners in Bangkok and Chiang Mai select formats based on storage constraints, feeding frequency, and humanization intensity.
- Dry Food:Extruded kibble formulations with moisture content below 10 percent dominate household penetration due to ambient storage compatibility and lower per-kilogram logistics costs. Thai mills source imported maize and soybean meal through Bangkok port elevators, exposing margin structures to currency fluctuation against the baht.
- Wet Food:Canned or pouch formats with 75-85 percent moisture content command higher per-unit pricing through refrigerated positioning and premium protein sourcing. Thai Union Group PCL leverages coastal tuna and shrimp processing residues to lower input costs for cat-focused formulations targeting condominium dwellers.
- Treats:Functional and reward-based formulations with specialized textures drive Bangkok impulse purchases through convenience retail proximity.
- Snacks:Air-dried or baked supplementary feeds occupy shelf-stable positioning between meals, gaining traction among time-constrained professionals seeking portion-controlled indulgence.
Dry food leads on scale; treats lead on momentum.
Animal Type:
Species-specific nutritional requirements shape formulation complexity and veterinary channel dependence.
- Dog:Omnivorous formulations span economy dry kibble to grain-free premium lines, with large-breed and senior variants driving veterinary clinic prescription volume in Bangkok.
- Cat:Obligate carnivore requirements concentrate demand for high-protein wet formats, with Thai seafood processors supplying taurine-rich inputs for urban indoor-cat segments.
- Fish:Ornamental and pond fish feeds represent a specialized tier with distinct distribution through aquarium retailers and garden centers.
- Bird:Seed and pellet formulations for companion parrots and songbirds occupy niche positioning with concentrated demand in Bangkok and Chiang Mai hobbyist communities.
Dogs dominate volume throughput; cats dominate margin expansion.
Distribution Channel:
Channel selection determines brand positioning, pricing authority, and consumer data access.
- Supermarkets:Mass-market dry food and mid-range wet formats occupy dedicated aisle space, with Bangkok hypermarkets driving promotional intensity and private-label penetration.
- Pet Stores:Specialized retailers in Bangkok and Chiang Mai concentrate premium assortment, staff expertise, and loyalty program deployment for treat and accessory bundling.
- Online Retail:Subscription auto-ship platforms capture recurring revenue from Bangkok professionals, with cold-chain last-mile partnerships enabling wet food expansion beyond metropolitan cores.
- Veterinary Clinics:Therapeutic and prescription diet distribution clusters in Bangkok and Chiang Mai networks, limiting brand reach into secondary provinces due to nutritionist talent scarcity.
Supermarkets anchor volume; online retail climbs the fastest.
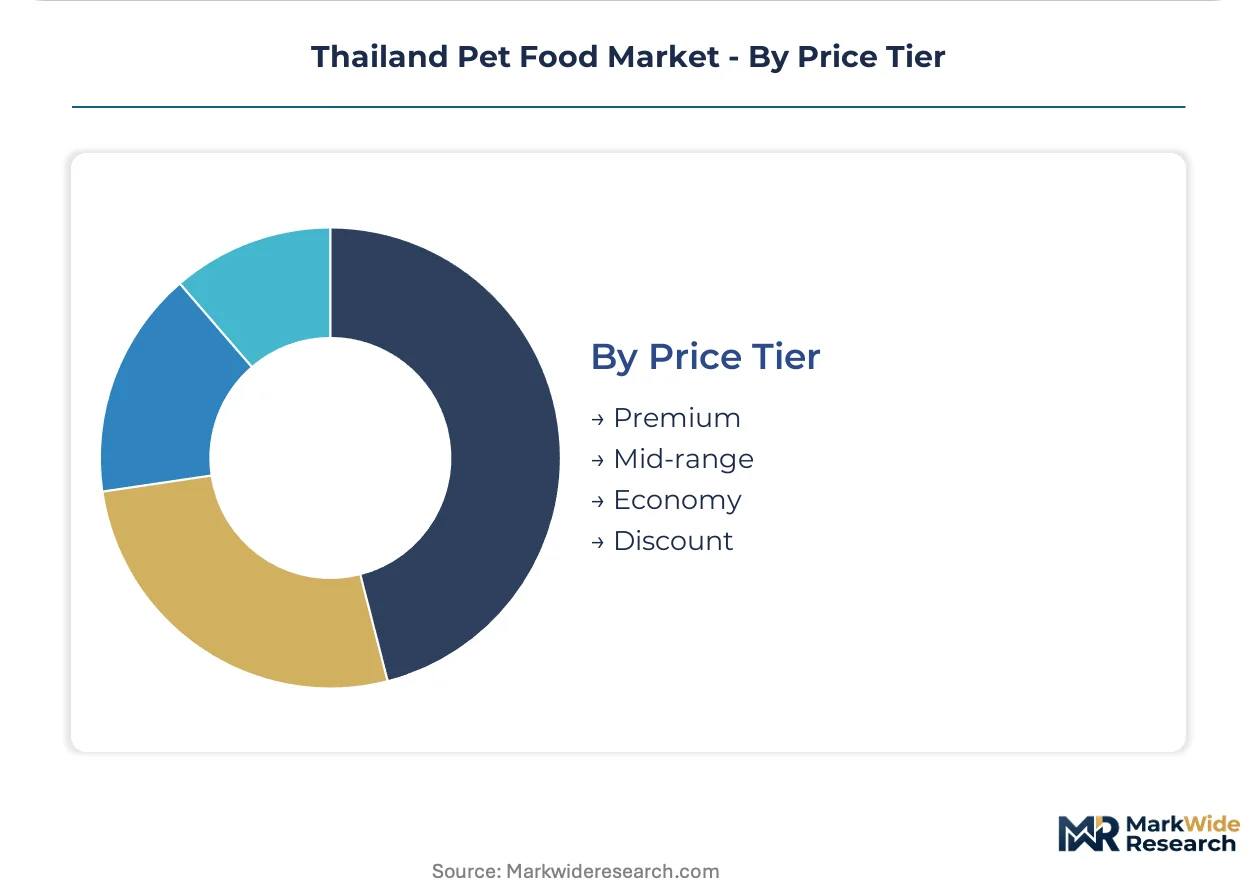
Price Tier:
Purchasing decisions stratify across income distribution, pet humanization intensity, and export eligibility requirements.
- Premium:Formulations with named protein sources, grain-free positioning, and Thai Industrial Standards Institute certification target Japanese and European export eligibility alongside Bangkok high-income households.
- Mid-range:Balanced nutrition positioning with selective premium features occupies the contested center, with Charoen Pokphand Group leveraging captive poultry supply for cost-competitive dry lines.
- Economy:Price-sensitive formulations face disproportionate compliance burden from Department of Livestock Development mycotoxin thresholds, forcing consolidation around certified grain elevators.
- Discount:Unbranded or regional-label products serve rural and price-elastic segments with minimal marketing investment and basic nutritional adequacy claims.
Economy tier leads on household penetration; premium tier leads on margin and export expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's concentration of companion animal nutrition specialists anchors Thailand's formulation R&D, while provincial veterinary networks in secondary cities struggle to match metropolitan expertise density.
Greater Bangkok Metropolitan Region
Vertical condominium living compresses feeding rituals into space-constrained formats, driving demand for single-serve pouches and refrigerated fresh positioning. The Department of Livestock Development enforces Animal Epidemic Act labeling compliance through Bangkok-based certification laboratories. Mars Incorporated and Thai Union Group PCL concentrate premium wet food manufacturing in Samut Prakan and Pathum Thani industrial zones to access refrigerated port logistics.
Chiang Mai-Lamphun Corridor
Affluent retiree and digital nomad communities sustain above-average spending on grain-free and functional treat categories. Provincial livestock officers apply mycotoxin testing protocols under central DLD directives, though analytical capacity lags Bangkok. Chiang Mai's Nimmanhaemin district hosts boutique pet retail clusters that import Japanese and Korean premium brands through informal cross-border channels.
Isaan Region
Rising dog ownership rates among lower-middle-income households create volume opportunity for economy-tier dry kibble, though cold-chain gaps block wet food penetration. Provincial feed safety enforcement relies on Bangkok-dispatched inspection teams with irregular coverage cycles. Khon Kaen and Udon Thani retail cooperatives serve as distribution gatekeepers for Charoen Pokphand Group's poultry-integrated economy lines.
Southern Coastal Provinces
Seafood processing residue streams from Songkhla and Surat Thani tuna canneries supply taurine-rich inputs for cat food formulations. Coastal humidity challenges dry food shelf stability, favoring laminated packaging investments. Thai Union Group PCL leverages its Samut Sakhon headquarters coordination to aggregate southern by-product flows into wet food supply chains.
Eastern Economic Corridor
Rayong and Chonburi industrial estates attract contract manufacturing investment targeting Japanese export eligibility through Thai Industrial Standards Institute certification. The corridor's refrigerated logistics infrastructure outperforms national averages, enabling fresh format trials. Japanese trading houses coordinate ingredient sourcing through Eastern Seaboard bonded warehouses.
Thailand Pet Food Market Competitive Environment
Capital-heavy processors compete with brand-marketing specialists for margin capture, creating a bifurcated structure where captive supply chains face agile importers. Thailand's pet food sector concentrates around three archetypes: diversified agro-conglomerates with backward-integrated protein supply, seafood processors valorizing by-product streams, and multinational nutrition science platforms importing global formulations. Competitive intensity manifests through M&A consolidation of coastal cannery assets and strategic partnerships between Bangkok distributors and Japanese ingredient suppliers.
Within the agro-industrial tier, Charoen Pokphand Group exemplifies captive poultry integration into economy dry food lines, while Thai Union Group PCL occupies seafood-processor positioning. Mars Incorporated anchors the multinational nutrition science archetype. These three represent distinct supply-chain logics rather than direct product rivalry, with each optimizing around different input cost structures and channel access points.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Thai Union Group PCL |
| Mars Incorporated |
| Inaba Pet Food Co Ltd |
| Betagro Agro Group PCL |
| Charoen Pokphand Group |
| Hunter Group Ltd |
| i-Tail Corporation |
| Nestlé |
| Others |
Value Chain & Pricing Dynamics
Companion animal nutritionist concentration in Greater Bangkok widens labor-cost differentials between metropolitan and provincial manufacturing, compressing margin spreads at the economy tier while premium formulations absorb specialist premiums through export pricing power.
Pricing Analysis
Bundled veterinary-channel service splits from unbundled retail transactions define Thailand's pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates TISI-certified export-grade formulations from domestic mid-range lines and price-sensitive commodity kibble. Price differentiation rests on certification tier and cold-chain delivery cost, with refrigerated wet formats commanding substantial premiums over ambient dry alternatives. Pricing pressure stems from imported maize and soybean meal currency exposure, forcing economy-tier producers into procurement consolidation around certified grain elevators. Bangkok condominium households show lowest price sensitivity for subscription fresh formats, while Isaan province buyers prioritize per-kilogram economy.
Supply Chain Analysis
Single-source vulnerability sits with Black Sea grain corridors feeding Bangkok port elevators, exposing dry food margins to geopolitical disruption. Thailand's pet food sector draws raw material inputs from Argentina and Ukraine for feed grains, China for packaging substrates, and domestic coastal zones for tuna and shrimp processing residues. Supply chain risk centers on refrigerated last-mile gaps in northeastern and southern provinces, constraining wet food penetration beyond metropolitan cores. Distribution runs through Bangkok hypermarkets and veterinary clinic networks for premium therapeutic diets, with subscription platforms capturing recurring revenue from time-constrained professionals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's pet food sector offers margin-expansion pathways through seafood processing residue valorization, lowering input costs for premium wet formulations while Bangkok's subscription economy locks in recurring revenue premiums.
For Market Incumbents: Acquire coastal cannery assets to secure taurine-rich by-product streams for cat food formulations. Consolidate procurement around Thai Industrial Standards Institute-certified grain elevators to deflect Department of Livestock Development mycotoxin compliance burdens. Channel control through veterinary clinic network partnerships protects therapeutic diet pricing power against digital-native subscription entrants. For New Entrants and Emerging Players: Subscription auto-ship platforms offer the lowest customer-acquisition-cost entry path for refrigerated fresh formats targeting Bangkok professionals. White-space concentration in Isaan province retail cooperatives enables economy-tier volume capture through Charoen Pokphand Group-style poultry integration partnerships. Veterinary telehealth bundling with prescription diet delivery creates direct-to-consumer bypass of established clinic networks. For Investors and Strategic Acquirers: Agro-industrial conglomerates with captive protein supply are the most active acquirer in this space, seeking nutrition science capabilities to bridge commodity processing into premium positioning. Long-term viability hinges on cross-border export eligibility through Japanese and European certification alignment. Acquisition target archetype: mid-tier wet food specialists with Thai Union Group-style seafood processing integration. Signal to watch: ASEAN harmonization timeline clarity on feed safety standard convergence.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Technology Adoption | Enables pathogen reduction without thermal degradation, supporting refrigerated fresh positioning in Bangkok. |
| Thai Industrial Standards Institute Certification Investment | Unlocks Japanese and European export eligibility for premium tier margin expansion. |
| Coastal Cannery Asset Acquisition | Secures tuna and shrimp processing residue streams for taurine-rich cat food formulations. |
| Veterinary Telehealth Platform Integration | Converges remote consultation with subscription diet delivery, opening direct-to-consumer therapeutic channels. |
| Isaan Province Distribution Partnership | Captures rising pet ownership in underpenetrated northeastern retail cooperative networks. |
Study Parameters
Coverage spans Greater Bangkok, Chiang Mai-Lamphun, Isaan region, southern coastal provinces, and Eastern Economic Corridor, with primary inputs from each. The approach combines structured interviews with companion animal nutrition specialists, Department of Livestock Development compliance officers, veterinary clinic procurement managers, and Bangkok retail category buyers with secondary validation through Thai Industrial Standards Institute certification databases, Animal Epidemic Act regulatory filings, and customs trade records. Bottom-up volume modeling and top-down value triangulation cross-validate segment outputs.
Granularity-level modeling operates at product type, animal species, distribution channel, price tier, and regional cluster dimensions across the projection horizon. CAGRs derive from segment-specific growth rate blending informed by urban pet ownership trajectory, condominium dwelling density, and cold-chain infrastructure buildout pace. Forecast inputs incorporate seafood processing residue availability curves and feed grain import dependency ratios.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing equipment leasing models would alter the outlook. Forecasts reflect assumptions around ASEAN harmonization progress, Department of Livestock Development enforcement intensity, and baht currency stability against grain-import exposures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Shampoo Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Dog Float Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Toy Dog Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Dog Pen Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Pet Toys Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Cat Collar Market
Pet Care Products
Europe Organic Pet Food for Cats and Dogs Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Dog Nail Clippers Market