
 Weight Management Dog Food Market | 2026-2036
Weight Management Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Management Dog Food Market Analytics
Premium therapeutic-grade formulations is bifurcating the competitive landscape between mass-market labels and clinically validated nutrition. Mars Petcare leverages its veterinary hospital network to channel prescription weight diets directly through licensed practitioners. Hill's Pet Nutrition sustains dominance in clinical settings through its Prescription Diet Metabolic line, which anchors practitioner trust. Royal Canin differentiates via breed-specific weight management matrices that occupy premium shelf space in European and North American pet specialty stores.
Weight management dog food denotes nutritionally engineered canine diets formulated with controlled caloric density, elevated fiber content, and optimized protein-to-fat ratios to induce or maintain healthy body condition. Manufacturers employ extrusion cooking with precise thermal profiling to preserve heat-labile micronutrients while achieving target kibble expansion indices for satiety signaling. Dry food commands the largest volume position due to cost efficiency and storage convenience, though wet food captures disproportionate margin pools among aging and dentally compromised dogs. Veterinary-recommended positioning attracts the highest per-unit pricing, while e-commerce channels represent the fastest-growing distribution vector as subscription models lock in recurring revenue.
The FDA's Center for Veterinary Medicine oversees feed safety and label claims, while AAFCO model guidelines define nutrient profiles for canine weight maintenance and reduction. State-level feed control officials enforce sampling and testing protocols that shape regional market access for imported formulations. Stakeholders must monitor evolving veterinary telehealth regulations, as remote prescription authority directly influences channel economics and customer acquisition costs in this category.
Market Dynamics
Veterinary prescription authority is restructuring channel economics as telehealth regulations expand remote diagnosis capabilities, diverting volume from traditional retail toward clinically supervised feeding programs.
Growth Catalysts
- AAFCO Nutrient Profiles:The Association of American Feed Control Officials tightened substantiation requirements for weight management claims, compelling manufacturers to invest in clinical validation that builds practitioner trust and commands premium positioning.
- Pet Obesity Epidemic:Rising canine obesity rates are driving insured veterinary visits where therapeutic weight formulas carry higher reimbursement rates than over-the-counter alternatives.
- Extrusion Thermal Profiling:Precision cooking technology preserves heat-labile micronutrients while achieving target kibble expansion indices that signal satiety, improving compliance in controlled-feeding protocols.
Market Restraints
- Input Cost Volatility:Specialized protein sources and novel fiber substrates face price instability as human food and pet food sectors compete for limited functional ingredient supplies.
- Veterinary Channel Concentration:Prescription diet authorization depends on licensed practitioner networks concentrated in urban veterinary hospitals, creating geographic access gaps in rural markets.
- Substitution Threat:Fresh-cooked pet food delivery services and homemade diet formulations guided by veterinary nutritionists capture affluent owners seeking perceived natural alternatives to extruded kibble.
Strategic Opportunities
- Subscription E-Commerce:Direct-to-consumer platforms with automated replenishment algorithms capture recurring revenue while bypassing retail margin compression and building proprietary customer data assets.
- Breed-Specific Matrices:Genetic diversity in canine metabolism creates white space for formulations calibrated to breed-specific energy requirements and satiety responses.
- US State Feed Control Harmonization:Interstate alignment of sampling and testing protocols reduces compliance fragmentation, lowering market access barriers for regional manufacturers seeking multi-state distribution.
Industry Challenges
- Veterinary Nutritionist Scarcity:Formulation science expertise resides in a limited pool of board-certified specialists, constraining R&D throughput and extending product development timelines.
- Legacy System Integration:Established manufacturers face technical debt reconciling decades-old enterprise resource planning systems with modern e-commerce fulfillment and customer analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Management Dog Food Market |
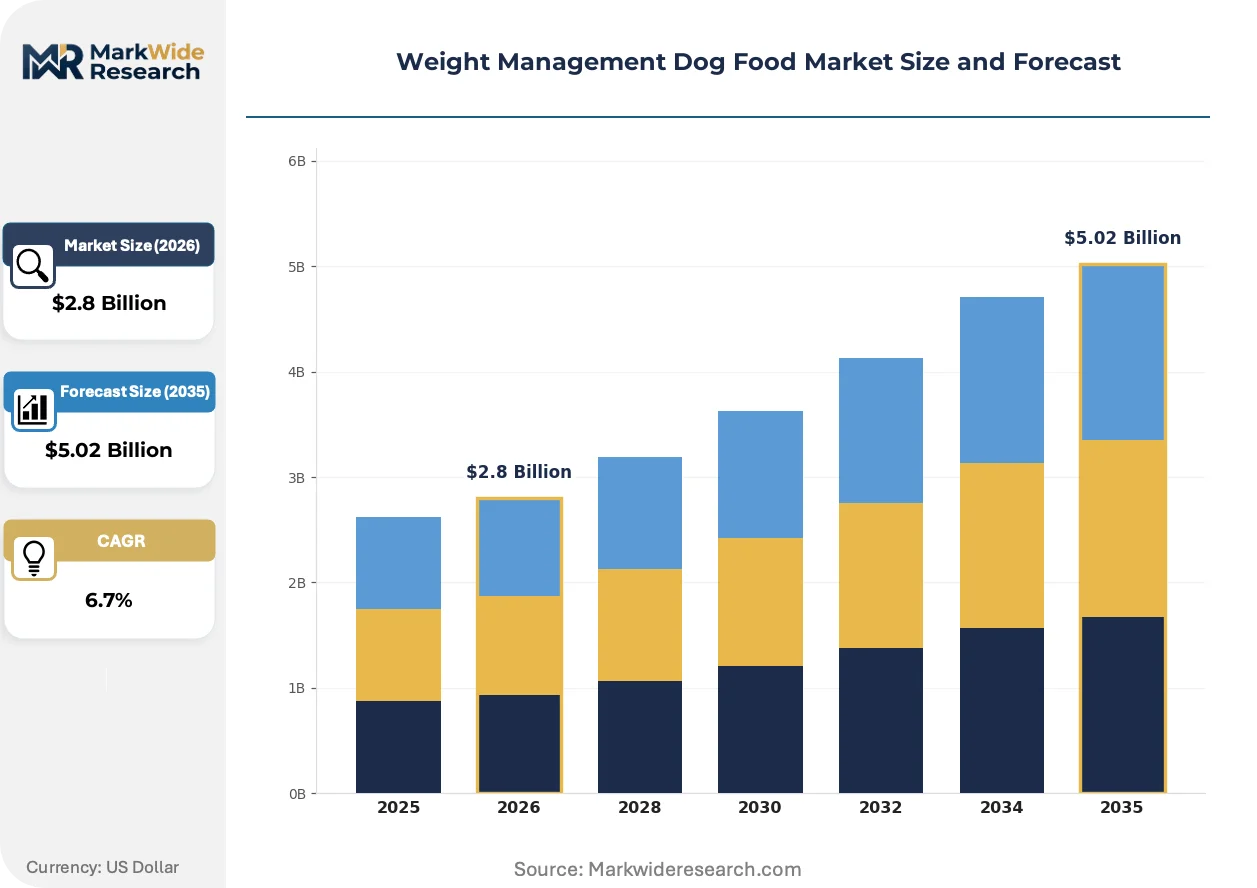
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Type: Grain-Free, High-Protein, Low-Fat, Functional Ingredients Brand Positioning: Premium, Economical, Veterinary-Recommended, Organic Distribution Channel: Pet Specialty Stores, Supermarkets, E-Commerce, Veterinary Clinics |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Royal Canin, Blue Buffalo, Pedigree, Iams, Virbac, FARMINA PET FOODS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Management Dog Food Market Evolving Landscape
Digital health integration and precision nutrition science are converging to transform how weight management protocols are prescribed, monitored, and adjusted throughout a dog's lifecycle.
Near-infrared spectroscopy is displacing traditional proximate analysis for real-time macronutrient verification during production. Mid-tier manufacturers are adopting inline sensors to reduce laboratory testing bottlenecks and batch-to-batch variability. This quality assurance automation is displacing manual sampling protocols that previously delayed release decisions by 48-72 hours.
The FDA Center for Veterinary Medicine's expanded enforcement of structure-function claim substantiation is forcing reformulation of marketing language across the therapeutic segment. Manufacturers must now generate clinical data supporting satiety and metabolic claims previously asserted through ingredient lists alone. Small and mid-size brands lacking veterinary hospital research partnerships face the steepest compliance cost escalation.
Subscription-based replenishment models are capturing owner relationships previously held by brick-and-mortar specialty retailers. Automated portion-dispensing hardware bundled with recurring food shipments locks in lifetime value through data-driven feeding recommendations. This channel shift concentrates most visibly among millennial pet owners in metropolitan US markets where veterinary telehealth adoption rates exceed national averages.
Weight Management Dog Food Market Segmentation
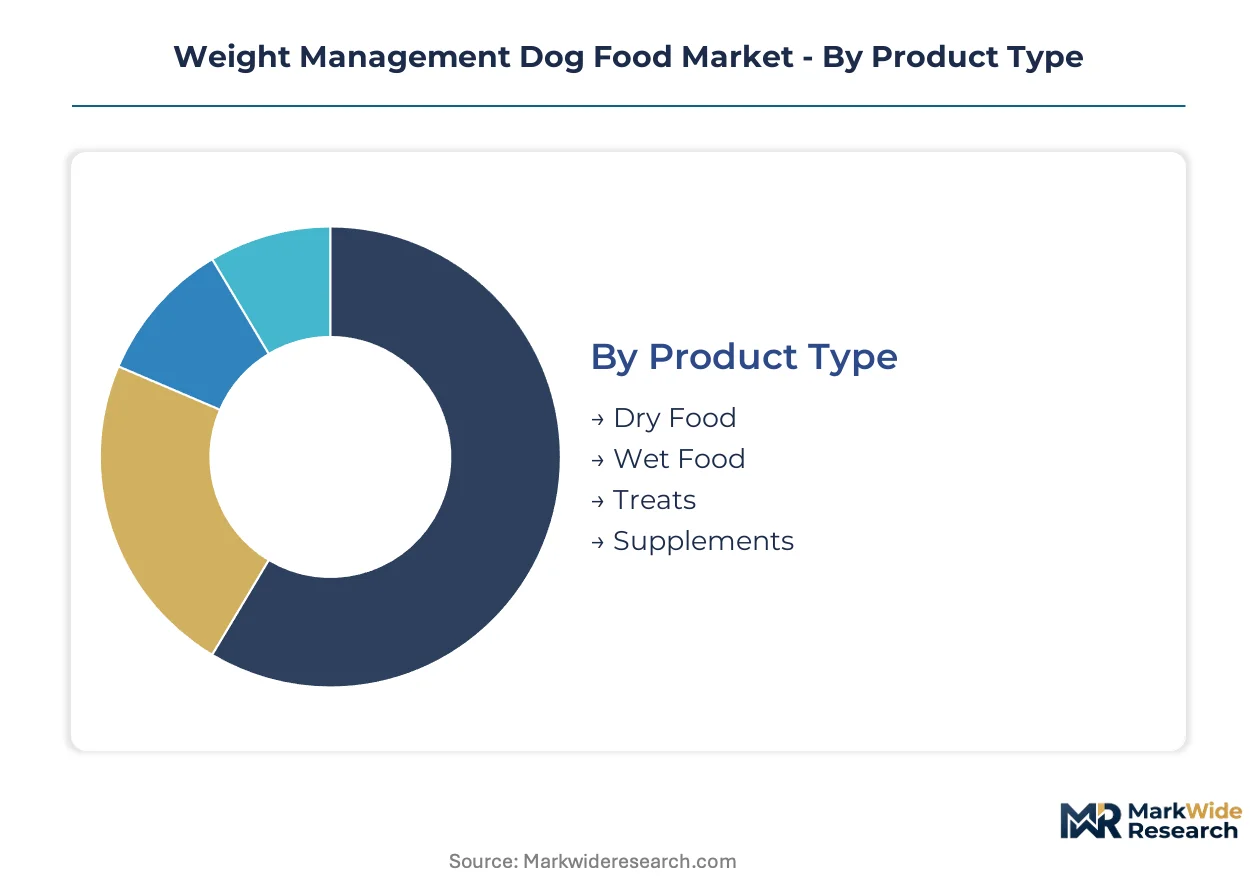
Segmentation in weight management dog food reveals how formulation science, channel access, and owner purchasing power intersect to determine commercial outcomes. Manufacturers must align product architecture with specific feeding protocols while navigating divergent regulatory requirements across prescription and retail channels.
Product Type:
Substitution pressure from fresh-cooked delivery services hits extruded formats hardest, while therapeutic positioning insulates prescription-grade segments from homemade diet encroachment.
- Dry Food:Extruded kibble with controlled expansion indices delivers cost-efficient caloric dilution and dental abrasion benefits. Demand concentrates in multi-dog households and insured veterinary weight programs where portion-controlled feeding protocols require measurable consistency.
- Wet Food:Retort-sterilized formulations achieve higher moisture content for satiety amplification and palatability in aging or dentally compromised dogs. Premium positioning in European and North American urban markets captures owners seeking hydration-integrated weight protocols for senior canines.
- Treats:Low-calorie training rewards with novel protein sources occupy impulse purchase occasions in pet specialty retail.
- Supplements:Fiber concentrates and metabolic support additives target owner-driven augmentation of base diets.
Dry food anchors the volume base while wet food gains share at the steepest rate.
Ingredient Type:
Cost tier stratification separates commodity grain-inclusive formulations from premium functional ingredient matrices that command veterinary endorsement.
- Grain-Free:Legume and tuber carbohydrate substitutes address owner perceptions of food sensitivity while maintaining glycemic control. Concentrated demand in US coastal metropolitan markets where pet humanization trends elevate clean-label preferences over traditional corn and wheat formulations.
- High-Protein:Elevated lean meat inclusion preserves muscle mass during caloric restriction phases of weight loss protocols. Veterinary-recommended positioning in clinical settings where AAFCO substantiation requirements favor amino acid-optimized matrices over carbohydrate-dense alternatives.
- Low-Fat:Restricted lipid content targets pancreatitis-prone breeds and post-surgical recovery feeding.
- Functional Ingredients:Prebiotic fibers, L-carnitine, and novel satiety peptides differentiate premium tiers through metabolic claim substantiation.
High-protein formulations dominate prescription channels while functional ingredients climb fastest in direct-to-consumer subscription platforms.
Brand Positioning:
Customer type divergence separates price-sensitive mass-market purchasers from clinically motivated owners seeking therapeutic validation.
- Premium:Super-premium positioning leverages human-grade ingredient sourcing and transparent supply chain narratives. Metropolitan US and Western European markets where household pet spending correlates with dual-income professional demographics.
- Veterinary-Recommended:Prescription authorization requirements create channel capture through licensed practitioner networks. Insured veterinary visits in the United States where therapeutic diets carry higher reimbursement rates and compliance monitoring.
- Economical:Private-label and mass-market brands compete on shelf price in supermarket and big-box retail.
- Organic:USDA Organic and equivalent certifications target sustainability-motivated owners in premium pet specialty.
Veterinary-recommended positioning commands the highest per-unit economics while premium tiers expand most quickly in e-commerce.
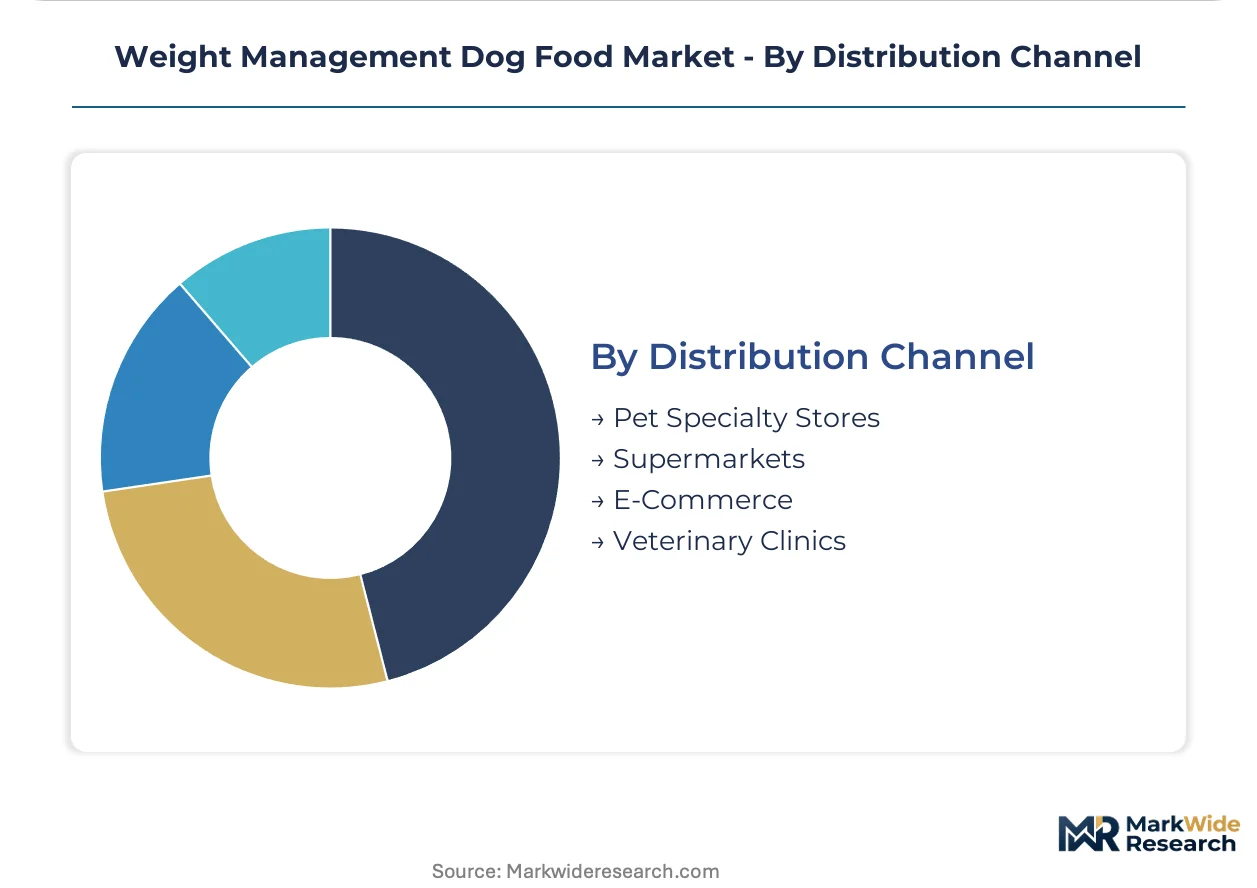
Distribution Channel:
Supply concentration in urban veterinary hospitals creates geographic access gaps that e-commerce platforms exploit through telehealth-integrated prescription fulfillment.
- E-Commerce:Direct-to-consumer platforms with automated replenishment algorithms capture recurring revenue and proprietary feeding data. Subscription models in US metropolitan markets where millennial pet owner penetration and veterinary telehealth adoption exceed national benchmarks.
- Veterinary Clinics:Prescription diet authorization through licensed practitioners anchors therapeutic segment integrity and compliance monitoring. Urban hospital networks where board-certified veterinary nutritionist consultation drives protocol adherence.
- Pet Specialty Stores:Curated assortment and staff expertise support premium positioning and breed-specific matrix selection.
- Supermarkets:Mass-market accessibility captures price-sensitive volume in routine replenishment occasions.
Veterinary clinics anchor therapeutic volume while e-commerce gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in Western Europe and North America supply premium therapeutic formulations to veterinary networks across Asia-Pacific and Latin America, while import-dependent markets in Southeast Asia source cost-optimized private-label products from Chinese extrusion facilities.
United States
Insured veterinary visits and pet humanization trends concentrate demand in coastal metropolitan corridors. The FDA Center for Veterinary Medicine enforces structure-function claim substantiation that elevates compliance costs for imported formulations. Mars Petcare operates prescription diet channels through its veterinary hospital network in California and Texas.
Germany
Specialty pet retailers in Berlin and Munich drive premium functional ingredient adoption among discerning owners. EFSA guidelines on novel food ingredients shape approval pathways for satiety peptides and metabolic enhancers. Baden-Württemberg hosts precision extrusion equipment manufacturers supplying thermal profiling systems to regional producers.
Japan
Aging canine demographics in Tokyo and Osaka elevate wet food demand for dentally compromised pets. METI standards on pet food manufacturing hygiene enforce batch-level traceability that favors domestic producers over imports. Aichi Prefecture concentrates mid-tier manufacturers serving the veterinary clinic channel.
United Kingdom
Veterinary telehealth adoption in London and Southeast England accelerates prescription diet fulfillment through e-commerce platforms. FSA labeling requirements on caloric density claims compel reformulation of mass-market lines. Manchester hosts subscription logistics providers bundling automated feeders with recurring shipments.
Australia
High livestock protein availability in New South Wales and Victoria supports local manufacturing of high-protein weight management lines. TGA veterinary medicine regulations overlap with state feed control protocols, creating dual compliance frameworks. Sydney anchors import distribution for European premium brands seeking Asia-Pacific beachheads.
Weight Management Dog Food Market Competitive Landscape
Concentration sits with diversified consumer goods conglomerates that leverage veterinary channel integration and retail scale to defend position. The market structure tiers between prescription-authorized therapeutic players, premium specialty marketers, and private-label mass-market suppliers. Strategic archetypes include clinically validated formulators, breed-specific matrix specialists, and direct-to-consumer subscription platforms. Dominant competitive moves encompass veterinary hospital network acquisitions and extrusion technology licensing partnerships.
Within the diversified conglomerate tier, Mars Petcare and Nestlé Purina PetCare represent scale-driven archetypes with cross-channel presence spanning prescription and retail segments. Hill's Pet Nutrition occupies a position exemplifying clinical validation authority through practitioner-endorsed therapeutic lines. Royal Canin anchors the specialization vector with breed-calibrated formulation matrices. These three entities collectively illustrate how veterinary trust, manufacturing precision, and distribution breadth determine competitive viability in therapeutic nutrition.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Royal Canin |
| Blue Buffalo |
| Pedigree |
| Iams |
| Virbac |
| FARMINA PET FOODS |
| Others |
Value Network & Pricing Analysis
Legume and tuber carbohydrate substitutes displacing traditional corn and wheat formulations simultaneously relocate sourcing networks toward Canadian prairie provinces and Australian grain belts while compressing margin structures for legacy ingredient suppliers dependent on commodity futures pricing.
Pricing Analysis
Veterinary clinic buyers anchor prescription-tier pricing through insured reimbursement protocols that insulate therapeutic formulations from direct consumer price sensitivity. Three-tier pricing structure across premium, standard, and economy levels stratifies by AAFCO substantiation status and practitioner endorsement depth. Cost compression in mass-market extruded kibble intensifies because fresh-cooked delivery services capture affluent owner switching. Price-sensitive volume concentrates in supermarket private-label segments while least-sensitive purchasers populate veterinary-supervised metabolic programs.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for novel fiber substrates sourced from Southeast Asian processing facilities. Manufacturing gravity centers on the United States, Germany, and China, with specialized thermal profiling equipment concentrated in Baden-Württemberg and Guangdong. Raw material dependencies include novel protein isolates, prebiotic fiber concentrates, and precision micronutrient premixes. Single-source vulnerability sits with board-certified veterinary nutritionist expertise concentrated in North American and Western European academic institutions. Distribution runs through veterinary hospital networks in urban corridors, supplemented by direct-to-consumer subscription fulfillment from regional extrusion facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to insured veterinary visit volumes, which rebound predictably following economic stabilization periods as pet owners restore discretionary spending on preventive clinical services.
For Market Incumbents: Secure practitioner network exclusivity through embedded nutritionist consultation services that deepen switching costs for competing therapeutic lines. Fortify backward integration into novel protein cultivation to offset input cost volatility from human food sector competition. The substitution threat from fresh-cooked delivery services demands rapid deployment of automated portion-dispensing hardware bundled with subscription replenishment.
For New Entrants and Emerging Players: AAFCO fast-track substantiation for weight management claims opens channel access through telehealth-integrated veterinary platforms lacking legacy hospital affiliations. Target rural and exurban geographies underserved by board-certified nutritionist concentration in metropolitan hospital networks. White space exists in breed-specific metabolic matrices for working and sporting dog segments overlooked by mass-market therapeutic lines. Go-to-market execution should prioritize direct-to-consumer subscription models with algorithmic replenishment to capture lifetime value before retail incumbents adapt.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers possessing thermal profiling equipment and extrusion capacity but lacking veterinary hospital channel relationships, as these assets command scarcity premiums in consolidation scenarios. Long-term viability hinges on telehealth regulatory harmonization expanding remote prescription authority across state jurisdictions. The inflection signal to monitor is state feed control alignment on sampling protocols, which would suddenly de-risk multi-state distribution for regional players.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Hospital Network Acquisition | Practitioner channel control locks in prescription volume and compliance monitoring data. |
| Extrusion Technology Licensing Partnership | Precision thermal profiling capabilities transfer manufacturing quality advantages to regional partners. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms capture recurring revenue and proprietary feeding behavior data. |
| Breed-Specific Matrix Development | Genetic calibration differentiates premium positioning in pet specialty retail channels. |
| Novel Protein Backward Integration | Captive supply of insect or cultivated protein isolates insulates against human food sector competition. |
Research Methodology
The analysis maps therapeutic prescription, premium specialty, and mass-market private-label segments, each validated through formulation scientists, veterinary nutritionists, procurement managers at pet specialty retailers, and channel distribution directors. Primary interviews with board-certified veterinary nutritionists, extrusion equipment manufacturers, and state feed control officials combined with secondary validation from FDA Center for Veterinary Medicine enforcement actions, AAFCO model guideline revisions, and customs trade data on novel ingredient imports. Bottom-up volume modeling and top-down value reconciliation triangulate segment outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. The analytical framework modeled product type, ingredient composition, brand positioning tier, and distribution channel segmentation dimensions. CAGRs were derived from fitted growth curves applied to veterinary visit volume elasticity, insured penetration rates, and e-commerce subscription adoption patterns. Forecast inputs incorporated telehealth regulatory expansion scenarios and state feed control harmonization timelines.
Decision-makers should treat outputs as directional under assumptions of steady insured veterinary visit growth and stable AAFCO substantiation requirements; material deviation in either would warrant model refresh. Specific risk factors include abrupt telehealth prescription authority restrictions, novel ingredient supply disruptions, and fresh-cooked delivery service margin compression in urban markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Flea, Tick, and Heartworm Products Market
Pet Care Products
Cat Window Perches and Wall Shelves Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Pet Car Seat Protectors Market
Pet Care Products
Pet Odor Absorber Market
Pet Care Products
Pet Treats and Chews Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Cannabidiol CBD Pet Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
South Africa Pet Training Services Market
Pet Care Products
Pet Oral Care Market
Pet Care Products
Raw Meat Pet Food Market