
 Global Kennel Software Market | 2026-2036
Global Kennel Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kennel Software Market Foresight
Cloud distribution channels for kennel management tools is reconfiguring how smaller pet care operators access enterprise-grade functionality without capital expenditure. PetExec Inc. leverages a partner-driven onboarding model that reduces implementation friction for independent boarding facilities. DaySmart Software anchors its position through deep calendar synchronization capabilities that span grooming and daycare workflows. Gingr competes on interface simplicity, targeting facilities with high staff turnover where training overhead determines retention.
Kennel software encompasses specialized operational platforms that coordinate animal intake, habitat assignment, feeding protocols, medication tracking, and owner communication through centralized digital interfaces, typically requiring API connectivity with veterinary record systems and payment processors. Cloud-based deployment leads the market by accessibility, while on-premises installations persist among large-scale breeding operations with stringent data sovereignty requirements. Boarding management applications dominate current revenue, though payment processing solutions are accelerating fastest as integrated financial workflows reduce reconciliation labor for multi-service facilities.
The FDA's veterinary feed directive compliance tracking shapes how U.S. platforms incorporate medication logging, while GDPR mandates in Europe constrain how customer pet data traverses cloud infrastructure across jurisdictions. Australia's TGA sets benchmark standards for clinical integration modules that veterinary clinics demand. Stakeholders must weigh regulatory fragmentation against the cost of region-specific feature development as they evaluate platform architecture decisions.
Market Dynamics
Cloud migration pressure from multi-location pet boarding chains is compressing deployment cycles and forcing vendors to modularize subscription tiers for capital-constrained independents.
Growth Catalysts
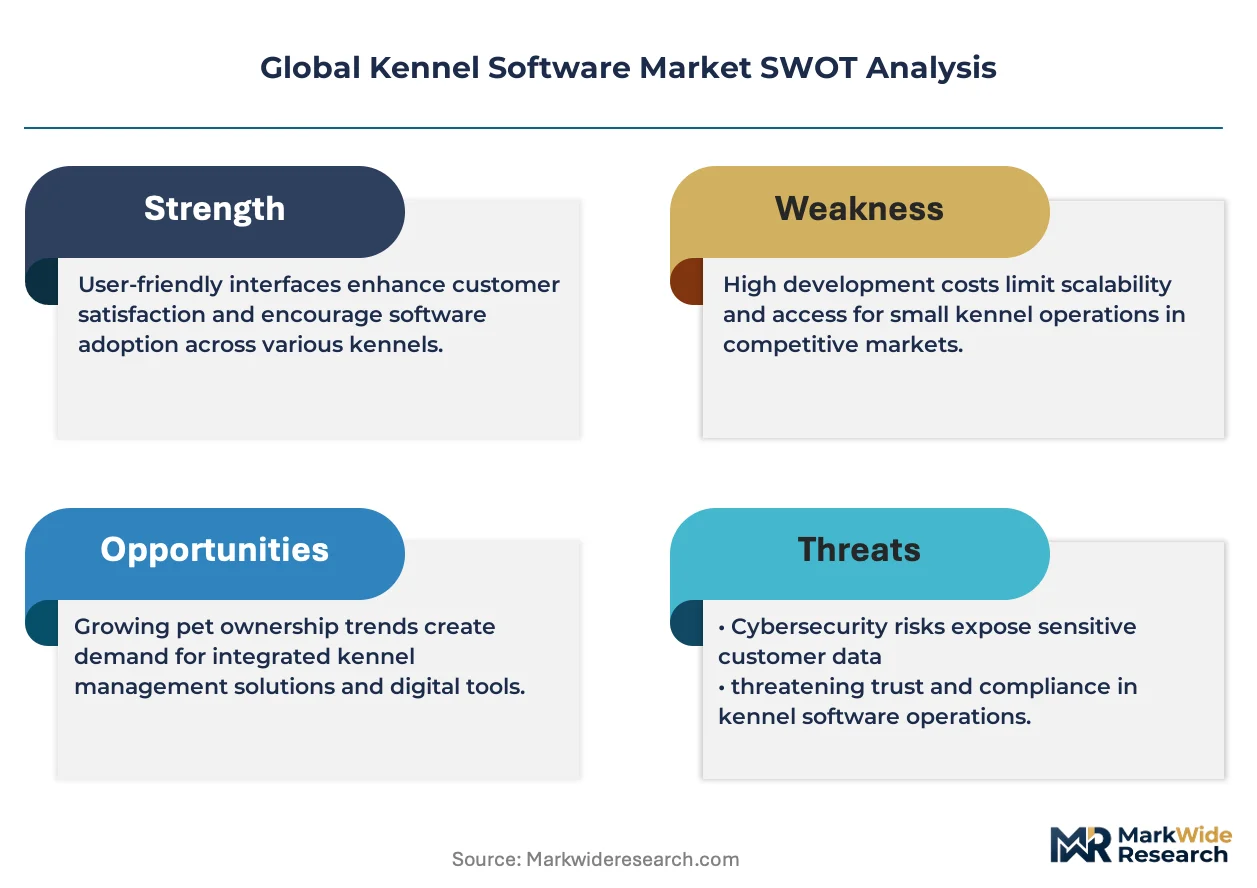
- EU AI Act algorithmic transparency:European facilities now demand explainable automated scheduling, pulling vendors toward auditable machine-learning architectures that command premium pricing.
- Veterinary practice consolidation:Large clinic networks in Australia require TGA-aligned clinical integration, expanding addressable market for platforms with embedded medication logging and pathology connectivity.
- API-first architectures:Open integration standards enable payment processors, telemedicine providers, and IoT habitat sensors to plug into core kennel systems without custom development.
Market Restraints
- Data sovereignty compliance:Breeding operations with genetic record confidentiality obligations in Germany and Switzerland resist cloud migration, capping SaaS penetration in high-value segments.
- Fragmented payment infrastructure:Regional processor dominance in Brazil, India, and Southeast Asia forces vendors to maintain multiple gateway integrations, elevating engineering overhead.
- Veterinary feed directive complexity:FDA logging requirements for medicated feeds create compliance layers that smaller platforms lack resources to implement, consolidating share among scaled vendors.
Strategic Opportunities
- Underpenetrated Japanese market:METI digitalization incentives for small businesses coincide with rising pet humanization, creating first-mover advantage for localized cloud offerings.
- Wearable telemetry convergence:Collar-mounted activity monitors and environmental sensors feeding directly into kennel dashboards enable differentiated wellness packages for premium boarding tiers.
- GDPR-compliant data portability:Vendors architecting seamless customer record export gain preference among EU facilities fearing vendor lock-in, particularly in France under CNIL guidance.
Industry Challenges
- Veterinary informatics skill scarcity:Facilities struggle to hire staff capable of configuring HL7-FHIR bridges between kennel platforms and practice management systems, extending implementation timelines.
- Legacy on-premises technical debt:Large breeding kennels running decade-old Windows-based systems face disruptive migration costs and staff retraining burdens when transitioning to modern architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kennel Software Market |
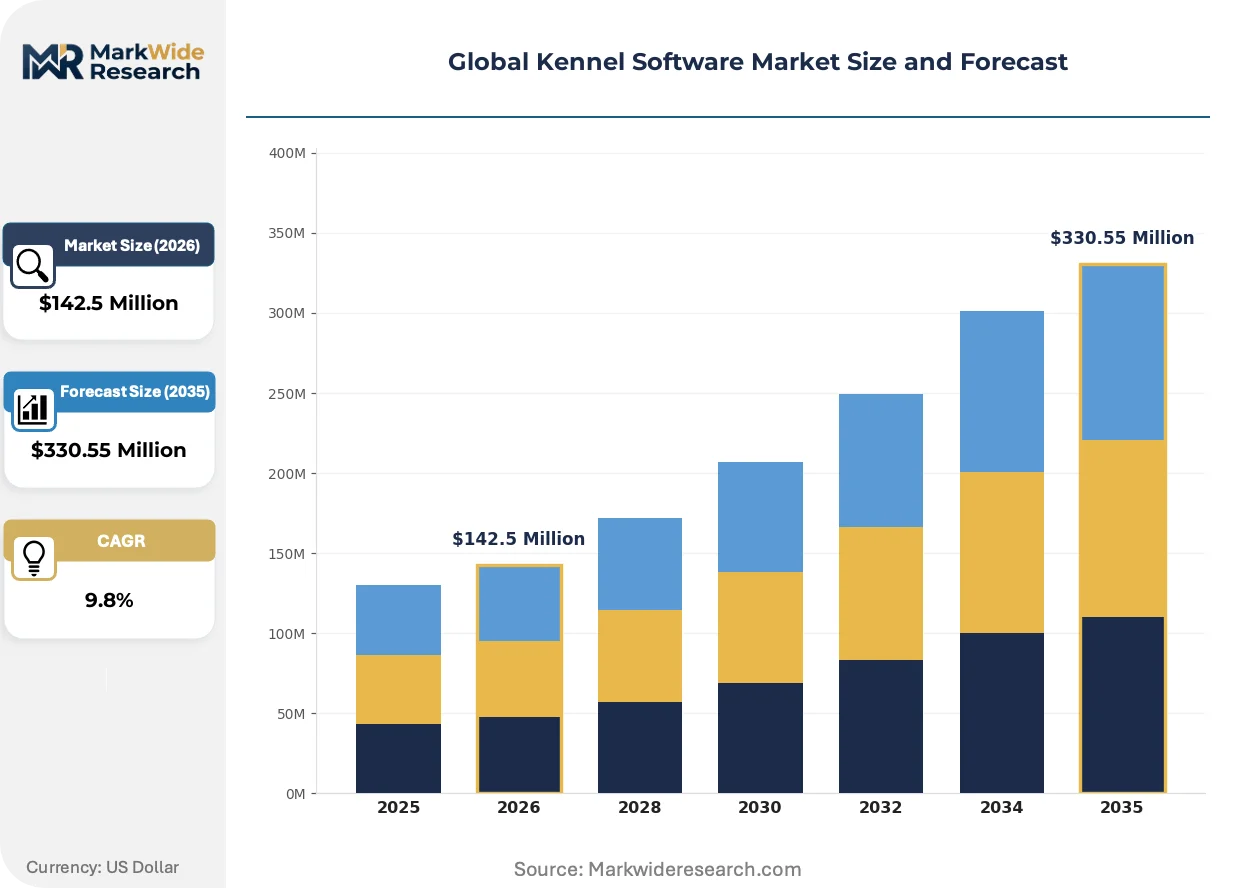
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $330.55 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS, Web-based Application: Boarding Management, Veterinary Scheduling, Customer Relationship Management, Billing & Invoicing, Inventory Tracking End User: Pet Boarding Facilities, Animal Shelters, Veterinary Clinics, Grooming Centers, Pet Daycare Services Solution Type: Appointment Management, Payment Processing, Reporting & Analytics, Staff Management, Marketing Automation |
| Companies Covered | PetExec Inc., DaySmart Software, Gingr, Pawfinity, PedFast Technologies, Software Revolutions Ltd, Shepherd Software, ProPet Software, PawLoyalty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kennel Software Market Shifts & Advancements
Platform architectures are bifurcating between all-in-one suites for enterprise chains and microservice-enabled stacks that let independents compose functionality from specialized vendors.
Embedded AI is hybridizing operational workflows across intake classification, habitat optimization, and predictive health alerting. Mid-size boarding facilities in the United Kingdom and Netherlands are piloting these capabilities fastest, compressing the competitive window for vendors lacking native machine-learning modules. The technology is hybridizing what were separate software categories—kennel management, veterinary records, and customer engagement—into unified data layers.
GDPR's Article 35 data protection impact assessments are mandating privacy-by-design documentation for any automated decision-making affecting animal care protocols. Vendors serving EU markets must now maintain algorithmic registries and human-override mechanisms, elevating compliance costs but creating switching costs for compliant incumbents. French and German facilities under national data authority guidance are demanding these attestations before contract signature.
Subscription flexibility is displacing perpetual licensing as the dominant commercial model among North American independents. Annual contracts with usage-scaled tiers replace upfront capital outlays, enabling smaller operators to access enterprise-grade functionality. This shift is most visible in Texas and Florida metropolitan clusters where pet services entrepreneurship rates exceed national averages.
Global Kennel Software Market Segmentation
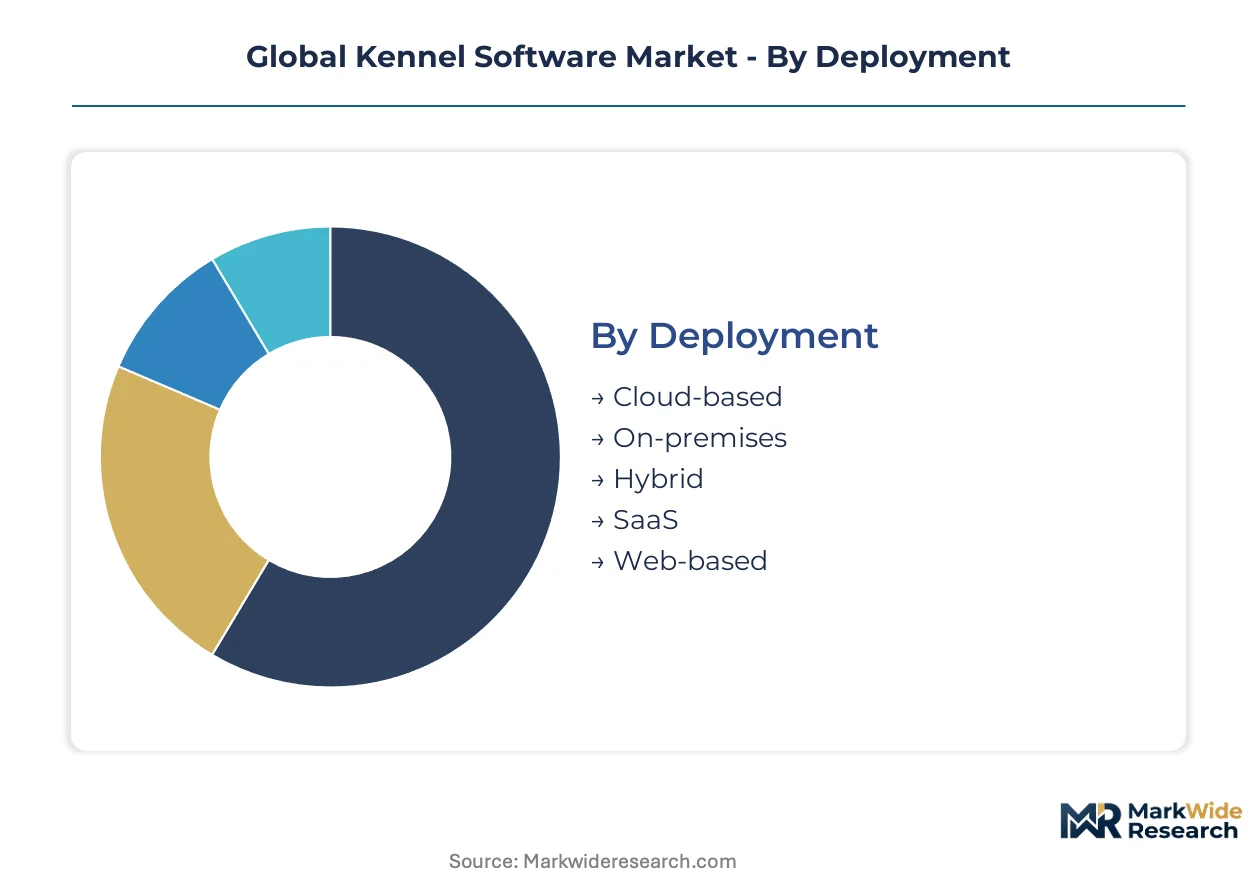
Kennel software vendors architect pricing and feature tiers around operational complexity rather than facility size alone. Deployment elasticity and application modularity determine how platforms penetrate multi-service operators versus single-focus independents.
Deployment:
Use-case spectrum spans capital-constrained startups needing instant activation to breeding operations guarding genetic data sovereignty.
- Cloud-based:Multi-tenant architectures with automatic updates dominate among Texas and Florida metropolitan boarding chains. These facilities prioritize remote staff access and eliminate server maintenance overhead. API connectivity with Stripe and Square enables embedded payment workflows without PCI compliance burden.
- SaaS:Subscription elasticity attracts independent operators converting from paper logs. Monthly billing aligns with seasonal cash flow fluctuations in resort-town boarding facilities. Established volume favors Cloud-based; emerging adoption favors SaaS.
- On-premises:German and Swiss breeding kennels with confidential genetic registries maintain air-gapped installations. Data residency requirements override total cost of ownership calculations.
- Hybrid:Large veterinary clinic networks in Australia synchronize sensitive clinical data locally while pushing customer engagement tools to cloud tiers. TGA audit trails demand this bifurcation.
- Web-based:Browser-native interfaces reduce IT support demands for rural shelters with volunteer technical staff. Minimal installation friction accelerates disaster-response deployments.
Established volume favors Cloud-based; emerging adoption favors SaaS.
Application:
Functional specialization tracks how facilities monetize animal contact hours across boarding, medical, and retail touchpoints.
- Boarding Management:Habitat assignment algorithms optimize cage utilization during holiday surges. Integration with IoT environmental sensors enables premium climate-controlled tier pricing. Demand concentrates in United States multi-location chains where occupancy visibility drives revenue per available kennel.
- Billing & Invoicing:Automated payment collection reduces accounts-receivable labor for Australian veterinary clinics with TGA-mandated record retention. Package pricing for daycare bundles improves customer lifetime value.
- Veterinary Scheduling:HL7-FHIR bridges to practice management systems require specialized implementation partners. Capability scarcity extends deployment timelines.
- Customer Relationship Management:Owner communication portals with photo updates differentiate premium boarding tiers in Japanese metropolitan markets.
- Inventory Tracking:Medicated feed lot tracing satisfies FDA veterinary feed directive compliance for large breeding operations.
Operational complexity favors Boarding Management; margin expansion favors Billing & Invoicing.
End User:
Customer archetypes range from municipal shelters with fixed budgets to luxury boarding facilities commanding per-night rates exceeding hotel tariffs.
- Pet Boarding Facilities:Revenue management tools optimize dynamic pricing during peak holiday windows. Staff scheduling modules reduce overtime exposure in 24-hour operations.
- Veterinary Clinics:Clinical integration requirements in Australia demand TGA-aligned pathology connectivity. Medication logging satisfies regulatory audit trails.
- Pet Daycare Services:High-frequency, low-duration transactions require frictionless check-in workflows. Mobile-first interfaces accommodate millennial owner expectations.
- Animal Shelters:Grant-funded operations prioritize donor management and adoption tracking over billing sophistication.
- Grooming Centers:Appointment density optimization drives platform selection, with calendar synchronization to kennel systems enabling bundled service sales.
Transaction velocity favors Pet Daycare Services; compliance depth favors Veterinary Clinics.
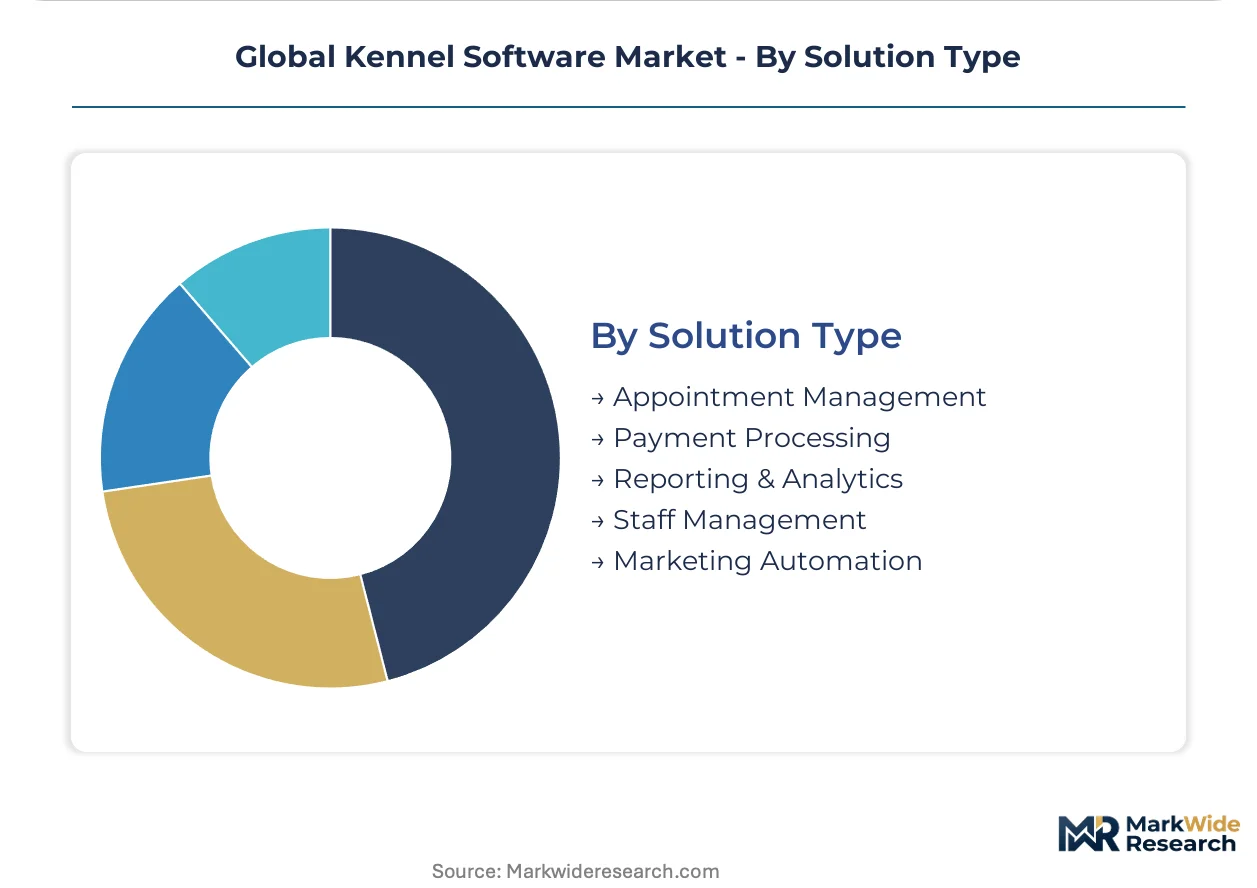
Solution Type:
Modular procurement patterns let facilities compose functionality from specialized vendors rather than accepting monolithic suites.
- Payment Processing:Embedded financial workflows reduce reconciliation labor for multi-service operators. Regional processor fragmentation in Brazil and India forces gateway-agnostic architecture.
- Reporting & Analytics:Occupancy forecasting and staff productivity dashboards attract private-equity-backed clinic networks. Predictive models identify high-churn customer segments.
- Appointment Management:EU AI Act transparency requirements reshape automated scheduling modules in France and Germany. Explainable algorithms command premium positioning.
- Staff Management:High-turnover environments prioritize minimal training overhead. Mobile clock-in and certification tracking reduce administrative burden.
- Marketing Automation:Vaccination reminder sequences and rebooking prompts recover lapsed customers. Email deliverability integration with Mailchimp and Klaviyo extends reach.
Revenue impact favors Payment Processing; operational insight favors Reporting & Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government digitalization incentives and veterinary regulatory harmonization are redrawing geographic adoption curves for kennel management platforms. Facilities in jurisdictions with aligned clinical standards command premium solution architectures.
United States
Multi-location pet boarding chains in Texas and Florida metropolitan clusters drive cloud deployment velocity. FDA veterinary feed directive compliance mandates reshape medication logging modules for large breeding operations. Dallas-Fort Worth anchors the highest concentration of private-equity-backed clinic networks demanding enterprise-grade integration.
Germany
Confidential genetic registries in commercial breeding kennels sustain demand for air-gapped on-premises installations. GDPR Article 35 data protection impact assessments constrain automated scheduling algorithm deployments. Bavarian facilities under LfD Bayern guidance require algorithmic registries before contract signature.
Australia
TGA-aligned veterinary practice management standards elevate clinical integration requirements for boarding-veterinary hybrid facilities. Sydney and Melbourne clinic networks synchronize sensitive pathology data locally while pushing customer engagement tools to cloud tiers. TGA audit trail mandates enforce bifurcated hybrid architectures.
Japan
METI digitalization incentives for small businesses accelerate cloud adoption among independent boarding operators. Rising pet humanization in Tokyo metropolitan markets creates demand for owner communication portals with photo updates. Osaka-based facilities pilot embedded AI for intake classification and habitat optimization.
United Kingdom
Mid-size boarding facilities in London and the Netherlands pilot predictive health alerting capabilities fastest. GDPR compliance documentation requirements compress vendor selection timelines. Manchester veterinary networks demand HL7-FHIR bridges to practice management systems, extending implementation partner scarcity.
Global Kennel Software Market Competitive Landscape
On the supply side, the industry is bifurcating between consolidated platform vendors and specialized microservice providers. Tiered competitive dynamics separate enterprise-scale suite vendors from modular point-solution specialists. Three strategic archetypes dominate: all-in-one suite vendors serving multi-location chains, API-first modular platforms for independents, and legacy on-premises incumbents defending breeding operation accounts. Dominant competitive moves include geographic localization partnerships and algorithmic transparency certifications for EU market access.
Within the established vendor tier, PetExec Inc. and DaySmart Software exemplify contrasting market positions. PetExec occupies a partner-driven onboarding archetype that reduces implementation friction for capital-constrained independents. DaySmart Software anchors the deep integration segment through calendar synchronization capabilities spanning adjacent service workflows. Gingr represents the interface-simplicity vector, targeting facilities where training overhead determines staff retention outcomes.
| Leading Market Players |
|---|
| PetExec Inc. |
| DaySmart Software |
| Gingr |
| Pawfinity |
| PedFast Technologies |
| Software Revolutions Ltd |
| Shepherd Software |
| ProPet Software |
| PawLoyalty |
| Others |
Supply & Pricing Matrix
Dallas-Fort Worth anchors the densest concentration of private-equity-backed pet clinic networks in North America, and this buyer clustering compresses vendor margins while elevating integration complexity premiums. Cloud deployment elasticity lets smaller operators access enterprise-grade modules without capital outlay, yet data sovereignty requirements in German and Swiss breeding kennels sustain premium pricing for air-gapped installations.
Pricing Analysis
Certification level creates the primary spread across vendor tiers, with TGA-aligned clinical integration modules in Australia commanding substantial premiums over basic boarding management suites. Subscription elasticity dominates North American independents, while perpetual licensing persists among European facilities fearing vendor lock-in under GDPR Article 35. Price differentiation tracks deployment complexity: hybrid architectures for Australian veterinary networks carry higher service bundles than pure SaaS offerings. Cost compression in entry-level tiers is intensifying because Stripe and Square API commoditization erodes payment processing markups. Municipal shelters and grant-funded operations exhibit highest price sensitivity; multi-location chains with occupancy optimization needs show lowest.
Supply Chain Analysis
Upstream feedstock for kennel software platforms draws from specialized veterinary informatics talent pools concentrated in the United States, United Kingdom, and Australia. Core components encompass HL7-FHIR interoperability engines, PCI-compliant payment gateways, and machine-learning frameworks for automated scheduling. Single-source vulnerability sits with AWS and Azure infrastructure dominance for cloud-native deployments, where regional outages cascade across multi-tenant customer bases. Distribution runs through direct sales teams for enterprise clinic networks and partner-driven onboarding channels for capital-constrained independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among private-equity-backed clinic networks in Texas and Florida, fragmenting vendor negotiating leverage and compressing implementation timelines. Multi-location chains now demand modular procurement with usage-scaled tiers rather than monolithic suite commitments.
For Market Incumbents: Build algorithmic transparency documentation as a compliance moat, particularly for EU AI Act market access where French and German facilities require attestations before contract signature. Invest in TGA-aligned clinical integration capabilities to defend Australian veterinary network accounts against API-first modular competitors. Vertical integration into embedded payment processing reduces gateway fragmentation exposure in Brazil and India. For New Entrants and Emerging Players: Japanese metropolitan boarding facilities represent underpenetrated white space where METI digitalization incentives coincide with rising pet humanization demand. Target rural shelters with web-based browser-native interfaces that minimize IT support overhead. Partner with regional payment processors in Southeast Asia to circumvent established gateway dependencies. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because API-first architectures are hybridizing separate software categories into unified data layers, rewarding scaled vendors with integration density. Acquisition targets should exhibit embedded AI modules for intake classification and habitat optimization, plus existing algorithmic registries for EU compliance. Watch wearable telemetry convergence with collar-mounted sensors as the inflection signal for premium tier differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7-FHIR bridges to practice management systems extend vendor switching costs for Australian TGA-aligned facilities. |
| Geographic Expansion | Localized cloud offerings in Japan capture METI incentive windows before incumbent localization accelerates. |
| Strategic Partnership | Payment processor alliances in Brazil and India reduce engineering overhead from gateway fragmentation. |
| Acquisition of Specialist Firm | Veterinary informatics boutiques with FHIR expertise alleviate implementation partner scarcity in Manchester networks. |
| Product Launch | GDPR-compliant data portability modules gain preference among EU facilities fearing vendor lock-in under CNIL guidance. |
Research Methodology
Cross-validation between primary interviews with kennel software CTOs, veterinary clinic operations directors, and pet boarding facility owners anchors the qualitative findings against secondary validation from SEC filings, TGA regulatory databases, and EU AI Act implementation guidance. Bottom-up triangulation across deployment model adoption curves and top-down reconciliation against veterinary practice consolidation patterns ensures segmentation integrity.
Calibration against historical cloud migration velocity in Texas and Florida metropolitan clusters shapes the projection framework across deployment models, application types, end-user archetypes, and regional regulatory clusters. CAGRs derive from fitted adoption curves rather than extrapolated linear trends, with embedded AI penetration rates and payment processing integration depth serving as key forecast inputs throughout the modeling period.
Practitioners should monitor EU AI Act enforcement granularity and TGA audit trail mandate expansion for early signals requiring forecast revision. Cross-checking against IHS Markit veterinary practice consolidation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Hypoallergenic Dog Food Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Europe Pet Treats Market
Pet Care Products
Dog Vest Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Mink Oil Market
Pet Care Products
Dog Supplement Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Natural Cat Litter Products Market