
 Cannabidiol CBD Pet Market | 2026-2036
Cannabidiol CBD Pet Market Size, Share, and Industry Trends Forecast 2026-2036
Cannabidiol CBD Pet Market Insights
Single-source hemp extract procurement is pivoting toward multi-origin supplier networks as brands seek supply resilience. Honest Paws leverages certified organic hemp partnerships to sustain premium positioning. Charlotte's Web anchors its competitive stance through vertical control over cultivation and extraction. Green Roads differentiates via third-party testing transparency and pharmacist-formulated product lines.
Cannabidiol for companion animals denotes hemp-derived non-psychoactive formulations, typically containing less than 0.3% THC by dry weight, extracted via CO2 or ethanol methods for oral or topical administration. These products modulate endocannabinoid receptor activity to address inflammation, anxiety, and nociception in mammals. Oils retain the dominant revenue position due to dosing precision and bioavailability advantages over treats. Joint Support applications command premium pricing relative to Skin Care, where efficacy verification remains less standardized. Online Retailers capture expanding share as direct-to-consumer subscriptions bypass veterinary channel gatekeeping.
The FDA maintains ambiguous enforcement posture on CBD pet health claims, while the USDA oversees hemp cultivation licensing under the 2018 Farm Bill framework. State agriculture departments in Colorado and Oregon impose additional testing protocols that exceed federal baselines. Stakeholders must monitor regulatory clarity on veterinary medical claims versus wellness positioning to anticipate channel access shifts.
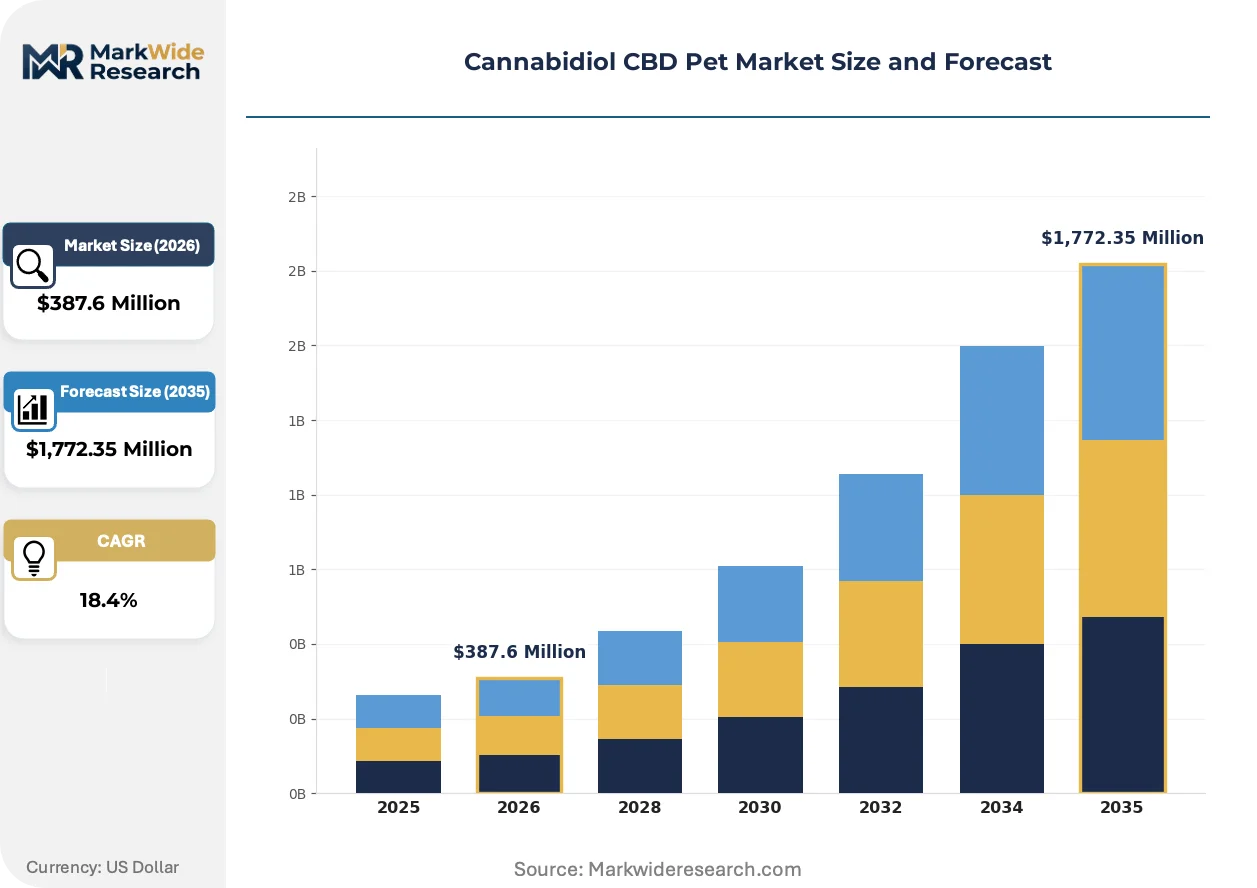
Market Dynamics
The 2018 Farm Bill's hemp descheduling created a compliance patchwork where state agriculture departments impose testing protocols exceeding federal baselines, forcing brands to maintain multiple quality systems simultaneously.
Growth Catalysts
- Veterinary channel legitimization:State veterinary boards in California and Colorado have issued guidance documents permitting practitioner discussion of hemp-derived products, reducing consumer hesitation.
- Endocannabinoid research expansion:University veterinary schools are publishing pharmacokinetic studies on canine CBD metabolism, building clinical credibility for dosing protocols.
- Subscription commerce infrastructure:Direct-to-consumer platforms now offer automated reordering with veterinary telehealth integration, bypassing retail shelf competition.
Market Restraints
- Input cost volatility:Organic hemp biomass prices fluctuate with weather patterns in Kentucky and Oregon growing regions, compressing margin predictability for certified product lines.
- Regulatory friction:FDA warning letters targeting unapproved health claims create channel access risk for products positioned beyond general wellness.
- Technical limitation:First-pass canine metabolism reduces oral CBD bioavailability to approximately 13-19%, requiring higher dosing volumes than human equivalents.
Strategic Opportunities
- Underpenetrated geography:German and French pet specialty retailers remain minimally stocked with CBD SKUs due to novel food authorization requirements, creating first-mover potential.
- Emerging application:Feline anxiety and inflammatory bowel disease represent formulation white spaces with limited competitive entrants.
- Technology convergence:Nanotechnology emulsion combined with transdermal patch delivery is automating bypass of gastrointestinal degradation for chronic pain management.
Industry Challenges
- Veterinary pharmacology expertise gap:Few practicing veterinarians receive cannabinoid therapeutics training, limiting prescription-adjacent recommendation confidence.
- Certification timeline compression:USDA Organic and NASC Quality Seals require 12-18 month audit cycles that delay product launches behind competitor speed-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cannabidiol CBD Pet Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oils, Treats, Capsules, Topicals, Supplements Application: Anxiety Relief, Pain Management, Skin Care, Digestive Health, Joint Support Pet Type: Dogs, Cats, Birds, Small Mammals, Reptiles Distribution Channel: Veterinary Clinics, Pet Specialty Stores, Online Retailers, Pharmacies, Supermarkets |
| Companies Covered | Honest Paws, Pet Releaf, Charlotte's Web, HolistaPet, cbdMD, Canna-Pet, Joy Organics, Green Roads, CBD Living, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cannabidiol CBD Pet Market Trends and Innovations
Formulation science and distribution infrastructure are converging to reshape how cannabinoid products reach companion animals, with precision delivery mechanisms displacing conventional oil tinctures.
Supercritical CO2 extraction with winterization is automating removal of chlorophyll and wax contaminants while preserving minor cannabinoid profiles. Mid-tier pet wellness brands are adopting this equipment to match premium competitor purity claims. The technology is automating quality differentiation that previously required manual batch oversight.
USDA hemp cultivation licensing under the 2018 Farm Bill mandates THC testing by DEA-registered laboratories, adding cost and timeline constraints to harvest release. State agriculture departments in Oregon and Colorado have layered additional heavy metal and pesticide screening requirements. Small-batch producers in these states are responding by consolidating testing contracts with multi-state analytical laboratories.
Subscription-based replenishment with veterinary telehealth integration is displacing episodic retail purchasing among chronic condition managers. Pet owners managing osteoarthritis or separation anxiety in aging dogs are migrating to automated delivery with dosage tracking apps. This shift concentrates most visibly in United States metropolitan markets with established veterinary telehealth platforms.
Cannabidiol CBD Pet Market Segmentation
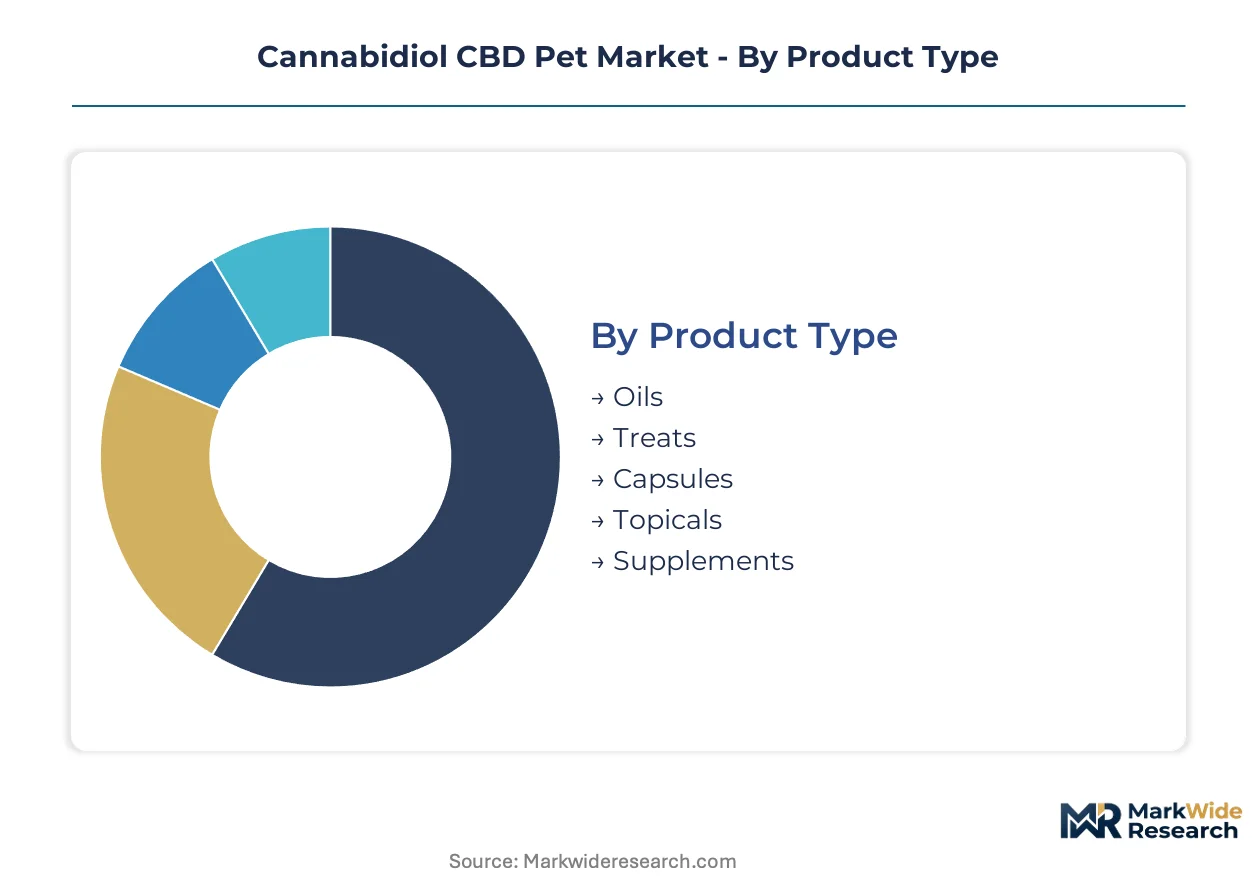
Segmentation in the CBD pet market reveals how formulation science, species-specific physiology, and channel access create distinct competitive arenas. Understanding these divides exposes where margin concentrates and where new entrants face structural barriers.
Product Type:
Standalone oil formulations dominate precision dosing applications, while embedded formats in treats and supplements integrate CBD into daily feeding routines with lower per-dose visibility.
- Oils:Liquid formulations with measured dropper delivery enable titration flexibility for veterinarians managing chronic conditions. Concentrated demand in United States metropolitan markets with established veterinary telehealth platforms reflects pet owner preference for dosing control.
- Treats:Palatable baked or soft-chew matrices mask hemp terpene bitterness while embedding CBD into reward-based administration. Growth concentrates among subscription commerce providers automating replenishment for separation anxiety management in working households.
- Capsules:Hard-shell gelatin or vegetable-based enclosures standardize dosage for multi-pet households.
- Topicals:Transdermal balms and sprays target localized inflammation without systemic absorption.
- Supplements:Powder or liquid additives blend into commercial pet food for passive administration.
Oils lead volumes today; treats are gaining share fastest through subscription channel expansion.
Application:
Cost tier stratification separates premium-priced therapeutic positioning from mass-market wellness claims, with veterinary endorsement commanding price multiples over retail shelf equivalents.
- Joint Support:Anti-inflammatory formulations targeting osteoarthritis in aging canines carry premium pricing reflecting clinical credibility investments. United States demand concentrates in states with veterinary board guidance permitting practitioner discussion, reducing consumer hesitation.
- Anxiety Relief:Calming protocols for separation distress and noise phobia require rapid-onset formulations with pharmacokinetic validation. Growth accelerates in subscription platforms integrating veterinary telehealth for chronic condition monitoring.
- Pain Management:Nociception modulation for post-surgical recovery or degenerative conditions.
- Skin Care:Topical anti-inflammatory and antimicrobial applications for dermatological conditions.
- Digestive Health:Gut microbiome modulation and anti-inflammatory support for inflammatory bowel conditions.
Joint Support commands premium pricing today; Anxiety Relief is expanding most quickly through direct-to-consumer channel development.
Pet Type:
Volume concentration in canine populations reflects body weight scaling for dosing economics, while feline and exotic segments present formulation white spaces with limited competitive entrants.
- Dogs:Large body mass enables cost-effective per-milligram dosing that supports sustainable margin structures. United States demand anchors the category, with Canada and the United Kingdom emerging as secondary adoption markets.
- Cats:Obligate carnivore metabolism and finicky palatability requirements create formulation complexity that deters mass-market entrants. Growth potential concentrates in anxiety and inflammatory bowel disease applications with limited competitive supply.
- Birds:Avian endocannabinoid system research remains preliminary, constraining product development.
- Small Mammals:Rabbits, guinea pigs, and ferrets present dosing precision challenges at low body weights.
- Reptiles:Ectothermic metabolism and limited veterinary cannabinoid research restrict commercial viability.
Dogs dominate volume today; cats represent the steepest expansion trajectory as formulation science addresses species-specific delivery challenges.
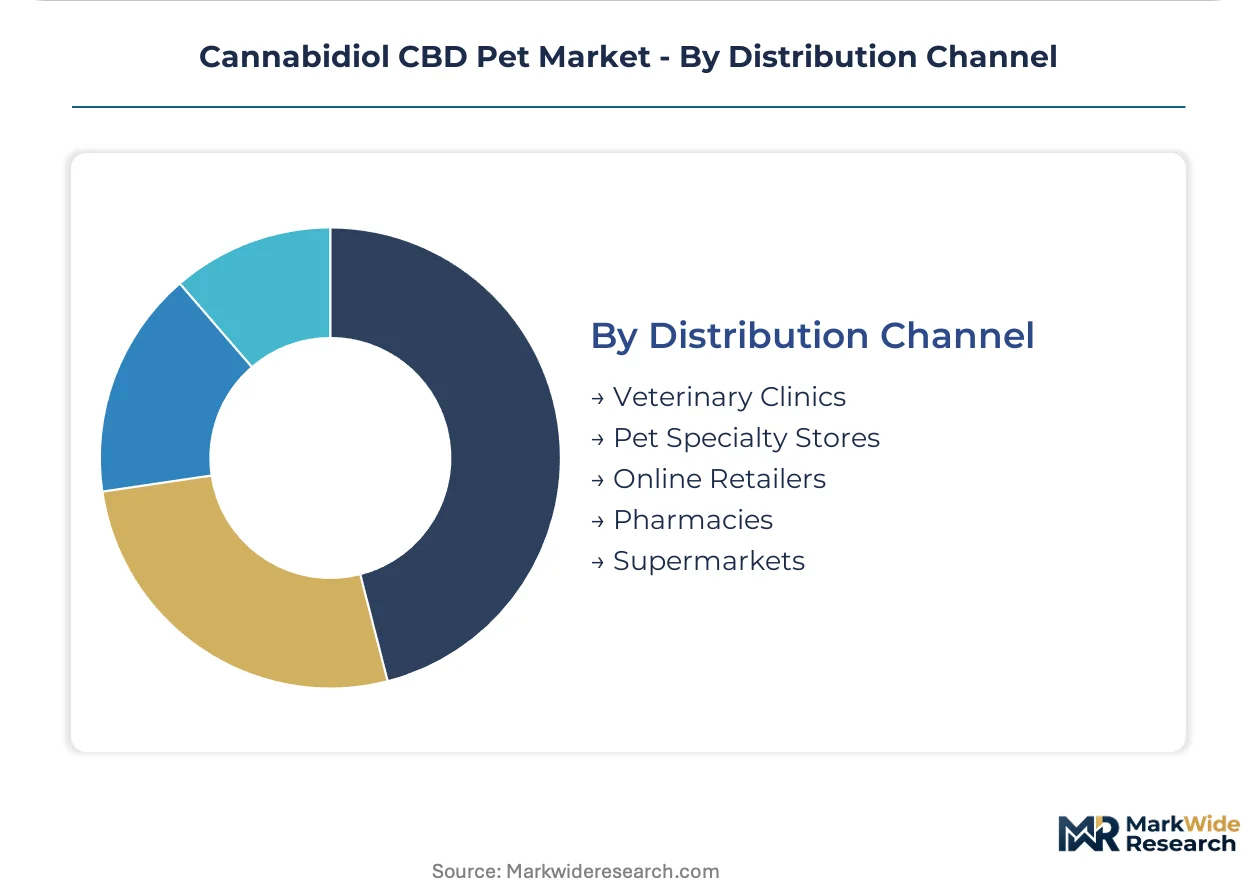
Distribution Channel:
Customer type stratification separates veterinary gatekeeping for therapeutic claims from self-directed wellness purchasing through retail and digital channels.
- Online Retailers:Direct-to-consumer platforms bypass shelf competition through subscription automation and dosage tracking applications. United States metropolitan markets with established veterinary telehealth infrastructure show concentrated migration from episodic retail purchasing.
- Veterinary Clinics:Professional endorsement channels carry prescription-adjacent credibility that supports premium positioning. Access depends on state veterinary board guidance permitting practitioner discussion of hemp-derived products.
- Pet Specialty Stores:Curated retail environments with trained staff provide education-intensive purchase support.
- Pharmacies:Human health retail networks with limited pet-specific formulation expertise.
- Supermarkets:Mass-market retail with minimal staff education and price-competitive positioning.
Online Retailers are climbing the fastest; Veterinary Clinics retain margin leadership through professional endorsement scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where CBD pet brands establish production, with compliance cost gaps between jurisdictions driving facility location decisions. Kentucky and Oregon hemp growers face state-mandated heavy metal screening that exceeds federal baselines, pushing some extraction capacity toward Colorado where testing harmonization reduces overhead. This migration pattern concentrates finished goods manufacturing in states with veterinary board guidance already published.
United States
Canine anxiety and joint support applications dominate demand, with subscription commerce penetration highest in metropolitan markets. The FDA maintains ambiguous enforcement posture on veterinary health claims, while the USDA oversees hemp cultivation licensing under the 2018 Farm Bill. Colorado and California state veterinary boards have issued practitioner guidance documents, reducing consumer hesitation in Denver and Los Angeles corridor markets.
Canada
Secondary adoption concentrates in Ontario and British Columbia, where Health Canada oversight of cannabis products creates distinct compliance pathways from hemp-derived goods. The country's national pharmaceutical regulator distinguishes veterinary health claims from wellness positioning, forcing brands to maintain separate labeling systems. Calgary and Toronto pet specialty retailers are expanding CBD SKU counts as provincial distribution clarifies.
United Kingdom
Novel food authorization requirements from the Food Standards Agency constrain product availability, creating first-mover potential for compliant entrants. London and Manchester veterinary practices are fielding rising client inquiries despite regulatory friction. British hemp cultivation remains minimal, forcing brands to source biomass from European Union suppliers with EFSA-aligned testing protocols.
Germany
BfArM oversight of cannabis products and BVL regulation of animal feed create dual compliance exposure for pet CBD formulations. Munich and Hamburg pet specialty retailers remain minimally stocked due to novel food authorization delays. German veterinary schools are publishing pharmacokinetic studies that may accelerate practitioner comfort with cannabinoid therapeutics.
France
ANSM positioning on veterinary CBD remains restrictive, with novel food authorization timelines extending 18-24 months for hemp-derived ingredients. Paris and Lyon pet wellness markets show latent demand constrained by channel access limitations. French hemp cultivation in Auvergne-Rhône-Alpes is expanding, though extraction capacity lags domestic biomass growth.
Cannabidiol CBD Pet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue feline-specific formulations and transdermal delivery mechanisms. The vendor base stratifies across three tiers: vertically integrated cultivators with captive hemp supply, contract-manufacturing brands relying on third-party extraction, and white-label distributors with minimal quality infrastructure. Strategic archetypes include organic-certified premium specialists, pharmacist-formulated transparency leaders, and subscription-commerce-native direct brands. Competitive moves concentrate on multi-origin supplier network construction and third-party testing transparency investments.
Among US-based wellness specialists, Honest Paws and Charlotte's Web exemplify divergent supply strategies, with the former leveraging certified organic hemp partnerships and the latter anchoring positioning through cultivation-to-extraction vertical control. Green Roads occupies a pharmacist-formulated transparency tier that distinguishes its third-party testing protocols. These three entities represent how quality-system investments and channel access choices segment competitive positioning in a market where regulatory clarity remains pending.
| Leading Market Players |
|---|
| Honest Paws |
| Pet Releaf |
| Charlotte's Web |
| HolistaPet |
| cbdMD |
| Canna-Pet |
| Joy Organics |
| Green Roads |
| CBD Living |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between USDA Organic and conventional hemp extracts bifurcates both pricing power and supplier qualification requirements. Premium positioning commands sustained margin capture through controlled cultivation partnerships, while mass-market tiers compete on input cost arbitrage across multi-origin sourcing networks.
Pricing Analysis
Distributor margin layers in veterinary channels absorb 35-45 points before clinic markup, compressing landed costs for brands dependent on professional endorsement. Three-tier pricing structure across premium, standard, and economy levels separates NASC-certified organic lines from conventional extracts and white-label commodities. Price differentiation hinges on third-party testing transparency and state-level compliance depth, with California and Oregon protocols adding cost premiums. Veterinary clinics show lowest price sensitivity due to prescription-adjacent positioning; mass-market retail buyers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from major brands now mandate qualified backup suppliers across Kentucky, Oregon, and Colorado growing regions. Raw material flows draw from organic hemp biomass, DEA-registered testing capacity, and certified extraction equipment. Tariff exposure on European biomass imports threatens margin stability for UK and German market entrants. Distribution runs through direct-to-consumer platforms, veterinary wholesale networks, and pet specialty retail with divergent service level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
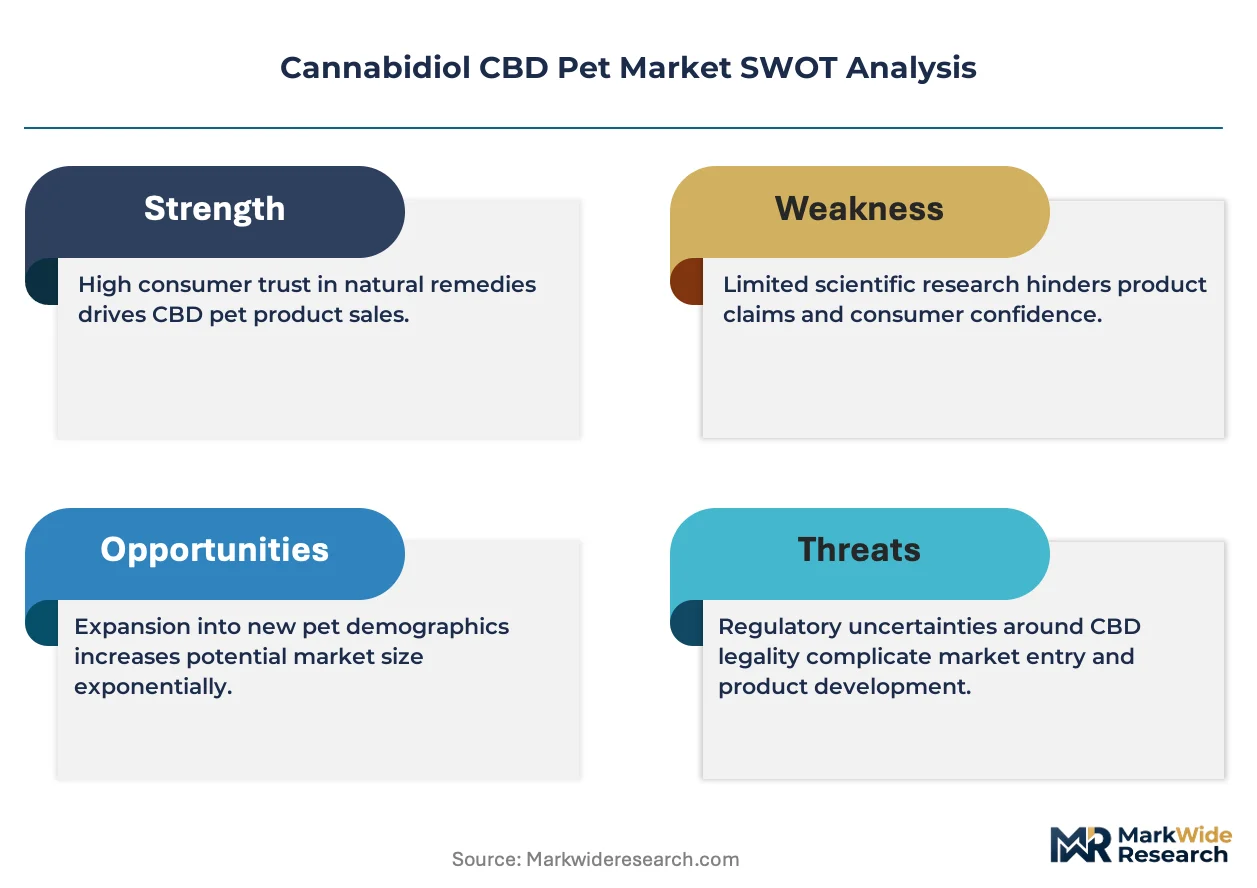
The Cannabidiol CBD Pet Market compounds steadily as veterinary legitimization normalizes cannabinoid therapeutics in clinical practice. Endocannabinoid research expansion builds dosing credibility that sustains premium pricing power.
For Market Incumbents: Extend formulation pipelines into feline-specific applications and transdermal delivery mechanisms before competitive entry accelerates. Consolidate multi-origin supplier networks to defend against organic hemp price volatility in Kentucky and Oregon. Deepen veterinary telehealth platform integrations to lock subscription renewal rates. For New Entrants and Emerging Players: Capture underpenetrated German and French pet specialty retail through novel food authorization compliance investments. Target feline anxiety and inflammatory bowel disease formulations where competitive supply remains minimal. Pursue pharmacist-formulated positioning with transparent third-party testing protocols to differentiate from established organic brands. For Investors and Strategic Acquirers: Consolidation pressure builds where certification timeline compression disadvantages small-batch producers against scaled quality systems. Five-to-ten year viability favors vertically integrated cultivators with captive hemp supply and multi-state testing harmonization. Watch FDA enforcement clarity on veterinary health claims as the critical inflection signal for channel access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Origin Supplier Network Construction | Builds resilience against organic hemp price volatility in Kentucky and Oregon growing regions. |
| Feline-Specific Formulation Development | Addresses white-space demand in anxiety and inflammatory bowel disease applications with limited entrants. |
| Veterinary Telehealth Platform Integration | Automates subscription retention through dosage tracking and chronic condition monitoring infrastructure. |
| USDA Organic Certification Investment | Creates 12-18 month audit barrier that delays competitor speed-to-market behind established players. |
| Transdermal Delivery Mechanism R&D | Bypasses canine first-pass metabolism limitations through nanotechnology emulsion and patch innovation. |
Research Methodology
Multiple input streams — executive interviews with pet wellness brand leadership, procurement discussions with veterinary distributors, and regulatory affairs consultations with state agriculture departments — were reconciled against secondary validation. Primary fieldwork engaged product formulators, veterinary telehealth platform operators, and pet specialty retail category managers. Secondary sources included USDA hemp cultivation licensing records, FDA warning letter archives, state veterinary board guidance documents, and subscription commerce platform disclosures. Bottom-up SKU-level modeling and top-down category sizing were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against panel input from supply chain participants to anchor projection assumptions across the analysis window. Segmentation dimensions modeled include product formulation type, application indication, pet species, and distribution channel structure. CAGRs were derived from fitted growth curves applied to normalized baseline data. Industry-specific forecast inputs incorporated veterinary board guidance publication timelines and novel food authorization progressions in European markets.
Regulatory enforcement shifts, veterinary pharmacology training adoption rates, and organic hemp harvest yield variability are the dominant revision risks to modeled outputs. Deviation in FDA clarity on veterinary health claims would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Hotels Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Pet Toys Market
Pet Care Products
Cat Mat Market
Pet Care Products
Europe Dog Food Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
North America Cat Food Market
Pet Care Products
North America Pet Treats Market
Pet Care Products
Cat Furniture and Scratchers Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
Dog Pen Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Gcc Pet Food Market