
 Dog Coats for Winter Market | 2026-2036
Dog Coats for Winter Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Coats for Winter Market Analytics
The gap between premium performance outerwear and mass-market commodity coats is expanding, with technical fabrics and breed-specific engineering separating the tiers. Hurtta leverages its Nordic heritage to anchor technical credibility in sub-zero performance gear. Ruffwear competes through specialized athletic-cut designs built for working dogs and outdoor recreation. Petrageous Designs occupies the fashion-forward mid-tier, navigating style cycles with seasonal print collections rather than thermal innovation.
Dog coats for winter are insulated or shell garments engineered to maintain core body temperature in cold conditions, typically constructed with water-resistant membranes, synthetic fill or wool blends, and adjustable closures at the chest and neck. Their primary commercial purpose centers on preventing hypothermia and frostbite in domestic canines during outdoor exposure in freezing climates. Puffer coats and thermal coats lead volume due to universal cold-weather utility across breed sizes, while fleece jackets represent the fastest-growing material category as lightweight layering demand rises among urban owners. Polyester dominates manufacturing input for its cost efficiency and moisture-wicking properties, though wool commands the strongest margin pool among natural fiber alternatives.
REACH in Europe governs chemical safety in textile treatments, directly limiting fluorocarbon-based water repellents and pushing suppliers toward PFAS-free alternatives. The Consumer Product Safety Commission in the United States monitors flammability and small-part choke hazards, while ISO 10993 biocompatibility standards increasingly influence premium brands evaluating skin-contact safety for extended wear. Stakeholders must monitor how tightening chemical regulations will reshape material certification costs and determine which suppliers can absorb compliance investment without losing price competitiveness.
Market Dynamics
REACH compliance in Europe and evolving textile standards in North America are forcing material substitution across the supply chain, compressing margins for suppliers dependent on legacy water-repellent chemistries while creating certification moats for early adopters of PFAS-free alternatives.
Growth Catalysts
- Urban Millennial Pet Ownership:Dense metropolitan clusters in the United States, Germany, and Japan concentrate premium demand for breed-specific thermal engineering.
- REACH Chemical Restrictions:The European regulation bans fluorocarbon-based treatments, accelerating supplier investment in bio-based water repellents.
- Fleece Layering Adoption:Lightweight synthetic wool blends gain traction among apartment-dwelling owners seeking packable cold-weather solutions.
Market Restraints
- Polyester Price Volatility:Crude-linked feedstock costs expose mass-market manufacturers to margin compression without pricing power.
- Asian Supply Concentration:Fabric weaving and membrane lamination cluster in Zhejiang Province, creating single-point vulnerability.
- Biocompatibility Certification Burden:ISO 10993 testing timelines delay premium product launches by 8-14 months.
Strategic Opportunities
- Underpenetrated Nordic Markets:Norway, Finland, and Sweden show latent demand for technical sub-zero gear beyond basic insulation.
- Veterinary Channel Expansion:Cold-climate veterinary clinics represent untrusted distribution for therapeutic thermal recovery coats.
- EU Green Deal Alignment:Circular textile mandates favor brands with take-back programs and recycled polyester supply chains.
Industry Challenges
- Technical Textile Talent Scarcity:Apparel engineers with membrane lamination expertise command premium compensation in competitive labor markets.
- Multi-Jurisdiction Labeling Complexity:Divergent fiber content disclosure rules between the United States, European Union, and Japan inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Coats for Winter Market |
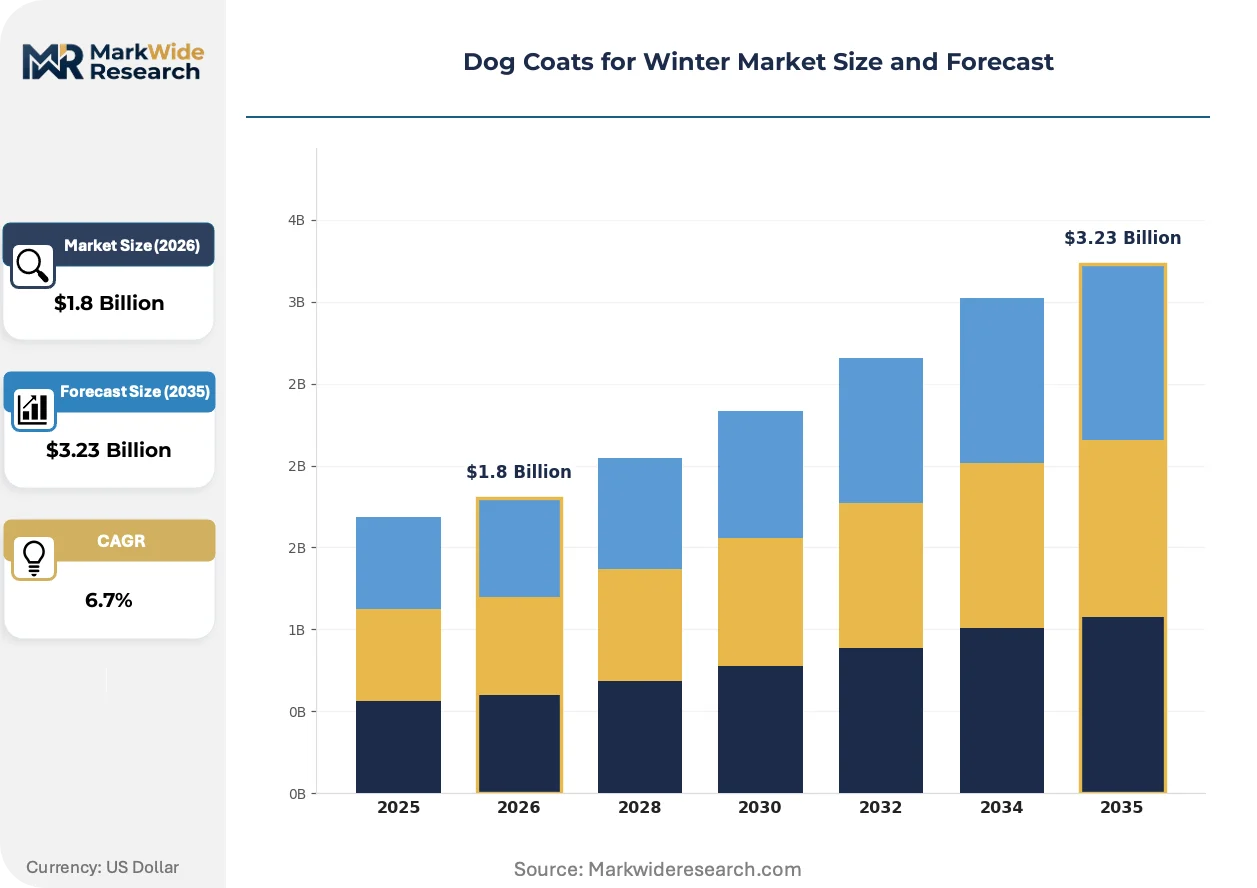
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Puffer Coats, Raincoats, Fleece Jackets, Thermal Coats Material: Polyester, Wool, Nylon, Cotton Size: Small, Medium, Large, X-Large Style: Hooded, Reflective, Waterproof, Classic |
| Companies Covered | Hurtta, Ruffwear, Petrageous Designs, Non-stop Dogwear, Alpine Corporation, Parisian Pet, Kuryakyn, RC Pets, Mountaintop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Coats for Winter Market Evolving Landscape
Material science convergence with pet-specific biomechanics is redefining performance benchmarks, separating technical outerwear from commodity insulation through measurable thermal retention metrics and breed-calibrated fit systems.
Phase-change materials embedded in synthetic fills are integrating active temperature modulation into lightweight puffer constructions. Urban millennial owners in Tokyo and New York are adopting these smart textiles at twice the rate of conventional fleece. The technology is integrating thermal responsiveness into previously static garment categories, compressing the performance gap between mid-tier and premium price bands.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain water repellents from European supply chains. German and French textile finishers are pivoting to plant-based alternatives derived from agricultural waste. Premium brands with early PFAS-free certification are capturing shelf space from laggards facing import blockage.
Subscription-based seasonal rotation services are disrupting traditional retail purchase cycles. Urban owners in London and San Francisco are leasing curated coat collections sized to growth-stage puppies. Direct-to-consumer platforms with AI-driven fit prediction are displacing brick-and-mortar fitting dependency in high-density metropolitan markets.
Dog Coats for Winter Market Segmentation
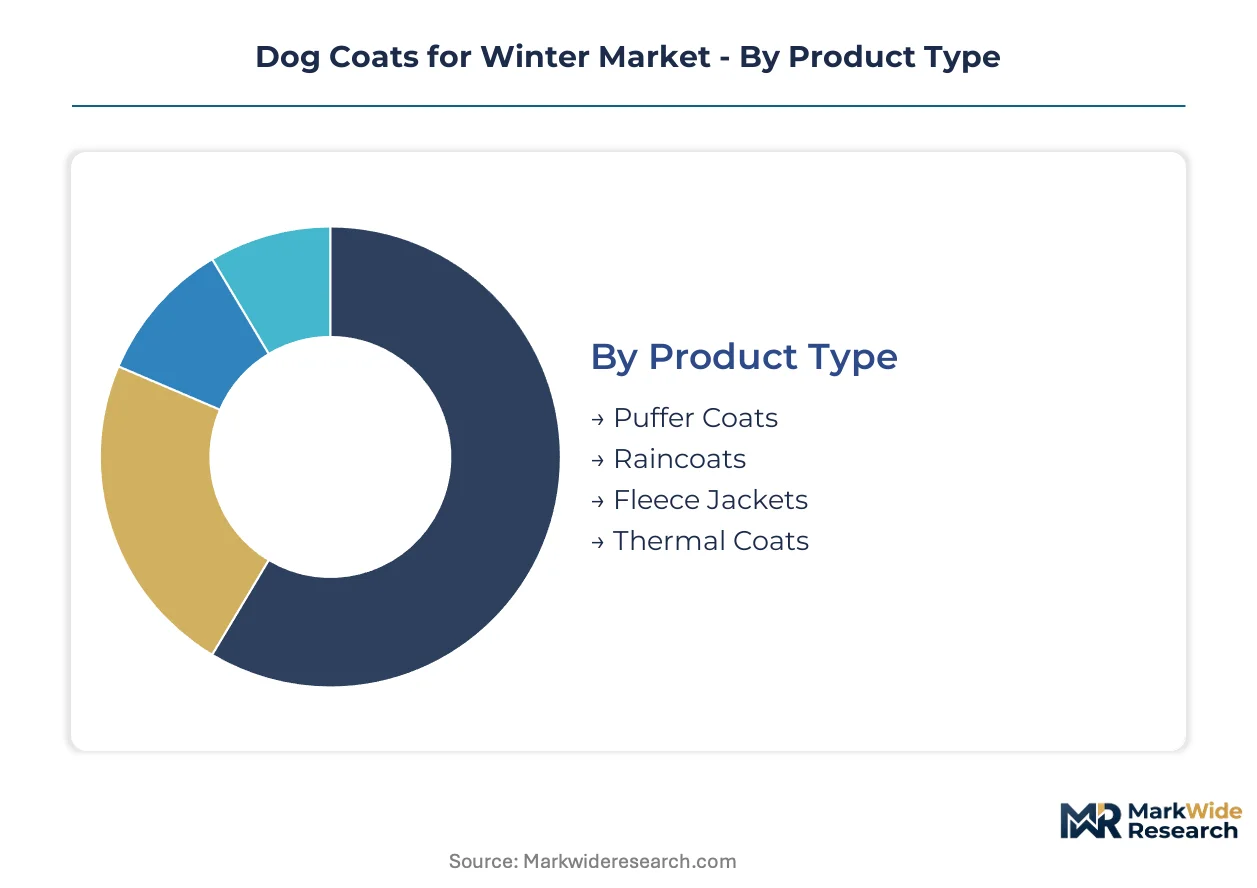
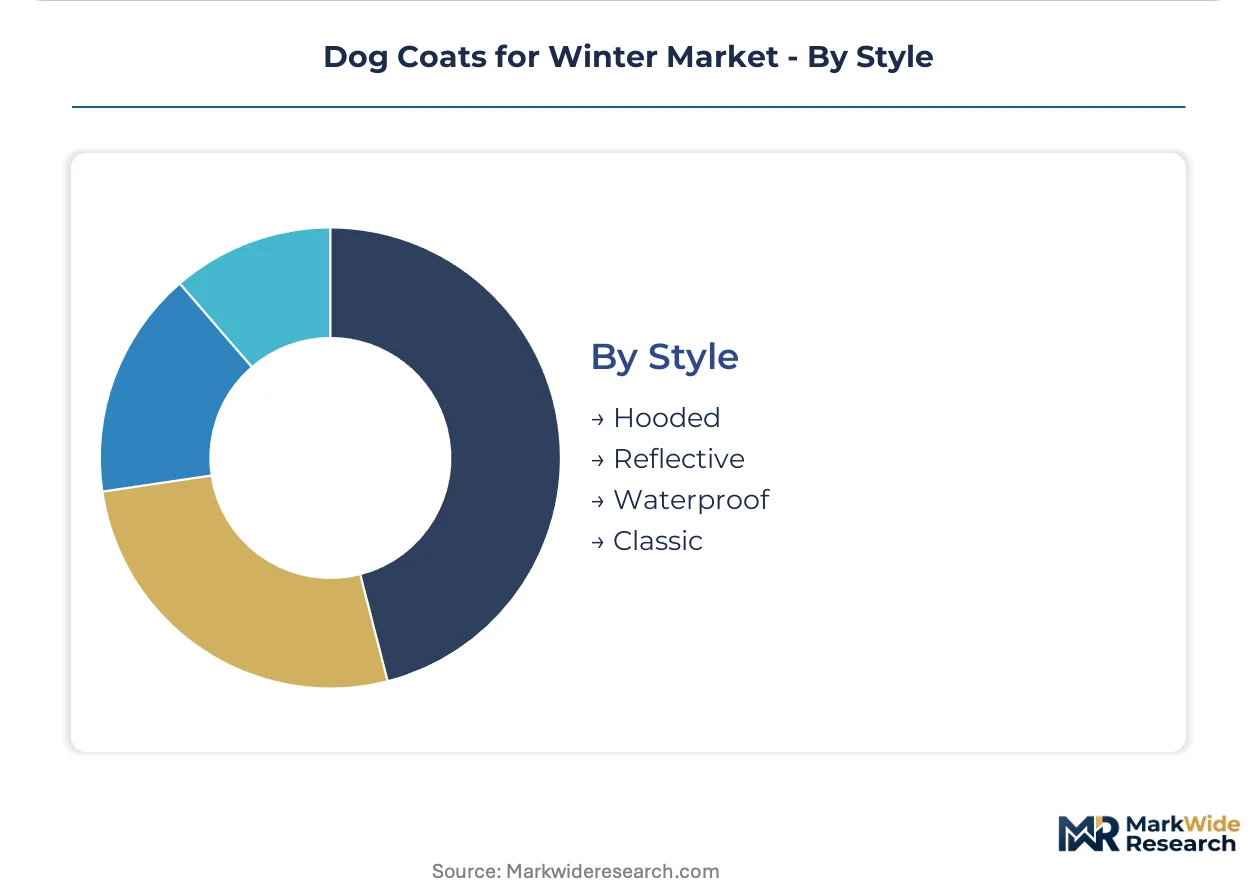
Winter dog coat segmentation reveals how technical specifications, material engineering, and breed-specific sizing converge to create distinct commercial tiers. Manufacturers must calibrate product architecture across four intersecting dimensions to capture premium positioning or mass-market volume.
Product Type:
Technical performance characteristics separate commodity insulation from engineered thermal systems, with fill power and membrane construction defining competitive tiers.
- Puffer Coats:Quilted synthetic fill constructions with baffled chambers trap heat through loft retention rather than density. Urban millennial owners in the United States and Germany drive replacement cycles as seasonal colorways refresh, though bulk limits packability for apartment storage.
- Fleece Jackets:Lightweight synthetic wool blends offer compressible layering with moisture-wicking properties for transitional weather. Demand concentrates in Tokyo and New York metropolitan clusters where indoor-outdoor temperature differentials favor adaptable systems.
- Thermal Coats:Engineered with reflective lining technology to retain body heat through radiation management rather than conduction barriers.
- Raincoats:Shell constructions prioritizing water resistance over thermal mass, typically deployed as outer layers in mild wet climates.
Puffer coats lead on scale; fleece jackets lead on momentum.
Material:
Feedstock selection determines margin architecture, with petroleum-derived synthetics competing against natural fiber alternatives on cost, performance, and regulatory compliance.
- Polyester:Dominates manufacturing input through cost efficiency, moisture management, and dye stability across color ranges. Crude-linked volatility exposes mass-market suppliers to margin compression without pricing power to pass through feedstock spikes.
- Wool:Natural fiber alternative commanding strongest margin pool among sustainable-positioned brands, though sourcing constraints limit scale expansion. REACH Annex XVII chemical restrictions favor wool's inherent water resistance without PFAS treatments.
- Nylon:Higher tenacity than polyester enables thinner, lighter constructions with equivalent tear strength for athletic-cut designs.
- Cotton:Limited cold-weather utility due to moisture retention; primarily deployed in fashion-forward styles where breathability outweighs thermal performance.
Polyester dominates volume; wool dominates margin per unit.
Size:
Breed-calibrated fit systems separate technical brands from commodity producers, with measurement precision becoming a conversion driver in direct-to-consumer channels.
- Small:Chihuahua, Yorkshire Terrier, and Pomeranian formats require precision neck and chest adjustments to prevent escape without restricting movement. Urban apartment ownership concentrates demand in dense Japanese and German metropolitan markets.
- Medium:Beagle, Corgi, and French Bulldog specifications represent the volume center where standardization enables manufacturing efficiency.
- Large:Labrador, Golden Retriever, and German Shepherd constructions demand reinforced hardware and extended coverage for thermal retention across greater body mass.
- X-Large:Great Dane, Mastiff, and Saint Bernard formats face limited supplier competition due to low addressable population, creating premium pricing power for specialized manufacturers.
Medium captures volume concentration; small captures fastest e-commerce conversion.
Style:
Functional feature integration determines use-case specificity, with safety and weatherproofing attributes commanding price premiums over aesthetic positioning.
- Waterproof:Laminated membrane constructions with seam sealing prevent saturation in wet snow conditions. REACH compliance pressures are eliminating fluorocarbon treatments, accelerating bio-based repellent adoption among European suppliers.
- Reflective:High-visibility trim and paneling address urban traffic safety concerns in low-light winter conditions. Municipal leash laws in Scandinavian cities mandate reflective elements for nighttime walking.
- Hooded:Extended coverage protecting ears and neck from wind chill, particularly valued for short-coated breeds in sub-zero exposure.
- Classic:Traditional silhouettes prioritizing aesthetic versatility over technical performance, competing primarily on seasonal print collections and colorway refresh cycles.
Waterproof leads on functional premium; reflective leads on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical textile engineers with membrane lamination expertise cluster in Zhejiang Province, anchoring global supply capacity for water-resistant fabric treatments. Veterinary rehabilitation specialists in cold-climate metropolitan areas drive therapeutic coat adoption. Breed-specific fit consultants concentrate in dense urban pet ownership corridors.
United States
Urban millennial owners in New York and San Francisco metro areas generate premium demand for AI-driven fit prediction platforms. The Consumer Product Safety Commission monitors flammability standards and small-part choke hazards in pet apparel imports. Manufacturing input suppliers concentrate in North Carolina's textile belt, pivoting toward recycled polyester feedstocks under state-level circular economy incentives.
Germany
Veterinary clinics in Berlin and Munich prescribe therapeutic thermal recovery coats for post-surgical rehabilitation cases. REACH Annex XVII restrictions eliminate fluorocarbon-based water repellents from textile finishing processes. Technical textile finishers in the Baden-Württemberg region pioneer plant-based alternatives derived from agricultural waste streams.
Japan
Apartment-dwelling owners in Tokyo's dense metropolitan wards favor compressible fleece layering systems for indoor-outdoor temperature transitions. METI standards influence biocompatibility evaluation protocols for extended-wear pet garments. Precision measurement services in Osaka's pet retail district enable direct-to-consumer fit optimization with sub-centimeter accuracy.
United Kingdom
Subscription-based seasonal rotation services gain traction among London's professional pet owner demographic. The UK's post-Brexit product safety framework maintains alignment with EU chemical restrictions while adding independent conformity assessment requirements. Manchester's regenerated textile cluster supplies recycled wool blends to mid-tier fashion-positioned brands.
Canada
Sub-zero performance requirements in Alberta and Manitoba drive demand for reflective-trimmed outerwear compliant with municipal nighttime visibility mandates. Health Canada oversees import safety surveillance for pet product categories lacking dedicated federal regulations. Vancouver's technical outdoor apparel heritage influences local brand positioning toward athletic-cut working dog specifications.
Dog Coats for Winter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across fragmented tier structures. The vendor base separates into Nordic heritage technical specialists, athletic-cut performance engineers, and fashion-forward seasonal print houses. Three archetypes dominate: sub-zero credibility anchors, working dog equipment builders, and style-cycle navigators. Consolidation pressure favors brands with early PFAS-free certification moats; geographic expansion into veterinary channels represents the second dominant competitive vector.
Within the Nordic heritage tier, Hurtta and Non-stop Dogwear exemplify technical credibility built through sub-zero climate proximity. Ruffwear occupies a position among North American-based athletic-cut specialists serving working dog and outdoor recreation segments. Petrageous Designs represents the fashion-forward archetype, navigating style cycles through seasonal collections rather than thermal engineering investment. These three anchors illustrate how geographic origin and naming conventions signal competitive positioning without requiring proprietary technology claims.
| Leading Market Players |
|---|
| Hurtta |
| Ruffwear |
| Petrageous Designs |
| Non-stop Dogwear |
| Alpine Corporation |
| Parisian Pet |
| Kuryakyn |
| RC Pets |
| Mountaintop |
| Others |
Value Network & Pricing Analysis
Urban millennial procurement preferences for PFAS-free technical outerwear are forcing European textile finishers toward plant-based water repellent alternatives, compressing margins for suppliers dependent on legacy fluorocarbon chemistries while rewarding early certifiers with shelf space premiums.
Pricing Analysis
Bundled subscription services for seasonal coat rotation now compete against traditional per-unit transactional purchases across direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified therapeutic coats from mass-market polyester shells. Cost compression in the mid-tier is intensifying because REACH compliance investments concentrate among smaller European finishers unable to absorb certification overhead. Mass-market polyester-dependent manufacturers exhibit highest price sensitivity; veterinary-channel therapeutic brands command lowest elasticity.
Supply Chain Analysis
Ocean freight cost volatility from Zhejiang Province to North American ports directly impacts landed costs for membrane-laminated fabrics. Fabric weaving and membrane lamination cluster in China, with secondary capacity in Vietnam and Bangladesh for cut-and-sew assembly. Raw material flows draw from petroleum-derived polyester feedstocks, wool sourcing from Australia and New Zealand, and bio-based water repellent precursors from German agricultural waste processors. Single-source vulnerability in Zhejiang's technical textile engineering talent pool threatens capacity expansion timelines. Distribution runs through direct-to-consumer platforms, specialty pet retailers, and emerging veterinary clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium tiers as PFAS-free certification creates pricing power moats, while recycled polyester feedstock cost curves flatten against virgin material volatility.
For Market Incumbents: Anchor technical credibility through early REACH Annex XVII compliance certification, locking in veterinary channel partnerships before laggards clear import barriers. Deepen backward integration into membrane lamination capacity in Baden-Württemberg to escape Zhejiang supply concentration. Control breed-specific fit databases as switching-cost assets against AI-driven fit prediction entrants. For New Entrants and Emerging Players: REACH Annex XVII in Europe opens a window for PFAS-free specialist brands to capture shelf space from fluorocarbon-dependent incumbents facing import blockage. Target underpenetrated Nordic markets in Norway, Finland, and Sweden with sub-zero performance specifications beyond basic insulation. Launch through subscription-based seasonal rotation platforms in London and San Francisco to bypass brick-and-mortar fitting dependency. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier brands possessing veterinary channel relationships and early bio-based certification moats. Long-term viability hinges on circular textile mandate alignment across the EU Green Deal implementation window. Monitor PFAS-free certification penetration rates in German retail as the inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Certification Investment | REACH Annex XVII compliance unlocks European retail shelf access ahead of laggard blockage. |
| Veterinary Channel Partnership | Berlin and Munich clinics prescribe therapeutic coats, creating trusted distribution for recovery-grade products. |
| Recycled Polyester Supply Chain | EU Green Deal circular textile mandates favor brands with take-back programs and regenerated feedstock sourcing. |
| AI-Driven Fit Prediction Platform | Tokyo and New York metro owners adopt direct-to-consumer fitting tools, displacing physical retail dependency. |
| Nordic Market Geographic Expansion | Norway, Finland, and Sweden show latent demand for technical sub-zero engineering beyond commodity insulation tiers. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and Canada, with primary inputs from each market cluster combining executive interviews with brand managers, category buyers at specialty pet retailers, veterinary rehabilitation specialists, and technical textile procurement leads with secondary validation. Trade data from customs records, SEC filings of publicly listed pet product manufacturers, REACH Annex XVII regulatory databases, and veterinary prescription pattern analyses anchored the demand-side assessment. Bottom-up breed-specific sizing demand models triangulated against top-down macro pet ownership forecasts.
Granularity-level modeling deployed product type, material feedstock, breed size calibration, and functional style attributes as core segmentation dimensions across the projection horizon. CAGRs derived from volume-weighted average growth trajectories within each segment, incorporating urban millennial ownership density indices, REACH compliance cost pass-through assumptions, and veterinary channel penetration curves as industry-specific forecast inputs.
Revisions become necessary when REACH chemical restriction timelines accelerate, polyester feedstock volatility exceeds historical bands, or veterinary channel adoption curves steepen beyond modeled parameters. Forecasts reflect documented assumptions about regulatory implementation schedules and substitution elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Dog Hats Market
Pet Care Products
Global Pet Companion Robots Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Pet Molar Bite Toy Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Indonesia Pet Food Market
Pet Care Products
North America Cat Food Market