
 Italy Pet Food Market | 2026-2036
Italy Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Pet Food Market Foresight
Subscription-based auto-replenishment services is recalibrating how Italian households purchase pet nutrition, shifting volume from impulse retail toward locked-in recurring revenue streams. Nestlé Purina PetCare leverages its direct-to-consumer platform to capture repeat orders in northern metropolitan zones. Mars Petcare Italy anchors its position through veterinary channel partnerships that bundle therapeutic diets with clinic loyalty programs. Farmina Pet Foods differentiates via region-specific formulations using locally sourced proteins from Italian supply chains.
Italy pet food comprises formulated nutritional products manufactured through extrusion, canning, or cold-pressing processes, designed to meet specific species dietary requirements across complete and complementary feeding regimes. Dry food dominates volume due to shelf stability and lower per-kilogram logistics costs, while wet food commands margin premiums through humanization positioning and moisture-content benefits for feline renal health. Grain-free and high-protein ingredient categories attract formulation investment as owners scrutinize carbohydrate ratios and protein sourcing transparency.
Italy's Ministry of Health enforces pet food labeling under EU Regulation 767/2009, while the National Institute of Health monitors Salmonella and mycotoxin thresholds in raw and dehydrated products. FSSAI-aligned import checks on non-EU protein meals shape supplier eligibility for brands sourcing outside the single market. Stakeholders must track pending EU-wide packaging waste directives that will mandate recycled content minimums in flexible pet food pouches.
Market Dynamics
Subscription auto-replenishment is restructuring Italian pet food distribution, locking households into recurring revenue streams and displacing impulse retail purchases in northern metropolitan zones.
Growth Catalysts
- EU Regulation 767/2009 labeling harmonization:Standardized nutritional declarations reduce cross-border compliance costs for Italian manufacturers exporting to France and Germany.
- Lombardy urban cat ownership density:Milan's apartment-dwelling feline population drives premium wet food volume through convenience-oriented purchasing patterns.
- Cold-pressing technology adoption:Lower-temperature processing preserves thermolabile vitamins, attracting formulation investment from specialty producers in Emilia-Romagna.
Market Restraints
- Poultry meal import dependency:Italian producers rely on Brazilian and Argentine rendered protein, exposing margins to currency volatility and shipping cost spikes.
- Raw material Salmonella screening:Italy's National Institute of Health mandates batch testing that extends lead times for dehydrated treat manufacturers.
- Veterinary channel concentration:Therapeutic diet distribution concentrates through clinic networks in Turin and Bologna, limiting independent retailer access to prescription segments.
Strategic Opportunities
- Sicily and Calabria underpenetration:Southern Italy's lower pet ownership rates present whitespace for affordable dry food formats distributed through agricultural cooperatives.
- EU packaging waste directive compliance:Recycled content mandates in flexible pouches create first-mover advantage for domestic converters with circular supply chain partnerships.
- Veterinary telehealth bundling:Remote consultation platforms enable subscription platforms to attach diagnostic services to recurring nutrition orders.
Industry Challenges
- Pet food technologist scarcity:Italian universities produce limited graduates with dual competency in animal nutrition and extrusion engineering, forcing producers to recruit from Dutch and Danish talent pools.
- Legacy ERP integration with D2C platforms:Mid-sized manufacturers in Veneto struggle to synchronize inventory systems between veterinary wholesale and direct-to-consumer channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Pet Food Market |
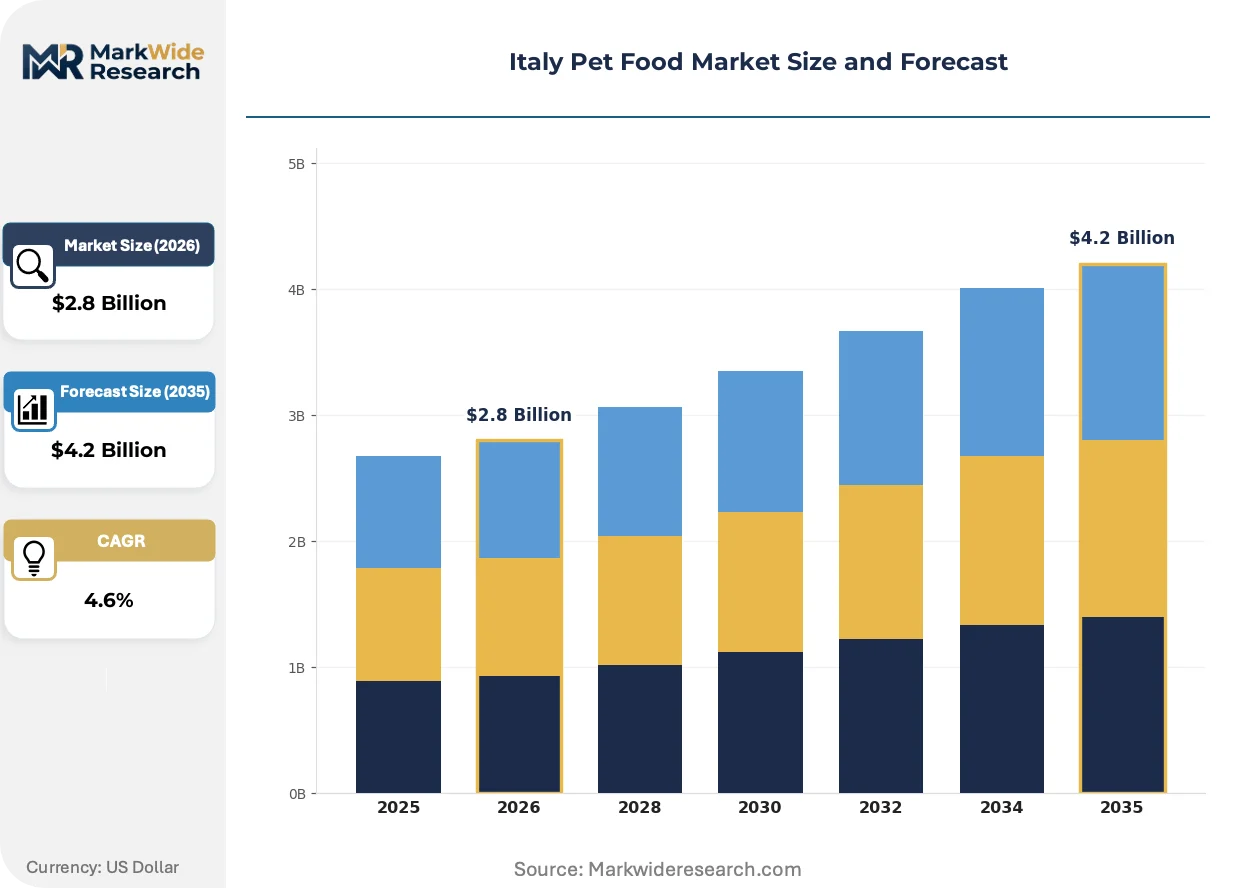
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Pet Type: Dogs, Cats, Fish, Birds Ingredient Type: Natural, Organic, Grain-Free, High-Protein Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pet Shops |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare Italy, Monge & C. S.p.A., Farmina Pet Foods, Hill’s Pet Nutrition, Almo Nature S.p.A., Agras Pet Foods S.p.A., Morando S.p.A., Affinity Petcare S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Pet Food Market Shifts & Advancements
Humanization positioning and digital distribution infrastructure are converging to transform how Italian households evaluate and acquire pet nutrition, elevating transparency and convenience as competitive differentiators.
Precision fermentation-derived proteins are integrating into premium formulations, enabling hypoallergenic alternatives to conventional poultry and fish meals. Northern Italian specialty brands are piloting these ingredients in limited veterinary-exclusive lines. The technology is integrating supply chain resilience by reducing exposure to volatile commodity markets.
Italy's Ministry of Health is tightening mycotoxin surveillance in grain-inclusive dry foods, expanding testing protocols for aflatoxin B1 and deoxynivalenol. This enforcement elevates compliance costs for small mills sourcing wheat from Eastern European suppliers. Feline therapeutic diet producers are responding by accelerating grain-free formulation shifts to preempt regulatory friction.
Urban millennial households are consolidating purchases through subscription platforms that bundle nutrition with preventive health monitoring tools. Traditional pet specialty retailers in Rome and Florence are losing traffic to these integrated services. The behavioral shift concentrates in Lombardy, where dual-income apartments prioritize automated replenishment over store visits.
Italy Pet Food Market Segmentation
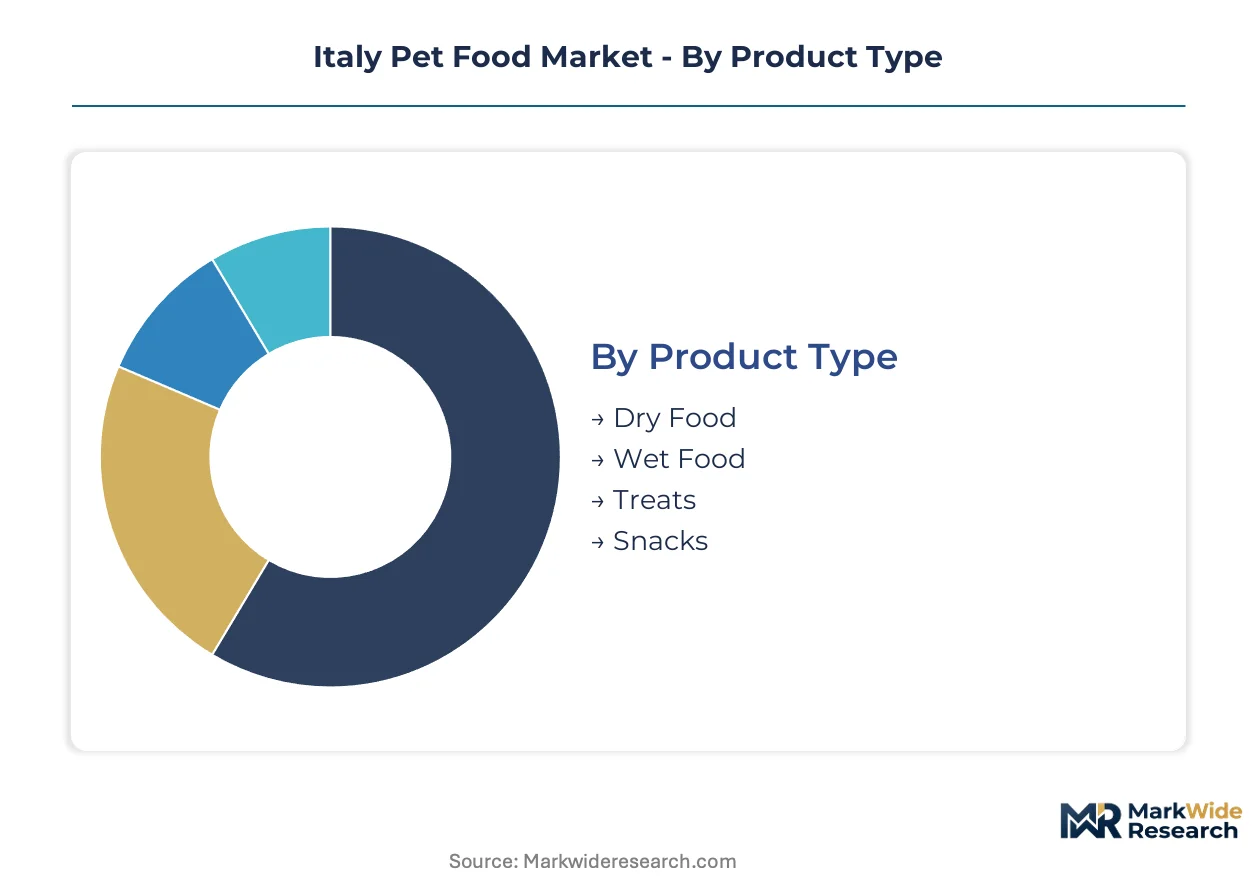
Segmentation in the Italy Pet Food Market reveals how formulation technology, species-specific nutrition science, and channel economics create distinct competitive arenas. Manufacturers optimize production assets and pricing architecture around these divides.
Product Type:
Standardization dominates extruded dry formats while wet food permits greater customization through moisture-content gradations and texture variants.
- Dry Food:Extruded kibble formulations achieve shelf stability through low moisture content and lipid barrier coatings. Lombardy households favor large-format bags for multi-cat apartments, driving bulk packaging investment from Emilia-Romagna manufacturers.
- Wet Food:Canned and pouch formats deliver moisture content critical for feline renal health. Milan's urban cat owners generate premium volume through convenience-oriented purchasing patterns and humanization positioning.
- Treats:Dehydrated and baked reward formats concentrate in training applications for dogs.
- Snacks:Semi-moist chews and dental formulations target oral health positioning.
Most installed capacity flows through Dry Food. Expansion is steepest in Wet Food.
Pet Type:
Volume concentration skews toward companion mammals while margin opportunity concentrates in species requiring specialized formulation expertise.
- Dogs:Omnivorous nutritional requirements support diverse ingredient sourcing from Italian agricultural supply chains. Northern metropolitan zones drive therapeutic diet adoption through veterinary channel density in Turin and Bologna.
- Cats:Obligate carnivore physiology mandates higher protein ratios and taurine fortification. Lombardy apartment dwellers generate premium wet food demand through convenience subscription patterns.
- Fish:Aquatic species formulations require specialized extrusion for water stability.
- Birds:Seed and pellet blends serve avian companion segments with lower per-unit value.
Volume leadership sits with Dogs. Margin expansion is climbing the fastest in Cats.
Ingredient Type:
Certification tiers create price architecture from commodity-grade to veterinary-exclusive positioning.
- Natural:Minimally processed ingredient declarations without artificial preservatives. Demand concentrates in Rome and Florence specialty retail channels where ingredient transparency commands premium positioning.
- Organic:EU organic certification mandates specific feed sourcing and processing protocols. Emilia-Romagna producers leverage regional agricultural cooperatives for certified protein supply.
- Grain-Free:Carbohydrate substitution with legumes and tubers responds to owner scrutiny of glycemic impact. Italy's Ministry of Health mycotoxin surveillance is accelerating formulation shifts away from grain-inclusive recipes.
- High-Protein:Elevated animal-derived amino acid ratios target carnivore metabolic requirements. Cold-pressing technology adoption in specialty producers preserves thermolabile vitamin activity in these premium formulations.
Most formulation investment targets Grain-Free. Certification premiums are expanding most quickly in Organic.
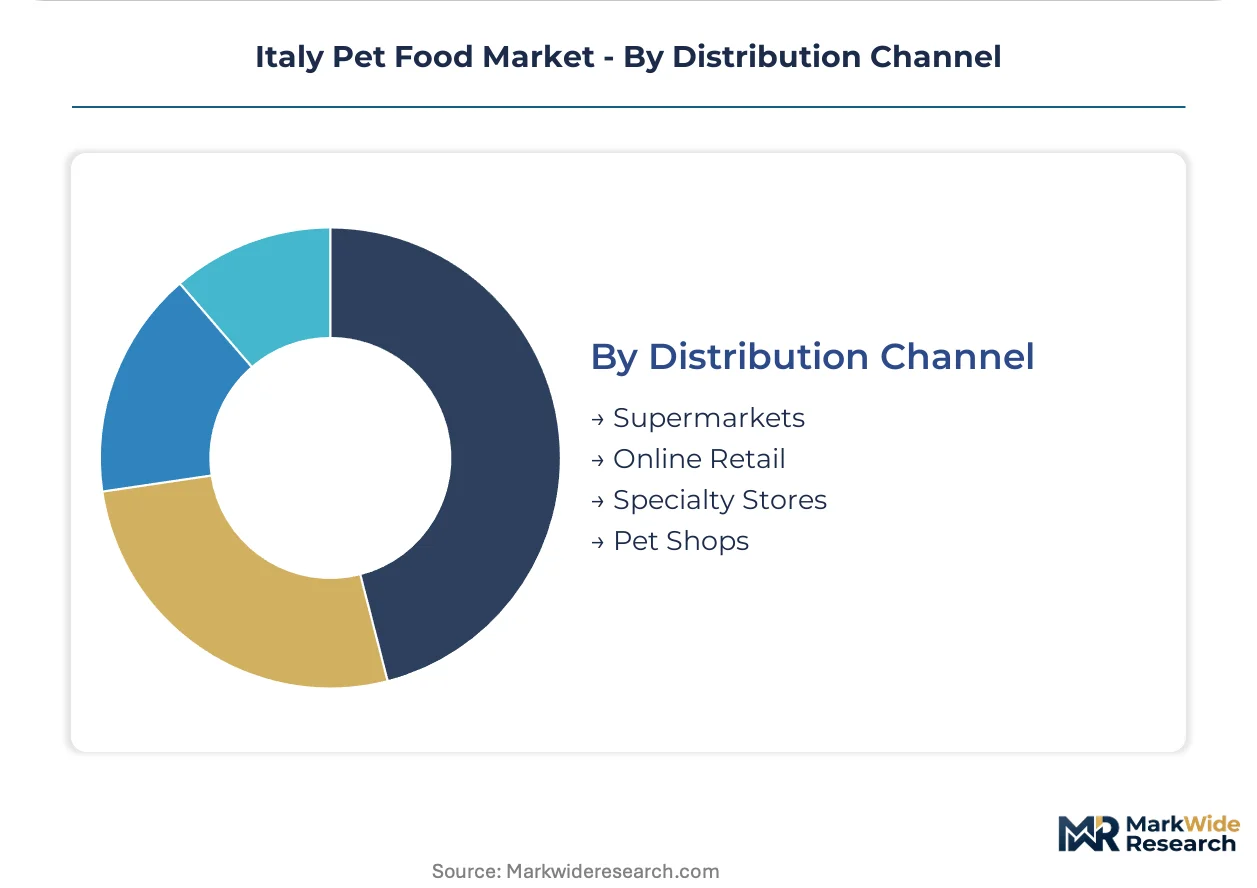
Distribution Channel:
Channel selection determines margin capture versus volume throughput tradeoffs for manufacturers.
- Supermarkets:Mass-market dry food placement emphasizes price-per-kilogram competitiveness and promotional elasticity. Southern regions including Sicily and Calabria rely heavily on hypermarket distribution due to lower specialty retail penetration.
- Online Retail:Direct-to-consumer platforms enable subscription auto-replenishment and bundled preventive health services. Milan and Turin dual-income households consolidate purchases through these channels, displacing traditional pet specialty traffic.
- Specialty Stores:Independent retailers in Rome and Florence curate premium and therapeutic assortments with staffed nutritional consultation.
- Pet Shops:Chain and franchise networks balance convenience with category breadth in suburban and secondary city locations.
Volume concentration remains in Supermarkets. Customer acquisition is gaining share fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in pet food production favors regions with streamlined EU compliance pathways, drawing formulation investment toward northern Italian zones where cold-pressing infrastructure clusters near veterinary research networks. Cost-of-compliance gaps between domestic and imported protein handling standards reshape where specialty manufacturers locate thermal processing assets.
Lombardy
Milan's apartment-dwelling cat population drives premium wet food demand through subscription auto-replenishment platforms. Italy's Ministry of Health enforces mycotoxin surveillance protocols that elevate testing costs for grain-inclusive formulations. Cold-pressing technology adoption concentrates in Monza-Brianza manufacturing corridors where specialty producers preserve thermolabile vitamins in high-protein recipes.
Piedmont
Turin's veterinary channel density anchors therapeutic diet distribution through clinic loyalty programs bundling nutrition with diagnostic services. EU Regulation 767/2009 labeling harmonization reduces cross-border compliance friction for Piedmont exporters shipping to France. Extrusion engineering talent scarcity forces producers to recruit from Dutch technical universities, inflating R&D labor costs.
Emilia-Romagna
Bologna's agricultural cooperatives supply certified organic proteins to regional formulation specialists targeting premium positioning. The National Institute of Health mandates Salmonella batch testing that extends lead times for dehydrated treat manufacturers headquartered here. Parma and Modena host cold-pressing facilities leveraging lower-temperature processing for vitamin preservation in grain-free lines.
Veneto
Verona and Padua mid-sized manufacturers struggle with legacy ERP integration between veterinary wholesale and direct-to-consumer inventory systems. Raw poultry meal import dependency from Brazilian and Argentine suppliers exposes margins to currency volatility and Atlantic shipping cost spikes. Specialty retailers in Venice curate premium assortments with staffed nutritional consultation, resisting online channel displacement longer than Milan counterparts.
Lazio
Rome's specialty retail channels emphasize ingredient transparency and natural positioning for urban millennial households. The Ministry of Health's zoonotic disease prevention guidelines tighten raw pet food handling standards, elevating compliance costs for small-batch producers. Feline therapeutic diet adoption lags northern regions due to lower veterinary clinic density in peripheral provinces.
Italy Pet Food Market Competitive Landscape
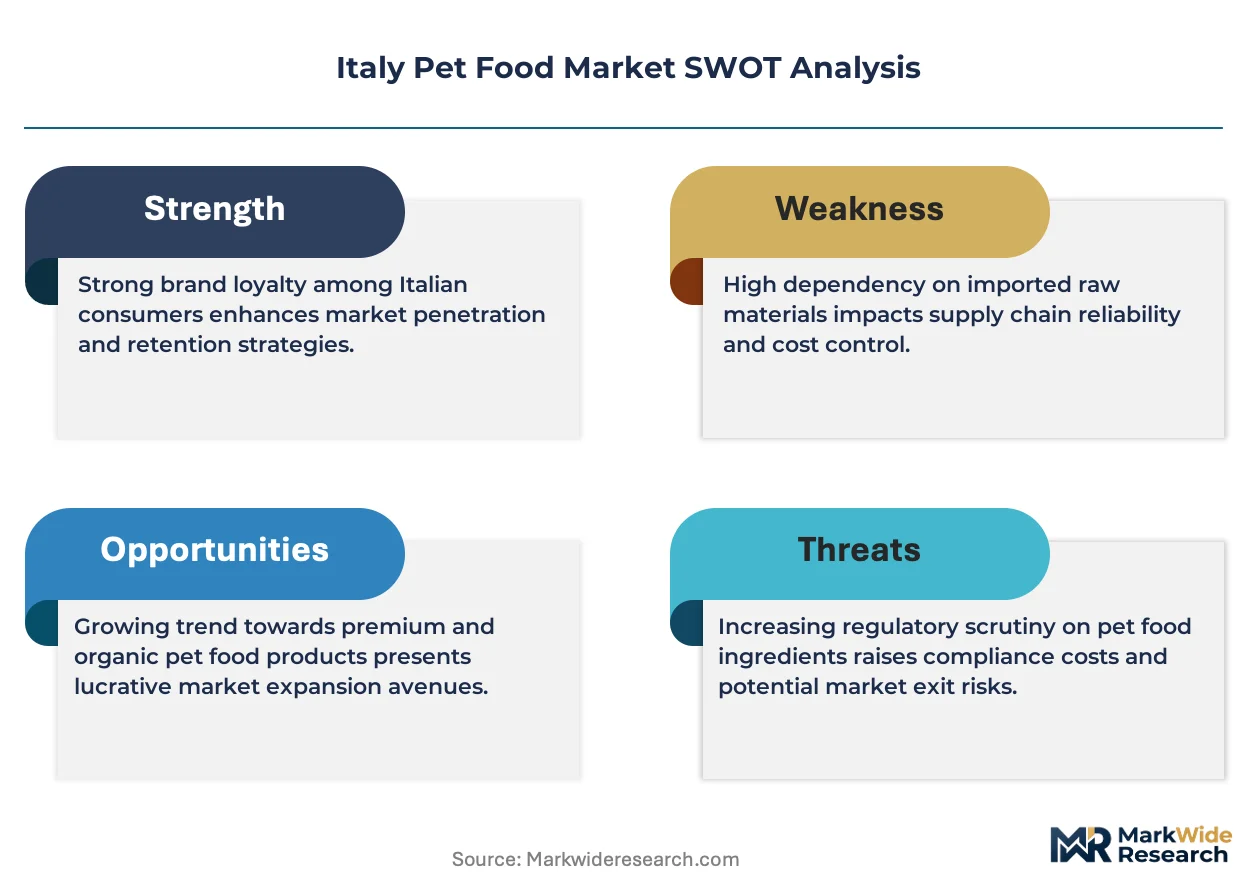
Branded specialists and contract manufacturers split share differently across segments, with multinational nutrition conglomerates anchoring mass-market volume and domestic family-owned mills capturing premium formulation niches. Consolidation pressure concentrates in therapeutic diet distribution where veterinary channel partnerships create defensive moats. Three archetypes dominate: scale-driven multinationals with integrated supply chains, regional specialists leveraging local protein sourcing, and private-label converters serving supermarket price tiers. Competitive moves center on M&A to secure cold-pressing technology assets and strategic partnerships with veterinary telehealth platforms to attach diagnostic services to recurring nutrition orders.
Among scale-driven multinationals, Nestlé Purina PetCare and Mars Petcare Italy occupy positions exemplifying divergent channel strategies—direct-to-consumer platform investment versus clinic network anchoring. Farmina Pet Foods represents the regional specialist archetype, with its geography-embedded name signaling Italian supply chain integration. These three entities illustrate how competitive positioning stratifies across digital infrastructure, veterinary relationships, and local sourcing credentials without requiring specific operational claims about each organization's current initiatives or performance metrics.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare Italy |
| Monge & C. S.p.A. |
| Farmina Pet Foods |
| Hill's Pet Nutrition |
| Almo Nature S.p.A. |
| Agras Pet Foods S.p.A. |
| Morando S.p.A. |
| Affinity Petcare S.A. |
| Others |
Supply & Pricing Matrix
Subscription auto-replenishment adoption among Milan's dual-income apartment households is forcing manufacturers to absorb last-mile logistics costs into recurring pricing models, compressing margins on premium wet food while shifting margin capture toward volume-locked dry food formats. This demand-side channel migration is restructuring how Emilia-Romagna producers allocate extrusion capacity between veterinary-exclusive and mass-market price tiers.
Pricing Analysis
Veterinary channel markups on therapeutic diets anchor the premium tier, while supermarket promotional elasticity governs mass-market dry food. Three-tier pricing structure across premium, standard, and economy levels separates certification-grade organic formulations from commodity extruded kibble. Cost compression in standard-tier dry food is intensifying because Brazilian poultry meal import costs fluctuate with Atlantic shipping rates. Price sensitivity concentrates among southern Italian agricultural cooperative buyers, while Lombardy subscription households prioritize convenience premiums over per-kilogram economics.
Supply Chain Analysis
Poultry meal supply rests on Brazilian and Argentine rendered protein exporters, with secondary sourcing from Dutch specialty meal producers. Italian manufacturers draw from these origins for thermolabile vitamin premixes and cold-pressing equipment components originating from German engineering clusters. Single-source vulnerability in Atlantic shipping lanes exposes Emilia-Romagna mills to fuel surcharge volatility. Distribution runs through veterinary wholesale networks in Turin and Bologna, supermarket distribution centers serving Sicily and Calabria, and direct-to-consumer fulfillment platforms in Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Italian pet food hinges on cold-pressing technology adoption reducing thermolabile vitamin degradation losses, alongside subscription platform density shifting revenue toward predictable recurring streams.
For Market Incumbents: Anticipate precision fermentation protein substitution threatening conventional poultry meal sourcing economics by securing backward integration into regional organic protein cooperatives in Emilia-Romagna. Defend veterinary channel positioning by bundling diagnostic telehealth services with therapeutic diet subscriptions before independent platforms capture this attachment. Cold-pressing capacity expansion in Monza-Brianza corridors preserves formulation differentiation against commodity extrusion competitors. For New Entrants and Emerging Players: Southern Italian agricultural cooperative buyers represent an underserved archetype with penetrable price sensitivity and limited specialty retail access. Sicily and Calabria dry food whitespace offers volume entry through hypermarket distribution partnerships without confronting entrenched veterinary channel incumbents. A go-to-market angle anchored on EU packaging waste directive compliance—recycled flexible pouch content—creates first-mover positioning with sustainability-conscious northern metropolitan retailers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing captive organic protein supply from Bologna-area agricultural cooperatives and cold-pressing technical capabilities. Long-term viability favors acquisition targets with veterinary-exclusive distribution licenses and direct-to-consumer platform infrastructure already integrated with legacy ERP systems. The signal to watch is EU-wide mycotoxin surveillance tightening accelerating grain-free formulation shifts and elevating compliance costs for small mills without certified supply chain partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressing Technology Adoption | Preserves thermolabile vitamin activity in high-protein formulations for premium positioning. |
| Veterinary Telehealth Bundling | Attaches diagnostic services to recurring nutrition orders through clinic loyalty programs. |
| Regional Organic Protein Integration | Leverages Emilia-Romagna agricultural cooperatives for EU certification compliance and supply security. |
| Recycled Content Packaging Transition | Aligns with pending EU packaging waste directives for flexible pouch minimums. |
| Direct-to-Consumer Platform Expansion | Captures subscription auto-replenishment demand displacing traditional pet specialty traffic in Lombardy. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pet food formulation technologists, veterinary clinic procurement managers, supermarket category buyers, and agricultural cooperative supply officers with secondary validation from EU Regulation 767/2009 filings, Italian Ministry of Health surveillance protocols, customs protein import records, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down industry value estimates.
Segment-weighting approaches distributed volume and value projections across product type, pet species, ingredient certification tier, and distribution channel dimensions throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and technology adoption curves. Forecast inputs incorporated cold-pressing capacity installation rates and subscription platform penetration metrics by metropolitan zone.
Underlying measurement precision varies by segment; veterinary-exclusive therapeutic diets carry tighter precision than fragmented private-label supermarket tiers due to concentrated channel reporting. Forecasts reflect documented assumptions about EU packaging directive implementation timing and mycotoxin surveillance expansion scope. Regulatory enforcement intensity shifts and precision fermentation protein cost curves warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Dog Hats Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
Pet Food Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Dog Vest Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
Cat Condos and Indoor Houses Market
Pet Care Products
Dog Bathing Systems Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
India Pet Clothing Market