
 Pet Oral Care Market | 2026-2036
Pet Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Oral Care Market Outlook
European manufacturing of enzymatic pet toothpaste is shifting toward pharmaceutical-grade production facilities. Virbac leverages its veterinary pharmaceutical heritage to dominate prescription-grade dental formulations. Mars Incorporated anchors mass-market chew segments through intensive R&D on mechanical cleaning efficacy. Colgate-Palmolive Company competes by extending human oral care brand equity into pet-specific retail channels.
Pet oral care encompasses prophylactic and therapeutic products designed to reduce plaque accumulation, control gingivitis, and manage periodontal disease in companion animals, typically incorporating chlorhexidine, zinc ascorbate, or proprietary enzyme systems at concentrations safe for ingestion. Toothpaste and dental chews currently occupy the largest revenue pools due to established daily-use routines and premium pricing on veterinary-recommended formulations. Online retail represents the fastest-expanding distribution channel as subscription models and telehealth integration reshape how owners procure preventive dental supplies.
FDA Center for Veterinary Medicine oversees ingredient safety and labeling claims for dental health products distributed in the United States, while the EU's EMA and national regulators enforce the Veterinary Medicines Regulation on products crossing into therapeutic claims. These frameworks compel manufacturers to distinguish cosmetic cleaning claims from regulated drug indications, directly influencing formulation strategy and market access pathways. Stakeholders must monitor evolving telehealth regulations that could expand remote dental prescribing authority beyond traditional clinic boundaries.
Market Dynamics
Telehealth integration with veterinary dental prescribing is collapsing traditional clinic-centric distribution, forcing manufacturers to rebuild go-to-market architectures around remote consultation platforms and direct-to-consumer subscription fulfillment.
Growth Catalysts
- FDA Center for Veterinary Medicine clearance pathways:Streamlined approval for enzymatic formulations with drug-device combination claims accelerates premium product launches in the United States.
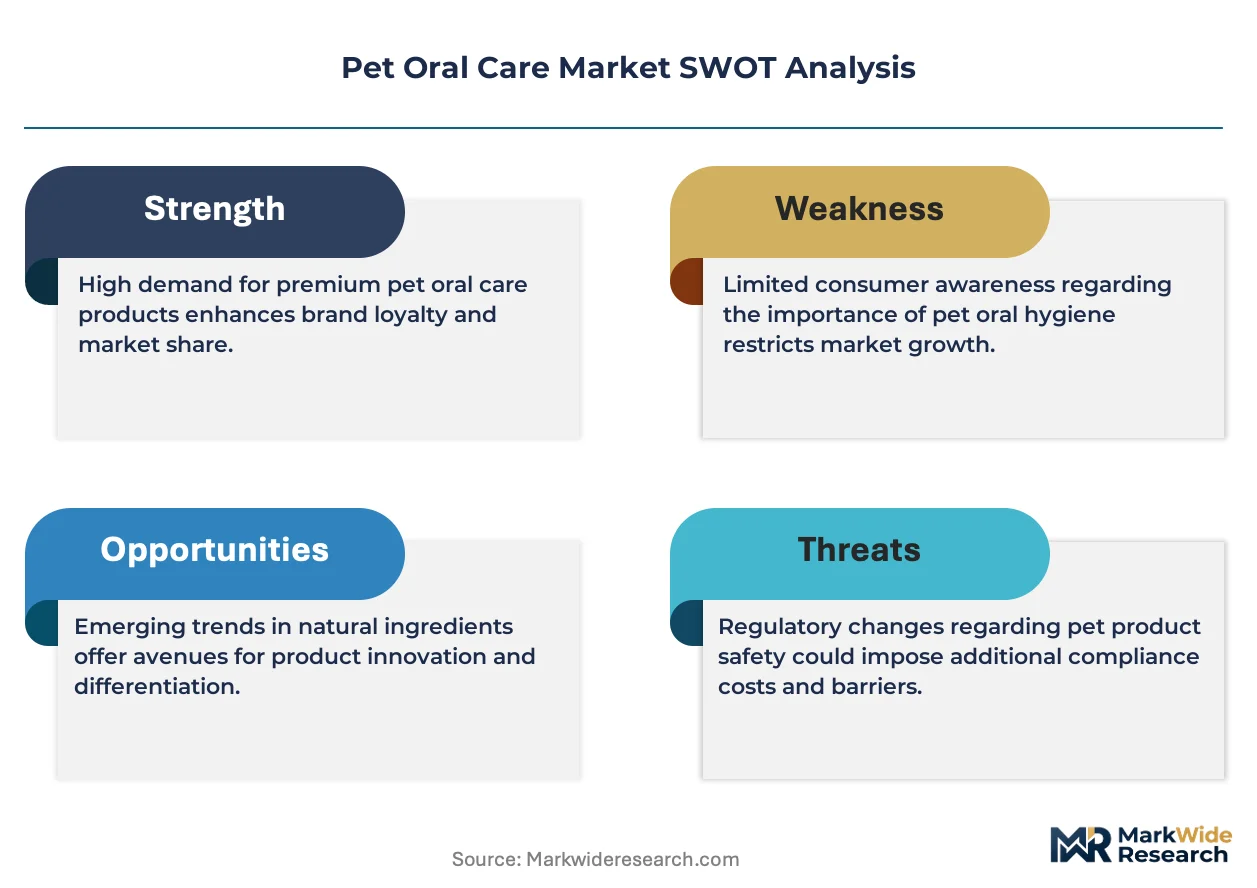
- Pet insurance reimbursement expansion:Dental procedure coverage under companion animal policies in OECD nations reduces out-of-pocket cost barriers for prophylactic cleanings and periodontal treatments.
- EU Green Deal animal welfare provisions:Mandatory wellness plan bundling in Germany and France creates institutional demand pull through veterinary clinic networks.
Market Restraints
- Pharmaceutical-grade manufacturing capex:Conversion of cosmetic-grade toothpaste facilities to GMP-compliant enzymatic production requires seven-figure capital commitments per facility.
- Ingredient supply concentration:Chlorhexidine and zinc ascorbate active pharmaceutical ingredients source predominantly from Chinese chemical manufacturers, creating single-geography dependency risk.
- Therapeutic-cosmetic claim boundary:FDA and EMA enforcement actions against products crossing into unapproved drug indications force costly reformulation and label revision cycles.
Strategic Opportunities
- Subscription commerce integration:Automated replenishment models tied to telehealth dental monitoring platforms capture recurring revenue streams outside traditional retail markups.
- Underpenetrated feline oral care:Dog-centric product development leaves cat periodontal disease management underserved, with feline-specific formulations commanding veterinary channel premiums.
- EMA Veterinary Medicines Regulation harmonization:Centralized EU market authorization reduces national regulatory fragmentation, enabling scale economies for prescription-grade dental therapeutics.
Industry Challenges
- Veterinary dental specialist scarcity:Board-certified veterinary dentists represent less than one percent of practicing veterinarians, creating diagnostic bottleneck for advanced periodontal staging and treatment planning.
- Telehealth prescribing authority ambiguity:State-level veterinary medical board regulations in the United States create a patchwork of remote prescription legality, complicating national distribution strategies for prescription dental formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Oral Care Market |
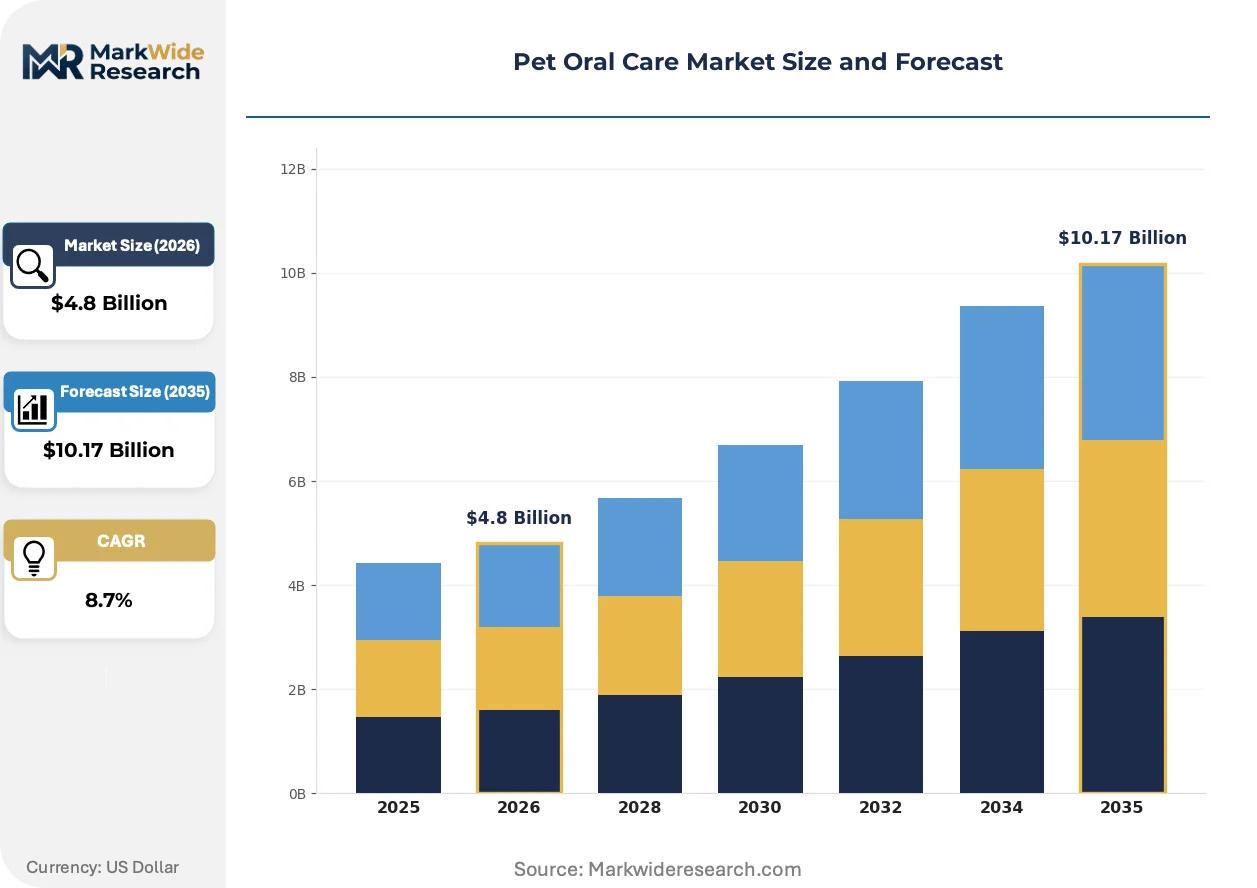
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Chews, Dental Water Additives, Rinses Form: Gel, Liquid, Powder, Foam Animal Type: Dogs, Cats, Rabbits, Ferrets Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Veterinary Clinics |
| Companies Covered | Virbac, Central Garden & Pet Company, Mars Incorporated, Hill’s Pet Nutrition Inc., Dechra Pharmaceuticals plc, Nestlé Purina PetCare Company, Vetoquinol SA, Ceva Santé Animale, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Oral Care Market Strategic Shifts
Digital health infrastructure is penetrating veterinary dentistry through connected monitoring devices and AI-assisted plaque assessment, rewiring how owners perceive preventive care value and where they purchase intervention products.
Probiotic oral microbiome modulation is converging with traditional enzymatic cleaning systems in next-generation formulations. Early-adopter veterinary clinics in the United States and United Kingdom are piloting these dual-mechanism products for refractory periodontal cases. This convergence is compressing the differentiation window between cosmetic and therapeutic product categories, forcing regulatory clarity investments.
The EU's Veterinary Medicines Regulation implementation is tightening border controls on dental products with antimicrobial claims. Manufacturers must now submit centralized marketing authorization applications for chlorhexidine-based therapeutics previously sold under national derogations. Small and mid-sized suppliers lacking EMA regulatory affairs capacity are exiting the prescription channel, consolidating formulation expertise among pharmaceutical heritage players.
Subscription-based procurement of preventive dental supplies is displacing episodic retail purchasing among millennial and Gen Z pet owners. Chewy and Amazon Pet are capturing recurring revenue through auto-ship programs bundled with telehealth dental consultations. This channel shift concentrates most visibly in United States metropolitan markets where veterinary deserts and convenience priorities intersect.
Pet Oral Care Market Segmentation
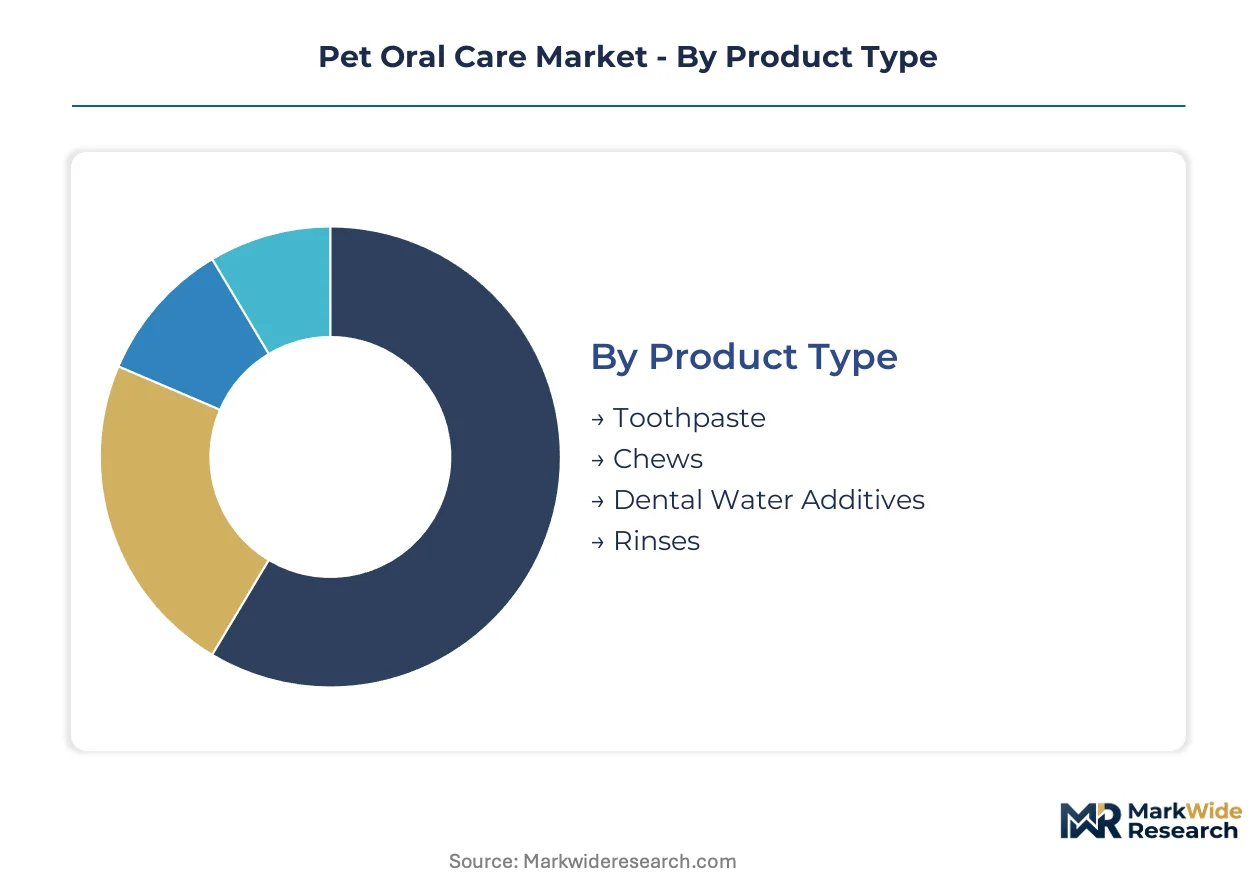
Product differentiation in pet oral care tracks closely to owner compliance patterns and veterinary channel influence. Formulation complexity, species-specific palatability engineering, and distribution economics create distinct competitive arenas within each segmentation dimension.
Product Type:
Toothpaste and chews split the market between daily preventive routines and intermittent mechanical cleaning, with premium pricing concentrated in enzymatic formulations carrying veterinary endorsement.
- Toothpaste:Enzymatic formulations incorporating glucose oxidase and lactoperoxidase systems dominate prescription channels, with chlorhexidine variants restricted to veterinary dispensing in the United States under FDA Center for Veterinary Medicine oversight. Demand clusters in metropolitan markets where pet insurance reimbursement for dental prophylaxis reduces owner price sensitivity.
- Chews:Mechanical cleaning efficacy depends on texture engineering and residence time in the oral cavity; Mars Incorporated and other mass-market manufacturers optimize for palatability retention to extend chewing duration. Revenue concentrates in big-box retail and subscription auto-ship programs.
- Dental Water Additives:Zinc ascorbate and chlorhexidine solutions target compliance-resistant pets, with palatability masking agents determining repurchase rates in online retail channels.
- Rinses:Chlorhexidine-based antiseptic formulations serve post-procedural home care protocols prescribed by veterinary dentists, with limited retail penetration due to taste aversion issues.
Mature deployment sits with toothpaste. Newer deployment is concentrated in dental water additives as millennial owners prioritize convenience over mechanical brushing compliance.
Form:
Physical presentation determines application method compatibility and shelf stability requirements, with gel and liquid formats commanding formulation expertise premiums.
- Gel:High-viscosity enzymatic gels enable finger-application protocols for non-compliant pets, with Virbac's CET product line establishing veterinary channel benchmarks for adhesion and residence time.
- Liquid:Water additive and rinse formulations require solubility engineering for active ingredient stability; pH buffering systems determine compatibility with metal water bowls and fountain dispensers.
- Powder:Probiotic and enzyme blends target raw-feeding pet owners, with cold-processing requirements limiting supplier base to specialty manufacturers.
- Foam:Aerosolized delivery systems for professional dental cleaning preludes, with compressed gas propellant regulations constraining formulation options in the European Union under REACH.
Volume leadership belongs to liquid formats. Steepest expansion trajectory is occurring in gel applications as telehealth dental consultations drive finger-brushing protocol adoption.
Animal Type:
Species-specific anatomy and disease prevalence reshape product development priorities, with feline periodontal disease historically underserved relative to clinical incidence rates.
- Dogs:Larger oral cavity dimensions and cooperative behavior enable chew-based mechanical cleaning at scale; breed-specific size variants create SKU proliferation challenges for mass-market manufacturers.
- Cats:Smaller mouth geometry and finicky palatability responses demand specialized formulation concentration and flavor masking; veterinary channel premiums exceed dog-equivalent products due to manufacturing complexity and lower volume scale.
- Rabbits:Herbivore dental anatomy with continuously growing incisors and molars creates distinct prophylactic needs; product availability concentrates in exotic veterinary practices and specialty online retailers.
- Ferrets:Obligate carnivore dentition and susceptibility to periodontal disease drive demand in North American and European markets with established exotic pet ownership cultures.
Commercial maturity centers on dogs. Emerging deployment is concentrated in cats as EMA Veterinary Medicines Regulation harmonization enables scaled prescription therapeutic launches.
Distribution Channel:
Channel selection determines margin structure and customer relationship depth, with veterinary clinics capturing premium pricing through professional authority and insurance reimbursement integration.
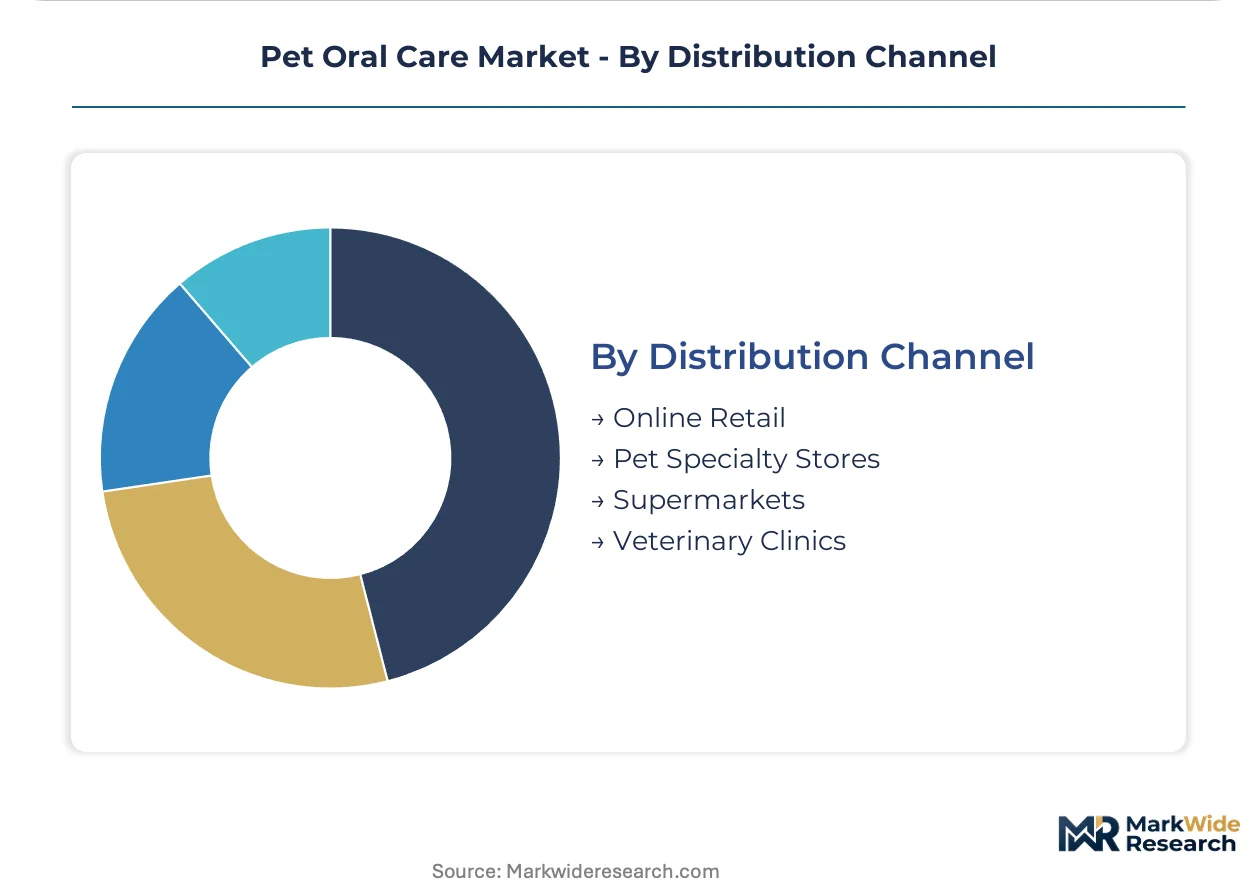
- Online Retail:Subscription auto-ship models tied to telehealth dental monitoring platforms are gaining share fastest in United States metropolitan markets; Chewy and Amazon Pet dominate recurring revenue capture.
- Pet Specialty Stores:Staff consultation and product demonstration drive trial conversion for mechanical cleaning devices; independent retailers compete through veterinary referral relationships.
- Supermarkets:Mass-market chew and basic toothpaste segments concentrate here, with price competition and promotional intensity compressing manufacturer margins.
- Veterinary Clinics:Prescription-grade enzymatic formulations and professional cleaning preludes generate highest per-unit revenue; wellness plan bundling in Germany and France under EU Green Deal provisions is institutionalizing demand pull.
Established volume flows through veterinary clinics. Channel momentum is shifting toward online retail as telehealth integration collapses traditional clinic-centric procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorhexidine and zinc ascorbate supply chains originating in Chinese chemical manufacturing districts feed formulation facilities across three continents. Demand localization varies sharply by veterinary infrastructure maturity and insurance reimbursement frameworks.
United States
Pet insurance reimbursement for dental procedures expands fastest among OECD nations, reducing owner cost barriers for prophylactic cleanings. FDA Center for Veterinary Medicine oversees ingredient safety and therapeutic-cosmetic claim boundaries. Metropolitan veterinary deserts in Texas and Arizona accelerate telehealth dental prescribing adoption.
Germany
Veterinary clinics bundle dental cleanings with wellness plans under EU Green Deal animal welfare provisions. EMA Veterinary Medicines Regulation enforcement tightens border controls on antimicrobial dental claims. Manufacturing clusters in North Rhine-Westphalia convert cosmetic-grade facilities to pharmaceutical-grade enzymatic production.
France
Mandatory wellness plan bundling mirrors German institutional demand patterns through veterinary clinic networks. ANSM enforces national derogation phase-outs for chlorhexidine-based therapeutics. Lyon and Paris veterinary pharmaceutical corridors consolidate formulation expertise among heritage players.
United Kingdom
Telehealth dental consultations drive finger-brushing protocol adoption among millennial pet owners. Veterinary Medicines Directorate aligns with EMA harmonization timelines for prescription-grade therapeutics. London and Southeast England pilot AI-assisted plaque assessment in specialty practices.
Japan
Aging pet demographics elevate periodontal disease management priority among small animal practitioners. PMDA regulates enzymatic formulations crossing into therapeutic indications. Osaka-Kobe pharmaceutical manufacturing zone supplies East Asian markets with GMP-compliant dental additives.
Pet Oral Care Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue microbiome modulation and connected monitoring device integration. Market structure consolidates around pharmaceutical heritage manufacturers with veterinary channel relationships and mass-market consumer goods conglomerates with retail scale. Three archetypes dominate: prescription-grade enzymatic formulators, mechanical cleaning efficacy optimizers, and telehealth-integrated subscription platforms. Competitive intensity concentrates on M&A absorption of specialty manufacturers and strategic partnerships with remote consultation providers.
Within the pharmaceutical heritage tier, Virbac leverages its veterinary pharmaceutical legacy to anchor prescription-grade dental formulation expertise. Mars Incorporated and Colgate-Palmolive Company occupy mass-market positions, with the former optimizing chew-based mechanical cleaning and the latter extending human oral care brand equity into pet-specific retail channels. These three entities exemplify the divergence between clinical authority and consumer scale that structures competitive positioning.
| Leading Market Players |
|---|
| Virbac |
| Central Garden & Pet Company |
| Mars Incorporated |
| Hill's Pet Nutrition Inc. |
| Dechra Pharmaceuticals plc |
| Nestlé Purina PetCare Company |
| Vetoquinol SA |
| Ceva Santé Animale |
| Colgate-Palmolive Company |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal animal welfare provisions gate qualified supply and premium-tier pricing access, mandating pharmaceutical-grade manufacturing upgrades that exclude cosmetic-grade producers from veterinary reimbursement channels. Manufacturers bearing GMP conversion costs capture pricing power through wellness plan bundling in Germany and France, while uncertified suppliers retreat to unregulated retail tiers.
Pricing Analysis
Service-bundling with telehealth dental consultations separates premium enzymatic formulations from unbundled retail equivalents, with subscription auto-ship models commanding recurring revenue premiums. Price differentiation hinges on FDA Center for Veterinary Medicine clearance status and veterinary channel endorsement, with prescription-grade chlorhexidine variants priced above cosmetic cleaning claims. Cost compression in mass-market chew segments is intensifying because Mars Incorporated and Colgate-Palmolive Company optimize manufacturing scale against palatability engineering investments. Millennial pet owners in United States metropolitan markets exhibit lowest price sensitivity where pet insurance reimbursement reduces out-of-pocket exposure.
Supply Chain Analysis
Freight cost volatility from Chinese chemical manufacturing districts to North American and European formulation facilities is reshaping inventory positioning strategies for chlorhexidine and zinc ascorbate inputs. Active pharmaceutical ingredient supply concentrates in China, with secondary sourcing from Indian specialty chemical manufacturers and limited European capacity in North Rhine-Westphalia. Raw material dependencies include glucose oxidase enzyme systems, chlorhexidine base compounds, and palatability masking agents. Single-geography concentration creates tariff exposure vulnerability as REACH compliance costs escalate for cross-border antimicrobial shipments. Distribution runs through veterinary clinic networks for prescription tiers and subscription platforms for preventive maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade manufacturing capacity scarcity props premium-tier pricing, with GMP facility conversion timelines creating 18-24 month supply bottlenecks for enzymatic formulation entrants. This constraint institutionalizes incumbent pricing power while excluding commodity-grade competitors from reimbursement-integrated channels.
For Market Incumbents: Deploy telehealth platform partnerships to lock in subscription recurring revenue before emerging entrants replicate veterinary channel integration. Acquire specialty microbiome modulation manufacturers to preempt probiotic-enzyme convergence threats. Secure backward integration into chlorhexidine active pharmaceutical ingredient sourcing to mitigate Chinese supply concentration risk. For New Entrants and Emerging Players: Capture feline-specific formulation white space where veterinary channel premiums exceed dog-equivalent products due to manufacturing complexity and historically underserved clinical incidence. Target United Kingdom and United States metropolitan markets where AI-assisted plaque assessment pilots create protocol disruption openings. Pursue direct-to-consumer subscription positioning with telehealth dental monitoring bundling to bypass clinic-centric distribution barriers. For Investors and Strategic Acquirers: EMA centralized marketing authorization approvals for chlorhexidine-based therapeutics is the leading indicator that prescription-channel consolidation will accelerate among pharmaceutical heritage players. Position for 5-10 year holding periods centered on veterinary pharmaceutical manufacturers with regulatory affairs capacity and enzymatic formulation expertise. Monitor telehealth prescribing authority clarifications in United States state-level veterinary medical boards as signal for direct-to-consumer platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Chewy and Amazon Pet subscription models collapse traditional clinic-centric procurement patterns in metropolitan veterinary deserts. |
| GMP Manufacturing Conversion | North Rhine-Westphalia facilities upgrading to pharmaceutical-grade production capture EU Green Deal wellness plan bundling demand. |
| Feline-Specific Formulation Launch | Virbac's veterinary channel relationships provide template for premium-priced cat periodontal disease management products. |
| Probiotic Microbiome Acquisition | Dual-mechanism enzymatic-probiotic convergence compresses differentiation window between cosmetic and therapeutic categories. |
| Active Pharmaceutical Ingredient Backward Integration | Chinese chlorhexidine supply concentration creates vulnerability for formulation-dependent manufacturers without captive sourcing. |
Study Parameters
Multi-period observation of pet insurance reimbursement expansion rates, telehealth prescribing adoption curves, and enzymatic formulation regulatory clearance timelines anchored the trend analysis, supplemented by interviews with veterinary pharmaceutical executives, regulatory affairs specialists at EMA and FDA, pet insurance product managers, and telehealth platform operators. Secondary validation drew from FDA Center for Veterinary Medicine filings, EMA centralized marketing authorization databases, EU Green Deal implementation progress reports, and pet insurance policy coverage disclosures. Bottom-up segmentation sizing triangulated against top-down market aggregation across product type, species, and distribution channel dimensions.
Input-output matrices modeled volume and value trajectories across toothpaste, chew, water additive, and rinse categories intersecting with dog, cat, rabbit, and ferret species segments throughout the forecast period. CAGRs derived from regression analysis of historical veterinary dental procedure reimbursement growth correlated with preventive product penetration rates. Industry-specific forecast inputs included EMA Veterinary Medicines Regulation harmonization implementation schedules and United States state-level telehealth prescribing authority evolution patterns.
The model holds under stable regulatory enforcement of therapeutic-cosmetic claim boundaries; deviation in FDA or EMA permissiveness toward microbiome modulation claims would shift competitive positioning toward probiotic-focused entrants. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Shampoo Market
Pet Care Products
Large Breed Dog Food Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Dog Vest Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
Asia-Pacific Pet Travel Services Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
Bird Toy Market
Pet Care Products
Europe Organic and Natural Pet Food Market
Pet Care Products
Pet Hotels Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Dog Collars Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Small Dog Harness Market