
 Reconciliation Software Market | 2026-2036
Reconciliation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Reconciliation Software Market Intelligence
Subscription-based delivery is recalibrating how reconciliation capabilities reach finance teams, shifting capital expenditure into predictable operating budgets. BlackLine leverages cloud-native architecture to anchor enterprise-grade close management across multinational clients. HighRadius competes through AI-powered cash application modules that extend into automated reconciliation workflows. Oracle NetSuite dominates mid-market penetration by embedding reconciliation within broader ERP suites.
Reconciliation software automates the matching of internal financial records against external statements, bank feeds, and subsidiary ledgers using rule engines, machine learning matching algorithms, and exception-handling protocols to eliminate manual spreadsheet-driven processes. Cloud-based deployment leads product-type segmentation due to lower infrastructure overhead and faster implementation cycles, while on-premises installations persist in jurisdictions with strict data residency laws. API integration levels are expanding fastest as enterprises demand real-time sync between ERP systems and banking platforms, whereas batch processing remains entrenched in legacy corporate finance environments where change management cycles run longer.
The SEC enforces accuracy requirements under Sarbanes-Oxley that compel publicly traded US firms to maintain auditable reconciliation trails, directly shaping software feature roadmaps around immutable logging and role-based access controls. EBA guidelines on internal governance and the EU Digital Operational Resilience Act impose operational continuity standards that European banking end users must satisfy through resilient reconciliation infrastructure. Stakeholders must weigh whether to consolidate around full-suite platforms or preserve best-of-breed architectures as regulatory fragmentation between jurisdictions intensifies compliance complexity.
Market Dynamics
Cloud migration mandates under the EU Digital Operational Resilience Act are compressing procurement cycles for automated reconciliation platforms, forcing banks to replace legacy batch systems with real-time API architectures.
Growth Catalysts
- SEC Enforcement:Sarbanes-Oxley accuracy requirements compel publicly traded US firms to maintain auditable reconciliation trails, driving demand for immutable logging capabilities.
- API-First Architectures:Real-time sync between ERP systems and banking platforms eliminates manual spreadsheet processes, accelerating financial close cycles for multinational enterprises.
- Banking Sector Consolidation:Merged institutions require unified reconciliation infrastructure to harmonize disparate legacy systems and subsidiary ledgers.
Market Restraints
- Data Residency Laws:Strict jurisdictional requirements in Germany, Switzerland, and Saudi Arabia block cloud migration, perpetuating on-premises installations with higher infrastructure overhead.
- Legacy System Entrenchment:Batch processing remains embedded in corporate finance environments where change management cycles extend 18-36 months.
- Integration Complexity:Fragmented ERP landscapes across acquired entities create matching algorithm failures that require expensive custom rule-engine development.
Strategic Opportunities
- AI-Powered Exception Handling:Machine learning matching algorithms reduce manual intervention rates in high-volume transaction environments like payment processors.
- Mid-Market ERP Embedding:Reconciliation modules integrated within broader cloud suites capture customers unwilling to procure standalone best-of-breed solutions.
- EU DORA Compliance Services:Operational continuity certification for European banking end users creates recurring revenue streams around resilience auditing.
Industry Challenges
- Specialized Talent Scarcity:Shortage of engineers proficient in both financial accounting rules and machine learning model training slows implementation timelines.
- Multi-Jurisdiction Certification:Divergent audit standards between the SEC, EBA, and Japan's FSA force vendors to maintain parallel compliance roadmaps.
- Legacy Protocol Migration:Converting decades-old COBOL-based reconciliation routines to cloud-native microservices architectures risks data integrity failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconciliation Software Market |
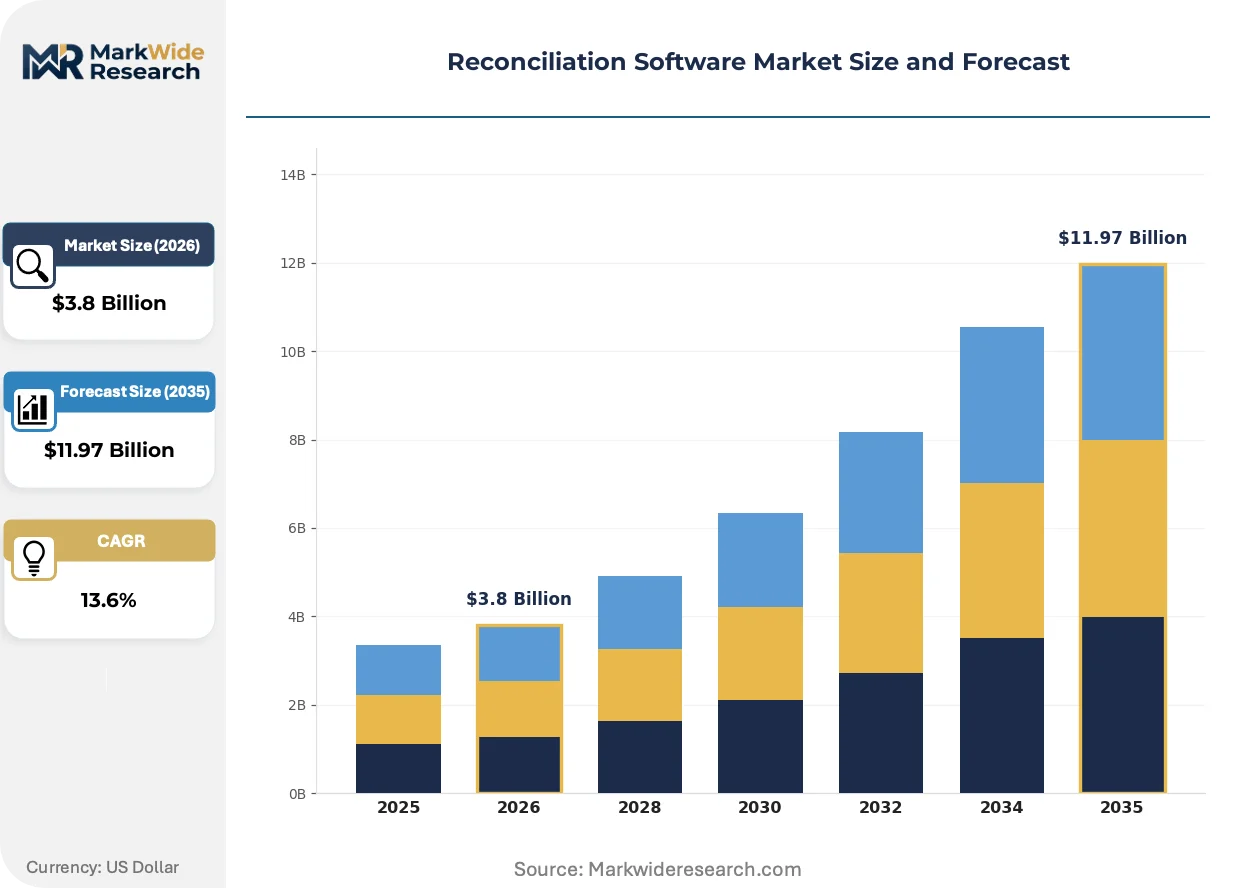
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premises, Hybrid, Mobile End User: Banking, Insurance, Retail, Corporate Finance Deployment Model: Public Cloud, Private Cloud, Community Cloud, SaaS Integration Level: API, Batch Processing, Manual Entry, Real-time Sync |
| Companies Covered | FloQast, Oracle NetSuite, Solvexia, HighRadius, Sage Intacct, BlackLine, OneStream, FIS Global, Trintech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconciliation Software Market Strategic Shifts & Innovations
Real-time data synchronization architectures are displacing overnight batch processing across treasury operations, compressing the financial close from weeks to hours.
API-native reconciliation platforms is overtaking file-based data exchange as the dominant integration method. Corporate treasurers at Fortune 500 manufacturers are mandating direct bank connectivity through open banking protocols. This shift is overtaking traditional SWIFT message formats and compressing vendor margins on custom integration services.
The EU Digital Operational Resilience Act imposes operational continuity standards that European banking end users must satisfy through resilient reconciliation infrastructure. Vendors must now certify uptime guarantees and disaster recovery protocols to maintain procurement eligibility. Tier-1 banks in Frankfurt and Paris are rewriting RFP criteria to prioritize DORA-compliant architecture over feature breadth.
Subscription-based delivery models are displacing perpetual license sales in enterprise procurement. Finance teams at mid-market SaaS companies prefer predictable operating budgets over capital expenditure approval cycles. This preference is most visible in the United States, where CFOs at technology firms negotiate three-year SaaS contracts with embedded reconciliation modules rather than standalone on-premises deployments.
Reconciliation Software Market Segmentation
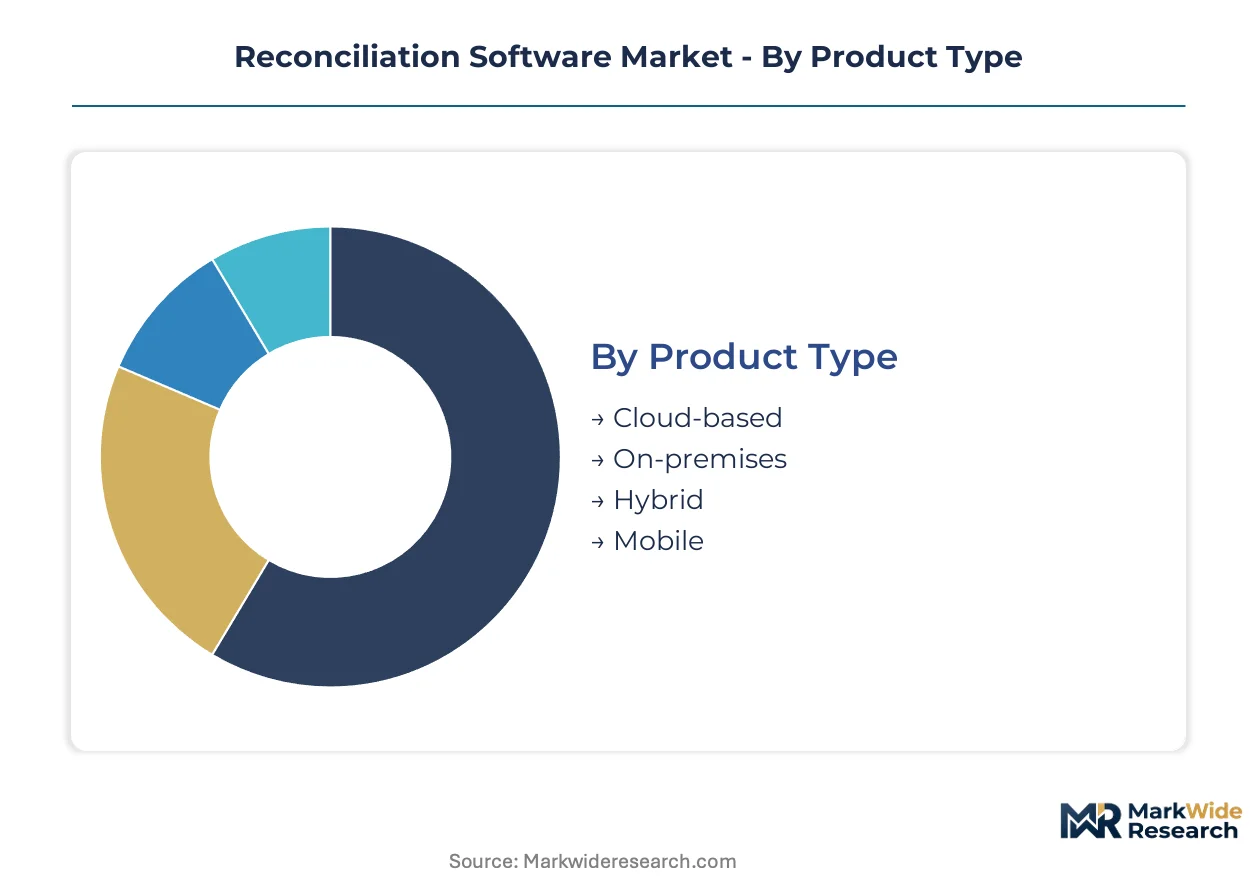
Segmentation in reconciliation software reveals how procurement decisions split between infrastructure constraints and functional requirements. Buyers prioritize deployment flexibility, regulatory jurisdiction, and integration velocity when selecting platforms.
Product Type:
Cloud-native architectures dominate procurement roadmaps as enterprises abandon capital-intensive infrastructure commitments.
- Cloud-based:Multi-tenant SaaS platforms eliminate server procurement cycles and compress implementation timelines from quarters to weeks. Banking institutions in the United States favor this model for SEC audit trail requirements, though data residency concerns in Germany and Switzerland limit penetration.
- On-premises:Licensed software running on client-controlled hardware persists where national regulators mandate physical data sovereignty. Saudi Arabian banks and Swiss private wealth managers maintain these installations despite higher total cost of ownership.
- Hybrid:Split architectures process sensitive reconciliation steps locally while pushing non-critical matching to cloud instances. Japanese megabanks deploy this pattern to satisfy FSA guidelines while capturing scalability benefits.
- Mobile:Native applications for exception approval and dashboard monitoring extend platform reach to field finance personnel. Retail treasury teams at multinational manufacturers use these for travel expense reconciliation on distributed supply chain audits.
Cloud-based solutions lead on scale; mobile applications lead on momentum.
End User:
Industry verticals impose distinct matching complexity and regulatory overlay requirements on platform selection.
- Banking:Transaction volumes exceeding millions per day demand machine learning matching algorithms and sub-second exception routing. EU DORA compliance mandates now dominate European procurement criteria, displacing feature-checklist evaluations.
- Insurance:Policy premium reconciliation against broker statements and reinsurance treaties requires specialized rule engines for multi-currency settlements. Lloyd's syndicates in London drive demand for immutable audit logging under Solvency II.
- Retail:High-frequency POS reconciliation across thousands of storefronts prioritizes API throughput over analytical depth. US-based omnichannel retailers integrate these platforms with Shopify and Amazon seller central feeds.
- Corporate Finance:Multi-entity close management for Fortune 500 manufacturers demands ERP-agnostic connectivity and role-based workflow orchestration. CFOs at technology firms negotiate three-year SaaS contracts with embedded modules.
Banking commands the largest addressable base; corporate finance shows the steepest expansion trajectory.
Deployment Model:
Infrastructure tenancy arrangements determine how reconciliation workloads share physical resources and security boundaries.
- Public Cloud:Shared infrastructure pools deliver lowest per-transaction economics for mid-market enterprises. AWS and Azure host the majority of new reconciliation platform deployments in North America.
- Private Cloud:Dedicated single-tenant environments satisfy audit requirements for institutions handling classified government payments. French defense contractors and US federal credit unions specify this model in RFPs.
- Community Cloud:Industry-specific cloud fabrics shared among non-competing peers reduce compliance duplication. European banking consortiums in Frankfurt and Amsterdam pilot these for collective DORA certification.
- SaaS:Fully managed software subscriptions abstract all infrastructure decisions from finance teams. Oracle NetSuite and BlackLine anchor their growth strategies on this delivery mechanism.
SaaS dominates new contract volume; private cloud retains pricing power in regulated segments.
Integration Level:
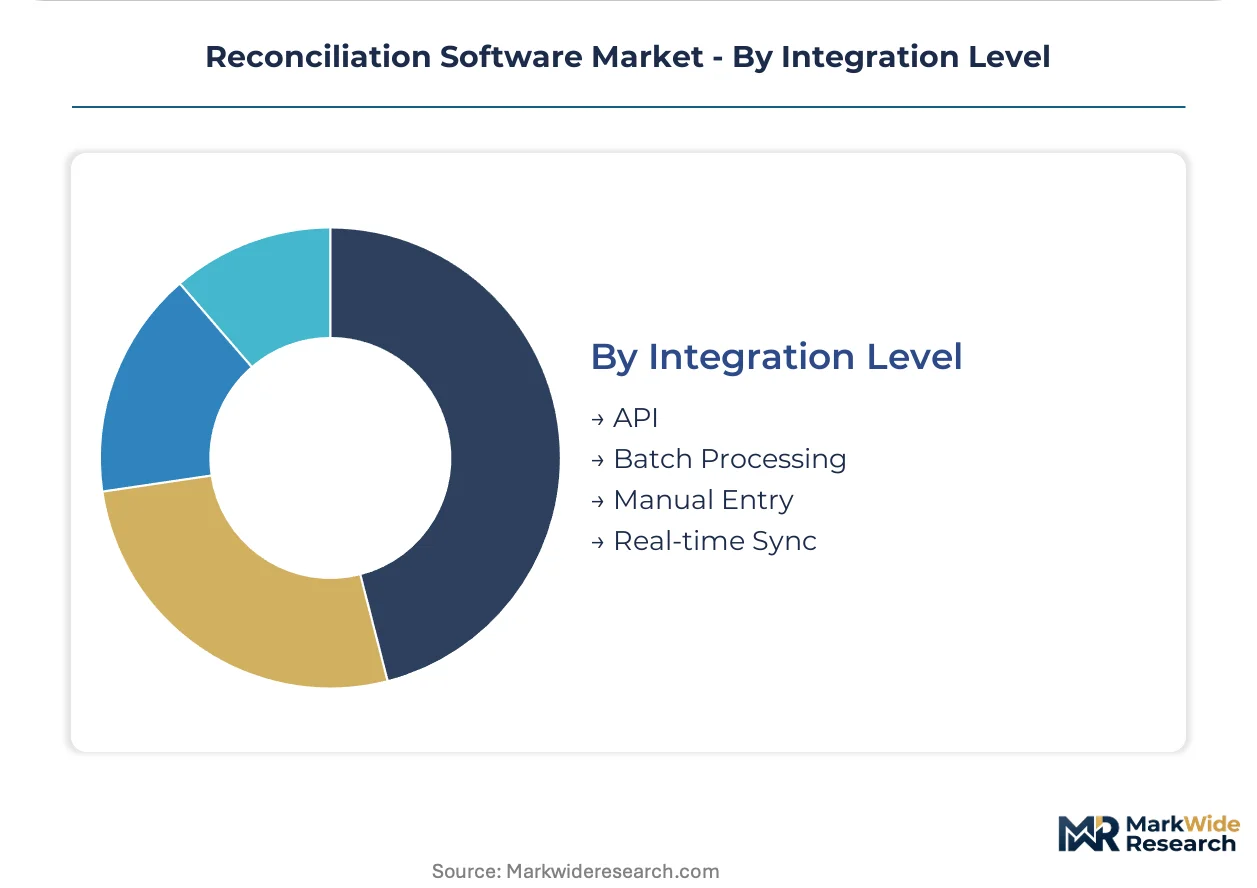
Data exchange protocols determine how quickly internal records synchronize with external statements and banking platforms.
- API:REST and GraphQL endpoints enable real-time balance verification and instant exception flagging. Open banking mandates in the United Kingdom and Brazil accelerate adoption among corporate treasurers.
- Batch Processing:Scheduled file transfers during overnight windows persist in legacy environments where change management cycles extend 18-36 months. Japanese regional banks and German mittelstand manufacturers maintain these patterns.
- Manual Entry:Spreadsheet upload interfaces and keyboard-driven reconciliation screens survive only in smallest enterprises and transitional migration phases. These incur error rates exceeding automated methods by orders of magnitude.
- Real-time Sync:Event-driven architectures push transaction updates within milliseconds of bank ledger commits. Payment processors and cryptocurrency exchanges demand this capability for continuous position monitoring.
Batch processing retains installed base scale; API integration gains share fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing procurement budgets as compliance cost differentials between jurisdictions reshape vendor selection. Banks in lower-compliance-cost environments capture implementation speed advantages while their counterparts in high-scrutiny markets absorb certification overhead.
United States
SEC enforcement of Sarbanes-Oxley accuracy requirements compels publicly traded firms to maintain immutable reconciliation trails. The regulatory burden falls heaviest on Fortune 500 manufacturers and technology firms concentrated in California and New York. San Francisco-based SaaS companies negotiate three-year embedded reconciliation contracts rather than standalone deployments.
Germany
Strict data residency laws under national banking supervision perpetuate on-premises installations despite higher total cost of ownership. The EU Digital Operational Resilience Act imposes operational continuity standards that Frankfurt-based Tier-1 banks must satisfy through certified infrastructure. Bavarian mittelstand manufacturers maintain batch processing patterns with 18-36 month change management cycles.
United Kingdom
Open banking mandates accelerate API-first adoption among corporate treasurers demanding real-time sync capabilities. Lloyd's syndicates in London drive specialized demand for immutable audit logging under Solvency II requirements. The City of London concentrates procurement authority for multinational insurance and reinsurance reconciliation.
Japan
FSA guidelines on internal governance push megabanks toward hybrid architectures that process sensitive steps locally while cloud-scaling non-critical workloads. Tokyo-based financial institutions pilot community cloud fabrics to reduce compliance duplication across peer consortiums. Regional banks in Osaka and Nagoya retain entrenched batch processing environments.
Switzerland
Physical data sovereignty requirements block cloud migration for private wealth managers and cantonal banks. Swiss private banking centers in Zurich and Geneva maintain licensed on-premises installations despite SaaS pressure from multinational competitors. The national regulator mandates jurisdictional control over client ledger reconciliation.
Reconciliation Software Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-suite ERP embedders capturing mid-market volume while best-of-breed vendors retain premium pricing in complex banking environments. The vendor base organizes into three tiers: cloud-native SaaS platforms, legacy on-premises incumbents with hybrid transition roadmaps, and AI-powered specialists targeting high-volume transaction matching. Consolidation pressure intensifies as banking sector M&A creates demand for unified reconciliation infrastructure across merged entities. Strategic partnerships between reconciliation vendors and open banking API providers are displacing traditional SWIFT integration services.
Within the cloud-native tier, BlackLine and Oracle NetSuite exemplify divergent go-to-market approaches, with the former anchoring enterprise-grade close management and the latter embedding reconciliation within broader ERP suites. HighRadius occupies a position among AI-powered specialists, representing the archetype of vendors extending cash application automation into reconciliation workflows. These three companies illustrate how procurement criteria are splintering between real-time API architectures and embedded module convenience.
| Leading Market Players |
|---|
| FloQast |
| Oracle NetSuite |
| Solvexia |
| HighRadius |
| Sage Intacct |
| BlackLine |
| OneStream |
| FIS Global |
| Trintech |
| Others |
Cost & Logistics Intelligence
Procurement teams at Fortune 500 manufacturers are mandating real-time API architectures over legacy batch systems, forcing vendors to restructure delivery models and compress margin structures across implementation services. This specification shift concentrates pricing power with cloud-native platform providers while eroding margins for custom integration specialists.
Pricing Analysis
Direct-to-enterprise subscription discounts dominate the reconciliation software market, with SaaS vendors offering three-year contracts to displace perpetual license incumbents. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with DORA-compliant and SOC 2 Type II certified platforms commanding substantial premiums over uncertified alternatives. Pricing pressure stems from open banking API commoditization in the United Kingdom and Brazil, which collapses margins on traditional SWIFT integration services. Mid-market SaaS companies exhibit highest price sensitivity, while Tier-1 banks in Frankfurt and Paris absorb premium pricing for resilience guarantees.
Supply Chain Analysis
Regional distribution centers in Ireland, Singapore, and Virginia anchor cloud infrastructure delivery for reconciliation platforms serving banking clients across the European Union, Asia-Pacific, and North America. The software supply chain draws from hyperscaler compute capacity, specialized machine learning engineering talent pools in Bangalore and Toronto, and financial services domain expertise concentrated in London and New York. Single-source vulnerability rests on AWS and Azure dominance in public cloud hosting, with limited viable alternatives for DORA-compliant European deployments. Distribution runs through direct enterprise sales teams and strategic systems integrators, bypassing traditional value-added reseller channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reconciliation software market compounds regulatory complexity into durable demand, with the EU Digital Operational Resilience Act mandating operational continuity certification that locks banking clients into compliant vendor relationships.
For Market Incumbents: Deploy AI-powered exception handling modules to defend against specialist entrants like HighRadius. Incumbents should accelerate hybrid cloud certifications for German and Swiss data residency requirements while acquiring machine learning engineering capability in Bangalore to offset talent scarcity. BlackLine and Oracle NetSuite exemplify divergent consolidation paths—anchoring enterprise close management versus embedding reconciliation within ERP suites. For New Entrants and Emerging Players: Mid-market corporate finance teams at technology firms represent the most penetrable buyer archetype, as these buyers prioritize embedded modules over best-of-breed procurement. New entrants should target three-year SaaS contract structures with predictable operating budget alignment, avoiding capital expenditure approval cycles that favor incumbents. A vertical-specific go-to-market angle—such as Solvency II compliance for Lloyd's syndicates—circumvents direct confrontation with full-suite ERP embedders. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-powered cash application specialists extending into reconciliation workflows, as these vendors capture payment processor volumes with machine learning matching algorithms. Long-term viability hinges on multi-jurisdiction certification roadmaps spanning SEC, EBA, and FSA requirements. Acquisition targets should demonstrate DORA compliance progress and open banking API integration depth. The signal to watch is Tier-1 bank RFP criteria rewriting to prioritize resilience certification over feature breadth.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding reconciliation within ERP suites captures mid-market buyers unwilling to procure standalone solutions. |
| Strategic Partnership | Alliances with open banking API providers displace traditional SWIFT integration services and compress custom development margins. |
| Acquisition of Specialist Firm | Consolidating AI-powered cash application vendors accelerates machine learning matching capability for high-volume transaction environments. |
| Geographic Expansion | Establishing DORA-compliant infrastructure in Frankfurt and Paris maintains procurement eligibility for European Tier-1 banking clients. |
| Product Launch | Real-time sync architectures displace overnight batch processing and compress financial close cycles from weeks to hours. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation. SEC filings, open banking regulatory disclosures, hyperscaler capex reports, and EU DORA implementation guidance provided foundational data. Bottom-up transaction volume modeling and top-down regulatory mandate impact assessment were triangulated to reconcile demand estimates.
Rate-of-change decomposition across the analysis window isolates cloud migration velocity, API adoption curves, and regulatory compliance deadline effects. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from installation base conversion rates and new contract velocity by tier. Forecast inputs incorporate banking sector M&A pipeline activity and machine learning model deployment timelines at payment processors.
Inputs from regulatory filings and vendor contract disclosures were available through the study window; gaps in private company pricing data introduce uncertainty bands around mid-market penetration estimates. Forecasts reflect documented assumptions regarding DORA implementation timelines and open banking mandate enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
India Payroll Services Market
Financial Services
Benefits Consulting Service Market
Financial Services
China Factoring Services Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
Germany E-Brokerage Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Financial Advisory Services Market
Financial Services
Global Medical Equipment Financing Market
Financial Services
Canada Credit Cards Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Europe B2C Legal Services Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Global Treasury Software Market
Financial Services
UK Islamic Finance Market
Financial Services
BFSI A2P SMS Market