
 US Online Trading Platform Market | 2026-2036
US Online Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
US Online Trading Platform Market Insights
API-based architecture is fragmenting the traditional monolithic trading stack into modular, embeddable components. Interactive Brokers leverages its proprietary order-routing infrastructure to sustain institutional-grade execution speeds. Charles Schwab anchors its competitive position through hybrid advisory-brokerage workflows that bridge self-service and guided investing.
US online trading platforms are digital intermediaries that match buy and sell orders across equities, derivatives, and fund vehicles while providing real-time market data, charting tools, and portfolio analytics. Brokerage Services dominates transaction revenue, while Mobile Applications represents the fastest-growing device channel as retail engagement shifts to smartphone-native interfaces. Wealth Management and Advisory Services concentrate margin pools through recurring fee structures that offset commission compression in pure execution.
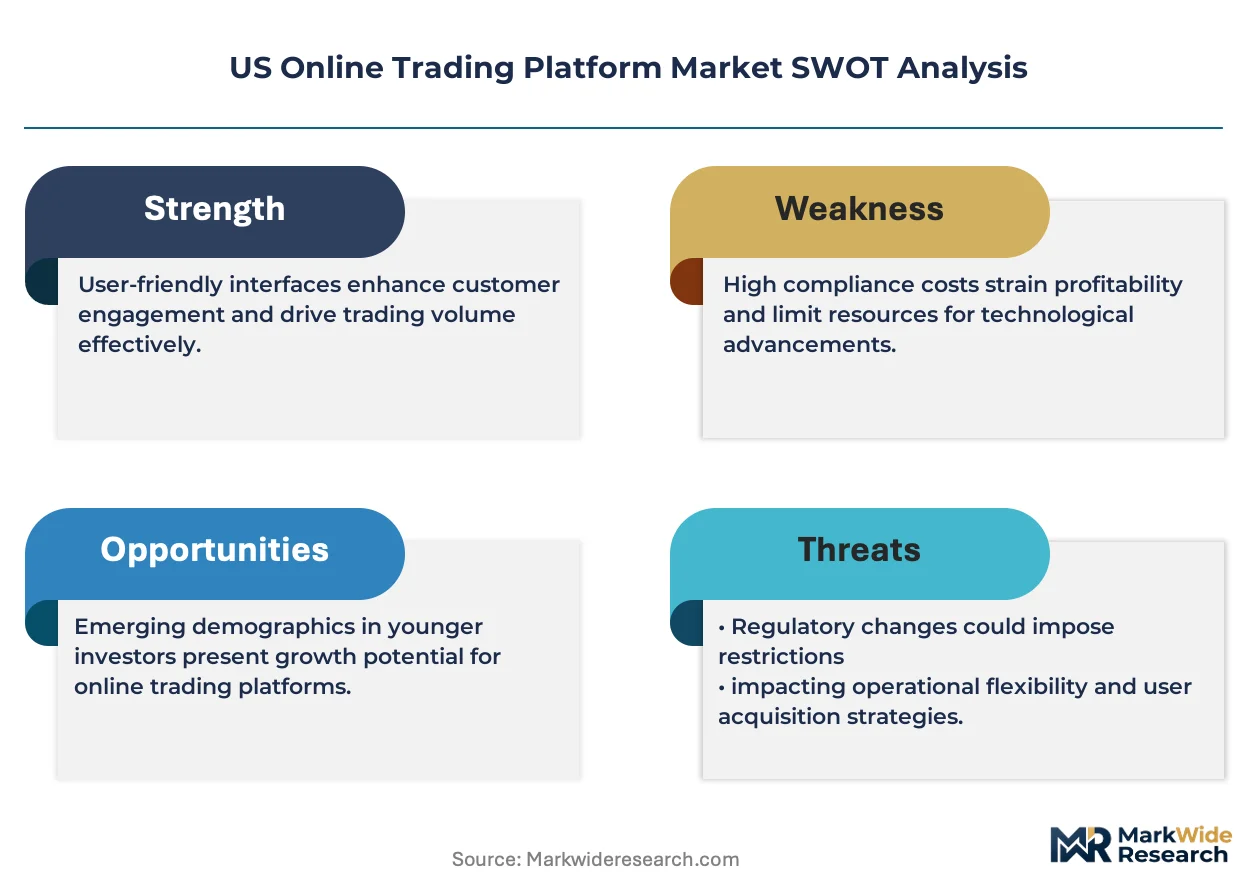
The SEC enforces disclosure and best-interest standards through Regulation BI and ongoing broker-dealer examinations, while FINRA maintains surveillance over trading conduct and platform advertising claims. The CFTC oversees derivatives-access protocols for platforms offering futures and forex instruments. Stakeholders must monitor evolving fiduciary-rule litigation and state-level registration requirements that could reshape platform economics and compliance staffing models.
Market Dynamics
API-first brokerage infrastructure is fragmenting the traditional monolithic trading stack into modular, embeddable components that third-party fintechs can white-label. This architectural shift compresses barriers to entry while forcing incumbent platforms to defend execution speed and custody reliability as differentiated assets.
Growth Catalysts
- SEC Regulation Best Interest:Elevated compliance requirements favor scaled platforms with dedicated legal infrastructure, accelerating consolidation among broker-dealers with sub-$50 million regulatory budgets.
- Smartphone-native retail engagement:Mobile Applications now dominate account opening flows, pulling demand from desktop interfaces and forcing platform operators to reallocate engineering resources toward iOS and Android execution paths.
- California and New York fintech density:Institutional capital pools and regulatory expertise concentrate in these coastal states, creating self-reinforcing talent and vendor ecosystems that attract platform headquarters and R&D operations.
Market Restraints
- Clearing and custody infrastructure concentration:Dependence on a limited set of bank-owned clearing firms creates systemic operational risk and limits pricing leverage for mid-tier platforms.
- Commission compression in pure execution:Zero-commission models have eliminated transaction revenue as a standalone profit center, forcing dependence on payment for order flow and securities lending.
- State-level registration fragmentation:Non-uniform licensing requirements across 50 states impose redundant compliance costs that disproportionately burden emerging platform entrants.
Strategic Opportunities
- Wealth Management and Advisory Services:Recurring fee structures through hybrid robo-advisory workflows offset commission erosion and capture higher lifetime value per account.
- Texas and Florida sub-regions:Migration of high-net-worth individuals to low-tax states creates underpenetrated demand for sophisticated self-directed tools outside traditional coastal clusters.
- FINRA advertising surveillance modernization:Automated compliance tooling for social media and influencer marketing represents a white-space service layer adjacent to core brokerage operations.
Industry Challenges
- Real-time risk engine engineering talent:Scarcity of specialists capable of building sub-millisecond order validation systems limits platform capacity to offer complex derivatives products safely.
- FINRA examination cycle unpredictability:Irregular regulatory audit timing disrupts product roadmaps and forces defensive resource allocation away from innovation.
- Core banking system integration:Legacy ACH and wire infrastructure creates friction in instant funding workflows that neobank competitors have conditioned retail investors to expect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Online Trading Platform Market |
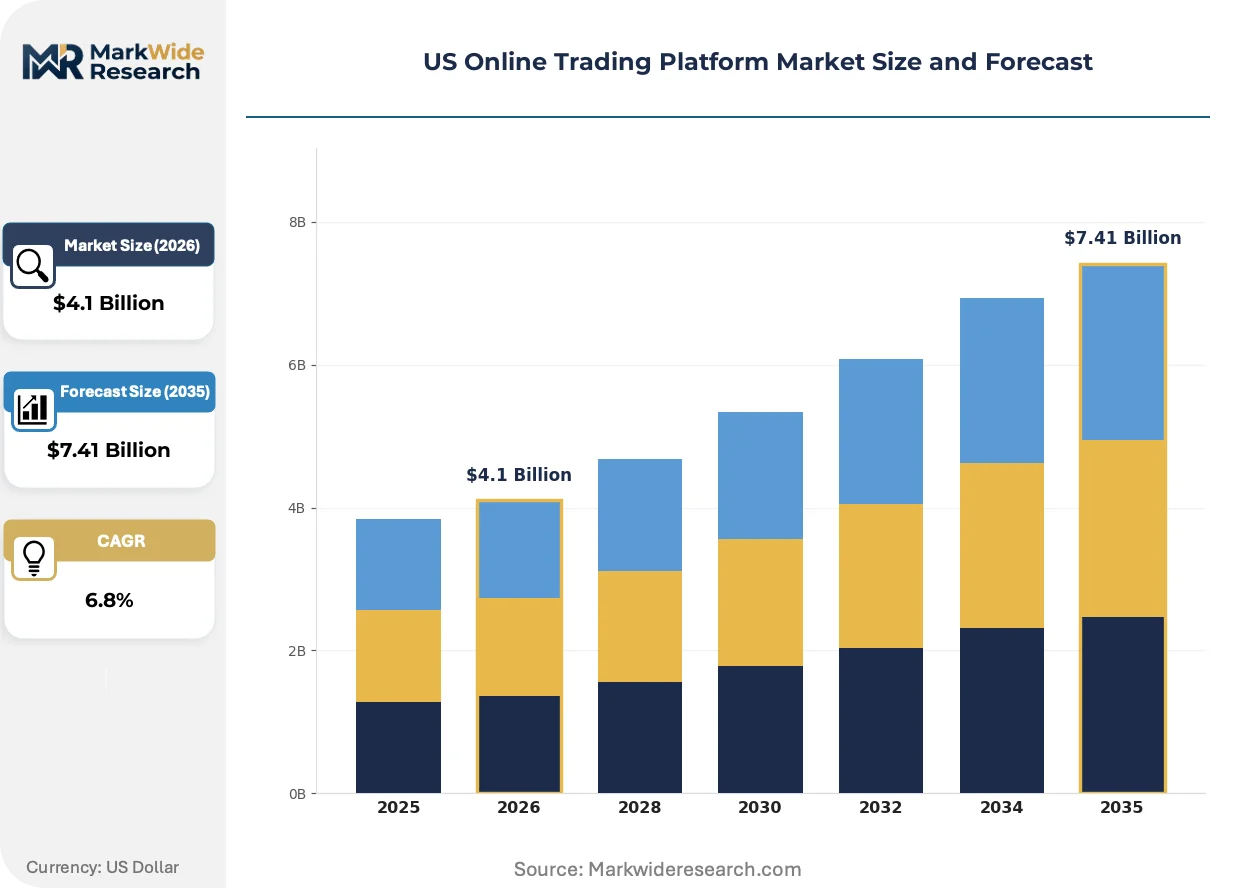
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Brokerage Services, Advisory Services, Wealth Management, Research Tools Client Type: Retail Investors, Institutional Investors, High Net Worth Individuals, Corporations Transaction Type: Stock Transactions, Options Trading, Forex Trading, Mutual Funds Device Type: Web Platforms, Mobile Applications, Desktop Applications, APIs |
| Companies Covered | Interactive Brokers, Robinhood, Charles Schwab, Vanguard, Webull, Fidelity, TD Ameritrade, Betterment, E*TRADE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Online Trading Platform Market Trends and Innovations
Embedded finance architectures are dissolving the boundary between trading platforms and adjacent consumer applications. Three convergent forces are compressing development cycles and redefining how retail investors discover and execute positions.
Fractional share technology is rendering obsolete minimum investment thresholds that previously excluded small-balance retail participation. Gen Z and millennial account holders now build diversified equity positions with sub-$100 commitments. Traditional mutual fund minimums and whole-share requirements are losing relevance as primary entry barriers.
SEC cybersecurity disclosure rules now mandate incident reporting within four business days, elevating information security to board-level governance. Platform operators must maintain 24/7 threat detection capabilities and document response protocols. Mid-size broker-dealers face particular strain as they lack dedicated security operations centers.
Social trading and copy-portfolio features are restructuring how inexperienced investors select strategies. TikTok and Discord channels now function as discovery surfaces that bypass traditional financial media and advisor relationships. This behavioral shift concentrates in 18-34 demographic segments where conventional brand loyalty to established institutions has weakened.
US Online Trading Platform Market Segmentation
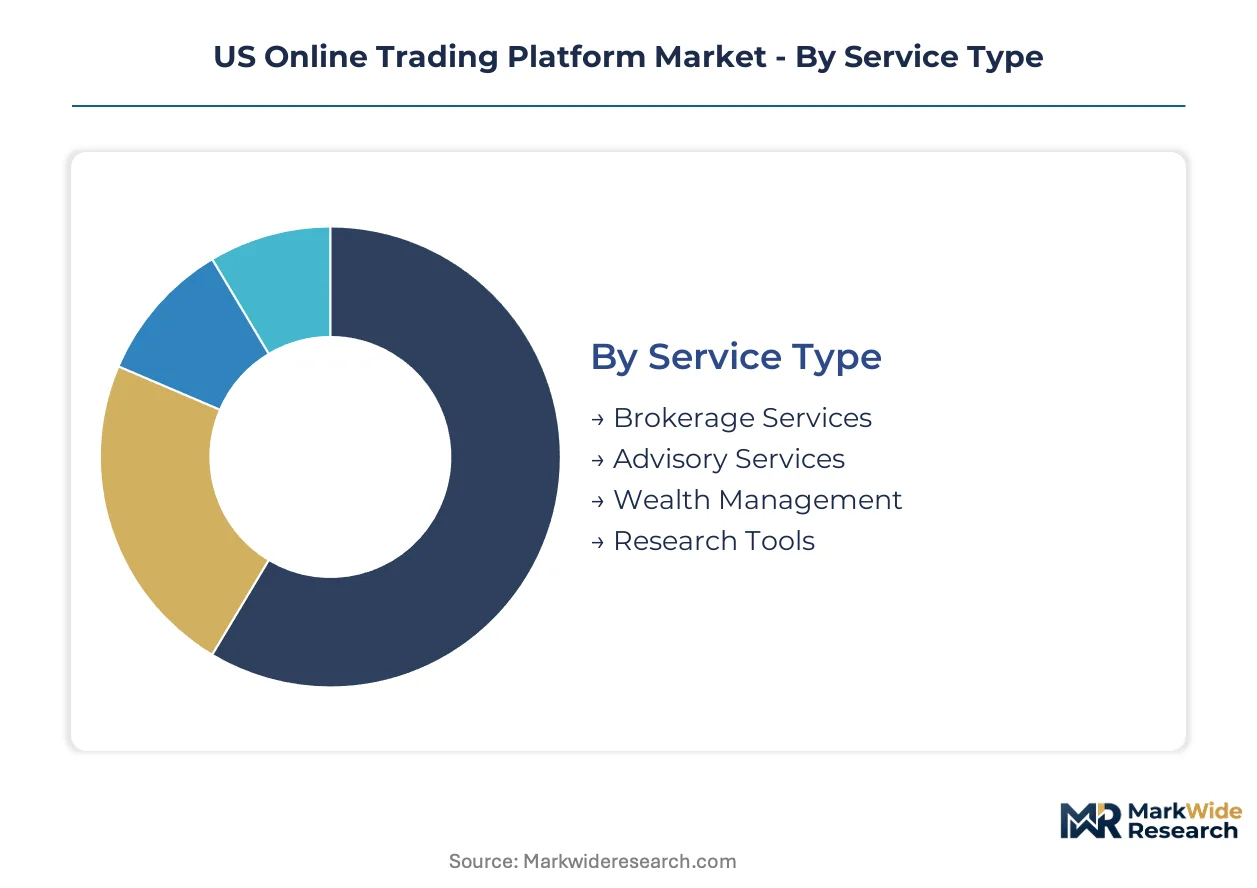
Platform operators configure service architectures around distinct investor workflows and execution preferences. Segmentation reveals where engineering resources concentrate versus where margin pools resist commoditization pressures.
Service Type:
Brokerage Services turn over fastest with transaction velocity measured in milliseconds, while Wealth Management cycles stretch across multi-year advisory relationships.
- Brokerage Services:Core execution infrastructure matching buy and sell orders across equities, derivatives, and fund vehicles with real-time market data feeds. Demand concentrates among self-directed retail investors in California and New York where fintech density sustains platform innovation and user acquisition costs remain lowest.
- Advisory Services:Hybrid human-digital guidance workflows blending algorithmic portfolio construction with licensed planner oversight. High net worth individuals migrating to Texas and Florida drive demand as these states attract capital flight from high-tax coastal jurisdictions.
- Wealth Management:Comprehensive financial planning integrating tax optimization, estate structuring, and liability management.
- Research Tools:Proprietary analytics, screeners, and fundamental data packages monetized through subscription tiers.
Brokerage Services anchors the volume base while Advisory Services gains share at the steepest rate.
Client Type:
Cost tiers separate mass-market retail from institutional clients with diverging infrastructure requirements and pricing sensitivity.
- Retail Investors:Individual account holders executing self-directed strategies through smartphone-native interfaces. Smartphone-native engagement in the 18-34 demographic pulls demand toward mobile-first platforms with fractional share capabilities.
- Institutional Investors:Asset managers, hedge funds, and pension funds requiring FIX protocol connectivity, colocated servers, and sub-millisecond execution. SEC Regulation Best Interest compliance costs disproportionately burden smaller institutional platforms, accelerating consolidation.
- High Net Worth Individuals:Accredited investors with $1 million-plus investable assets accessing specialized products and dedicated service teams.
- Corporations:Treasury departments managing cash positions, employee stock plans, and corporate retirement vehicles.
Retail Investors generates the transaction volume while Institutional Investors commands the premium pricing tier.
Transaction Type:
Maturity gradients separate established equity markets from derivatives segments with evolving regulatory frameworks.
- Stock Transactions:Equity order flow across listed securities with commission compression eliminating standalone profit margins. Payment for order flow arrangements with market makers now subsidize zero-commission models.
- Options Trading:Multi-leg strategies requiring sophisticated risk engines and margin calculation systems. Retail demand for complex derivatives outpaces platform engineering capacity, creating execution quality gaps.
- Forex Trading:Currency pair speculation with 24-hour market access and leveraged position structures.
- Mutual Funds:Long-term fund vehicle accumulation with recurring investment automation features.
Stock Transactions retains the deepest liquidity pool while Options Trading expands most quickly among active retail segments.
Device Type:
Application maturity separates legacy desktop workflows from API-first architectures reshaping distribution.
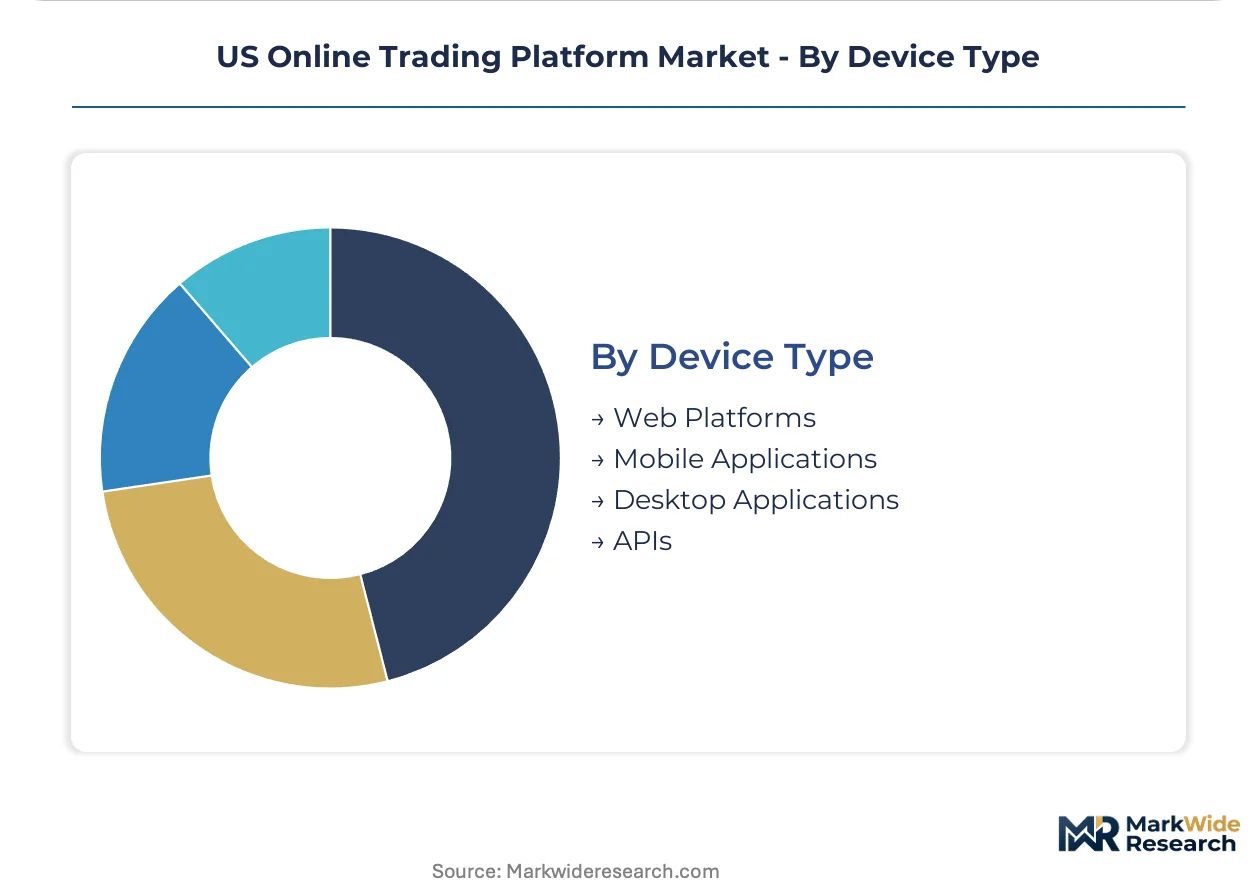
- Web Platforms:Browser-based interfaces balancing feature depth with cross-device accessibility. Hybrid advisory-brokerage workflows retain concentration here as advisors and clients co-navigate complex planning scenarios.
- Mobile Applications:Smartphone-native execution paths dominating account opening flows and casual position monitoring. California and New York fintech talent clusters drive iOS and Android innovation cycles.
- Desktop Applications:Downloadable software delivering advanced charting, algorithmic scripting, and multi-monitor workstation support.
- APIs:Programmatic interfaces enabling third-party fintech embedding and white-label brokerage infrastructure.
Web Platforms maintains the broadest user base while APIs climbs the fastest as embedded finance architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows from Texas and Florida into New York and California trading infrastructure define the dominant domestic corridor, with coastal fintech clusters processing execution volume from interior wealth migration.
California
Venture capital density and Stanford-Berkeley engineering pipelines sustain platform R&D concentration in San Francisco and Los Angeles. The California Department of Financial Protection and Innovation enforces state-level fintech licensing beyond federal SEC oversight. Silicon Valley hosts the densest cluster of API-first brokerage infrastructure startups.
New York
Wall Street proximity and FIX protocol engineering talent pools anchor institutional-grade execution infrastructure. The New York State Department of Financial Services maintains cybersecurity disclosure requirements that exceed federal baselines. Manhattan's fintech corridor houses the headquarters of three major clearing bank relationships.
Texas
High-net-worth migration from California and New York creates underpenetrated demand for self-directed tools in Dallas-Fort Worth and Austin. The Texas State Securities Board enforces registration requirements for platforms soliciting accredited investors. Houston's energy-sector wealth managers are adopting hybrid advisory-brokerage workflows.
Florida
Zero state income tax attracts retiree capital seeking self-directed retirement account management. The Florida Office of Financial Regulation coordinates with FINRA on advertising surveillance for social media influencer campaigns. Miami's emerging fintech cluster specializes in Latin American cross-border account onboarding.
Illinois
Chicago's derivatives exchange heritage sustains specialized options trading platform engineering talent. The Illinois Secretary of State Securities Department enforces registration for platforms offering complex multi-leg strategies. The city's commodity trading legacy informs risk engine architecture for retail derivatives access.
US Online Trading Platform Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three identifiable tiers. Incumbent platforms with hybrid advisory-brokerage workflows defend margin pools through recurring fee structures. API-first entrants fragment execution infrastructure into embeddable components. Consolidation pressure from SEC Regulation Best Interest compliance costs favors scaled operators with dedicated legal infrastructure over sub-$50 million regulatory budget competitors.
Within the incumbent tier, Charles Schwab and Fidelity occupy positions defined by hybrid human-digital guidance workflows. Interactive Brokers exemplifies the infrastructure-specialist archetype through proprietary order-routing systems. Robinhood represents the smartphone-native engagement model that has redefined retail account acquisition economics.
| Leading Market Players |
|---|
| Interactive Brokers |
| Robinhood |
| Charles Schwab |
| Vanguard |
| Webull |
| Fidelity |
| TD Ameritrade |
| Betterment |
| E*TRADE |
| Others |
Pricing and Supply Chain Analysis
New York's clearing bank corridor concentrates custody infrastructure capacity, compressing pricing leverage for mid-tier broker-dealers while amplifying margin capture for scaled operators with direct clearing relationships. Commission-free execution has shifted revenue capture toward payment-for-order-flow arrangements and securities lending programs, embedding pricing power within order-routing sophistication rather than headline transaction fees.
Pricing Analysis
Next-generation API-first brokerage infrastructure commands premium pricing against legacy web-platform tiers and basic mobile execution paths. Three-tier pricing structure across premium, standard, and economy levels segments by execution speed, data depth, and advisory overlay intensity. Pricing pressure stems from zero-commission normalization and payment-for-order-flow regulatory scrutiny. Retail investors in the 18-34 demographic exhibit highest price sensitivity, while institutional clients prioritize execution quality over cost minimization.
Supply Chain Analysis
Bank of New York Mellon, JPMorgan Chase, and Citigroup dominate contract clearing and custody capacity for US broker-dealer infrastructure. Taiwan and South Korea supply critical semiconductor components for co-located server farms and risk-engine hardware. Raw material dependencies include fiber-optic cable, specialized cooling systems, and high-frequency trading chipsets. Single-source vulnerability concentrates in clearing bank relationships, where operational disruption would cascade across downstream platforms. Distribution runs through direct-to-consumer onboarding flows and white-label API embedding into third-party fintech applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first disruption and SEC regulatory tightening are compressing traditional brokerage economics while elevating compliance infrastructure as a competitive moat. Platforms must navigate between execution speed investment and advisory service margin capture.
For Market Incumbents: Harden custody reliability and order-routing speed as differentiated assets against modular API competitors. Prioritize vertical integration into proprietary clearing infrastructure to reduce dependence on bank-owned utilities. Defensive consolidation of sub-scale broker-dealers with sub-$50 million regulatory budgets will accelerate as SEC examination intensity rises. For New Entrants and Emerging Players: Texas and Florida sub-regions offer underpenetrated demand from high-net-worth migrants seeking self-directed tools outside coastal advisory networks. Target hybrid robo-advisory workflows in these markets with lower customer acquisition costs than saturated California and New York corridors. White-label API distribution through embedded finance partnerships accelerates scale without direct brand building. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance costs and technology infrastructure requirements favor scaled operators over fragmented mid-tier competitors. Target acquisition profiles center on API-first infrastructure specialists with modular embeddable components and established clearing relationships. Monitor FINRA examination cycle intensity and state-level registration harmonization efforts as early signals of competitive pressure direction.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Clearing Infrastructure Development | Reduces PFOF dependence and captures margin from custody services directly. |
| Hybrid Advisory-Brokerage Workflow Expansion | Offsets commission compression through recurring fee structures and higher LTV. |
| API-First Platform Architecture | Enables white-label embedding and third-party fintech distribution channels. |
| Real-Time Risk Engine Investment | Supports complex derivatives access and sub-millisecond order validation capabilities. |
| Geographic Expansion to Low-Tax States | Captures high-net-worth migration demand in Texas and Florida corridors. |
Research Methodology
Operator-level perspectives from brokerage platform CTOs, clearing operations directors, SEC compliance officers, and retail trading product managers anchored the qualitative base. Secondary validation drew from SEC 10-K filings, FINRA disciplinary actions databases, broker-dealer registration records, and platform engineering job posting analytics. Bottom-up account and transaction volume estimates triangulated against top-down addressable market sizing.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with CAGRs derived from regression analysis of historical platform adoption curves and demographic wealth migration patterns. Segmentation dimensions modeled include service type, client type, transaction type, and device channel. Industry-specific forecast inputs incorporated payment-for-order-flow revenue per account and advisory service attach rates.
Practitioners should monitor SEC enforcement intensity, FINRA advertising surveillance modernization, and state-level registration harmonization proposals for early signals of forecast revision. Quarterly review of clearing bank operational incidents, API security disclosures, and high-frequency trading talent migration patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Cash Flow Market
Financial Services
Australia Online Gambling Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
E-Invoicing Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Virtual Account Management Software Market
Financial Services
ATM Software Market
Financial Services
Africa Factoring Services Market
Financial Services
White Glove Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Financial Services Application Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Financial Auditing Professional Services Market