
 Africa Lottery Market | 2026-2036
Africa Lottery Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Lottery Market Outlook
Young adult players on mobile platforms are redrawing the Africa lottery landscape as digital-native demand overtakes traditional retail purchasing. ITHUBA leverages its technology leadership in South Africa's online segment to sustain channel control across multiple provinces. Goldrush competes through extensive retail kiosk networks that anchor physical ticket distribution in urban centers. Uganda National Lottery differentiates by integrating mobile money payment rails that dominate East African transaction flows.
An Africa lottery constitutes a regulated game of chance operated by licensed entities, utilizing randomized number draws or instant-win mechanisms with defined prize pools and predetermined odds structures, primarily generating revenue for operator margins and mandated public benefit allocations. Scratch cards and number draws represent the mature revenue base, while online platforms and mobile apps capture the fastest expansion as smartphone penetration deepens across the continent. Subscription tickets concentrate margin pools through recurring revenue models that reduce customer acquisition costs for operators building long-term player databases.
South Africa's National Gambling Board, Nigeria's National Lottery Regulatory Commission, and Kenya's Betting Control and Licensing Board shape market access through divergent licensing tiers, tax structures, and advertising restrictions that operators must navigate across jurisdictions. These frameworks directly determine which game formats reach market and how revenue splits flow to state treasuries versus operator retention. Stakeholders must monitor regulatory harmonization pressures as cross-border digital platforms test the boundaries of territorially bounded licensing regimes.
Market Dynamics
Mobile-first player behavior is decomposing traditional retail lottery distribution across Africa, forcing operators to rebuild infrastructure around smartphone penetration and mobile money rails rather than physical kiosk networks.
Growth Catalysts
- Mobile money integration:East African payment rails now dominate transaction flows, enabling instant ticket purchases without banking infrastructure.
- Nigeria's National Lottery Regulatory Commission:Tightened licensing frameworks channel gaming revenue into public welfare funds, legitimizing operator expansion.
- Smartphone penetration:Young adult digital-native demand overtakes legacy retail purchasing in urban centers.
Market Restraints
- Fragmented regulatory geography:Divergent licensing tiers across South Africa, Nigeria, and Kenya force operators to maintain parallel compliance systems.
- Retail kiosk concentration:Physical networks in urban centers create sunk-cost inertia that slows digital pivot timelines.
- Cross-border platform ambiguity:Territorially bounded licensing regimes face pressure from digital operators testing jurisdictional boundaries.
Strategic Opportunities
- Subscription ticket models:Recurring revenue structures reduce customer acquisition costs while building long-term player databases.
- Kenya's Betting Control and Licensing Board:Digital distribution infrastructure expansion creates regulatory tailwind for online platform entrants.
- Instant-win mobile games:Scratch-card mechanics ported to app environments capture players seeking immediate gratification.
Industry Challenges
- Platform integration complexity:Legacy retail systems must synchronize with mobile backends without disrupting existing agent commissions.
- Harmonization timeline uncertainty:Cross-border digital platforms await clarity on whether national regulators will coordinate or compete on licensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Lottery Market |
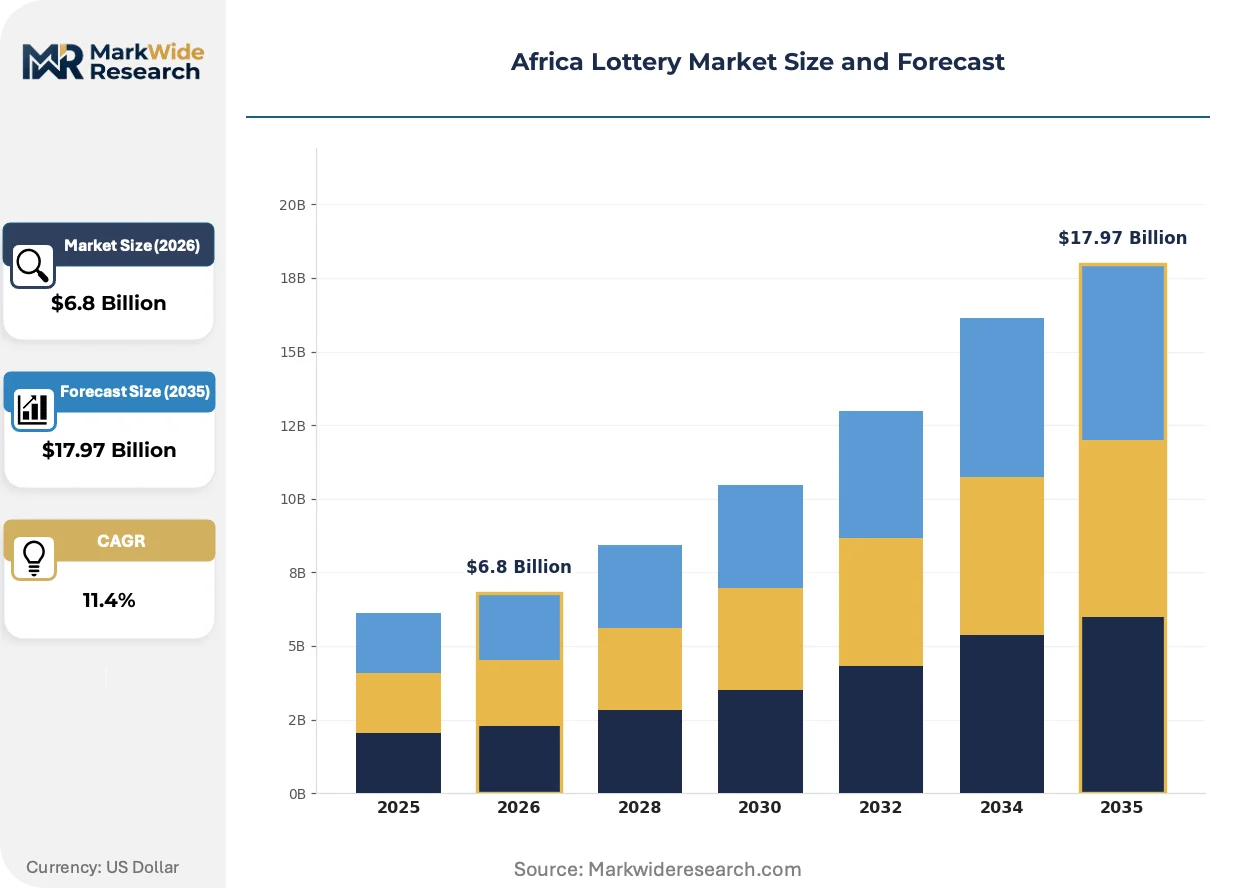
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ticket Type: Physical Tickets, Online Tickets, Instant Win Tickets, Subscription Tickets Game Format: Scratch Cards, Number Draw, Raffles, Multi-State Draws Player Demographics: Young Adults, Middle-aged Players, Seniors, High Rollers Distribution Channel: Retail Outlets, Online Platforms, Mobile Apps, Kiosks |
| Companies Covered | Goldrush, Uganda National Lottery, ITHUBA, Botswana National Lottery, Tanzania National Lottery, Sizekhaya Holdings, Benin National Lottery (LNB), Wina Njalo, Genlot, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Lottery Market Strategic Shifts
Digital distribution infrastructure is actively reshaping how African lottery operators reach players, with technology investments now outpacing physical network expansion for the first time.
Blockchain-based transparency mechanisms are decomposing traditional trust architectures in number-draw verification. South African operators pilot distributed ledger systems for real-time result publication. This technology compression eliminates intermediary audit costs while satisfying National Gambling Board demands for provable fairness.
South Africa's National Gambling Board enforces advertising restrictions that limit how operators target young adults across digital channels. Compliance teams now embed age-verification protocols directly into mobile app onboarding flows. Online segment leaders absorb these friction costs to preempt regulatory suspension.
Agent commission structures face unbundling as mobile direct sales bypass traditional retail intermediaries. Urban kiosk operators see ticket volume migrate to smartphone purchases, forcing network owners to renegotiate revenue splits. This channel displacement concentrates in Nigeria and Kenya where mobile money adoption deepest.
Africa Lottery Market Segmentation
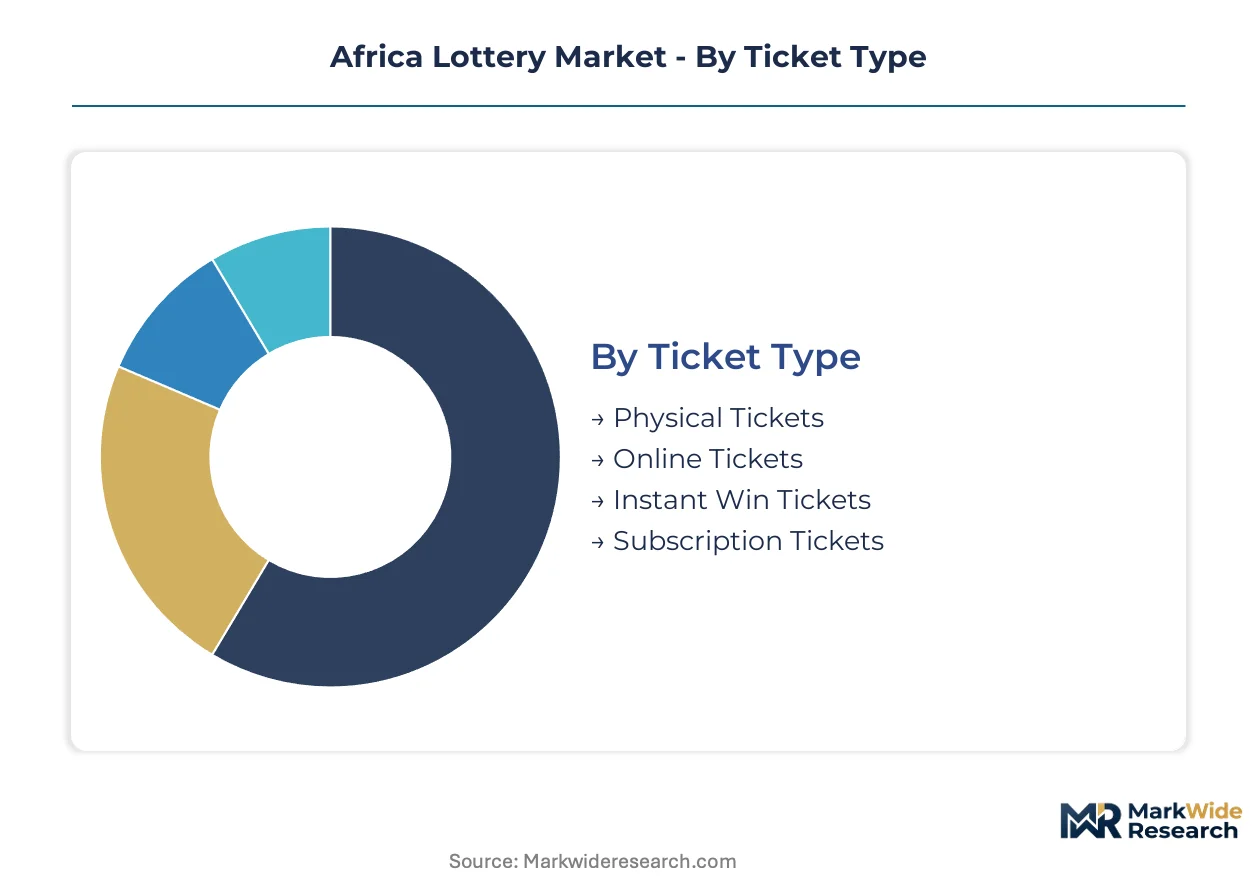
Segmentation across Africa's lottery market reveals how regulatory divergence shapes product availability and channel access. National frameworks in South Africa, Nigeria, and Kenya create distinct operating environments that favor certain ticket formats and distribution methods over others.
Ticket Type:
South Africa's National Gambling Board, Nigeria's National Lottery Regulatory Commission, and Kenya's Betting Control and Licensing Board each impose distinct technical standards on ticket issuance that operators must satisfy for market entry.
- Physical Tickets:Printed paper tickets with serialized barcode tracking remain the compliance baseline for retail-heavy jurisdictions. Demand concentrates in South Africa's urban centers where legacy kiosk networks maintain regulatory-approved distribution density.
- Online Tickets:Web-based purchase systems with integrated age verification and geolocation locking. Nigeria's tightened licensing frameworks now mandate server location within national borders, channeling revenue toward public welfare funds while legitimizing operator expansion.
- Instant Win Tickets:Digital scratch-card mechanics ported to screen interfaces.
- Subscription Tickets:Recurring purchase models with automated draw entry and win notification.
Physical tickets handle the majority of throughput; online tickets are expanding most quickly as smartphone penetration deepens.
Game Format:
Margin structures vary sharply across formats, with instant-win products capturing higher per-transaction value while draw games build sustained player engagement through jackpot accumulation mechanics.
- Scratch Cards:Pre-printed or digital instant-win products with fixed prize pools and immediate outcome revelation. Kenya's mobile money rails dominate East African transaction flows for these low-ticket items.
- Number Draw:Scheduled randomized draws with rolling jackpots and tiered prize structures. South Africa's National Gambling Board enforces advertising restrictions that limit how operators target young adults across digital channels for these games.
- Raffles:Limited-ticket sales with guaranteed winner mechanics and defined odds.
- Multi-State Draws:Cross-jurisdictional pooled jackpots requiring harmonized regulatory approval.
Number draws generate the steadiest revenue base; scratch cards are gaining share fastest through mobile app deployment.
Player Demographics:
Smartphone ownership curves and mobile literacy rates determine which demographic segments operators can reach through digital channels versus requiring physical retail presence.
- Young Adults:Digital-native players aged 18-35 with high mobile app engagement and preference for instant-win mechanics. Urban centers across Nigeria and Kenya see this cohort migrate ticket volume from retail kiosks to smartphone purchases.
- Middle-aged Players:Established lottery participants with brand loyalty to specific draw games and hybrid channel usage.
- Seniors:Demographic segment requiring simplified interfaces and retail-assisted transaction support.
- High Rollers:Premium players with elevated ticket volume and demand for VIP service tiers.
Young adults anchor volume growth in digital channels; middle-aged players sustain the core revenue base through subscription retention.
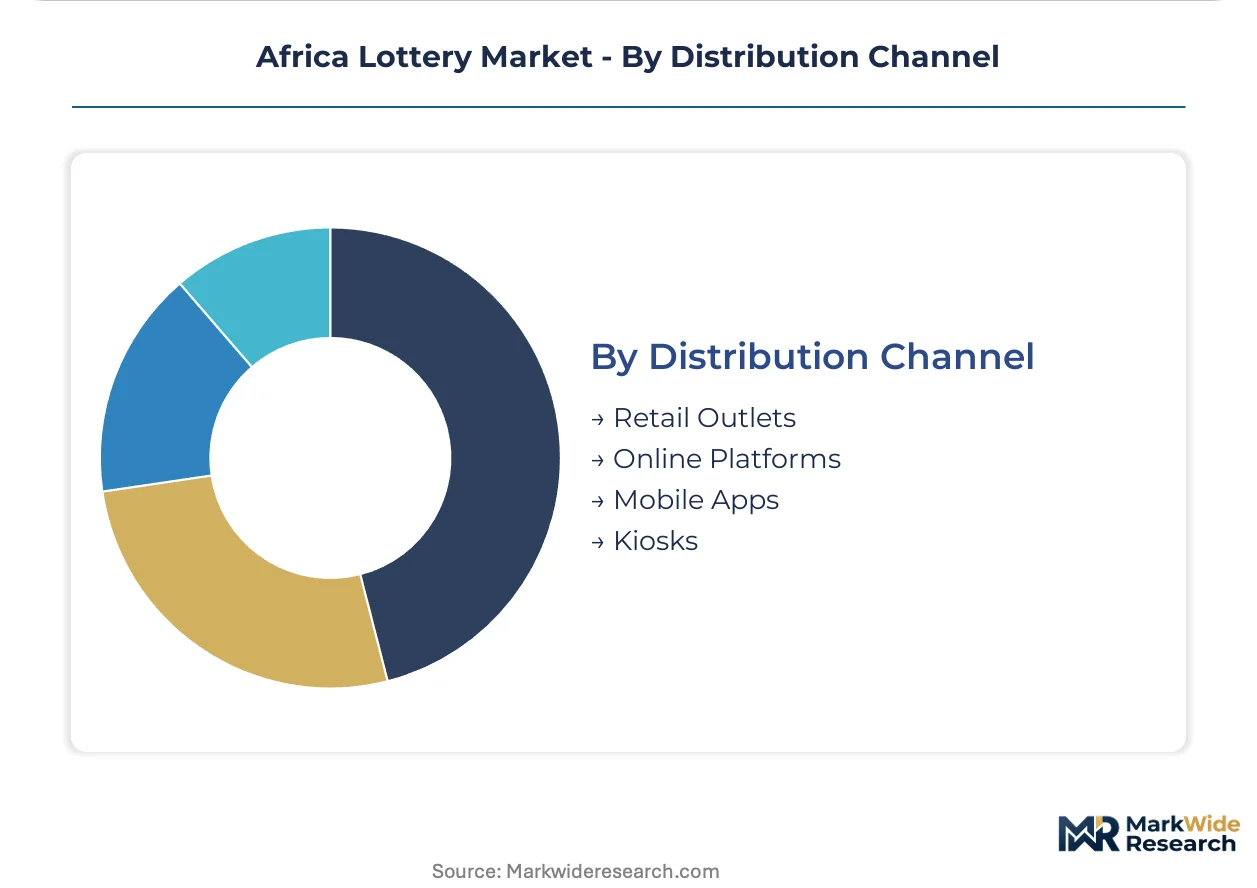
Distribution Channel:
Channel economics are decomposing as mobile direct sales bypass traditional retail intermediaries, forcing network owners to renegotiate revenue splits with urban kiosk operators seeing ticket volume migrate.
- Retail Outlets:Licensed physical points of sale with staffed counters and cash handling. South Africa maintains the most extensive compliant network, though agent commission structures face unbundling pressure.
- Online Platforms:Browser-based purchase portals with integrated payment processing and account management.
- Mobile Apps:Native smartphone applications with push notification engagement and biometric login. East African operators leverage mobile money payment rails that dominate transaction flows.
- Kiosks:Unattended self-service terminals with touchscreen interfaces and cash/card acceptance.
Retail outlets still process the highest absolute transaction count; mobile apps are climbing the fastest on share as infrastructure investments pivot toward digital distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa exports lottery technology and management expertise to neighboring Botswana and Namibia, creating a regional trade corridor that channels operational know-how northward while Nigeria's regulatory reforms attract West African capital flows.
South Africa
Mobile app penetration and retail kiosk networks drive ticket volume across Gauteng and Western Cape provinces. The National Gambling Board enforces advertising restrictions that limit digital targeting of young adults. Johannesburg anchors technology development while Cape Town concentrates operator headquarters and compliance functions.
Nigeria
Smartphone adoption among urban youth and mobile money integration reshape purchasing patterns in Lagos and Abuja. The National Lottery Regulatory Commission tightened licensing frameworks to mandate revenue flows into public welfare funds. Lagos State hosts the densest retail agent networks as operators build hybrid physical-digital distribution.
Kenya
Mobile money rails dominate transaction flows for instant-win products in Nairobi and Mombasa. The Betting Control and Licensing Board expanded digital distribution infrastructure approvals for online platform entrants. Nairobi's technology corridor attracts regional operator investment in app development and payment integration.
Uganda
Mobile money payment integration and young adult digital literacy accelerate smartphone-based ticket purchases in Kampala. The national lottery operator leverages East African transaction infrastructure to bypass traditional banking requirements. Kampala concentrates retail agent networks transitioning toward digital-assisted sales models.
Ghana
Urban youth smartphone ownership and instant-win game preference drive digital channel migration in Accra and Kumasi. The national gaming commission maintains licensing tiers that favor established operators with physical retail presence. Accra's financial technology cluster supports mobile payment integration for lottery transactions.
Africa Lottery Market Competitive Environment
Listed leaders compete with private specialists across technology and distribution dimensions, creating a tiered structure where scale advantages separate national incumbents from regional challengers. State-licensed operators hold territorial exclusivity in number-draw formats while private specialists capture mobile-first instant-win segments. Three archetypes dominate: technology-integrated national operators, retail-heavy physical distributors, and mobile-native platform specialists. Competitive moves concentrate on mobile app development and strategic partnerships with payment processors.
Within the technology-integrated tier, ITHUBA represents South African digital platform leadership while Goldrush exemplifies retail network density across urban centers. Uganda National Lottery occupies a position bridging mobile money integration with state-backed distribution authority. These three anchors illustrate how regulatory licensing shapes competitive positioning across divergent national frameworks.
| Leading Market Players |
|---|
| Goldrush |
| Uganda National Lottery |
| ITHUBA |
| Botswana National Lottery |
| Tanzania National Lottery |
| Sizekhaya Holdings |
| Benin National Lottery (LNB) |
| Wina Njalo |
| Genlot |
| Others |
Value Chain & Pricing Dynamics
Seven-to-fourteen-day settlement cycles for mobile money ticket purchases concentrate liquidity pressure on operators while amplifying pricing power for platform-integrated national incumbents across South Africa, Nigeria, and Kenya. This lead-time compression binds supply chain digitization directly to margin retention as physical retail networks face commission unbundling.
Pricing Analysis
Platform-generation pricing gaps separate mobile-native operators from legacy retail-dependent competitors across the Africa lottery market. Three-tier pricing structure across premium, standard, and economy levels dominates, with subscription models anchoring premium tiers and per-transaction instant-win products populating economy levels. Price differentiation stems from mobile money integration depth and National Gambling Board certification tier. Cost compression in standard-tier instant-win products is intensifying because Kenya's Betting Control and Licensing Board expanded digital distribution approvals. Young adult smartphone players exhibit highest price sensitivity; high-volume subscription players demonstrate lowest sensitivity due to automated draw entry convenience.
Supply Chain Analysis
Mombasa port congestion and Lagos-Abuja road freight delays constitute chokepoints that throttle physical ticket stock distribution across East and West Africa. Supply concentrates in South Africa for technology platforms, Nigeria for retail agent networks, and Kenya for mobile payment rails. Raw material dependencies include secure paper stock for physical tickets, server infrastructure for online platforms, and mobile money API access for digital transactions. Single-source vulnerability in M-Pesa and Airtel Money payment rails threatens East African operator continuity. Distribution runs through hybrid retail-digital channels with mobile apps capturing fastest share growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa lottery market sits at a platform-economics inflection where mobile money ecosystem interoperability between M-Pesa, Airtel Money, and MTN Mobile Money will determine operator survival. This interoperability shift decomposes territorial exclusivity models that previously protected national incumbents.
For Market Incumbents: Shield retail commission structures by embedding digital-assisted sales tools into existing agent networks before mobile direct sales bypass intermediaries entirely. Vertical integration into proprietary mobile money rails reduces dependency on third-party payment processors. National Gambling Board advertising restrictions demand pre-emptive compliance investment in age-verification technology to avoid regulatory suspension. For New Entrants and Emerging Players: Lead with instant-win mobile games in Ghana and Uganda where smartphone penetration among urban youth outpaces established operator digital pivot timelines. Kenya's expanded digital distribution infrastructure creates the most penetrable regulatory environment for online platform entrants. Partner with existing mobile money providers rather than building parallel payment rails. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription ticket models reduce customer acquisition costs while building defensible player databases. Target acquisition archetypes combine mobile-native platform technology with existing regulatory licenses in secondary markets like Botswana or Namibia. Watch for harmonization signals between South Africa's National Gambling Board and Nigeria's National Lottery Regulatory Commission as the key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Money Integration | M-Pesa and Airtel Money API partnerships eliminate banking infrastructure barriers for instant ticket purchases. |
| Subscription Platform Launch | Recurring revenue models reduce customer acquisition costs while building long-term player databases for retention. |
| Blockchain Verification Pilot | Distributed ledger systems for number-draw results satisfy National Gambling Board demands for provable fairness. |
| Retail-Digital Hybrid Network | Agent-assisted smartphone purchases preserve commission structures while capturing mobile-native demand migration. |
| Cross-Border Regulatory Harmonization | Coordinated licensing between South Africa, Nigeria, and Kenya enables multi-state pooled jackpot mechanics. |
Study Parameters
Operator-level perspectives from lottery platform executives, mobile money integration specialists, National Gambling Board compliance officers, and retail agent network managers anchored the qualitative base for this analysis. Secondary validation drew from National Lottery Regulatory Commission licensing filings, Betting Control and Licensing Board approval databases, mobile money transaction flow reports, and operator annual disclosures. Bottom-up ticket volume modeling and top-down revenue triangulation across Nigeria, South Africa, and Kenya calibrated market sizing.
Sensitivity analysis tested smartphone penetration trajectories, mobile money adoption curves, and regulatory harmonization timelines across the projection horizon. Segmentation dimensions modeled include ticket type, game format, player demographics, and distribution channel with mobile app deployment speed as an Africa-specific demand accelerator. CAGRs derived from compounding annual ticket volume growth against average revenue per user expansion, with mobile money transaction cost compression and digital platform scale economics as primary forecast inputs.
Underlying assumptions cover sustained smartphone penetration growth, stable mobile money regulatory treatment, and incremental licensing harmonization, with deviation risk concentrated in advertising restriction tightening and cross-border platform jurisdictional disputes. Practitioners should keep alternative scenarios live as National Gambling Board enforcement intensity and mobile money provider consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Reconciliation Software Market
Financial Services
Financial Services Software Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Solar Powered ATM Market
Financial Services
BFSI A2P SMS Market
Financial Services
Europe Factoring Services Market
Financial Services
Liquidation Service Market
Financial Services
Foreign Exchange Services Market
Financial Services
India Trade Finance Market
Financial Services
Global Financial Consulting Software Market
Financial Services
India Security Brokerage Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Trade Finance Market
Financial Services
Contract for Difference Broker Market
Financial Services
Legal Management Consulting Service Market
Financial Services
North America Management Consulting Services Market