
 MMA Triazine Market | 2026-2036
MMA Triazine Market Size, Share, and Industry Trends Forecast 2026-2036
MMA Triazine Market Analysis
ISO 9001 quality management certification is redrawing competitive boundaries for MMA triazine suppliers serving oilfield chemical buyers. Hexion leverages backward integration into formaldehyde and amine precursors to sustain cost discipline across North American supply chains. Evonik Industries anchors its position through R&D intensity in specialty amine chemistry, while Baker Hughes Company competes via captive demand from its drilling services division.
MMA triazine denotes a class of 1,3,5-triazine derivatives functionalized with methylol and melamine groups, synthesized through condensation of melamine with formaldehyde under controlled pH and temperature conditions to yield oligomeric structures with active hydrogen sulfide scavenging capacity. The compound serves primarily as a non-nitrogen-chloride-producing H2S scavenger in oil and gas production, replacing triazine alternatives that generate problematic byproducts. Liquid formulations dominate current volume owing to ease of injection into high-pressure wellbores, while powder and granular forms capture margin pools in remote logistics-constrained fields. Pharmaceutical-grade MMA-3 and MMA-4 variants command premium positioning as regulatory scrutiny intensifies on residual formaldehyde content.
EPA Office of Chemical Safety and Pollution Prevention oversight shapes permissible formaldehyde release thresholds, while REACH registration requirements in Europe constrain import flexibility for non-EU manufacturers. OSHA permissible exposure limits for triazine derivatives influence workplace handling protocols and personal protective equipment specifications across downstream blending operations. Stakeholders must monitor evolving state-level chemical disclosure mandates and assess backward integration into melamine supply as a hedge against feedstock volatility.
Market Dynamics
REACH registration deadlines and EPA formaldehyde thresholds are compressing formulation flexibility for MMA triazine producers, forcing simultaneous investment in low-emission synthesis routes and backward integration into melamine supply chains.
Growth Catalysts
- Offshore drilling intensity:Deepwater projects in the US Gulf Coast and Brazil's pre-salt basins require continuous H2S scavenger injection, locking in recurring chemical demand from integrated service providers.
- REACH Article 33 disclosure mandates:European downstream operators must document formaldehyde content across supply chains, advantaging pre-registered MMA triazine suppliers with existing dossier compliance.
- Low-toxicity substitution:Oilfield chemical buyers are displacing chlorine-generating triazine alternatives with MMA variants to reduce corrosion management costs in sour gas production.
Market Restraints
- Melamine price volatility:Feedstock costs fluctuate with Chinese industrial policy on urea-based chemical production, squeezing margin predictability for non-integrated formulators.
- Formaldehyde emission caps:EPA Office of Chemical Safety and Pollution Prevention thresholds constrain residual content in finished formulations, limiting high-concentration product options.
- Monoethanolamine substitution:Regenerable H2S scavengers in gas processing applications threaten MMA triazine volume in select downstream segments with lower chemical intensity.
Strategic Opportunities
- Pharmaceutical-grade certification:MMA-3 and MMA-4 variants command premium positioning as FDA scrutiny intensifies on residual formaldehyde in excipient applications.
- Remote logistics adaptation:Powder and granular formulations address supply constraints in North Dakota Bakken and West Texas Permian fields lacking liquid chemical infrastructure.
- EU Green Deal chemical sustainability criteria:Bio-based formaldehyde feedstock pathways align with emerging preferential procurement standards for low-carbon intensity scavengers.
Industry Challenges
- ISO 9001 certification timelines:Oilfield chemical buyers now mandate quality management system compliance as a gatekeeper for vendor qualification, extending sales cycles for emerging suppliers.
- Specialty amine chemistry talent scarcity:Condensation process optimization and pH-controlled synthesis require expertise concentrated among legacy melamine-formaldehyde chemists approaching retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MMA Triazine Market |
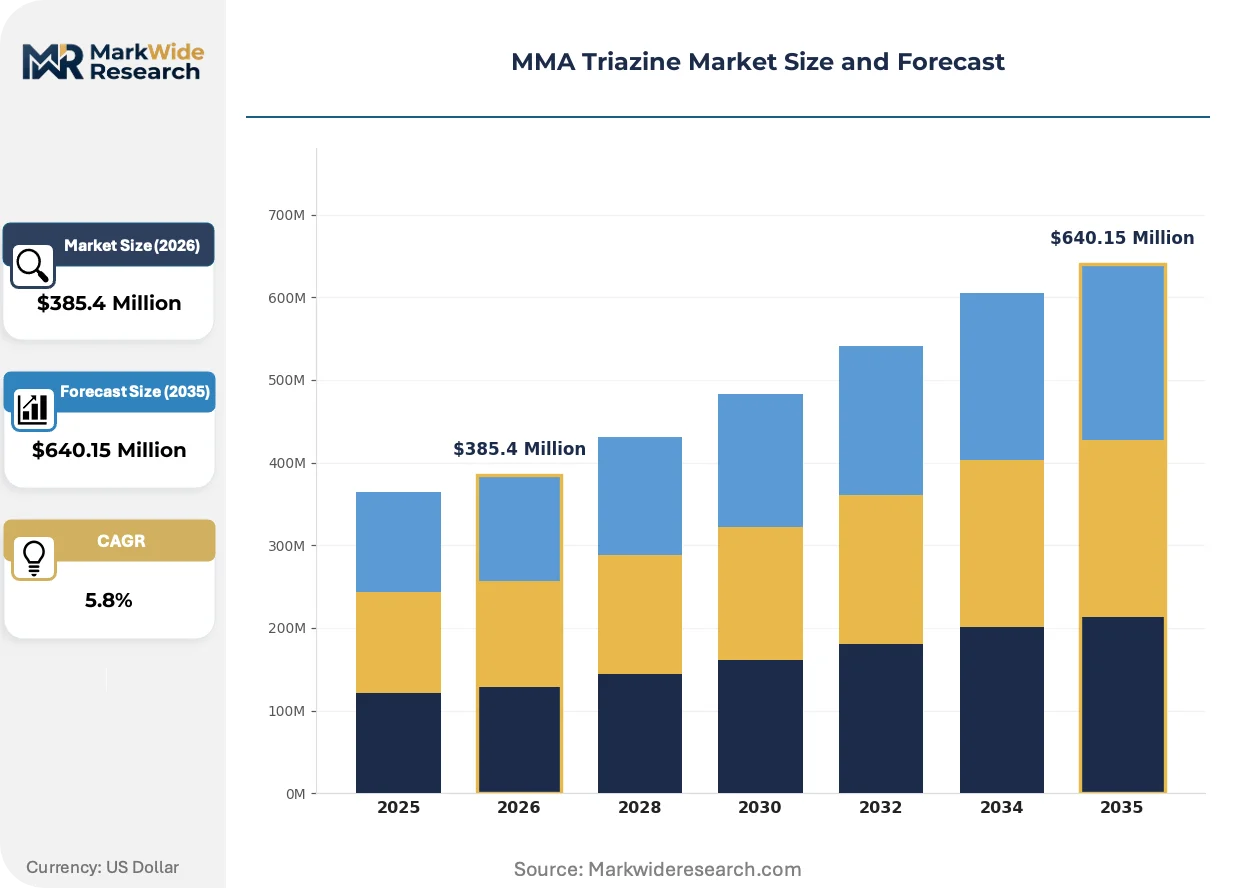
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MMA-1, MMA-2, MMA-3, MMA-4 Application: Agriculture, Automotive, Chemicals, Pharmaceuticals Form: Liquid, Powder, Granular, Emulsion End User: Farmers, Manufacturers, Retailers, Distributors |
| Companies Covered | Hexion, Eastman Chemical Company, Evonik Industries, Arkema S.A., Baker Hughes Company, BASF SE, Stepan, Huntsman Corporation, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MMA Triazine Market Emerging Trajectories
Formulation science and regulatory chemistry are diverging along separate innovation tracks, with liquid delivery systems optimizing for downhole injection performance while solid-state variants pursue logistics efficiency.
Pharmaceutical-grade MMA triazine synthesis is bifurcating the supplier base. High-purity MMA-3 and MMA-4 variants require dedicated reactor trains with formaldehyde stripping protocols. Specialty chemical divisions of integrated oilfield service companies are capturing this tier through captive R&D investment. The technology is bifurcating margin pools between commodity scavenger supply and certified excipient channels.
REACH registration renewal deadlines in 2025-2027 are compressing import flexibility for non-EU manufacturers. ECHA substance evaluation protocols now explicitly target formaldehyde release categories in triazine derivative classifications. European oilfield chemical distributors are consolidating supplier panels to reduce compliance audit burden, favoring registrants with complete Annex XV dossiers.
Buyer procurement patterns are fragmenting across performance tiers. Integrated operators with captive drilling services divisions are internalizing MMA triazine blending to secure supply continuity. Independent exploration companies without chemical infrastructure remain dependent on third-party formulators. This bifurcation is most visible in the US Gulf Coast petrochemical corridor, where downstream integration with offshore production platforms creates captive consumption clusters distinct from spot-market purchasing elsewhere.
MMA Triazine Market Segmentation
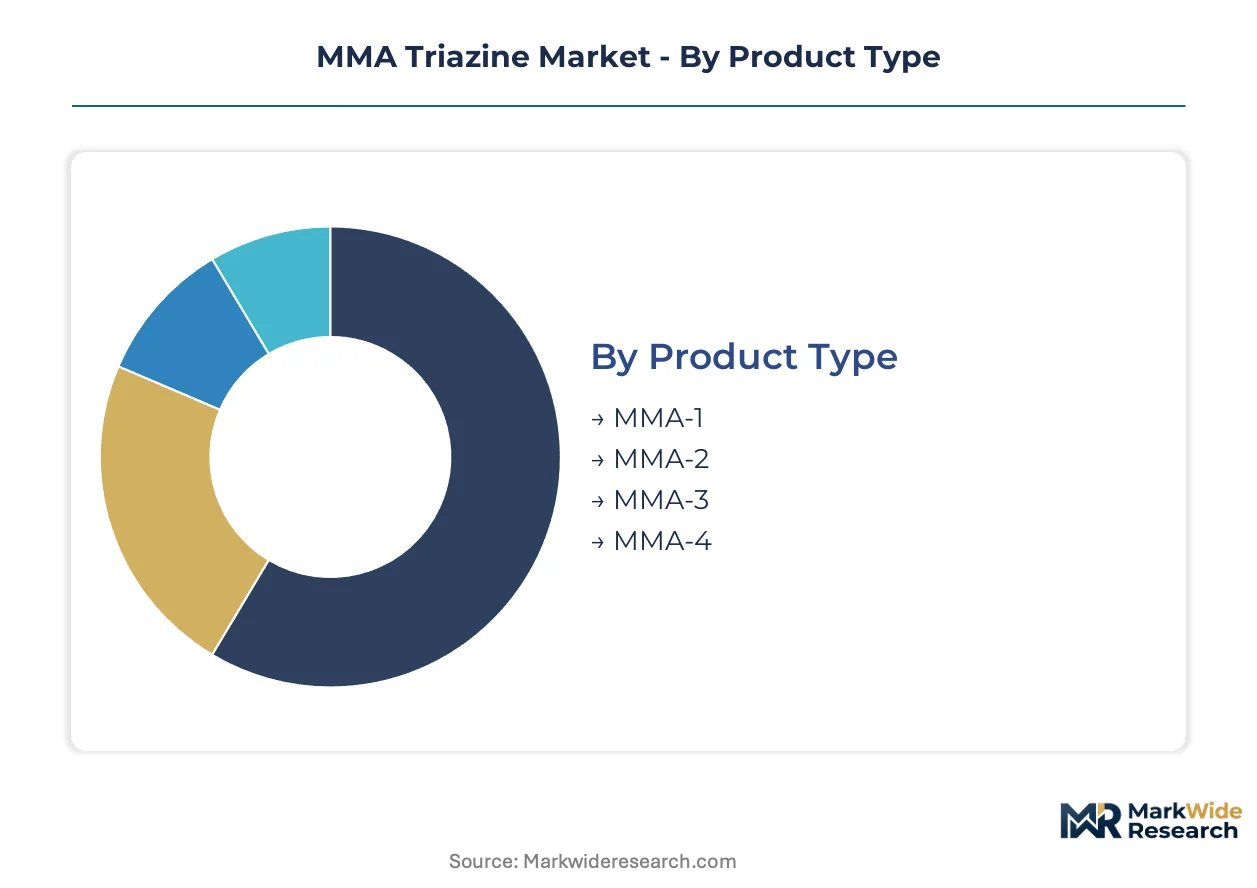
MMA triazine segmentation reveals how substitution pressures and regulatory thresholds fragment commercial opportunity across purity grades, delivery formats, and end-use specifications. Understanding these divides exposes where margin pools concentrate versus where commodity competition erodes returns.
Product Type:
Substitution pressure from regenerable amine scavengers falls hardest on lower-purity grades, while pharmaceutical and food-contact specifications build defensive moats through certification burden.
- MMA-1:Industrial-grade oligomer with elevated residual formaldehyde content, synthesized via standard condensation protocols. Demand concentrates in bulk oilfield chemical blending along the US Gulf Coast, where cost sensitivity outweighs emission constraints in non-REACh jurisdictions.
- MMA-2:Refined grade with intermediate formaldehyde stripping, balancing scavenging capacity against regulatory thresholds. European downstream operators under ECHA substance evaluation protocols now favor this tier for industrial applications requiring documented compliance without pharmaceutical-grade overhead.
- MMA-3:High-purity variant meeting FDA excipient standards for residual formaldehyde, produced through dedicated reactor trains with extended stripping cycles. Pharmaceutical formulators in New Jersey and North Carolina chemical corridors drive specification lock-in as FDA scrutiny intensifies on melamine-derived inputs.
- MMA-4:Ultra-pure grade with formaldehyde content below detectable thresholds, commanding premium positioning in parenteral drug applications and food-contact polymers. Synthesis requires batch-controlled pH management and specialized analytical certification that excludes commodity producers.
MMA-1 retains volume leadership; MMA-4 holds the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive process chemicals from specification-driven life science segments, with automotive and agriculture occupying intermediate positions defined by volume scale and performance thresholds.
- Chemicals:Oilfield H2S scavenging dominates tonnage, with deepwater drilling contractors in Brazil's pre-salt basins and the US Gulf of Mexico locking in recurring demand through integrated service contracts. EPA formaldehyde emission caps constrain high-concentration formulations, advantaging suppliers with backward integration into low-emission synthesis.
- Pharmaceuticals:Excipient-grade applications in tablet binders and controlled-release matrices require MMA-3 and MMA-4 certification. FDA Office of Pharmaceutical Quality oversight on residual formaldehyde creates qualification barriers that specialist chemical divisions of integrated oilfield service companies exploit through captive R&D investment.
- Agriculture:Slow-release nitrogen carriers and pesticide formulation aids utilize MMA-1 and MMA-2 grades. Brazilian soybean belt demand fluctuates with seasonal planting intensity and import tariff exposure on Chinese melamine feedstock.
- Automotive:Flame-retardant additives in interior polymers and underhood components specify MMA-2 for thermal stability. German OEM procurement standards under EU Green Deal sustainability criteria are shifting preference toward bio-based formaldehyde feedstock pathways.
Chemicals applications retain volume leadership; pharmaceuticals holds the steepest expansion curve.
Form:
Volume concentration in liquid formats reflects infrastructure legacy, while logistics-constrained geographies are forcing adaptation toward solid-state alternatives that trade injection performance for supply chain reach.
- Liquid:Dominant format for high-pressure wellbore injection, with continuous metering systems standard on offshore platforms. US Permian Basin and Bakken field operators maintain liquid chemical infrastructure that locks in format preference despite higher transport costs per active unit.
- Powder:Addresses remote logistics constraints in North Dakota and West Texas fields lacking liquid chemical terminals. Reconstitution at wellsite requires batch mixing equipment, creating equipment rental revenue streams for chemical distributors.
- Granular:Slow-dissolution format for agricultural soil amendment and controlled-release applications. Brazilian fertilizer blenders favor this form for mechanical spreading compatibility with existing equipment fleets.
- Emulsion:Water-dispersed systems for textile finishing and paper coating, where uniform film formation demands sub-micron particle distribution. Japanese textile chemical formulators in Osaka-Tokyo industrial corridors specify emulsion stability under shear conditions.
Liquid retains volume leadership; powder holds the steepest expansion curve.
End User:
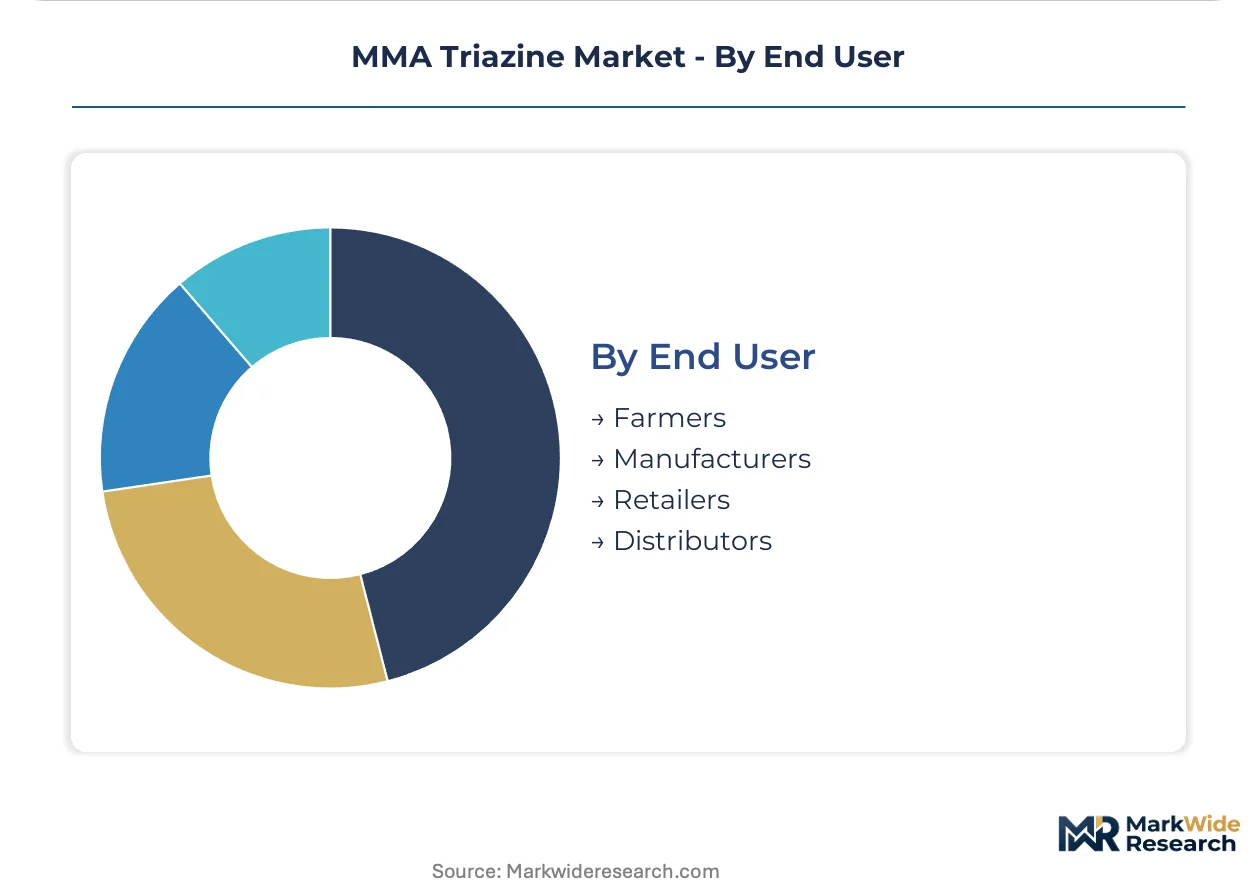
Customer type segmentation exposes bifurcation between integrated operators internalizing blending capability and independent explorers dependent on third-party formulators, with distribution channels capturing margin in fragmented demand pockets.
- Manufacturers:Integrated oilfield service companies and pharmaceutical chemical producers with captive synthesis capacity. Baker Hughes and similar operators internalize MMA triazine blending to secure supply continuity for drilling services divisions, removing volume from merchant markets.
- Distributors:European chemical distributors under REACH Article 33 disclosure mandates are consolidating supplier panels to reduce compliance audit burden. ECHA registration renewal deadlines favor incumbent registrants with complete Annex XV dossiers.
- Farmers:Direct procurement remains minimal; Brazilian cooperatives and US Midwest grain operations access MMA triazine through fertilizer blenders as nitrogen carrier components rather than standalone purchases.
- Retailers:Limited role given industrial specification requirements; agricultural supply cooperatives in Iowa and Illinois represent the primary retail-adjacent channel for soil amendment applications.
Manufacturers retain volume leadership; distributors holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH Article 33 disclosure mandates and EPA formaldehyde emission thresholds are redrawing procurement geography for MMA triazine suppliers, with compliance-advantaged registrants capturing volume in regulated jurisdictions while feedstock-integrated producers defend position in cost-sensitive basins.
United States
Deepwater drilling contractors in the Gulf of Mexico lock in recurring H2S scavenger demand through integrated service contracts with Baker Hughes and similar operators. EPA Office of Chemical Safety and Pollution Prevention oversight constrains residual formaldehyde thresholds, advantaging suppliers with backward integration into low-emission synthesis routes. The Houston-Baytown petrochemical corridor concentrates blending capacity, with captive consumption clusters forming around offshore production platforms.
Germany
Automotive OEM procurement standards under EU Green Deal sustainability criteria shift preference toward bio-based formaldehyde feedstock pathways for flame-retardant polymer applications. ECHA substance evaluation protocols explicitly target formaldehyde release categories in triazine derivative classifications. The Rhine-Ruhr industrial region hosts specialty chemical divisions with dedicated reactor trains for pharmaceutical-grade MMA-3 and MMA-4 synthesis.
Brazil
Pre-salt basin offshore projects require continuous H2S scavenger injection, creating recurring chemical demand from integrated service providers. ANVISA pharmaceutical regulations and evolving environmental licensing for oilfield chemicals shape import requirements for excipient-grade variants. São Paulo state chemical distributors consolidate supplier panels to reduce compliance audit burden ahead of ECHA-aligned regulatory convergence.
China
Melamine feedstock supply fluctuates with industrial policy on urea-based chemical production, squeezing margin predictability for non-integrated formulators across Asia-Pacific. MEE environmental standards on formaldehyde emissions tighten synthesis protocols for export-oriented producers. The Yangtze River Delta concentrates melamine-formaldehyde resin capacity, with Shandong Peninsula suppliers serving merchant MMA triazine markets.
Saudi Arabia
Aramco drilling services divisions internalize chemical blending to secure supply continuity for sour gas production in the Ghawar and Safaniya fields. SFDA pharmaceutical regulations create qualification barriers for excipient-grade imports, favoring pre-registered suppliers with complete technical dossiers. The Eastern Province industrial cities of Jubail and Yanbu host downstream formulation capacity tied to offshore Arabian Gulf production platforms.
MMA Triazine Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive amine chemistry expertise and oilfield service companies internalizing blending capability. Three archetypes dominate: melamine-formaldehyde specialists with backward integration into feedstock supply, diversified specialty chemical divisions leveraging R&D intensity in condensation process optimization, and integrated energy service providers capturing demand through drilling operations captive consumption. Competitive moves concentrate on REACH dossier completion ahead of 2025-2027 renewal deadlines and geographic expansion into Brazilian pre-salt and US Gulf Coast deepwater corridors.
Within the integrated chemical conglomerate tier, Hexion and Evonik Industries exemplify archetypes defined by precursor integration and specialty amine chemistry depth respectively. BASF SE occupies a position spanning both industrial-grade scavenger supply and pharmaceutical-grade certification channels. Baker Hughes Company anchors the energy-service-integrated segment, with captive demand from drilling services divisions removing volume from merchant markets. Eastman Chemical Company and Huntsman Corporation sit within the diversified specialty chemical tier, with portfolio breadth supporting cross-selling into automotive and pharmaceutical end-uses.
| Leading Market Players |
|---|
| Hexion |
| Eastman Chemical Company |
| Evonik Industries |
| Arkema S.A. |
| Baker Hughes Company |
| BASF SE |
| Stepan |
| Huntsman Corporation |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day melamine inventory positions at Gulf Coast blenders concentrate pricing power among backward-integrated suppliers while exposing non-integrated formulators to Chinese urea policy volatility. This inventory dynamic locks procurement flexibility to feedstock geography and amplifies margin compression during formaldehyde emission compliance cycles.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade MMA-4 and industrial MMA-1 tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA excipient qualification overhead versus bulk oilfield chemical blending. Cost compression in MMA-1 is intensifying because Brazilian pre-salt contractors negotiate volume offtakes with integrated service providers. Independent exploration companies in North Dakota Bakken fields show highest price sensitivity; pharmaceutical formulators in New Jersey chemical corridors demonstrate lowest.
Supply Chain Analysis
Just-in-time liquid delivery dominates offshore platform procurement while strategic stockpiling of powder formats addresses Permian Basin infrastructure gaps. Manufacturing concentrates in China, Germany, and the United States. Production draws from melamine, formaldehyde, and amine precursor inputs. Single-source vulnerability in Chinese melamine supply creates exposure to urea-based industrial policy shifts. Distribution runs through integrated oilfield service companies and REACH-compliant European chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deepwater drilling intensity in Brazil and the US Gulf Coast signals early-cycle expansion as hydrogen sulfide scavenger demand locks into recurring service contracts. REACH registration renewal timelines compress import flexibility, advantaging pre-registered suppliers with complete dossier compliance.
For Market Incumbents: Compound defensive positioning through backward integration into melamine supply chains and dedicated reactor trains for MMA-3 pharmaceutical certification. Monoethanolamine substitution in gas processing applications threatens volume in downstream segments; capacity addition in the Rhine-Ruhr region secures ECHA-advantaged supply to European automotive OEMs.
For New Entrants and Emerging Players: Differentiate on bio-based formaldehyde feedstock pathways aligned with EU Green Deal sustainability criteria. Powder formulation supply to logistics-constrained North Dakota Bakken fields represents the most penetrable white space. Go-to-market through equipment rental partnerships for wellsite reconstitution services bypasses liquid infrastructure deficits.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because REACH Article 33 disclosure mandates and EPA formaldehyde thresholds permanently elevate barriers to non-dossier suppliers. Target specialty chemical divisions with existing Annex XV registrations and captive R&D in condensation process optimization. The signal to watch is ECHA substance evaluation protocol expansion to additional triazine derivative classifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Hexion's formaldehyde and amine precursor control sustains cost discipline across North American supply chains. |
| Pharmaceutical-Grade Certification | FDA excipient qualification for MMA-3 and MMA-4 variants builds defensive moats against commodity scavenger competition. |
| Long-term Supply Agreement | Deepwater drilling contractors in Brazil's pre-salt basins lock in recurring chemical demand through integrated service contracts. |
| Green Manufacturing Transition | Bio-based formaldehyde feedstock pathways align with EU Green Deal preferential procurement standards for low-carbon intensity scavengers. |
| Joint Venture | European chemical distributors consolidate supplier panels to reduce REACH compliance audit burden ahead of renewal deadlines. |
Methodological Framework
Initial hypotheses were tested against primary input from oilfield chemical procurement managers, specialty amine R&D directors, pharmaceutical excipient qualification leads, and REACH compliance officers and refined through secondary validation. Sources included customs and trade data, ECHA registration dossiers, SEC 10-K filings from integrated chemical conglomerates, and ACC sector reports. Bottom-up volume modeling across purity grades and delivery formats triangulated with top-down market sizing from feedstock capacity analysis.
Variance decomposition across the projection horizon isolates drivers by segmentation dimension: product grade tier, end-use application, physical form, and regional regulatory cluster. CAGRs were derived from installed base expansion in deepwater drilling, substitution elasticity estimates for chlorine-generating scavenger alternatives, and pharmaceutical excipient penetration curves. Industry-specific inputs captured EPA formaldehyde threshold evolution and ECHA substance evaluation protocol scope.
The analysis sits within stated boundaries; outcomes outside sustained offshore capital expenditure cycles or REACH enforcement continuity would require recalibration. Forecasts reflect assumptions on melamine feedstock price stability and formaldehyde emission regulatory trajectory. Revision becomes warranted when Chinese urea industrial policy crosses volatility thresholds or when monoethanolamine regenerable scavenger cost curves shift competitive substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Preservative Blends Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
North America Disinfectants and Cleaning Agents Market
Disinfectants and Preservatives
Sterilants Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
UK Hypochlorous Acid Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Global Fumigation Products Market
Disinfectants and Preservatives
Low-Temperature Sterilization Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Microbial Control Chemical Market