
 Ceramic Travel Mug Market | 2026-2036
Ceramic Travel Mug Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Travel Mug Market Insights
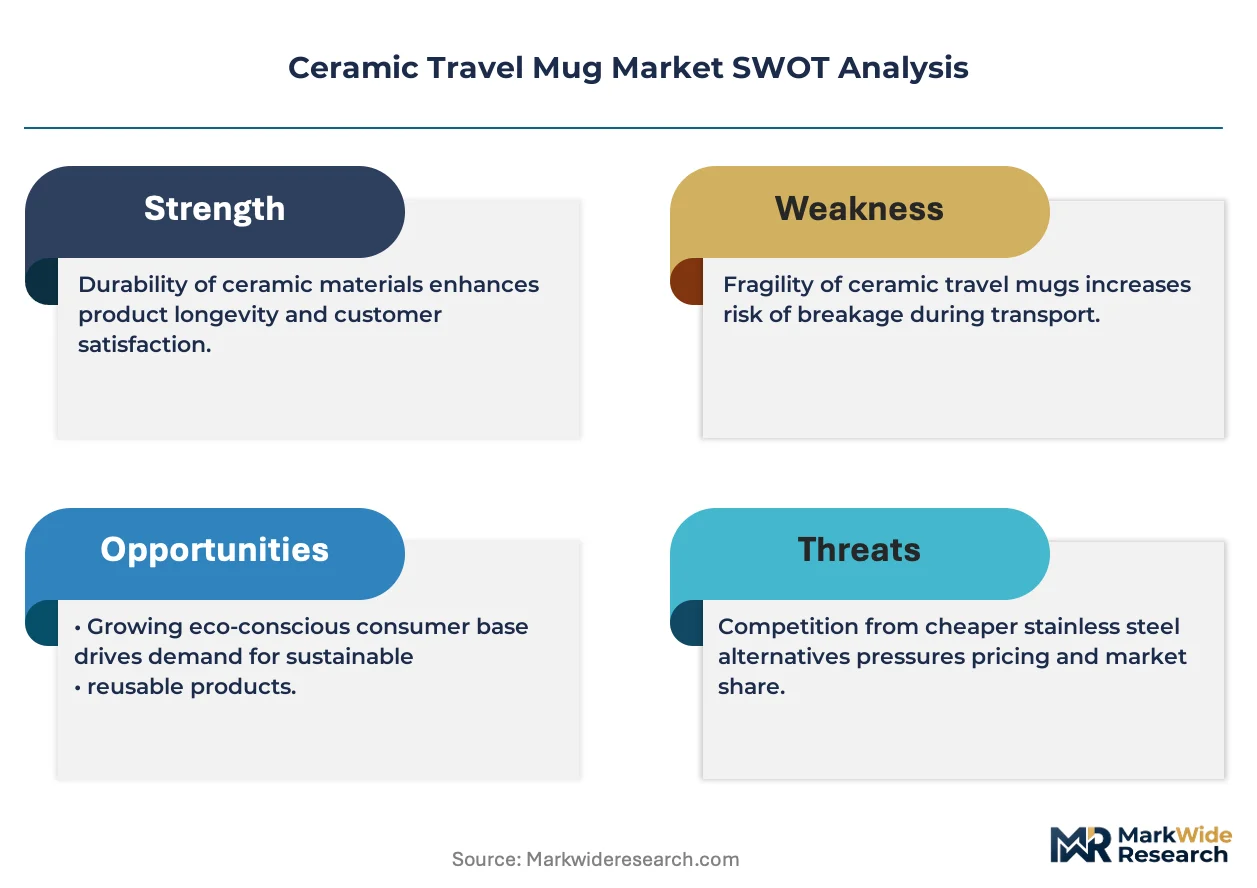
A capital-intensity divergence between vacuum-insulation specialists and commodity ceramic producers is unwinding traditional competitive boundaries. YETI leverages its premium thermal engineering heritage to command pricing power in the insulated ceramic sub-category. Zojirushi sustains manufacturing depth through precision vacuum-sealing capabilities imported from its domestic appliance operations. Ello Products competes on design-forward aesthetics targeting gift-channel and corporate-supplier segments with lower capital barriers to entry.
A ceramic travel mug comprises a fired-clay vessel, typically glazed with silica-based coatings, designed for portable beverage consumption with thermal retention properties ranging from basic single-wall conduction to advanced double-wall vacuum construction. The 450 ml and 550 ml capacity bands anchor volume demand among commuter and office-professional end users, where portability constraints intersect with daily caffeine consumption norms. Insulated ceramic and double-wall product types capture the fastest expansion as consumers trade up from basic single-wall alternatives, while matte finish and hand-painted variants concentrate margin pools in specialty-store and gift-shop channels.
FDA food-contact material standards govern ceramic glaze safety and lead-cadmium leaching thresholds in the United States, while the EU Green Deal and REACH chemical regulations impose parallel compliance burdens on European imports. California's Proposition 65 labeling mandates create additional state-level friction for non-compliant suppliers entering the US market. Stakeholders must monitor evolving extended-producer-responsibility frameworks and decide whether to absorb compliance costs or cede price-sensitive segments to unbranded imports.
Market Dynamics
The EU Green Deal's single-use plastics directives are forcing material substitution decisions across the ceramic travel mug value chain, as importers absorb compliance costs or exit price-sensitive segments entirely.
Growth Catalysts
- REACH chemical regulations:European importers must certify glaze compositions against cadmium and lead leaching thresholds, accelerating demand for pre-certified ceramic suppliers with laboratory documentation.
- Office-professional segment:Commuter caffeine consumption norms in Germany and France sustain 450-550 ml capacity bands as employers subsidize reusable vessel programs.
- Vacuum-insulation technology:Double-wall construction methods imported from appliance manufacturing are compressing thermal performance gaps between ceramic and stainless-steel alternatives.
Market Restraints
- Feldspar and kaolin cost volatility:Ceramic raw material prices fluctuate with energy-intensive mining operations concentrated in China and Turkey, squeezing margin pools for commodity producers.
- California Proposition 65:State-level labeling mandates for lead-cadmium warnings create friction for European and Asian suppliers lacking US legal infrastructure.
- Stainless-steel substitution:Metal alternatives with superior drop resistance capture outdoor and construction-worker end uses where ceramic fragility is prohibitive.
Strategic Opportunities
- Corporate gifting channel:Design-forward aesthetics with custom glaze finishes command premium positioning in employer-sponsored sustainability programs across Germany.
- Extended producer responsibility frameworks:EU member states are piloting take-back schemes that favor domestic ceramic producers with established recycling partnerships.
- Smart-mug convergence:Temperature-sensing electronics integrated into vacuum-insulated bases create a new premium tier between basic ceramic and connected appliances.
Industry Challenges
- Vacuum-sealing technician scarcity:Precision assembly skills imported from domestic appliance manufacturing remain concentrated in Japan and South Korea, limiting European production scale-up.
- Glaze certification timelines:FDA food-contact material approvals and EU food-safety testing cycles extend 12-18 months, delaying product launches for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Travel Mug Market |
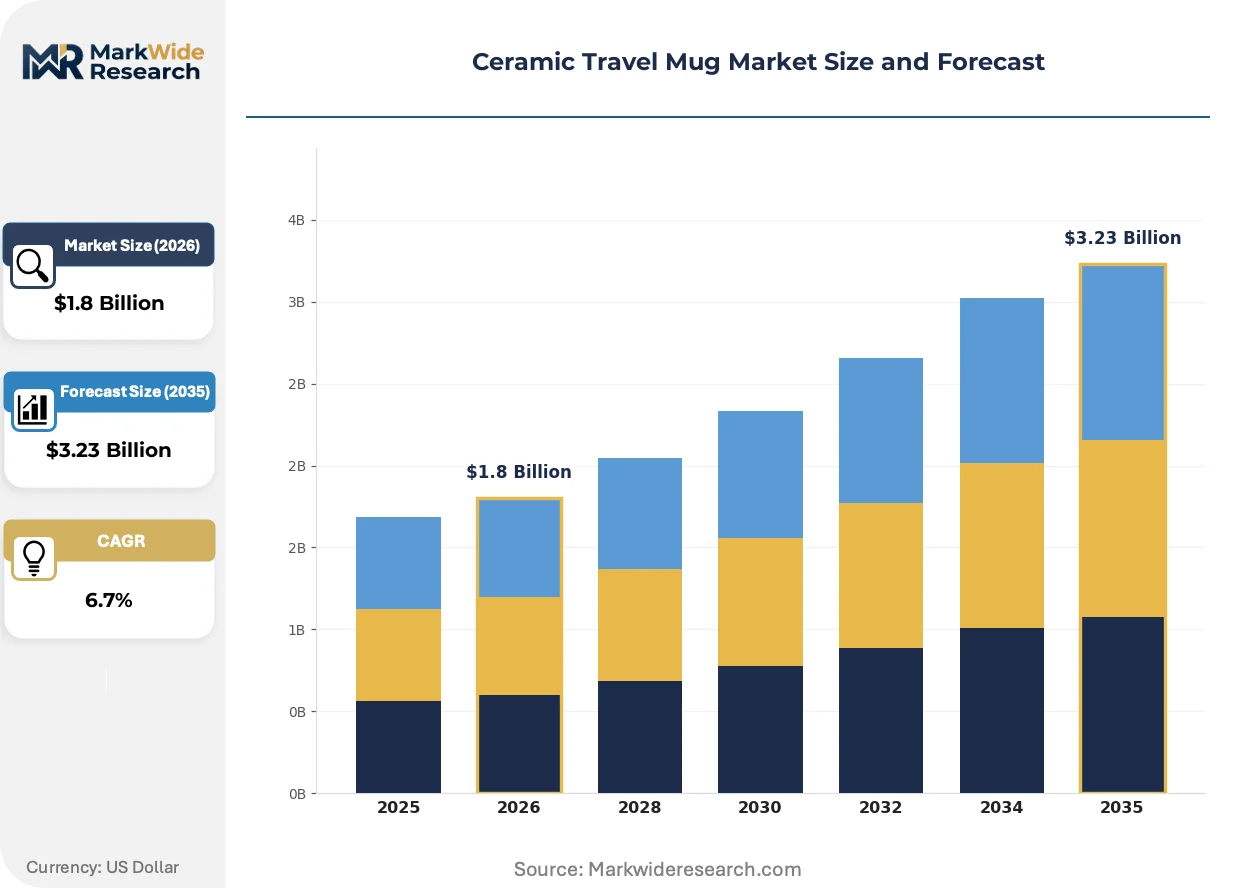
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic Ceramic, Insulated Ceramic, Double Wall, Hand-painted, Matte Finish, Glossy Finish Capacity: 250 ml, 350 ml, 450 ml, 550 ml, 700 ml Distribution Channel: Online Retailers, Specialty Stores, Department Stores, Gift Shops, Corporate Suppliers End User: Office Professionals, Students, Outdoor Enthusiasts, Commuters, Hospitality Providers |
| Companies Covered | Contigo, Thermos, YETI, Hydro Flask, Stanley, Zojirushi, S’well, Ello Products, Ember Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Travel Mug Market Trends and Innovations
Thermal engineering capabilities are migrating across material categories, while regulatory compliance costs reshape competitive boundaries between insulated and basic ceramic segments.
Double-wall vacuum construction is bifurcating the product landscape into thermal-performance tiers. Office professionals in Germany and France trade up from single-wall conduction models, compressing margin pools for commodity glaze producers while rewarding vacuum-sealing specialists with pricing power in the insulated sub-category.
REACH chemical regulations and the EU Green Deal are tightening glaze composition standards across member states. Importers face laboratory testing burdens for cadmium and lead leaching thresholds, with California's Proposition 65 adding parallel state-level friction that favors suppliers with established US legal infrastructure over new Asian entrants.
Gift-channel buyers now demand matte-finish and hand-painted variants with corporate customization capabilities. Specialty stores in urban Germany are displacing basic gloss-finish inventory, as employer-sponsored sustainability programs seek distinctive aesthetics for employee onboarding kits and client retention campaigns.
Ceramic Travel Mug Market Segmentation
Channel dynamics in ceramic travel mugs diverge sharply between impulse-driven gift purchases and planned corporate procurement. Material technology and capacity specifications determine which segments flow through premium specialty outlets versus mass online retail.
Product Type:
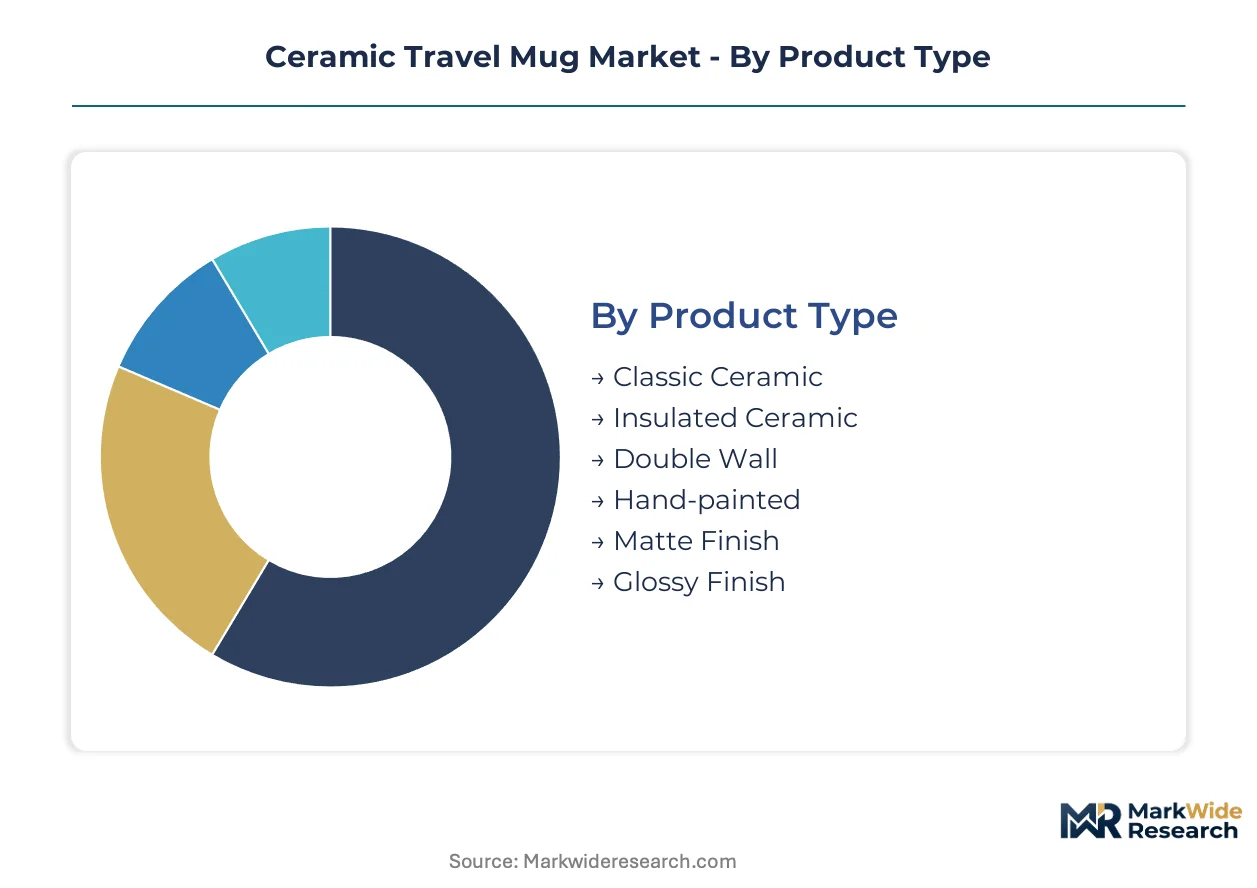
Channel-mix patterns split between thermal-performance tiers that command specialty-store placement and aesthetic variants that dominate gift-shop turnover. Vacuum-insulated products concentrate in premium outdoor and office channels, while hand-painted and finish-driven segments rotate through corporate gifting and seasonal retail.
- Insulated Ceramic:Double-wall vacuum construction with silica-based glaze coatings achieves thermal retention parity with metal alternatives. Demand concentrates among German office professionals where employer sustainability subsidies support premium price points, though vacuum-sealing technician scarcity limits European production scale.
- Matte Finish:Non-reflective glaze surfaces require specialized firing protocols that elevate unit costs 15-25% above glossy equivalents. Urban specialty stores in Germany and France are displacing basic gloss inventory as corporate onboarding programs seek distinctive aesthetics for employee retention campaigns.
- Classic Ceramic:Single-wall fired-clay construction with standard glaze application serves price-sensitive commuter segments through mass-market online channels.
- Double Wall:Air-gap insulation without vacuum sealing occupies a mid-tier thermal performance band, popular among students and casual commuters.
- Hand-painted:Artisanal glaze application creates one-of-a-kind surface patterns that command gift-shop premiums in tourist corridors and museum retail.
- Glossy Finish:High-sheen silica coatings dominate volume production for promotional and entry-level corporate gifting where unit cost minimization overrides aesthetic differentiation.
Classic Ceramic dominates installed base. Insulated Ceramic is where expansion concentrates.
Capacity:
Cost-tier stratification aligns with consumption rituals — smaller formats serve espresso culture and aviation retail, while larger vessels target all-day hydration and outdoor endurance activities.
- 450 ml:The commuter standard balances portability against single-serve caffeine norms, capturing the densest volume concentration across German and French office corridors.
- 550 ml:Expanded thermal mass suits extended meeting schedules and regional rail journeys, gaining share fastest among hybrid workers splitting time between home and corporate campuses.
- 250 ml:Espresso-dedicated format rotates through airport retail and boutique coffee equipment channels.
- 350 ml:Compact commuter option favored by cyclists and public transit users facing space constraints.
- 700 ml:All-day hydration format targets outdoor enthusiasts and construction-site workers despite ceramic fragility trade-offs.
450 ml commands the largest production runs. 550 ml is climbing the fastest as work patterns shift.
Distribution Channel:
Customer-type targeting separates planned procurement with customization requirements from impulse purchases driven by shelf presence and seasonal merchandising.
- Corporate Suppliers:B2B volume concentration with logo imprinting and bulk glaze customization, anchored by German employer sustainability mandates.
- Specialty Stores:Curated assortment of vacuum-insulated and design-forward variants with educated staff supporting thermal-performance claims.
- Online Retailers:Price-transparent environment where review velocity and search placement determine winner-take-most dynamics.
- Gift Shops:Seasonal velocity driven by tourist foot traffic and occasion-based purchasing with limited repeat visitation.
- Department Stores:Mid-tier aggregation serving gift-givers seeking brand recognition without specialty-store price premiums.
Online Retailers dominate transaction volume. Corporate Suppliers is where margin expansion concentrates.
End User:
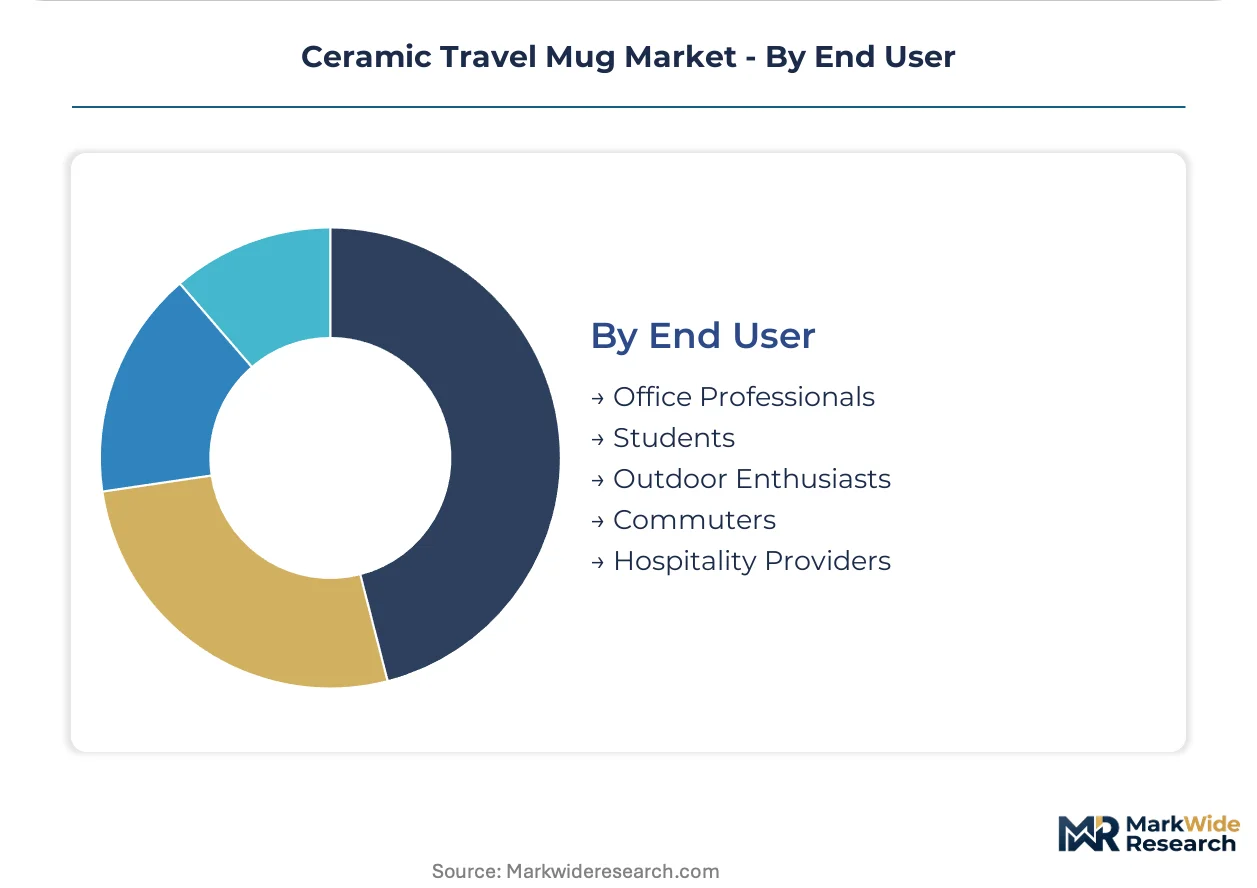
Application-specific requirements fragment demand across thermal-performance needs, durability tolerance, and aesthetic customization intensity.
- Office Professionals:Daily-use intensity with desktop thermal retention requirements and employer-subsidized replacement cycles.
- Commuters:Transit-optimized capacity preferences with spill-resistant lid specifications and vehicle-cupholder compatibility constraints.
- Students:Price elasticity dominates with campus bookstore distribution and semester-cycle replacement patterns.
- Outdoor Enthusiasts:Drop-resistance requirements push demand toward metal alternatives, limiting ceramic penetration to car-camping and base-camp scenarios.
- Hospitality Providers:Branded room-amenity and lobby-retail applications with volume procurement and logo-integration requirements.
Office Professionals anchor revenue concentration. Commuters is where product innovation cycles concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb sustainability premiums with minimal price elasticity, while price-sensitive segments in Southern Europe and emerging Asian markets resist comparable cost markups for certified ceramic vessels.
Germany
Employer-subsidized reusable vessel programs sustain dense office-corridor demand across Frankfurt, Munich, and Berlin. The EU Green Deal's extended producer responsibility frameworks favor domestic producers with established recycling partnerships. Vacuum-insulation specialists cluster in Bavaria's precision-manufacturing belt near Nuremberg.
France
Commuter rail culture and espresso consumption rituals anchor 450 ml format preferences throughout the Île-de-France region. ECHA REACH compliance mandates accelerate laboratory documentation requirements for glaze importers. Lyon-based specialty retailers curate design-forward assortments targeting corporate sustainability procurement.
United States
California Proposition 65 labeling mandates create state-level friction that favors suppliers with established US legal infrastructure over Asian entrants. FDA food-contact material standards govern ceramic glaze safety thresholds nationwide. Pacific Northwest urban clusters drive insulated ceramic adoption among remote-worker commuters.
Japan
Precision vacuum-sealing capabilities imported from domestic appliance manufacturing sustain manufacturing depth for thermal-performance tiers. METI energy-efficiency guidelines influence consumer preference toward double-wall construction. Osaka-Nagoya industrial corridor concentrates technician expertise for ceramic-metal hybrid assembly.
China
Feldspar and kaolin mining operations concentrated in Fujian and Jiangxi provinces expose commodity producers to energy-intensive cost volatility. SAMR national standards for food-contact materials parallel FDA and EU safety thresholds. Yangtze River Delta ceramic clusters pivot toward pre-certified export production for German and US buyers.
Ceramic Travel Mug Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where vacuum-insulation specialists command premium positioning against commodity glaze producers. The vendor base separates into three strategic archetypes: thermal-engineering heritage players leveraging appliance manufacturing capabilities, design-forward specialists targeting gift-channel aesthetics, and scale-driven fabricators serving promotional and entry-level corporate procurement. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through pre-certified supplier networks.
Within the thermal-engineering tier, YETI and Zojirushi exemplify archetypes that translate appliance-sector capabilities into ceramic-adjacent premium positioning. Ello Products occupies a design-specialist position targeting lower-capital-barrier segments. These three anchors illustrate how competitive boundaries unwind between vacuum-insulation heritage and commodity ceramic production.
| Leading Market Players |
|---|
| Contigo |
| Thermos |
| YETI |
| Hydro Flask |
| Stanley |
| Zojirushi |
| S’well |
| Ello Products |
| Ember Technologies |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German corporate buyers and pre-certified ceramic suppliers lock in feldspar access and glaze certification visibility, insulating premium-tier producers from spot-market kaolin volatility while compressing margins for commodity single-wall competitors.
Pricing Analysis
After-sales revenue from replacement lids and custom glaze refresh programs drives lifetime value for vacuum-insulation specialists. Three-tier pricing structure across premium insulated, standard double-wall, and economy single-wall levels stratifies by thermal performance certification and REACH documentation depth. Cost compression in the glossy-finish commodity tier intensifies because Yangtze River Delta fabricators absorb feldspar price swings to maintain volume share. Students and price-sensitive commuters exhibit highest elasticity, while German office professionals subsidized through employer sustainability programs show minimal sensitivity to 15-25% premiums for matte-finish variants.
Supply Chain Analysis
Inventory lead times for FDA-compliant glaze formulations stretch 12-18 months, forcing importers to pre-position certified stock ahead of seasonal corporate procurement cycles. Raw material sourcing draws from Fujian and Jiangxi provinces in China for feldspar and kaolin, with Bavarian precision-manufacturing clusters supplying vacuum-sealing technician expertise. Single-source vulnerability concentrates in Japanese and South Korean vacuum-assembly equipment, where METI-influenced production capacity limits European scale-up. Distribution runs through corporate supplier networks for B2B volume, specialty stores for premium thermal-performance tiers, and mass online retail for price-transparent commodity turnover.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-mug temperature-sensing electronics are creating a platform-economics inflection where vacuum-insulated ceramic bases interoperate with connected appliance ecosystems, rewarding first movers who establish data-layer partnerships with office coffee infrastructure providers.
For Market Incumbents: Compound thermal-engineering heritage through backward integration into captive feldspar sourcing from Turkish mining partnerships, while accelerating FDA pre-certification pipelines to defend against Asian entrants exploiting Proposition 65 compliance gaps. Vacuum-sealing technician scarcity in Europe represents the critical capability chokepoint requiring apprenticeship program investment in Bavaria. For New Entrants and Emerging Players: Lead with matte-finish customization capabilities targeting German corporate gifting procurement, where employer-sponsored sustainability programs seek distinctive onboarding aesthetics with lower capital barriers than vacuum-insulation scale-up. The 550 ml hybrid-worker segment offers fastest penetration for design-forward specialists lacking appliance-manufacturing heritage. For Investors and Strategic Acquirers: Pre-certified mid-cap ceramic fabricators with established REACH documentation and US legal infrastructure represent the highest-conviction acquisition archetype for rollup strategies. Long-term viability hinges on regulatory compliance moats widening against unbranded imports, with EU extended producer responsibility framework pilot adoption serving as the inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Insulation Scale-Up | Bavarian technician apprenticeship programs address scarcity limiting European production expansion. |
| REACH Pre-Certification Investment | Laboratory documentation moats displace Asian competitors lacking EU legal infrastructure. |
| Corporate Gifting Channel Expansion | German employer sustainability mandates drive premium positioning for custom glaze programs. |
| Smart-Mug Electronics Integration | Temperature-sensing base modules create premium tier between basic ceramic and connected appliances. |
| Feldspar Backward Integration | Turkish mining partnerships insulate margin pools from Yangtze River Delta cost volatility. |
Research Methodology
A spread of perspectives from ceramic plant managers, corporate procurement leads at German employers, specialty store category buyers, and vacuum-sealing equipment engineers converged on the working assumptions driving segmentation splits. Secondary validation drew from EU ECHA REACH registration databases, FDA food-contact material guidance documents, SAMR national standards filings, and customs trade flow records for feldspar and kaolin. Bottom-up capacity assessments across Yangtze River Delta and Bavarian manufacturing clusters were triangulated against top-down demand modeling from commuter consumption norms and employer subsidy program adoption rates.
Segmentation dimensions modeled include thermal-performance tier, glaze finish type, capacity format, distribution channel, and end-user application across the projection horizon. CAGRs were derived from elasticity-adjusted price-volume relationships and substitution dynamics between ceramic and stainless-steel alternatives. Forecast inputs incorporated EU Green Deal implementation timelines for extended producer responsibility frameworks and METI energy-efficiency guideline adoption patterns influencing Japanese vacuum-insulation demand.
The analysis sits within stated boundaries; outcomes outside sustained employer subsidy program expansion or accelerated REACH enforcement would require recalibration. Forecasts reflect documented assumptions regarding raw material cost trajectories and regulatory compliance burden shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Nap Pod Market
Household Items
Integrated Smart Toilet Market
Household Items
Washing Machine Cleaner Market
Household Items
MENA POU Water Purifiers Market
Household Items
Mosquito Trap Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Tiki Torch Market
Household Items
Electric Tealight Candles Market
Household Items
Remote Control Holder Market
Household Items
Heated Towel Rail Market
Household Items
Electric Hedge Trimmer Market
Household Items
Mirror Holder Market
Household Items
Portable Steam Cleaners Market
Household Items
Electric Soap Dispenser Market
Household Items
Smart Spin Mop Market
Household Items
Hangers Market