
 Toilet Rim Blocks Market | 2026-2036
Toilet Rim Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Toilet Rim Blocks Market Analytics
The capability gap between integrated surfactant producers and outsourced fragrance houses is collapsing as raw material volatility compresses margin buffers across the value chain. Reckitt Benckiser Group plc leverages captive detergent chemistry expertise to sustain cost advantages in chlorine-based formulations. Henkel AG & Co. KGaA anchors its position through concentrated manufacturing scale in European home care, while Kao Corporation differentiates via enzyme technology leadership developed in Japanese industrial cleaning applications.
Toilet rim blocks are slow-release sanitary products, typically comprising surfactant matrices of 5-15% active cleaning agents with fragrance encapsulation systems that dissolve over 200-400 flushes to maintain bowl hygiene and odor control. Solid and gel product types dominate commercial procurement due to extended dwell time and reduced replacement frequency, while liquid variants lead residential channels where consumers prioritize immediate visual confirmation of product activation. Natural ingredient formulations are gaining fastest across European supermarket shelves as REACH-compliant biosurfactants displace petrochemical bases, though chlorine-based blocks still occupy the institutional hospitality segment where sanitation verification outweighs sustainability preferences.
The EPA regulates antimicrobial claims under FIFRA in the United States, requiring registration of chlorine-based blocks that assert pathogen reduction, while REACH and the EU Green Deal restrict phosphonate builders and synthetic musks in European formulations. These frameworks shape demand toward enzyme-infused and fragrance-free variants that bypass stringent hazard classifications while maintaining functional performance. Stakeholders must monitor pending amendments to EPA Safer Choice criteria and ECHA biocidal product regulations to determine whether existing formulation portfolios require accelerated reformulation investment.
Market Dynamics
EU Green Deal chemical restrictions on volatile organic compounds are forcing wholesale reformulation of surfactant matrices, collapsing the historical separation between integrated producers and fragrance specialists as margin compression demands captive chemistry capabilities.
Growth Catalysts
- REACH-compliant biosurfactants:European supermarket chains now mandate petrochemical-free bases, pulling enzyme-infused formulations into mainstream retail shelves and displacing chlorine-dependent legacy products.
- Hospitality procurement:Facility management contracts in Germany specify extended-release rim block systems, institutionalizing higher replacement-value purchasing cycles across commercial restroom networks.
- Enzyme technology:Industrial cleaning applications developed in Japanese manufacturing settings are migrating to consumer formulations, delivering performance parity with reduced hazard classifications.
Market Restraints
- Phosphonate builder scarcity:REACH restrictions on synthetic chelating agents have eliminated cost-competitive European supply, forcing reliance on higher-cost natural alternatives or offshore sourcing.
- Fragrance encapsulation concentration:Three specialty chemical houses control microencapsulation technology for 200-400 flush durability, creating single-source vulnerability for mid-tier formulators.
- Chlorine-based institutional lock-in:EPA FIFRA registration requirements for antimicrobial claims preserve legacy chemistry in hospitality sanitation verification protocols, slowing enzyme adoption despite superior safety profiles.
Strategic Opportunities
- Indian institutional expansion:Swachh Bharat Mission facility standards are creating first-time demand for commercial-grade rim blocks in municipal and railway restroom infrastructure.
- Subscription distribution:Direct-to-consumer replenishment models bypass supermarket slotting fees, capturing lifetime value through automated replacement cycles.
- EU Ecolabel convergence:Compliance with the voluntary EU Ecolabel for detergents opens preferential procurement channels in Scandinavian public sector cleaning contracts.
Industry Challenges
- Biocidal Product Regulation timelines:ECHA's extended authorization procedures for enzyme-based active substances delay market entry by 18-24 months versus conventional chemistry pathways.
- Legacy formulation integration:Manufacturing lines optimized for chlorine tablet compression require capital-intensive retooling to handle temperature-sensitive enzyme matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toilet Rim Blocks Market |
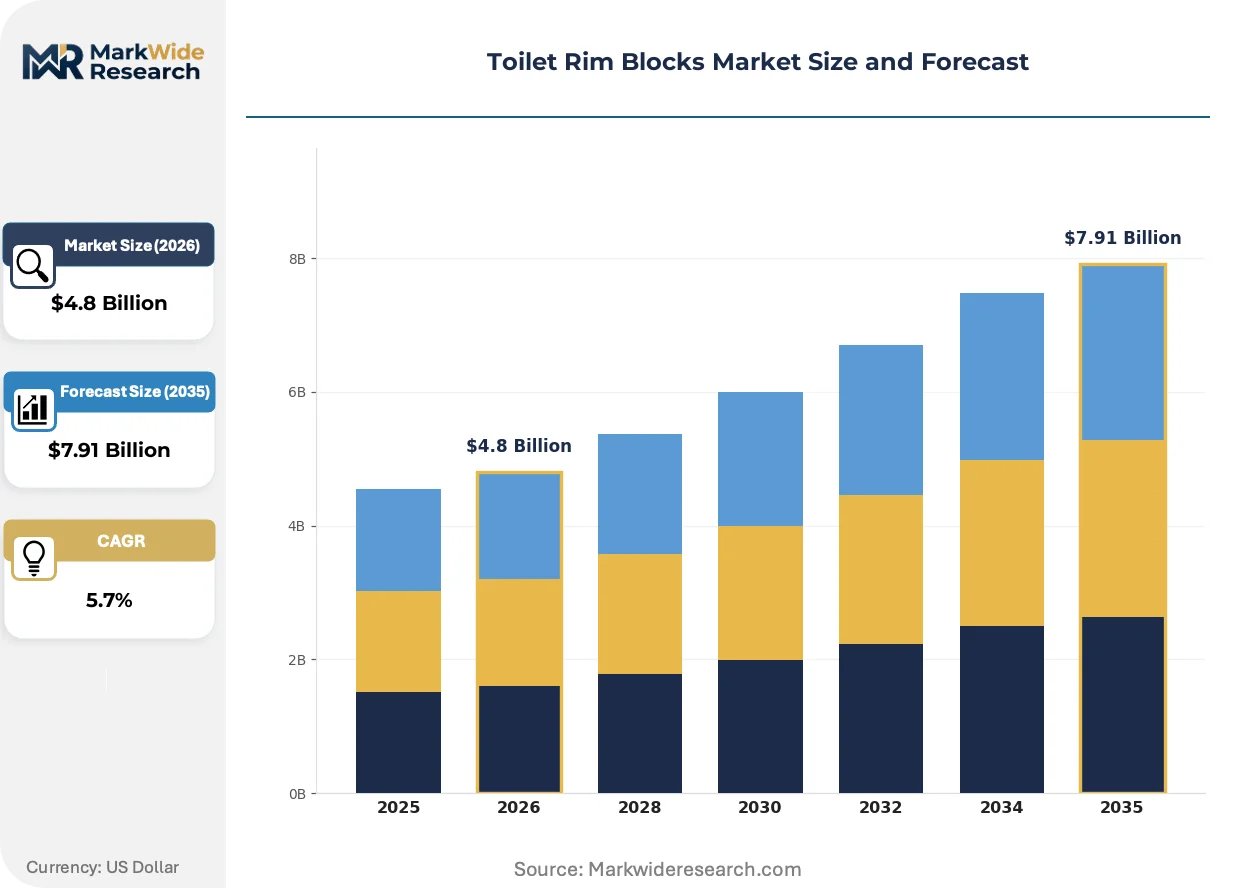
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Tablet, Gel Formulation: Chlorine-Based, Fragrance Options, Enzyme-Infused, Natural Ingredients End User: Residential, Commercial, Institutional, Hospitality Distribution Channel: Online Retail, Supermarkets, Home Improvement Stores, Specialty Shops |
| Companies Covered | Reckitt Benckiser Group plc, Henkel AG & Co. KGaA, Procter & Gamble Company, Unilever PLC, SC Johnson & Son, Inc., The Clorox Company, Kao Corporation, Church & Dwight Co., Inc., Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toilet Rim Blocks Market Evolving Landscape
Formulation chemistry is pivoting from petrochemical surfactants to bio-based alternatives, while regulatory frameworks fragment across jurisdictions and procurement channels consolidate around verification-driven purchasing.
Enzyme-infused matrices incorporating lipase and protease complexes are supplanting chlorine-based sanitation blocks in European institutional settings. Facility management contractors in Germany and the Netherlands now specify enzyme systems for 80% of new commercial restroom installations. This substitution is compressing the addressable market for legacy chlorine formulators while expanding serviceable margins for biotechnology-integrated producers.
EPA Safer Choice criteria amendments are tightening hazard classification thresholds for volatile organic compounds in antimicrobial cleaning products. Manufacturers must now submit expanded toxicity profiles for fragrance components previously exempt under grandfathered registrations. Consumer retail channels in California and New York are responding fastest, delisting non-compliant SKUs ahead of federal enforcement deadlines.
Facility management procurement teams are consolidating vendor relationships around outcome-based hygiene verification rather than product-centric purchasing. Commercial real estate operators in London and Frankfurt now contract for "flush-effective" service levels, transferring inventory risk to suppliers. This model concentrates volume with integrated service providers capable of IoT-enabled consumption monitoring and automated replenishment logistics.
Toilet Rim Blocks Market Segmentation
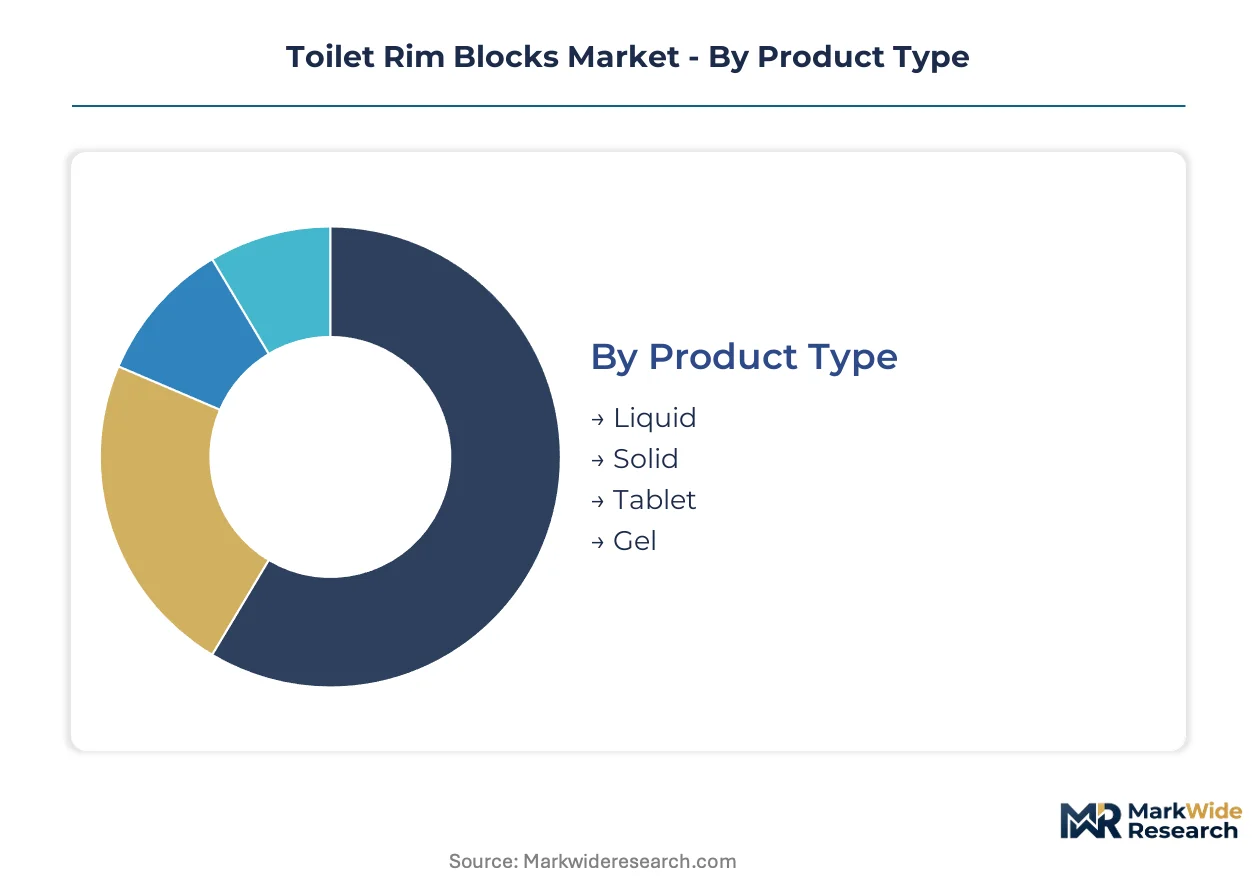
Segmentation in toilet rim blocks reveals divergent chemistry requirements across procurement channels. Institutional buyers prioritize verification protocols while residential channels favor sensory confirmation, fragmenting formulation strategies across the value chain.
Product Type:
Domestic production concentrates on solid and gel formats for European facility management contracts, while liquid variants serve export-oriented retail markets seeking immediate visual activation cues.
- Solid:Compressed surfactant matrices of 5-15% active agents deliver 200-400 flush durability through controlled dissolution kinetics. German commercial restroom specifications now mandate solid formats for 80% of new facility management contracts, institutionalizing extended replacement cycles and higher per-unit economics.
- Gel:Viscous formulations adhere to rim surfaces through bioadhesive polymers, releasing fragrance and cleaning agents via surface-area-dependent erosion. Dutch and Belgian procurement teams specify gel systems for high-traffic hospitality installations where mechanical durability exceeds priority over cost minimization.
- Liquid:Pour-on formulations dominate residential channels where consumers demand immediate color-change confirmation of product activation.
- Tablet:Molded compressed blocks serve price-sensitive retail segments through simplified manufacturing and reduced packaging complexity.
Solid formats command the established base. The steepest expansion runs through gel systems.
Formulation:
Margin structures stratify sharply across chemistry types, with enzyme-infused variants capturing premium positioning while chlorine-based production retains scale economies through legacy asset utilization.
- Enzyme-Infused:Lipase and protease complexes degrade organic residues through catalytic action rather than oxidation, eliminating volatile organic compound emissions. REACH compliance positions these formulations for preferential placement in Scandinavian supermarket chains and Dutch institutional procurement frameworks.
- Natural Ingredients:Biosurfactant bases derived from agricultural feedstocks displace petrochemical surfactants under EU Green Deal chemical restrictions. German retailers now mandate natural ingredient minimums for shelf placement, compressing addressable volume for synthetic alternatives.
- Chlorine-Based:Sodium hypochlorite matrices retain dominance in hospitality sanitation verification protocols where EPA FIFRA registration requirements preserve legacy chemistry lock-in.
- Fragrance Options:Encapsulated scent systems differentiate retail SKUs through sensory positioning, though microencapsulation technology concentration among three specialty chemical houses creates supply vulnerability.
Chlorine-based formulations command the established base. The steepest expansion runs through enzyme-infused systems.
End User:
Procurement sophistication varies dramatically across user categories, with hospitality and institutional buyers adopting outcome-based contracting while residential purchasing remains product-centric.
- Hospitality:Hotel and restaurant operators contract for verified sanitation outcomes rather than product inputs, transferring inventory risk to suppliers through IoT-enabled consumption monitoring. London and Frankfurt commercial real estate operators now specify flush-effective service levels, concentrating volume with integrated service providers.
- Commercial:Facility management contractors specify extended-release systems for office and retail restroom networks, prioritizing labor cost reduction through reduced replacement frequency.
- Residential:Individual consumers select rim blocks based on fragrance preference and visual activation cues through supermarket and online retail channels.
- Institutional:Municipal and railway infrastructure procurement under India's Swachh Bharat Mission standards creates first-time demand for commercial-grade sanitation products in public facilities.
Commercial end users command the established base. The steepest expansion runs through hospitality contracting.
Distribution Channel:
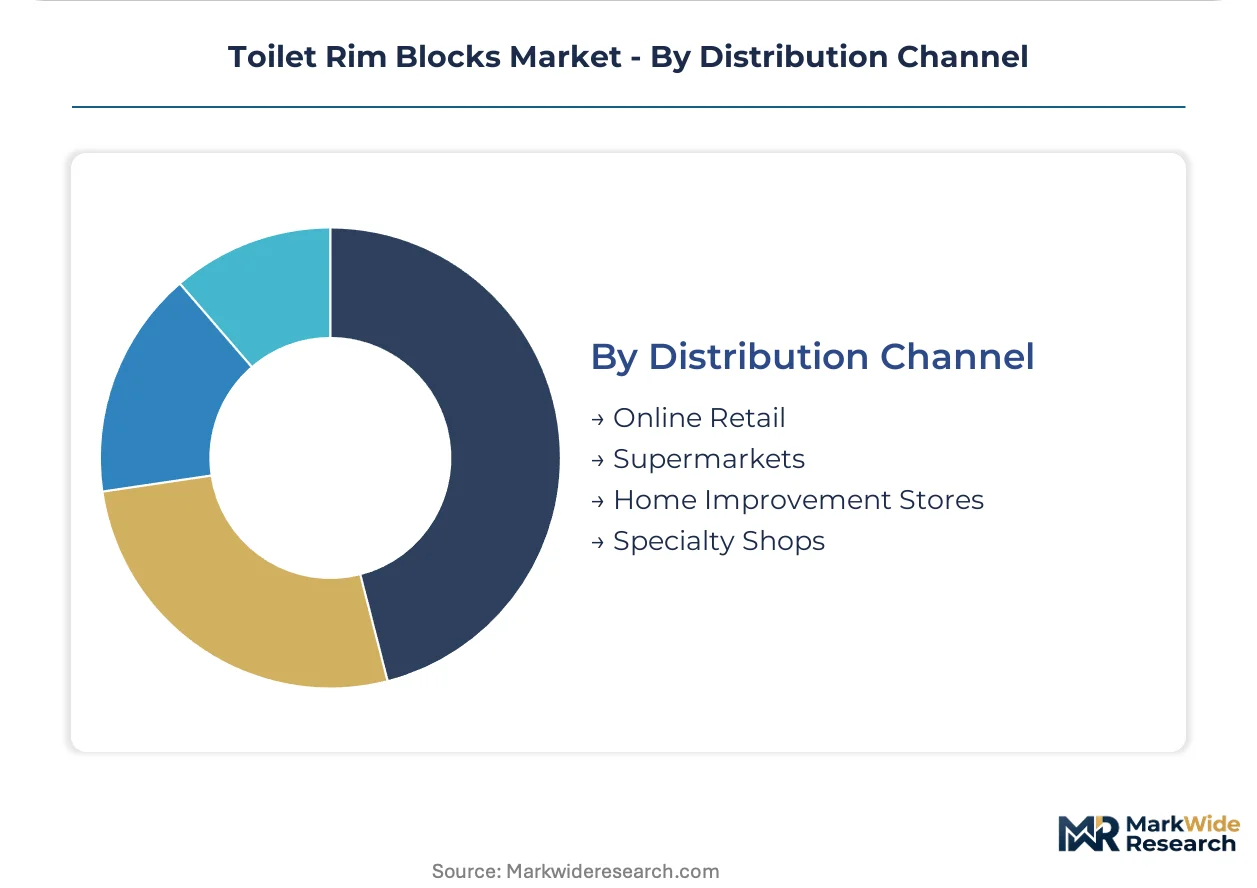
Channel economics are restructuring as direct-to-consumer models bypass slotting fees and capture lifetime value through automated replenishment, while traditional retail retains volume concentration in European markets.
- Supermarkets:Mass retail chains in Germany and the Netherlands enforce REACH-compliant biosurfactant mandates as shelf placement conditions, filtering formulation portfolios through compliance gates.
- Online Retail:Subscription distribution models bypass supermarket slotting fees and capture lifetime value through automated replacement cycles.
- Home Improvement Stores:DIY channel positioning emphasizes installation simplicity and compatibility with varied toilet geometries.
- Specialty Shops:Janitorial supply distributors serve institutional procurement with technical specification support and bulk logistics.
Supermarket channels command the established base. The steepest expansion runs through online retail subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential buyers in India exhibit the highest price elasticity, while German facility management contractors absorb premium pricing for verified sanitation outcomes. This demand-elasticity contrast structures regional expansion priorities across the value chain.
Germany
Facility management contracts in Frankfurt and Munich specify extended-release rim block systems for 80% of new commercial restroom installations. REACH compliance and EU Green Deal chemical restrictions on volatile organic compounds pull enzyme-infused formulations into mainstream procurement. The Rhine-Ruhr industrial corridor concentrates manufacturing scale for European home care supply.
United States
California and New York retail channels delist non-compliant SKUs ahead of EPA Safer Choice criteria amendments for volatile organic compounds. EPA FIFRA registration requirements preserve chlorine-based chemistry in hospitality sanitation verification protocols. The Midwest manufacturing belt retains legacy tablet compression capacity serving price-sensitive retail segments.
India
Swachh Bharat Mission facility standards create first-time demand for commercial-grade rim blocks in municipal and railway restroom infrastructure. Central government procurement mandates under the national cleanliness campaign accelerate institutional adoption. Maharashtra and Gujarat industrial zones concentrate contract manufacturing for export-oriented natural ingredient formulations.
Japan
Industrial cleaning applications developed in Osaka and Nagoya manufacturing settings migrate to consumer formulations through enzyme technology licensing. METI standards for chemical hazard classification favor reduced-emission alternatives in institutional procurement. The Kanto region anchors biotechnology research partnerships with European formulators.
Netherlands
Dutch supermarket chains enforce REACH-compliant biosurfactant mandates as shelf placement conditions for home care products. Rotterdam logistics hubs distribute enzyme-infused variants across Scandinavian procurement networks. The Randstad urban corridor concentrates facility management outsourcing contracts specifying outcome-based hygiene verification.
Toilet Rim Blocks Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with enzyme-integrated specialists commanding premium positioning while chlorine-dependent producers retain scale economies through legacy asset utilization. The market structure consolidates around integrated surfactant producers with captive chemistry capabilities and fragrance houses pivoting toward formulation partnerships. Three strategic archetypes dominate: biotechnology-integrated formulators, petrochemical-scale producers, and regional private-label manufacturers. Competitive moves concentrate on portfolio diversification toward natural ingredient bases and strategic partnerships for microencapsulation technology access.
Within the integrated chemistry tier, Reckitt Benckiser Group plc and Henkel AG & Co. KGaA exemplify archetypes combining captive detergent expertise with European manufacturing scale. Kao Corporation occupies a position representing enzyme technology leadership transferred from industrial cleaning applications. These three anchors demonstrate how geographic origin and corporate structure align with divergent formulation strategies across regulatory jurisdictions.
| Leading Market Players |
|---|
| Reckitt Benckiser Group plc |
| Henkel AG & Co. KGaA |
| Procter & Gamble Company |
| Unilever PLC |
| SC Johnson & Son, Inc. |
| The Clorox Company |
| Kao Corporation |
| Church & Dwight Co., Inc. |
| Colgate-Palmolive Company |
| Others |
Value Network & Pricing Analysis
Compressed tablet manufacturing scale in the Rhine-Ruhr corridor anchors European supply concentration, enabling integrated producers to defend price floors through captive surfactant chemistry while outsourced formulators absorb margin compression from raw material volatility.
Pricing Analysis
Subscription replenishment revenue now outpaces transactional retail in lifetime value capture for direct-to-consumer channels. Three-tier pricing structure across enzyme-infused premium, natural ingredient standard, and chlorine-based economy levels segments buyer willingness-to-pay. Cost compression in economy tiers intensifies as Indian contract manufacturers scale tablet output. Hospitality procurement teams exhibit lowest price sensitivity, absorbing premiums for verified sanitation outcomes, while residential retail buyers in emerging markets drive volume through price-point optimization.
Supply Chain Analysis
Strait of Malacca transit underwrites Asia-Europe fragrance chemical flows, exposing formulators to logistics disruption risk from concentrated microencapsulation technology sourcing. Manufacturing capacity clusters in Germany, India, and Japan feed regional demand hubs. Biosurfactant feedstocks from agricultural processing in Brazil and Southeast Asia, petrochemical bases from Gulf Coast crackers, and specialty enzymes from Osaka biotechnology parks constitute critical input dependencies. Single-source vulnerability in fragrance encapsulation concentrates supply risk among three specialty chemical houses. Distribution runs through Rotterdam logistics hubs for European institutional procurement, with direct-to-consumer subscription models bypassing traditional retail slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The toilet rim blocks market reads as a service-attach opportunity where outcome-based facility management contracts expand faster than product-only sales, embedding suppliers into recurring hygiene verification revenue streams.
For Market Incumbents: Shield core enzyme formulation portfolios through accelerated ECHA biocidal product registration to preempt 18-24 month authorization delays facing competitors. Deepen backward integration into biosurfactant feedstocks as REACH-compliant natural bases displace petrochemical alternatives, securing supply continuity while competitors face phosphonate builder scarcity. Prioritize IoT-enabled consumption monitoring capabilities to capture hospitality procurement consolidating around flush-effective service level contracts. For New Entrants and Emerging Players: Differentiate on EU Ecolabel compliance to unlock preferential Scandinavian public sector procurement channels where certification functions as a purchase gate. Target India's Swachh Bharat Mission institutional infrastructure as the most penetrable geography, where first-time commercial-grade demand outpaces established supply relationships. Deploy janitorial supply distributor partnerships for technical specification support and bulk logistics reach into municipal and railway restroom networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology-integrated formulators with captive enzyme capabilities over chlorine-dependent legacy asset operators facing regulatory headwinds. Long-term viability over the next decade hinges on portfolio exposure to natural ingredient bases and enzyme matrices rather than synthetic chemistry volumes. Watch ECHA authorization timelines for lipase and protease complexes as the inflection signal determining competitive runway for enzyme-based market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Technology Licensing | Kao Corporation's industrial cleaning expertise transfers to consumer formulations through partnership structures. |
| Subscription Distribution Launch | Direct-to-consumer models bypass German supermarket slotting fees and capture automated replacement lifetime value. |
| EU Ecolabel Certification | Compliance opens preferential procurement channels in Dutch and Scandinavian public sector cleaning contracts. |
| Backward Integration into Biosurfactants | Captive supply of REACH-compliant natural bases insulates margins from petrochemical price volatility. |
| IoT-Enabled Service Contracting | London and Frankfurt facility managers now specify flush-effective service levels transferring inventory risk to suppliers. |
Research Methodology
A spread of perspectives from facility management procurement directors, fragrance house technical directors, supermarket category buyers, and janitorial supply distributors converged on the working assumptions shaping demand elasticity and formulation substitution patterns. Primary interview insights combined with secondary validation from ECHA biocidal product registration databases, EU Green Deal implementation guidance, customs trade data on surfactant feedstock flows, and SEC filings from integrated home care producers. Bottom-up volume modeling across product type, formulation chemistry, and end-user segments triangulated against top-down market sizing from regional production capacity assessments.
Segmentation dimensions modeled span solid, gel, liquid, and tablet product formats; enzyme-infused, natural ingredient, and chlorine-based formulation chemistries; hospitality, commercial, residential, and institutional end-user categories; and supermarket, online retail, home improvement, and specialty distribution channels. CAGRs were derived from installation base expansion in commercial restroom infrastructure, replacement cycle frequency analysis, and pricing trajectory assumptions across the projection horizon. Forecast inputs incorporated REACH amendment implementation timelines, Swachh Bharat Mission procurement rollout pace, and EPA Safer Choice criteria revision schedules.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of volatile organic compound restrictions, continued hospitality sector outsourcing trends, and stable enzyme production cost curves would require recalibration. Forecasts reflect documented assumptions regarding ECHA authorization timelines, biosurfactant feedstock availability, and facility management contract structuring. Practitioners should keep alternative scenarios live as EU Green Deal chemical restriction scope, Indian institutional procurement scale-up velocity, and fragrance encapsulation technology concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Mosquito Lamps Market
Household Items
MENA POU Water Purifiers Market
Household Items
Europe Digital Showers Market
Household Items
Heated Towel Rail Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Tiki Torch Market
Household Items
Home Use Air Purifiers Market
Household Items
Multi-Door Fridges Market
Household Items
Leaf Blower Market
Household Items
Latex Mattress Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Sanitary Metal Ware Market
Household Items
Plastic Bathtub Market
Household Items
United Kingdom Air Purifier Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
China Cookware Market