
 India POU Water Purifiers Market | 2026-2036
India POU Water Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
India POU Water Purifiers Market Foresight
The capital-intensity divergence between membrane manufacturers and final assemblers is collapsing as proprietary RO module production becomes table stakes. Eureka Forbes Ltd. leverages its four-decade service network to sustain recurring filter replacement revenue across tier-2 towns. Kent RO Systems Limited anchors its position through in-house membrane fabrication, competing on total cost of ownership rather than sticker price. Hindustan Unilever Limited controls mass-market penetration via kirana store distribution density that specialty brands cannot replicate.
Point-of-use water purifiers are self-contained treatment units installed at single taps or dispensers, typically employing reverse osmosis membranes with pore sizes below 0.0001 microns, ultraviolet germicidal irradiation at 254 nanometers, or activated carbon adsorption to remove dissolved solids, pathogens, and organic contaminants from piped or stored water before consumption. RO systems dominate value capture due to consumables lock-in, while UV purifiers lead unit velocity in municipal supply zones with lower total dissolved solids. Gravity-based units occupy the price-sensitive rural fringe where electricity access remains intermittent.
BIS mandates electrical safety and performance testing for all POU devices sold in India, while FSSAI guidelines govern claims related to potable water output quality, creating a dual compliance burden that raises fixed costs for new entrants. The Jal Jeevan Mission's rural tap water push paradoxically expands the addressable base by exposing infrastructure gaps that POU units must bridge. Stakeholders must monitor how state-level groundwater contamination maps redirect technology preferences across installation types and end-user segments.
Market Dynamics
Membrane fabrication capabilities are consolidating among assemblers as BIS certification mandates force component standardization, eroding the historical divide between upstream material suppliers and downstream brands.
Growth Catalysts
- Jal Jeevan Mission infrastructure gaps:Rural tap water rollout exposes distribution network deficiencies, expanding addressable demand for POU bridging units in villages awaiting full connectivity.
- Hard-water geology concentration:Maharashtra and Karnataka aquifers exhibit elevated total dissolved solids, making RO systems non-discretionary for households in Mumbai and Bengaluru apartment clusters.
- FSSAI potable water claims governance:Output quality guidelines create compliance barriers that filter out subscale competitors, tightening supply concentration among certified manufacturers.
Market Restraints
- Import dependency for thin-film composite membranes:Domestic reverse osmosis membrane production remains limited, exposing assemblers to currency volatility and supply lead time extensions.
- Electricity access intermittency:Rural grids in eastern states constrain UV and RO unit penetration, preserving gravity-based substitutes that carry lower consumables lock-in.
- BIS electrical safety testing costs:Fixed compliance expenditures for certification laboratories disproportionately burden micro-assemblers in unorganized sector clusters.
Strategic Opportunities
- Tier-3 town service network white space:Filter replacement infrastructure remains sparse in Madhya Pradesh and Rajasthan urban peripheries, rewarding first-mover installation of technician depots.
- UV-RO hybrid convergence:Combined ultraviolet germicidal and reverse osmosis architectures address municipal supply zones with seasonal bacterial contamination spikes.
- Kirana store channel digitization:Traditional grocery networks in Gujarat and Tamil Nadu present untapped routes for mass-market unit distribution beyond specialty electronics retail.
Industry Challenges
- Membrane fabrication technician scarcity:Thin-film composite production requires specialized polymer chemistry expertise that vocational training institutes have not scaled to match demand.
- Dual certification timeline compression:Simultaneous BIS electrical safety and FSSAI quality claim approvals extend product launch cycles, straining working capital for new entrants.
- Groundwater contamination map volatility:State-level water quality data updates redirect technology preferences unpredictably, complicating inventory planning across RO, UV, and gravity-based SKU mixes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India POU Water Purifiers Market |
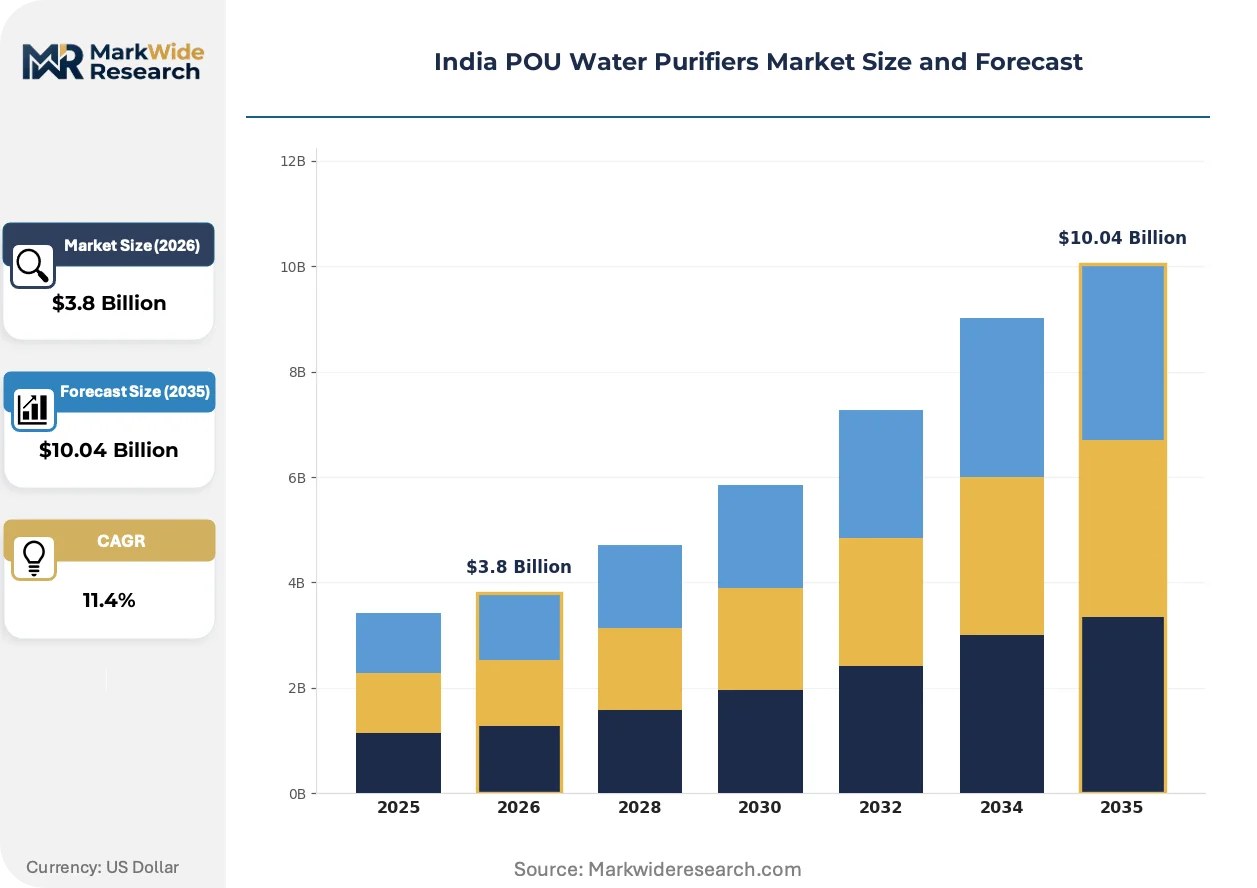
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RO, UV, Gravity, Activated Carbon Distribution Channel: Online, Retail Stores, Direct Sales, Distributors End User: Households, Offices, Schools, Restaurants Installation Type: Wall-Mounted, Countertop, Under-Sink, Portable |
| Companies Covered | Eureka Forbes Ltd., Kent RO Systems Limited, Hindustan Unilever Limited, Livpure Smart Homes Pvt Ltd., A.O. Smith Corporation, Panasonic Corporation, LG Electronics, Tata Chemicals Limited, Blue Star Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India POU Water Purifiers Market Shifts & Advancements
Component sourcing patterns are rewriting competitive boundaries as proprietary membrane production becomes essential rather than optional for market survival.
Thin-film composite reverse osmosis membrane technology is bifurcating the assembler landscape into captive producers and dependent buyers. Tier-1 brands with in-house fabrication lines in NCR and Pune industrial corridors now control total cost of ownership positioning. Tier-2 assemblers without upstream integration face margin compression as membrane suppliers consolidate pricing power.
FSSAI guidelines governing potable water output claims are tightening advertising compliance burdens. Manufacturers must substantiate pathogen removal percentages through certified laboratory testing before packaging assertions. Specialty brands lacking dedicated regulatory affairs functions are retreating from performance marketing, ceding mass-market positioning to enterprises with established compliance infrastructure.
After-sales service unbundling is compressing replacement filter procurement cycles. Apartment complex maintenance contracts in Hyderabad and Chennai are consolidating annual filter purchases through facility management intermediaries, bypassing traditional brand-direct consumer relationships. This channel shift rewards assemblers with logistics networks capable of bulk institutional fulfillment rather than individual household dispatch.
India POU Water Purifiers Market Segmentation
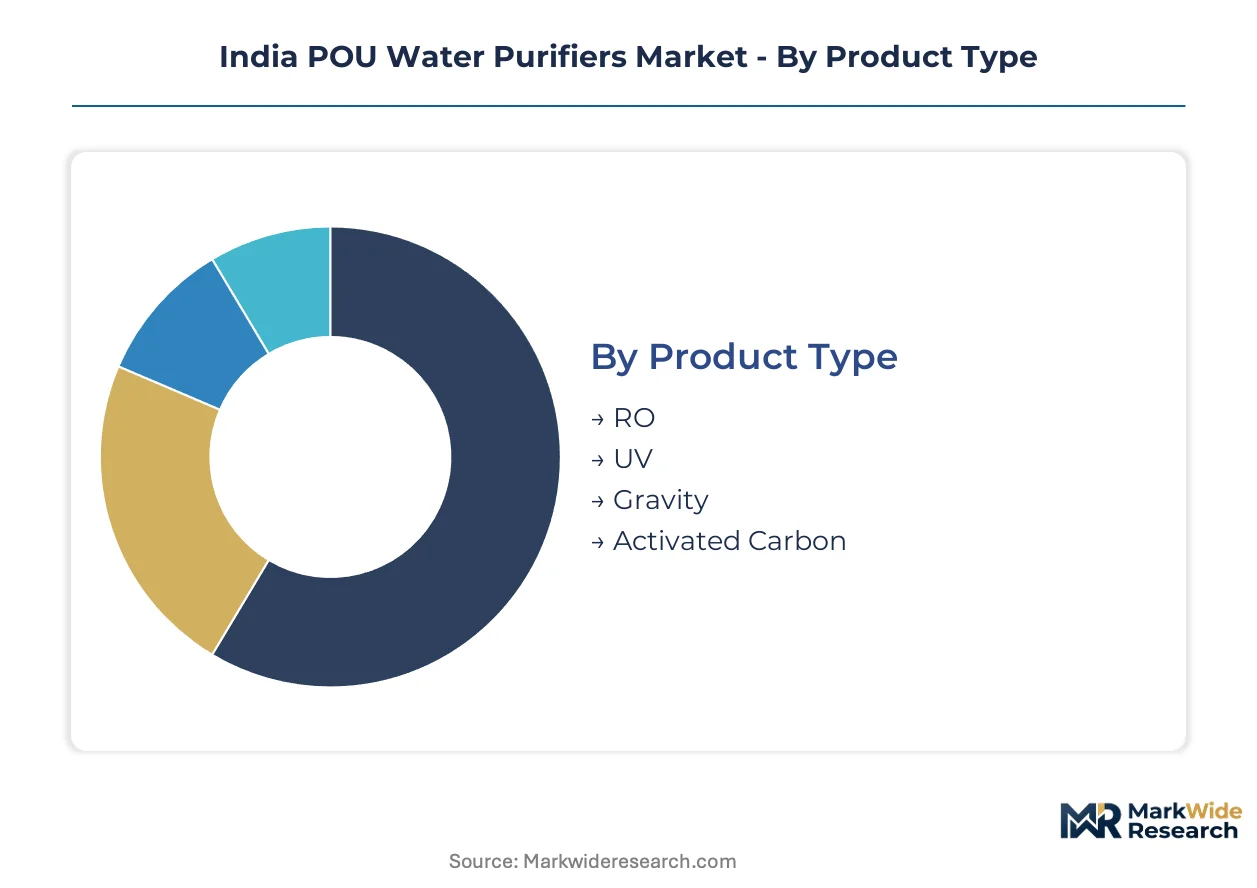
Technology differentiation across the India POU water purifiers market maps directly to BIS certification tiers and FSSAI compliance burdens. Segment boundaries harden where electrical safety mandates intersect with groundwater contamination profiles across Maharashtra and Karnataka aquifers.
Product Type:
BIS electrical safety testing and FSSAI potable water claims create divergent compliance costs across purification architectures, compressing margins for non-integrated assemblers.
- RO:Thin-film composite membranes with pore sizes below 0.0001 microns strip dissolved solids from hard-water aquifers in Mumbai and Bengaluru apartment complexes. Maharashtra and Karnataka households treat RO systems as non-discretionary where total dissolved solids exceed acceptable thresholds.
- UV:Germicidal irradiation at 254 nanometers neutralizes bacterial contamination in municipal supply zones with lower mineral content. Bengaluru's seasonal water quality fluctuations drive installation velocity where electricity access remains stable.
- Gravity:Non-electric ceramic and activated carbon units serve eastern state rural grids with intermittent power. Lower consumables lock-in preserves price-sensitive penetration.
- Activated Carbon:Adsorption-based systems target chlorine and organic compound removal in pre-treated municipal supplies. Compact form factors suit countertop installations in tier-2 town rentals.
Established volume favors RO; emerging adoption favors UV-RO hybrid architectures addressing seasonal bacterial spikes.
Distribution Channel:
Channel cost structures stratify by working capital intensity and technician deployment requirements, with kirana store density determining mass-market reach.
- Online:E-commerce platforms aggregate comparison shopping for replacement filters and new unit purchases. Tier-1 city consumers research membrane specifications before brand-direct fulfillment.
- Retail Stores:Electronics and appliance showrooms in Hyderabad and Chennai enable tactile evaluation of wall-mounted units. Commission structures favor higher-margin RO systems over gravity alternatives.
- Direct Sales:Branded technician networks handle installation and annual maintenance contracts. Eureka Forbes leverages four-decade service infrastructure for recurring filter replacement revenue.
- Distributors:Regional wholesalers bridge manufacturer production to fragmented retail endpoints. Madhya Pradesh and Rajasthan peripheries present technician depot white space for first-mover consolidation.
Volume concentrates in retail stores; expansion velocity climbs fastest through kirana store digitization in Gujarat and Tamil Nadu.
End User:
Consumption patterns diverge by scale economics and procurement centralization, with institutional buyers consolidating annual filter purchases through facility management intermediaries.
- Households:Individual family units drive replacement filter cycles through brand-direct or technician-mediated relationships. Apartment complex maintenance contracts in Chennai are unbundling procurement through facility managers.
- Offices:Corporate installations prioritize under-sink and countertop units with bulk filtration capacity. Centralized procurement departments negotiate annual service agreements over sticker price.
- Schools:Educational institutions require FSSAI-certified output quality documentation for health compliance. Government tenders favor BIS-certified electrical safety over unorganized assembler alternatives.
- Restaurants:Food service operators demand pathogen removal percentages substantiated through certified laboratory testing. FSSAI guidelines tighten advertising compliance burdens for performance claims.
Households anchor current penetration; institutional segments gain share fastest through maintenance contract consolidation.
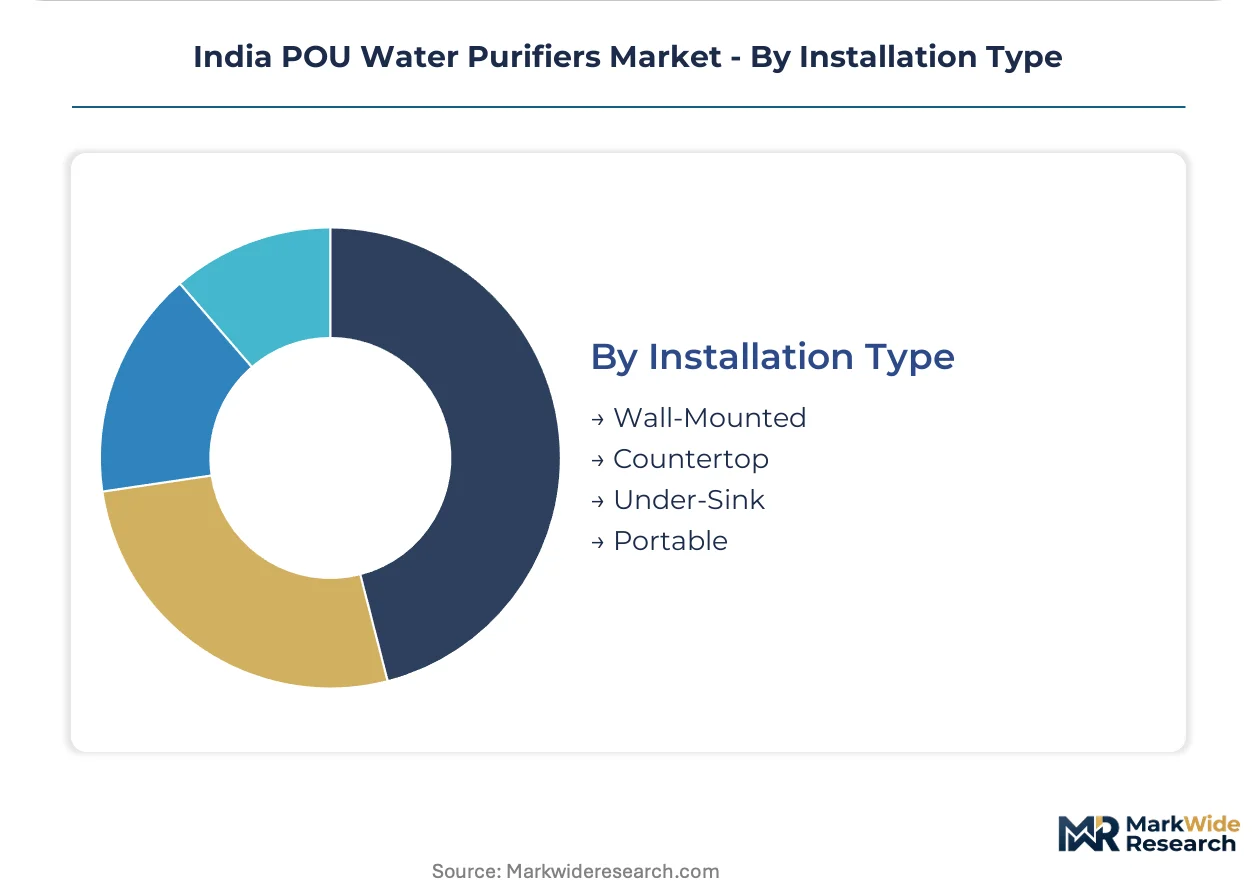
Installation Type:
Physical form factors align with kitchen infrastructure and rental tenure patterns, with portability premium pricing in transient urban demographics.
- Wall-Mounted:Fixed installations dominate owned apartments in Mumbai high-rises with dedicated plumbing modifications. Permanent fixtures lock in consumables replacement through branded service networks.
- Countertop:Non-invasive placement suits rental households avoiding landlord permissions. Compact UV and gravity units populate tier-2 town markets with price-sensitive tenants.
- Under-Sink:Concealed filtration preserves kitchen aesthetics in premium residential and commercial settings. Higher installation complexity requires certified technician deployment.
- Portable:Mobile units address travel and temporary housing needs with minimal setup. Niche positioning commands margin premium over fixed alternatives.
Wall-mounted units command installed base dominance; countertop configurations expand most quickly in rental-heavy urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for thin-film composite membranes shapes regional trade flows, with domestic membrane fabrication concentrated in NCR and Pune industrial corridors. State-level groundwater contamination profiles redirect technology preferences unpredictably across installation types.
Maharashtra
Mumbai high-rise apartment complexes drive wall-mounted RO unit placements as municipal water quality fluctuates seasonally. BIS electrical safety certification mandates pressure unorganized assemblers in Thane and Nashik industrial zones to upgrade component sourcing standards. The Pune membrane fabrication cluster anchors captive production for tier-1 brands controlling total cost of ownership positioning.
Karnataka
Bengaluru's hard-water geology exceeding total dissolved solids thresholds makes RO systems non-discretionary for apartment households. FSSAI potable water output quality guidelines tighten advertising compliance burdens for manufacturers serving the city's seasonal bacterial contamination spikes. Whitefield and Electronic City technician depots consolidate filter replacement procurement through facility management intermediaries.
Gujarat
Ahmedabad and Surat kirana store networks present untapped distribution density for mass-market unit penetration beyond specialty electronics retail. The state's intermittent rural electricity grids preserve gravity-based unit demand in eastern districts with lower consumables lock-in. Vadodara industrial zones host regional wholesaler consolidation bridging manufacturer production to fragmented retail endpoints.
Tamil Nadu
Chennai apartment complex maintenance contracts unbundle annual filter purchases through facility managers, bypassing traditional brand-direct consumer relationships. Jal Jeevan Mission rural tap water rollout exposes distribution network deficiencies, expanding addressable demand for POU bridging units in villages awaiting full connectivity. Coimbatore's service network white space rewards first-mover technician depot installation.
Telangana
Hyderabad's institutional procurement departments negotiate centralized annual service agreements over sticker price for corporate and educational installations. State-level groundwater contamination map updates redirect technology preferences between UV and RO architectures unpredictably. Secunderabad distributor networks consolidate bulk institutional fulfillment capabilities for replacement filter logistics.
India POU Water Purifiers Market Competitive Landscape
Concentration sits with integrated membrane fabricators and established service network operators. The assembler landscape bifurcates into captive producers controlling upstream material supply and dependent buyers facing margin compression. Three archetypes dominate: tier-1 brands with in-house fabrication, tier-2 assemblers sourcing externally, and mass-market distributors leveraging kirana store density. Competitive moves center on backward integration into membrane production and technician depot network expansion into tier-3 town peripheries.
Within the integrated fabrication tier, Kent RO Systems Limited and Eureka Forbes Ltd. occupy positions exemplifying divergent strategic anchors. Kent RO Systems Limited represents the captive production archetype through its in-house membrane fabrication capabilities. Eureka Forbes Ltd. anchors the service-network-dependent model, leveraging four-decade infrastructure for recurring filter replacement revenue. Hindustan Unilever Limited sits within the mass-market distribution archetype, controlling penetration through kirana store density that specialty competitors cannot replicate. These three entities collectively illustrate the competitive tension between upstream control and downstream reach that defines market structure.
| Leading Market Players |
|---|
| Eureka Forbes Ltd. |
| Kent RO Systems Limited |
| Hindustan Unilever Limited |
| Livpure Smart Homes Pvt Ltd. |
| A.O. Smith Corporation |
| Panasonic Corporation |
| LG Electronics |
| Tata Chemicals Limited |
| Blue Star Limited |
| Others |
Supply & Pricing Matrix
Annual maintenance contracts with take-or-pay provisions lock in both membrane supply access and replacement filter price visibility for apartment complex facility managers across Mumbai and Bengaluru. These multi-year agreements tether assemblers to fixed consumables margins while shielding institutional buyers from currency volatility on thin-film composite imports.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the India POU water purifiers market. Price differentiation rests on BIS certification grade and after-sales service bundling, with tier-1 brands commanding premium positioning through captive membrane production. Cost compression in the unorganized assembler tier is intensifying because FSSAI compliance investments raise fixed cost thresholds. Rural household segments exhibit highest price sensitivity, while corporate procurement departments prioritize total cost of ownership over sticker price.
Supply Chain Analysis
China, South Korea, and the United States anchor global thin-film composite membrane production, with domestic fabrication limited to NCR and Pune industrial corridors. Indian assemblers draw from imported polymer chemistry inputs, domestic activated carbon sourcing, and regional UV lamp suppliers. Single-source vulnerability concentrates in membrane supply, where currency volatility disrupts working capital cycles for tier-2 assemblers lacking captive production. Distribution runs through kirana store networks in Gujarat and Tamil Nadu, electronics retail showrooms in Hyderabad and Chennai, and direct technician-mediated relationships for annual maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against packaged drinking water and community RO plants that bypass individual household unit economics entirely. Incumbents must demonstrate superior total cost of ownership against these alternatives while hardening consumables lock-in.
For Market Incumbents: Fortify membrane fabrication capabilities in Pune and NCR corridors to control input cost volatility and compress tier-2 competitor margins. Expand technician depot networks into Madhya Pradesh and Rajasthan tier-3 peripheries before facility management intermediaries consolidate filter procurement. Prioritize BIS and FSSAI certification investments as regulatory barriers against unorganized assembler encroachment.
For New Entrants and Emerging Players: Filter replacement infrastructure gaps in Coimbatore and Vadodara service territories present white-space entry points for technician depot first-movers. Target UV-RO hybrid architectures addressing Bengaluru's seasonal bacterial contamination spikes where incumbents under-index. Pursue kirana store digitization partnerships in Ahmedabad and Surat as mass-market distribution bypass for specialty electronics retail.
For Investors and Strategic Acquirers: Capital is best deployed toward captive membrane fabricators with established BIS compliance infrastructure and tier-2 town service network density. Long-term viability hinges on consumables recurring revenue streams rather than unit placement velocity. Monitor state-level groundwater contamination map updates as inflection indicators redirecting technology preference between UV and RO architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Kent RO Systems' captive fabrication lines in Pune compress dependent assemblers' margin positions. |
| Tier-3 Town Service Network Expansion | Eureka Forbes leverages four-decade infrastructure to capture recurring filter replacement revenue. |
| Kirana Store Channel Digitization | Hindustan Unilever's grocery network density enables mass-market penetration beyond electronics retail. |
| UV-RO Hybrid Product Launch | Combined architectures address Bengaluru's seasonal bacterial contamination in municipal supply zones. |
| Facility Management Partnership | Chennai apartment contracts unbundle procurement through intermediaries, rewarding bulk fulfillment capabilities. |
Research Methodology
A standing panel of membrane fabrication technicians, kirana store channel partners, facility management procurement heads, and BIS certification laboratory directors provided ongoing calibration across the study. Primary interviews with tier-1 brand supply chain executives and tier-2 assembler operations managers combined with secondary validation from BIS notification records, FSSAI guideline publications, customs import data for thin-film composites, and state groundwater contamination reports. Bottom-up unit placement estimates triangulated against top-down addressable household projections across Maharashtra, Karnataka, Gujarat, Tamil Nadu, and Telangana.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled technology type, distribution channel, end-user segment, and installation type as core dimensions, with state-level groundwater quality profiles as an industry-specific overlay. CAGRs derived from segment-level growth trajectory blending, incorporating membrane import dependency cycles, electrification access patterns, and regulatory compliance timeline compression as forecast inputs.
Material uncertainties — state-level groundwater contamination map revisions, Jal Jeevan Mission connectivity acceleration, and thin-film composite import tariff adjustments — sit outside the modeled envelope. Forecasts reflect assumptions about technician network scalability and BIS certification enforcement intensity. Recalibration cycles align with material shifts in membrane supply availability and state water quality data releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Bathroom Products Market
Household Items
Cast Iron Cookware Market
Household Items
Coffin and Cremation Urn Market
Household Items
Washing Machine Cleaner Market
Household Items
Sanitary Napkin Vending Machine Market
Household Items
Global Buddhist Supplies Market
Household Items
Barbecue Grill Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Titanium Thermos Cup Market
Household Items
Flushable Wipes Market
Household Items
Beach Towel Market
Household Items
Toilet Brush Market
Household Items
Lunch Box Market
Household Items
Europe Digital Showers Market
Household Items
Residential Water Purifier Market
Household Items
Fan Market