
 Camping Lights and Lanterns Market | 2026-2036
Camping Lights and Lanterns Market Size, Share, and Industry Trends Forecast 2026-2036
Camping Lights and Lanterns Market Outlook
Subscription-based firmware updates and app-connected brightness controls is shifting how manufacturers monetize portable lighting. Coleman Company leverages its mass retail distribution network to sustain volume leadership in family camping channels. BioLite anchors its position through integrated stove-and-light ecosystems that appeal to eco-conscious backcountry users. Fenix Lighting specializes in high-lumen tactical output for professional and survivalist segments where performance commands premium positioning.
Camping lights and lanterns encompass portable, battery-powered illumination devices engineered with LED emitters typically rated between 100 and 1,000 lumens, housed in impact-resistant polymers or aluminum alloys with IPX4 to IPX8 water ingress protection, designed to provide task and area lighting in off-grid outdoor environments. LED lanterns dominate unit economics due to semiconductor efficiency gains and declining chip costs, while solar-integrated variants capture margin pools among ultralight hikers seeking to eliminate battery weight. Rechargeable lithium-ion power sources are displacing alkaline disposables fastest among outdoor enthusiasts, though battery-powered options retain volume among casual campers prioritizing shelf stability and immediate availability.
FCC certification governs radio-enabled smart lanterns in the United States, while REACH compliance in Europe restricts hazardous substances in polymer housings and solder compositions. California's Title 20 appliance efficiency regulations and the EU Ecodesign Directive are tightening standby power limits, forcing redesigns of USB passthrough and always-on indicator circuits. Stakeholders must monitor how emerging right-to-repair mandates affect sealed-unit waterproof designs and battery replacement architectures.
Market Dynamics
Lithium-ion energy density improvements and USB-C standardization are compressing product refresh cycles while forcing sealed-unit redesigns that conflict with emerging right-to-repair mandates across multiple jurisdictions.
Growth Catalysts
- Dispersed camping permit expansion:United States national park systems and Bureau of Land Management territories are issuing record backcountry access authorizations, directly stimulating portable lighting procurement among outdoor enthusiasts.
- REACH substance restrictions:European ECHA enforcement against hazardous polymer additives and solder compositions is accelerating compliant material substitution, creating upgrade demand among existing inventory holders.
- Semiconductor efficiency gains:LED chip cost curves and lumen-per-watt performance improvements are enabling feature-rich positioning at mass-market price points previously occupied by basic alkaline models.
Market Restraints
- Cobalt and lithium carbonate volatility:Battery-grade raw material price swings are compressing margin stability for rechargeable SKU portfolios, particularly affecting mid-tier manufacturers without long-term offtake agreements.
- Alkaline shelf-stability preference:Casual camper segments continue prioritizing immediate availability and storage reliability, creating demand inertia that slows rechargeable penetration in family camping channels.
- California Title 20 standby limits:Appliance efficiency regulations governing USB passthrough and always-on indicator circuits are forcing costly circuit redesigns without corresponding price recovery mechanisms.
Strategic Opportunities
- Subscription firmware monetization:App-connected brightness controls and over-the-air feature unlocking represent recurring revenue streams that hardware-centric competitors have left unharvested.
- Ultralight solar integration:Photovoltaic-embedded variants targeting thru-hiker and fastpacking communities command premium positioning while eliminating battery weight penalties that constrain conventional lithium-ion adoption.
- Ecodesign Directive alignment:EU regulatory pressure on standby power and circularity requirements rewards early movers with preferential placement in public procurement frameworks and retailer sustainability programs.
Industry Challenges
- IPX8 sealing versus repairability:Waterproof adhesive bonding and ultrasonic welding techniques that achieve submersion ratings conflict with battery replacement architectures demanded by French and German right-to-repair implementations.
- FCC Part 15 certification timelines:Radio-enabled smart lanterns face extended approval cycles for Bluetooth and mesh connectivity modules, compressing product launch windows against seasonal demand peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camping Lights and Lanterns Market |
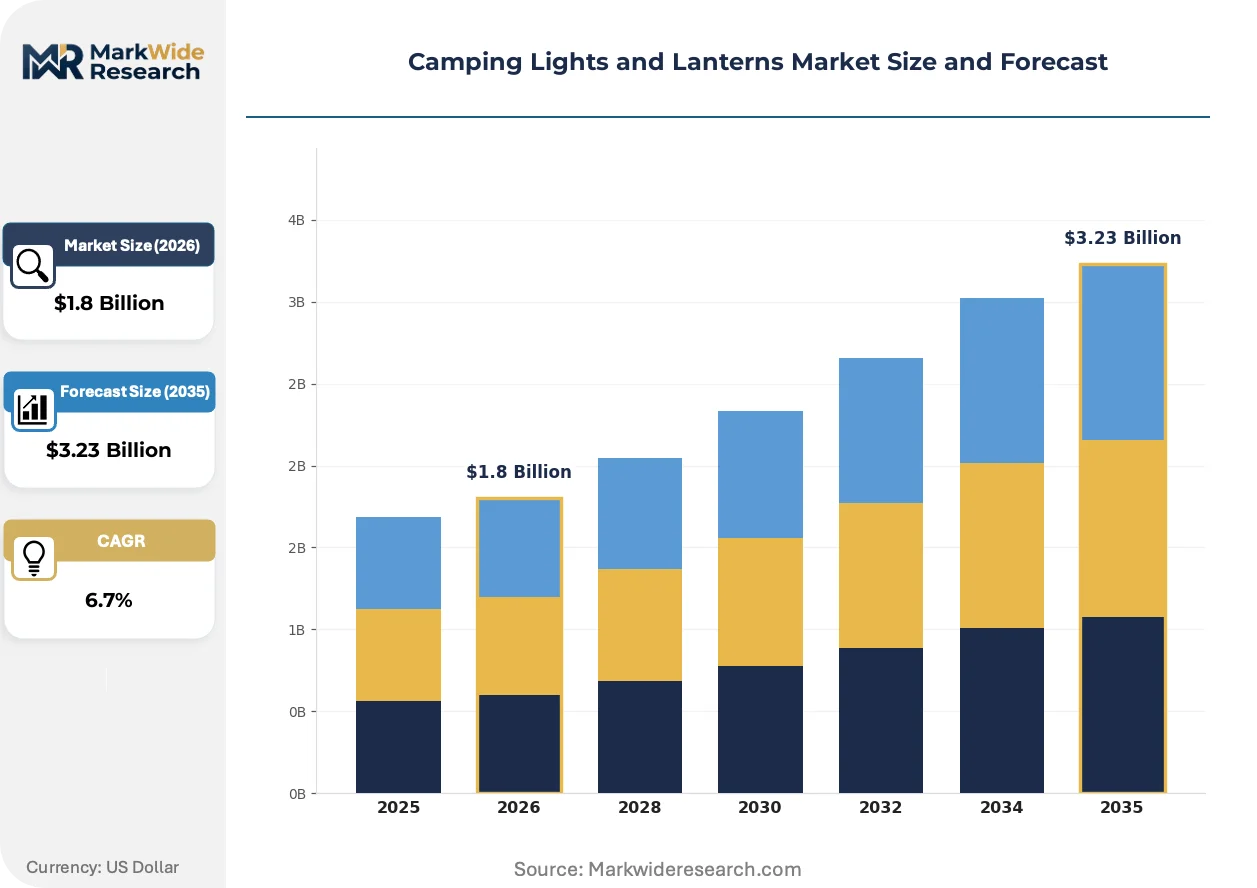
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lanterns, Solar Lights, Flashlights, String Lights Power Source: Batteries, Solar, Rechargeable, Mains Application: Campsites, Hiking, Emergency, Backyard Customer Type: Outdoor Enthusiasts, Casual Campers, Family Users, Survivalists |
| Companies Covered | Black Diamond Equipment, Ledlenser GmbH & Co. KG, Coleman Company, Nite Ize, Inc., Fenix Lighting, BioLite, UST, Primus, Goal Zero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camping Lights and Lanterns Market Strategic Shifts
Portable lighting is transitioning from commodity hardware to connected ecosystem components, with power management semiconductors and regulatory compliance frameworks jointly determining which product architectures survive.
GaN (gallium nitride) power electronics is rewriting charging speed and thermal performance benchmarks for lantern battery systems. Backcountry users and emergency preparedness buyers are adopting GaN-equipped models at accelerating rates, compressing the performance gap between compact lanterns and larger area-lighting solutions.
EU Ecodesign Directive standby power limits are forcing manufacturers to redesign always-on indicator circuits and USB passthrough functionality. The industrial consequence is elimination of convenience features that consumers expect, with premium segments responding through physical switch mechanisms that bypass regulatory scope.
Direct-to-consumer channel expansion is fragmenting traditional retail dependency among specialty outdoor brands. Specialty retailers are losing exclusive access to enthusiast segments as manufacturer-owned digital storefronts capture higher-margin repeat purchases, with North American and Nordic markets showing the most visible channel rotation.
Camping Lights and Lanterns Market Segmentation
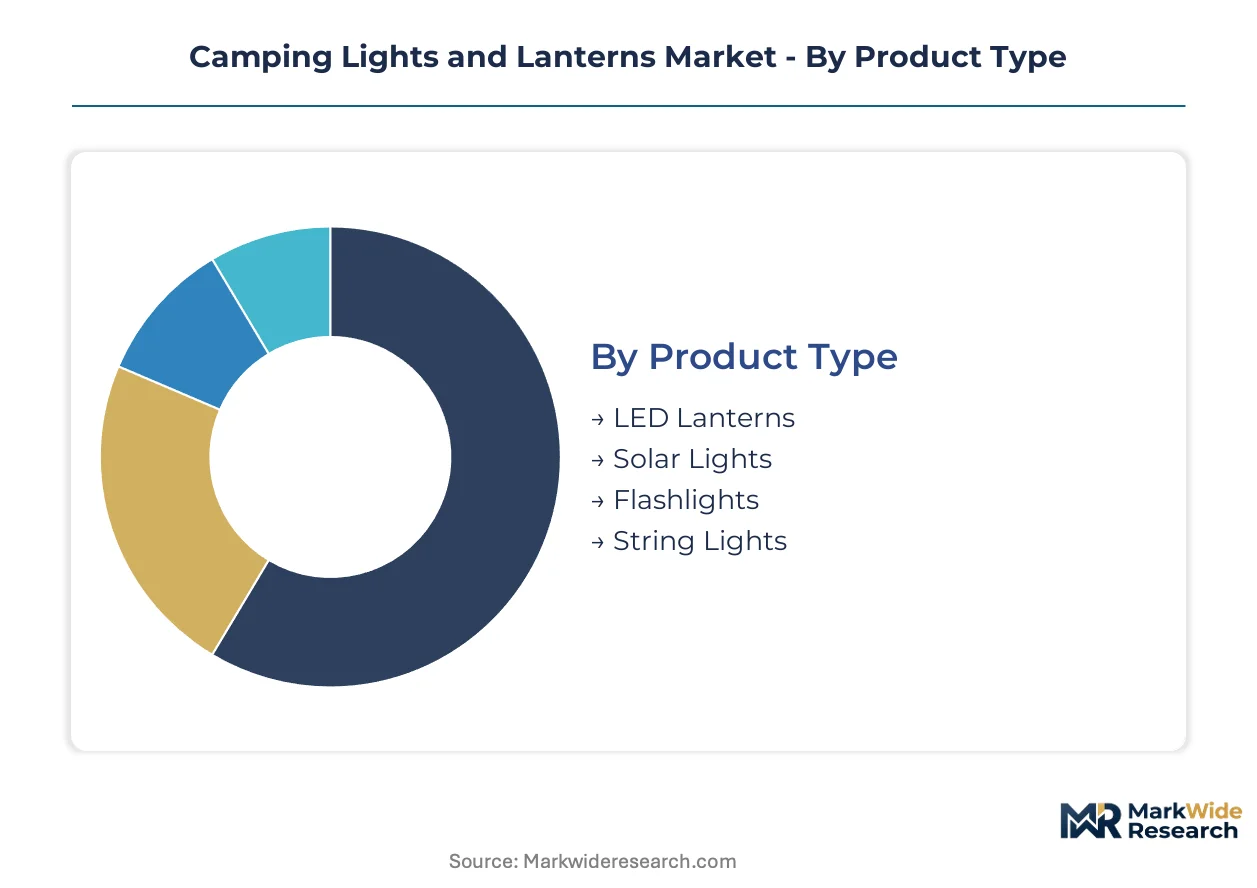
Portable lighting procurement patterns diverge sharply between technical performance seekers and convenience-oriented buyers, with power source preferences and use-case intensity determining margin capture across manufacturer portfolios.
Product Type:
LED Lanterns anchor volume leadership through semiconductor efficiency gains that enable feature-rich positioning at mass-market price points previously occupied by basic alkaline models.
- LED Lanterns:Semiconductor-based emitters rated 100-1,000 lumens housed in impact-resistant polymers or aluminum alloys with IPX4 to IPX8 protection. Demand concentrates among family campers in the United States where national park visitation and dispersed camping permits continue rising, with USB-C standardization forcing sealed-unit redesigns.
- Solar Lights:Photovoltaic-embedded variants eliminating battery weight penalties through integrated charging circuits. Ultralight hikers and fastpacking communities in backcountry recreation segments command premium positioning while lithium-ion energy density improvements compress conventional battery advantages.
- Flashlights:Directional beam devices with tactical output configurations for task-specific illumination.
- String Lights:Decorative ambient lighting systems for social camping environments and backyard installations.
Leading the category by volume: LED Lanterns. Expanding most quickly: Solar Lights.
Power Source:
Rechargeable lithium-ion architectures are displacing alkaline disposables fastest among outdoor enthusiasts, though battery-powered options retain volume among casual campers prioritizing shelf stability.
- Rechargeable:Lithium-ion cell configurations with USB-C input standardization enabling GaN-equipped fast charging. Outdoor enthusiasts represent the steepest expansion trajectory as participation in backcountry recreation climbs, with cobalt and lithium carbonate volatility compressing margin stability for mid-tier manufacturers.
- Batteries:Alkaline disposable cells offering immediate availability and storage reliability without charging infrastructure. Casual camper segments in family camping channels maintain demand inertia that slows rechargeable penetration despite semiconductor efficiency gains elsewhere.
- Solar:Photovoltaic panel integration eliminating external charging dependency for extended backcountry use.
- Mains:Grid-dependent operation limiting deployment to vehicle-accessible campsites and emergency home backup scenarios.
Volume concentration: Batteries. Technology transition momentum: Rechargeable.
Application:
Use-case intensity determines durability specifications and connectivity feature adoption, with backcountry applications demanding sealed waterproofing and emergency scenarios prioritizing standby reliability.
- Campsites:Area lighting solutions for established recreational vehicle and tent camping locations with vehicle access. Family users in United States national park systems drive procurement as dispersed camping permit expansion stimulates portable lighting demand.
- Hiking:Ultralight portable systems for mobile backcountry travel where weight minimization overrides absolute output. Thru-hiker communities gain share fastest as solar-integrated variants capture margin pools among weight-conscious segments.
- Emergency:Standby lighting systems for power outage preparedness with extended shelf-life requirements.
- Backyard:Decorative and functional lighting for residential outdoor entertainment without transport constraints.
Dominant procurement volume: Campsites. Steepest growth trajectory: Hiking.
Customer Type:
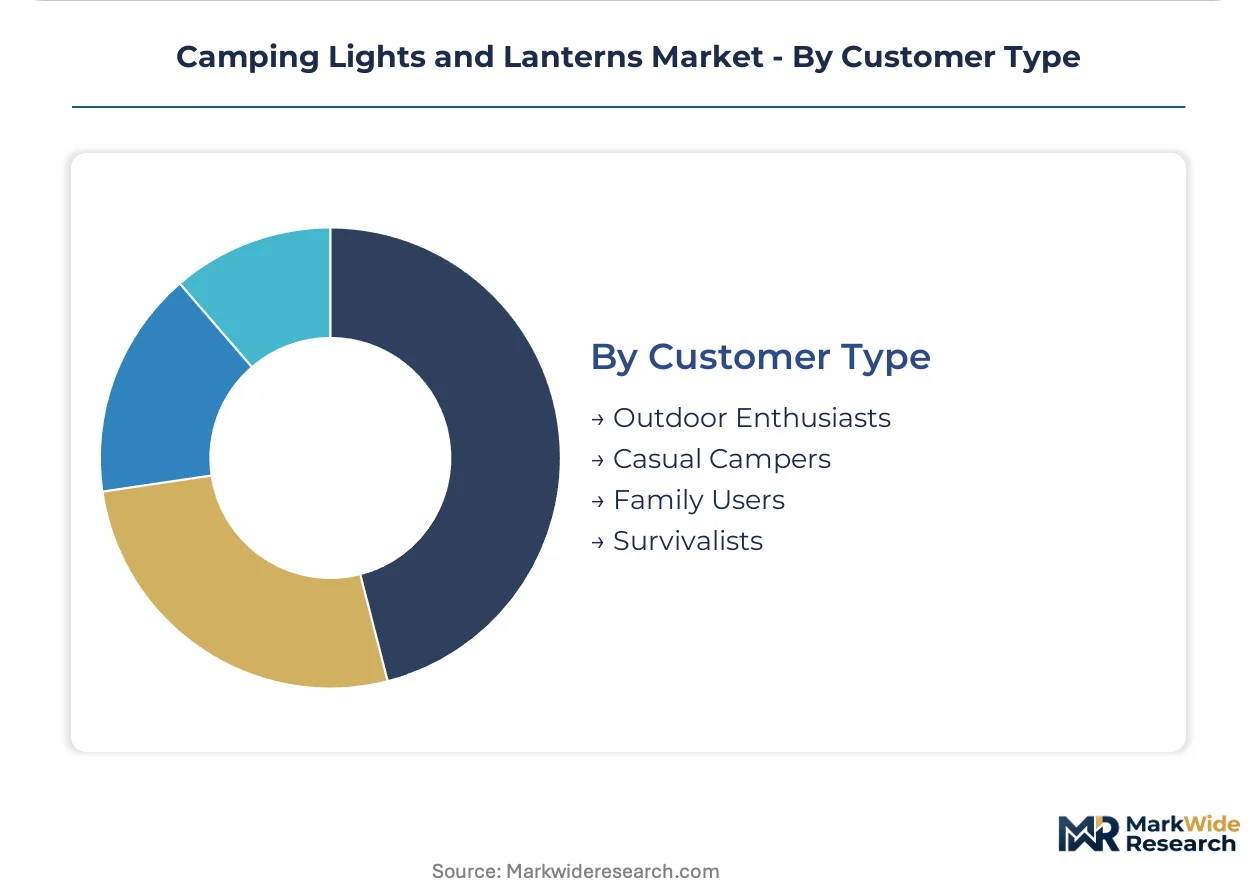
Purchasing sophistication spans from price-sensitive occasional users to performance-commanding technical buyers, with subscription firmware monetization and app-connected controls capturing recurring revenue from connected-device adopters.
- Outdoor Enthusiasts:Technical buyers prioritizing lumen-per-watt efficiency, waterproof sealing, and ecosystem integration. This segment gains share fastest as backcountry participation climbs and GaN power electronics adoption accelerates charging speed expectations.
- Survivalists:Professional and preparedness-oriented users demanding high-lumen tactical output where performance commands premium positioning. FCC Part 15 certification timelines for radio-enabled smart lanterns compress product launch windows against seasonal demand peaks.
- Casual Campers:Infrequent users prioritizing immediate availability and storage reliability over technical specifications.
- Family Users:Multi-person household buyers seeking durable, simple-operation products for recreational vehicle and car camping.
Largest addressable base: Casual Campers. Premium margin capture: Survivalists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American camping equipment distribution through its concentration of outdoor recreation headquarters and direct access to Rocky Mountain backcountry corridors.
United States
Yellowstone and Grand Canyon visitation records drive dispersed camping permit issuance, with Bureau of Land Management territories expanding backcountry access authorizations. FCC Part 15 certification timelines for radio-enabled smart lanterns compress seasonal product launches. Portland, Oregon hosts multiple specialty outdoor retailers losing share to manufacturer-owned digital storefronts.
Germany
REACH compliance enforcement by ECHA against hazardous polymer additives accelerates material substitution across existing inventory. The EU Ecodesign Directive tightens standby power limits for USB passthrough circuits. Munich and Stuttgart industrial clusters concentrate precision LED emitter manufacturing for premium lantern segments.
China
Shenzhen's electronics manufacturing ecosystem supplies GaN power semiconductors enabling fast-charging lantern battery systems. GB standards and MIIT regulations govern lithium-ion cell safety certifications. Yangtze River Delta factories dominate LED chip assembly for export-oriented portable lighting brands.
Japan
METI efficiency standards and JIS certification requirements shape product specifications for domestic outdoor enthusiasts. Thru-hiker communities in the Japanese Alps drive ultralight solar-integrated variant demand. Nagoya industrial corridors maintain specialty polymer housing production for IPX8-rated sealed units.
Australia
TGA-equivalent electrical safety standards and remote outback camping culture sustain demand for high-durability illumination systems. Victorian and New South Wales national parks report climbing backcountry permit applications. Melbourne distributors serve as Asia-Pacific logistics hubs for specialty outdoor equipment imports.
Camping Lights and Lanterns Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered market positions. The vendor base splits between mass-market volume players, premium technical specialists, and integrated ecosystem builders. Strategic archetypes include retail-dependent family camping suppliers, GaN-equipped fast-charging innovators, and solar-integrated ultralight developers. Competitive moves center on direct-to-consumer channel expansion and sealed-unit waterproofing redesigns.
Within the premium technical tier, Fenix Lighting and Ledlenser GmbH & Co. KG exemplify high-lumen output positioning where performance commands specialized buyer loyalty. Black Diamond Equipment anchors the integrated ecosystem archetype alongside BioLite, representing stove-and-light combination strategies that reduce carried weight for backcountry users. Coleman Company occupies the mass-market volume position through established retail distribution networks serving family camping channels.
| Leading Market Players |
|---|
| Black Diamond Equipment |
| Ledlenser GmbH & Co. KG |
| Coleman Company |
| Nite Ize, Inc. |
| Fenix Lighting |
| BioLite |
| UST |
| Primus |
| Goal Zero |
| Others |
Value Chain & Pricing Dynamics
Outdoor enthusiast procurement concentration in backcountry recreation channels anchors value-based pricing around lumen-per-watt performance and waterproof sealing certifications rather than commodity cost-plus structures.
Pricing Analysis
Outcome-based pricing tied to backcountry reliability metrics dominates premium tiers where IPX8 sealing and GaN fast-charging capability command substantial markups over basic alkaline alternatives. Three-tier pricing structure across premium, standard, and economy levels separates survivalist-grade tactical output from family camping convenience models. Cost compression in mid-tier rechargeable portfolios is intensifying because cobalt and lithium carbonate volatility erodes margin stability for manufacturers lacking long-term offtake agreements. Casual campers in family channels exhibit highest price sensitivity, while survivalists demonstrate lowest sensitivity as performance specifications override cost considerations.
Supply Chain Analysis
Workforce availability constraints in Shenzhen electronics clusters and Yangtze River Delta LED assembly hubs are compressing production flexibility for export-oriented portable lighting brands. Manufacturing gravity centers on China for GaN power semiconductors and lithium-ion cell integration, South Korea for advanced battery chemistry development, and Japan for specialty polymer housing production. Raw material flows draw from Chilean lithium carbonate, Congolese cobalt, and Taiwanese LED chip fabrication. Single-source vulnerability in battery-grade mineral processing creates systemic exposure to export restriction shocks. Distribution runs through Denver-based outdoor recreation headquarters serving North American specialty retail and direct-to-consumer digital storefronts capturing enthusiast repeat purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-grade raw material processing capacity bottlenecks prop pricing power for manufacturers with secured offtake agreements, creating durable margin advantages across the projection horizon.
For Market Incumbents: To counter direct-to-consumer channel fragmentation threatening specialty retail relationships, deepen exclusive distribution partnerships with national park concession operators and accelerate backward integration into lithium-ion cell assembly through joint ventures with Yangtze River Delta manufacturers. Prioritize FCC Part 15 pre-certification investments to compress seasonal launch windows against demand peaks. For New Entrants and Emerging Players: Launch via ultralight solar-integrated positioning targeting thru-hiker communities where weight elimination commands premium tolerance and incumbent ecosystem lock-in remains weakest. White-space concentration in app-connected firmware subscription models remains unharvested by hardware-centric competitors, with fastest penetration potential among outdoor enthusiasts seeking brightness control customization. For Investors and Strategic Acquirers: The window for entry favors GaN-equipped fast-charging specialists with established USB-C design architectures and Ecodesign Directive compliance documentation. Long-term viability hinges on circularity-adaptable product platforms compatible with emerging right-to-repair mandates. Monitor French and German regulatory implementation timelines as inflection indicators for sealed-unit redesign requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Power Electronics Integration | Fast-charging capability compresses performance gaps between compact and area-lighting solutions for backcountry users. |
| Subscription Firmware Monetization | App-connected brightness controls unlock recurring revenue streams from outdoor enthusiasts seeking customization. |
| Ultralight Solar Integration | Photovoltaic-embedded variants eliminate battery weight penalties for thru-hiker communities in Japanese Alps corridors. |
| Ecodesign Directive Alignment | Early standby power compliance secures preferential placement in EU public procurement frameworks. |
| Direct-to-Consumer Channel Expansion | Manufacturer-owned digital storefronts capture higher-margin repeat purchases from specialty retail defection. |
Study Parameters
Document review covered customs trade databases, Bureau of Land Management permit issuance records, and FCC equipment authorization filings, complemented by interviews with product development directors at portable lighting manufacturers, category buyers at specialty outdoor retailers, lithium-ion procurement leads at battery cell suppliers, and backcountry recreation program officers at national park systems. Secondary validation drew from LED chip cost curve analyses, REACH substance restriction enforcement reports, and GaN semiconductor supply disclosures. Bottom-up SKU-level volume builds were cross-referenced against top-down category expenditure estimates.
Historical shipment trajectories were cross-referenced against panel input from industry participants to anchor projection parameters across the analysis window. Segmentation modeling incorporated product type, power source architecture, application intensity, and customer sophistication tiers. CAGRs were derived from slope consistency checks against macro outdoor recreation participation trends and semiconductor efficiency improvement curves. Forecast inputs included dispersed camping permit issuance velocities and USB-C standardization adoption rates.
Raw material price volatility, regulatory implementation timeline delays, and right-to-repair mandate scope expansion are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding backcountry participation growth and lithium-ion energy density improvement trajectories. Material deviation in cobalt carbonate spot markets or ECHA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Compound Bow and Crossbows Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Camping Utensils Market